
 Cargo and Vehicle Screening Market | 2026-2036
Cargo and Vehicle Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Cargo and Vehicle Screening Market Insights
Aftermarket service revenue is fragmenting across the Cargo and Vehicle Screening landscape as hardware commoditization pushes vendors toward recurring revenue models. Smiths Detection leverages its installed base of X-ray systems to sustain premium service contracts across European port authorities. L3Harris Technologies anchors its position through deep integration with U.S. government screening programs, while Nuctech Company Limited competes aggressively on manufacturing scale in emerging markets.
Cargo and vehicle screening encompasses non-intrusive inspection technologies that detect contraband, explosives, and hazardous materials in commercial freight and passenger vehicles using gamma-ray, neutron, or millimeter-wave interrogation with throughput rates exceeding 150 trucks per hour at land borders. X-Ray Systems dominate product-level revenue due to mature supply chains and established maintenance protocols, while AI-Based Solutions represent the fastest-expanding technology segment as convolutional neural networks reduce false alarm rates below two percent. Automated Systems command the highest margins in the technology dimension by eliminating labor costs at high-volume seaport terminals, though Manual Screening persists in military applications where operator judgment remains irreplaceable.
The U.S. Transportation Security Administration and U.S. Customs and Border Protection jointly mandate certification under the ANSI N42.45 standard for radiation detection equipment, while the EU AI Act imposes conformity requirements on automated threat-recognition algorithms deployed at Schengen crossings. India's BIS and DGFT enforce phased domestic content rules that reshape procurement eligibility for port authority tenders. Stakeholders must weigh the capital efficiency of AI retrofit kits against full system replacement cycles as regulatory timelines for algorithmic accountability tighten.
Market Dynamics
Automated threat-recognition algorithms are compressing operator labor requirements at high-throughput seaports while tightening certification timelines under the EU AI Act reshape procurement specifications across Schengen border infrastructure.
Growth Catalysts
- EU AI Act Conformity Mandates:Automated threat-detection systems deployed at Schengen crossings must now meet algorithmic accountability standards, forcing replacement cycles for legacy screening equipment across German and Dutch port authorities.
- India PLI Scheme Incentives:Domestic security manufacturing subsidies accelerate localization of X-ray system production, shortening procurement cycles for Mumbai and Chennai port modernization tenders.
- Millimeter-Wave Integration:Passive screening arrays combined with active interrogation reduce false alarm rates below operator-review thresholds, driving adoption at land border checkpoints with throughput requirements exceeding 150 vehicles hourly.
Market Restraints
- Helium-3 Supply Concentration:Neutron detection systems depend on radiological isotope supplies concentrated in Russian and U.S. government stockpiles, creating procurement vulnerability for radiation portal monitors deployed at commercial seaports.
- F-Gas Phase-Down Requirements:Cooling systems for superconducting sensors face refrigerant restrictions under updated EU regulations, adding retrofit costs to deployed base maintenance contracts.
- Legacy System Interoperability:Proprietary data formats from 1990s-era X-ray installations block seamless AI retrofit integration, fragmenting upgrade paths across European customs authorities with heterogeneous installed bases.
Strategic Opportunities
- AI Retrofit Kit Deployment:Convolutional neural network modules upgrade existing X-ray tunnels without full system replacement, capturing margin from budget-constrained port authorities in Spain and Italy facing compressed replacement timelines.
- Domestic Content Rules in India:Phased BIS and DGFT local sourcing mandates create captive demand for indigenized screening equipment, advantaging manufacturing joint ventures with Indian component suppliers.
- Service Contract Unbundling:Predictive maintenance algorithms enable remote diagnostics, allowing vendors to tier service offerings separately from hardware procurement and capture recurring revenue from distributed land border installations.
Industry Challenges
- ANSI N42.45 Certification Timelines:U.S. Customs and Border Protection radiation detection approval processes extend 18-24 months, delaying revenue recognition for neutron interrogation systems targeting land border deployment.
- Algorithmic Bias Audit Requirements:EU AI Act mandatory conformity assessments for automated threat recognition demand specialized machine-learning validation expertise scarce among traditional screening equipment engineering teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cargo and Vehicle Screening Market |
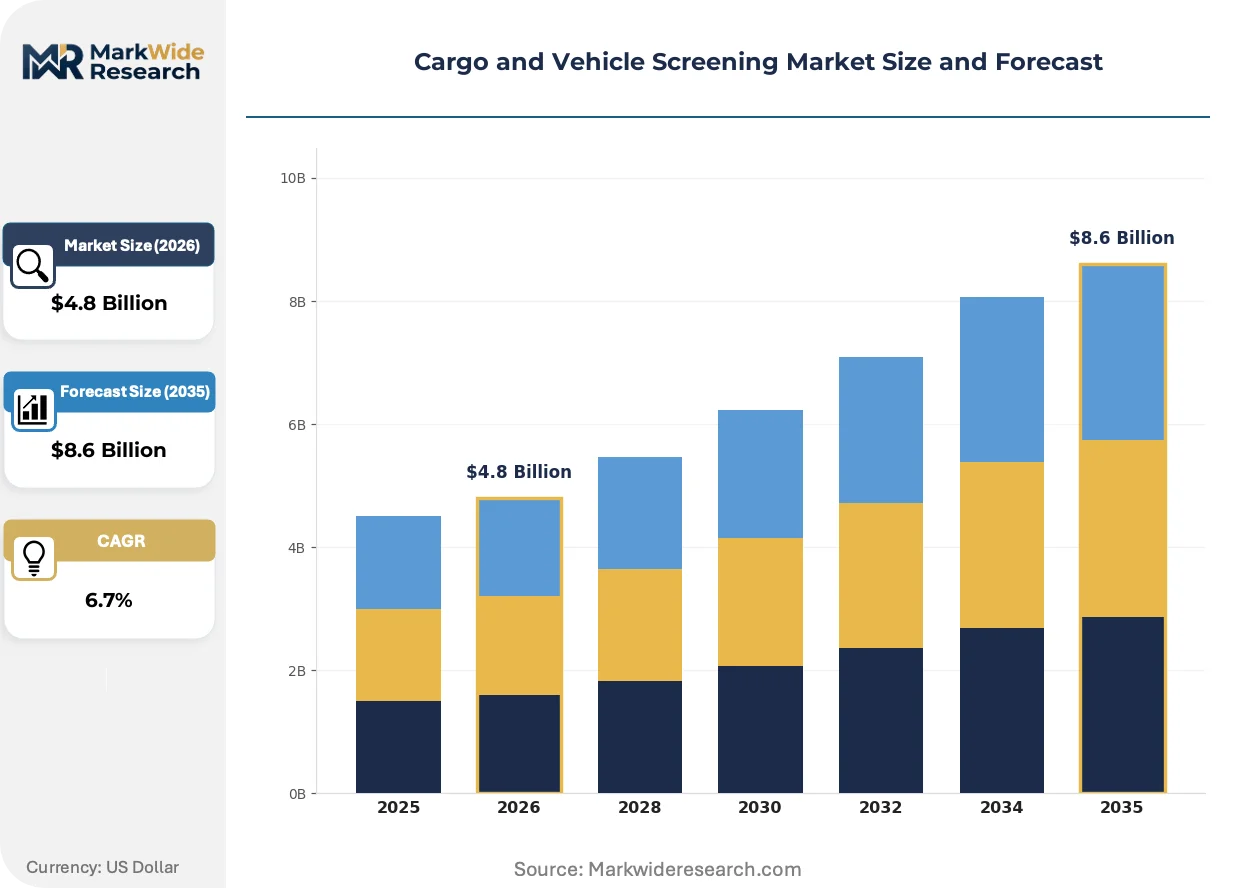
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray Systems, Chemical Detection, Explosive Detection, Biological Detection End User: Airports, Seaports, Railways, Military Technology: AI-Based Solutions, Manual Screening, Automated Systems, RFID Technology Application: Border Security, Event Security, Infrastructure Protection, Customs Compliance |
| Companies Covered | Leidos, OSI Systems, Rapiscan Systems, AS&E, L3Harris Technologies, LINEV Systems, Smiths Detection, UVeye, Nuctech Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cargo and Vehicle Screening Market Trends and Innovations
Convolutional neural networks are compressing false alarm review labor while passive millimeter-wave arrays enable drive-through screening without vehicle stopping. Regulatory mandates for algorithmic accountability are tightening equipment certification requirements across multiple jurisdictions simultaneously.
Dual-energy X-ray detection is hybridizing with neutron backscatter interrogation to identify shielded nuclear material without secondary inspection delays. German and Belgian customs authorities at Antwerp and Hamburg terminals are piloting these fused-technology lanes for high-risk container flows. The convergence is compressing capital expenditure cycles as single-technology installations face premature obsolescence against integrated-platform procurement specifications.
The EU F-Gas Regulation phase-down schedule is accelerating transition to cryocooler-based sensor cooling in superconducting detection systems deployed at Rotterdam and Le Havre container terminals. Equipment vendors are redesigning thermal management subsystems to eliminate hydrofluorocarbon refrigerants before 2027 prohibition deadlines. This regulatory compression is elevating total cost of ownership calculations in European port authority tender evaluations.
Outcome-based service contracts are displacing time-and-materials maintenance agreements at high-volume screening installations. Dutch and Danish port operators now specify guaranteed system availability percentages with penalty clauses, transferring operational risk to equipment vendors. This preference shift is visible across North Sea corridor terminals where labor cost inflation makes fixed-fee service structures economically attractive despite premium pricing.
Cargo and Vehicle Screening Market Segmentation
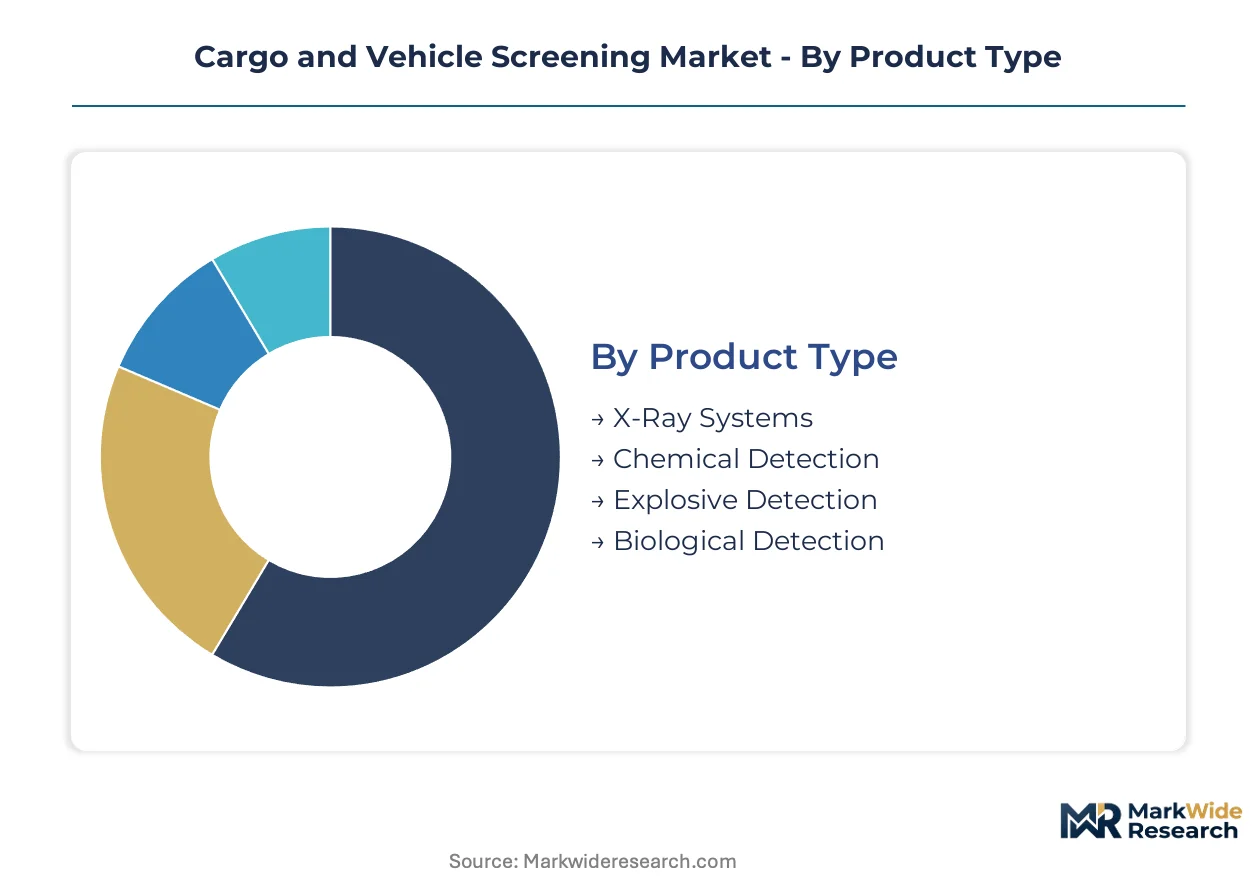
Cargo and vehicle screening equipment serves distinct operational environments with divergent throughput requirements and threat profiles. Understanding how demand fragments across product configurations, deployment settings, and detection technologies reveals where procurement budgets concentrate and where upgrade cycles accelerate.
Product Type:
Screening hardware spans a use-case spectrum from high-volume container inspection at Rotterdam terminals to specialized chemical identification at military checkpoints.
- X-Ray Systems:Dual-energy transmission arrays penetrate steel containers up to 300mm thickness, generating density-discriminated images for contraband identification. Seaports in Germany and the Netherlands deploy these for baseline cargo screening, though EU F-Gas Regulation cooling-system mandates are elevating retrofit costs for legacy installations.
- Chemical Detection:Ion mobility spectrometry and Raman spectroscopy identify toxic industrial chemicals and narcotics residue on container surfaces. Demand concentrates at Belgian and French customs facilities handling high-risk pharmaceutical shipments from Asian manufacturing hubs.
- Explosive Detection:Trace particle analyzers detect nitro-based and peroxide compounds at airport cargo terminals and land border checkpoints.
- Biological Detection:Fluorescence-based aerosol sensors and PCR-confirmation systems address bioterrorism scenarios at military installations and critical infrastructure nodes.
The dominant share belongs to X-Ray Systems, while AI-Based Solutions is closing the gap fastest through retrofit deployment at budget-constrained European port authorities.
End User:
Customer procurement patterns vary sharply by operational tempo and regulatory oversight intensity.
- Airports:Integrated hold-baggage and cargo screening networks must achieve 99% detection probability for threat items per ICAO standards. U.S. Transportation Security Administration certification timelines extend 18-24 months for new radiation detection deployments.
- Seaports:Automated scanning infrastructure processes 150+ containers hourly at Hamburg and Antwerp terminals. EU AI Act conformity mandates are forcing replacement cycles for legacy threat-recognition algorithms.
- Railways:Mobile screening units inspect cross-border freight at European corridor terminals with lower capital intensity than fixed installations.
- Military:Forward-deployable systems prioritize operator judgment over automation, sustaining demand for manual screening protocols in contested logistics environments.
Seaports command the largest equipment volume, though Airports generate the highest per-unit revenue through integrated multi-technology procurement specifications.
Technology:
Technology selection hinges on labor cost trajectories and algorithmic accountability requirements tightening across jurisdictions.
- AI-Based Solutions:Convolutional neural networks reduce false alarm rates below two percent, eliminating operator review for cleared containers. Indian port modernization tenders under PLI scheme incentives are accelerating adoption at Mumbai and Chennai terminals.
- Manual Screening:Operator-dependent visual inspection persists where threat libraries lack training data or where military protocols override automation preferences.
- Automated Systems:Drive-through millimeter-wave arrays combined with passive screening eliminate vehicle stopping at land border checkpoints.
- RFID Technology:Container tracking and tamper-evident seals integrate with screening workflows for supply chain visibility at customs compliance checkpoints.
Automated Systems capture the highest margins through labor elimination, while AI-Based Solutions is expanding most quickly via retrofit kits avoiding full system replacement.
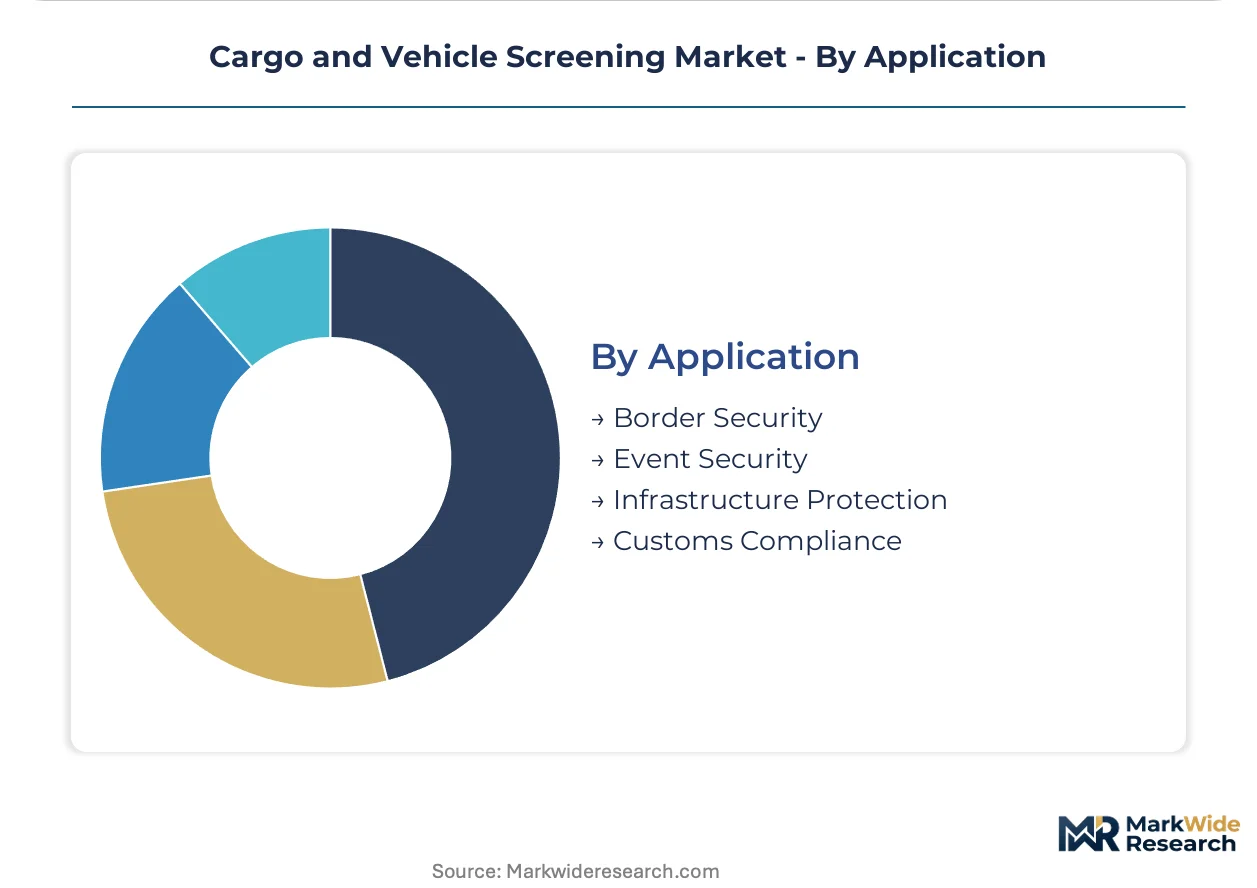
Application:
Application segmentation reflects divergent threat models and response-time requirements across security domains.
- Border Security:Land crossing installations must process commercial freight without disrupting just-in-time supply chains. Millimeter-wave integration at German-Polish and Dutch-Belgian corridors enables 150+ vehicle hourly throughput.
- Event Security:Temporary vehicle screening at stadiums and government summits demands rapid deployment and teardown capabilities.
- Infrastructure Protection:Critical facility perimeters combine passive detection with active interrogation for layered defense.
- Customs Compliance:Revenue protection and trade enforcement drive X-ray deployment at import processing terminals with duty-recovery justification.
Border Security absorbs the greatest equipment volume, though Customs Compliance is gaining share fastest as tariff enforcement intensifies and revenue recovery metrics justify capital expenditure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing concentrates in the United States, Germany, China, and Japan, with assembly and certification facilities clustered near major port authorities and border crossing infrastructure. Demand fragmentation follows customs modernization timelines across four distinct national markets.
United States
U.S. Customs and Border Protection operates the world's largest radiation portal monitor network at land borders and seaports. The ANSI N42.45 certification process governs radiation detection equipment approval, extending procurement cycles to 18-24 months. Deployment concentrates at the San Ysidro and El Paso land crossings, where automated vehicle screening infrastructure processes commercial freight at throughput rates exceeding 150 trucks hourly.
Germany
German customs authorities at Hamburg and Bremerhaven terminals are replacing legacy threat-recognition algorithms under EU AI Act conformity mandates. The EU F-Gas Regulation is accelerating cooling system retrofits for superconducting sensors before 2027 prohibition deadlines. Equipment integration is visible at the Hamburg container terminal complex, where dual-energy X-ray and neutron backscatter systems are piloting for high-risk cargo flows.
India
Port modernization at Mumbai and Chennai is accelerating under PLI scheme incentives for domestic security manufacturing. BIS and DGFT phased domestic content rules are reshaping procurement eligibility for port authority tenders. Manufacturing joint ventures are forming in Maharashtra and Gujarat to capture localization requirements for X-ray system assembly and component sourcing.
China
Domestic port automation is driving demand for high-throughput screening systems at Shanghai and Shenzhen container terminals. GB standards and MIIT regulations govern equipment certification for customs deployment. Manufacturing scale advantages are concentrated in the Yangtze River Delta and Pearl River Delta, where component supply chains support integrated system production for export markets.
United Kingdom
UK Border Force is upgrading screening infrastructure at Dover and Felixstowe to post-Brexit customs enforcement requirements. The UKCA marking transition is creating certification complexity for equipment previously validated under CE marking protocols. Deployment activity is visible at the Port of Dover, where drive-through vehicle screening arrays are being installed to manage commercial freight volume without disrupting cross-Channel supply chains.
Cargo and Vehicle Screening Market Competitive Landscape
Defense-integrated conglomerates and specialized detection equipment manufacturers split the market between government program anchoring and commercial port automation. The vendor base organizes around three strategic archetypes: systems integrators with deep government relationships, component-scale manufacturers serving emerging markets, and AI-software layer specialists retrofitting legacy hardware. Consolidation pressure is visible through strategic partnerships combining hardware platforms with algorithmic threat-recognition capabilities, alongside geographic expansion through manufacturing joint ventures in India.
Within the defense-integrated tier, L3Harris Technologies and Leidos occupy positions anchored by U.S. government screening program relationships. Smiths Detection represents the European systems specialist archetype with established port authority service contracts. Nuctech Company Limited exemplifies the scale-driven manufacturing model targeting emerging market procurement cycles. These three archetypes illustrate how competitive positioning fragments across government program dependency, regional service infrastructure, and manufacturing cost structures.
| Leading Market Players |
|---|
| Leidos |
| OSI Systems |
| Rapiscan Systems |
| AS&E |
| L3Harris Technologies |
| LINEV Systems |
| Smiths Detection |
| UVeye |
| Nuctech Company Limited |
| Others |
Pricing and Supply Chain Analysis
Helium-3 supply concentration in Russian and U.S. government stockpiles creates procurement vulnerability for neutron detection systems, compressing pricing spreads between premium radiation portal monitors and standard X-ray configurations while forcing vendors toward dual-source qualification strategies that reshape component sourcing geography.
Pricing Analysis
The EU AI Act dictates the pricing tier structure across automated threat-recognition systems, separating certified algorithmic accountability tiers from uncertified legacy equipment. Three-tier pricing structure across premium, standard, and economy levels reflects algorithm validation depth, after-sales service bundling, and integration complexity with existing port infrastructure. Cost compression in standard-tier X-ray retrofits is intensifying because Indian PLI scheme subsidies accelerate domestic manufacturing scale. Port authorities in Southern Europe exhibit highest price sensitivity due to budget constraints, while German and Dutch terminals prioritize availability guarantees over unit cost.
Supply Chain Analysis
Superconducting sensor feedstocks draw from specialized cryocooler manufacturers concentrated in Germany, Japan, and the United States. High-purity germanium crystals, precision-machined tungsten collimators, and FPGA-based signal processors anchor bill-of-materials for dual-energy X-ray arrays. Single-source vulnerability concentrates in helium-3 neutron generator tubes, where Russian export licensing creates chokepoint exposure for radiation detection OEMs. Distribution runs through systems integrators with customs authority service contracts, bypassing direct procurement by end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among national port authorities consolidating procurement through framework agreements, compressing vendor margins and elevating service performance penalties as selection criteria.
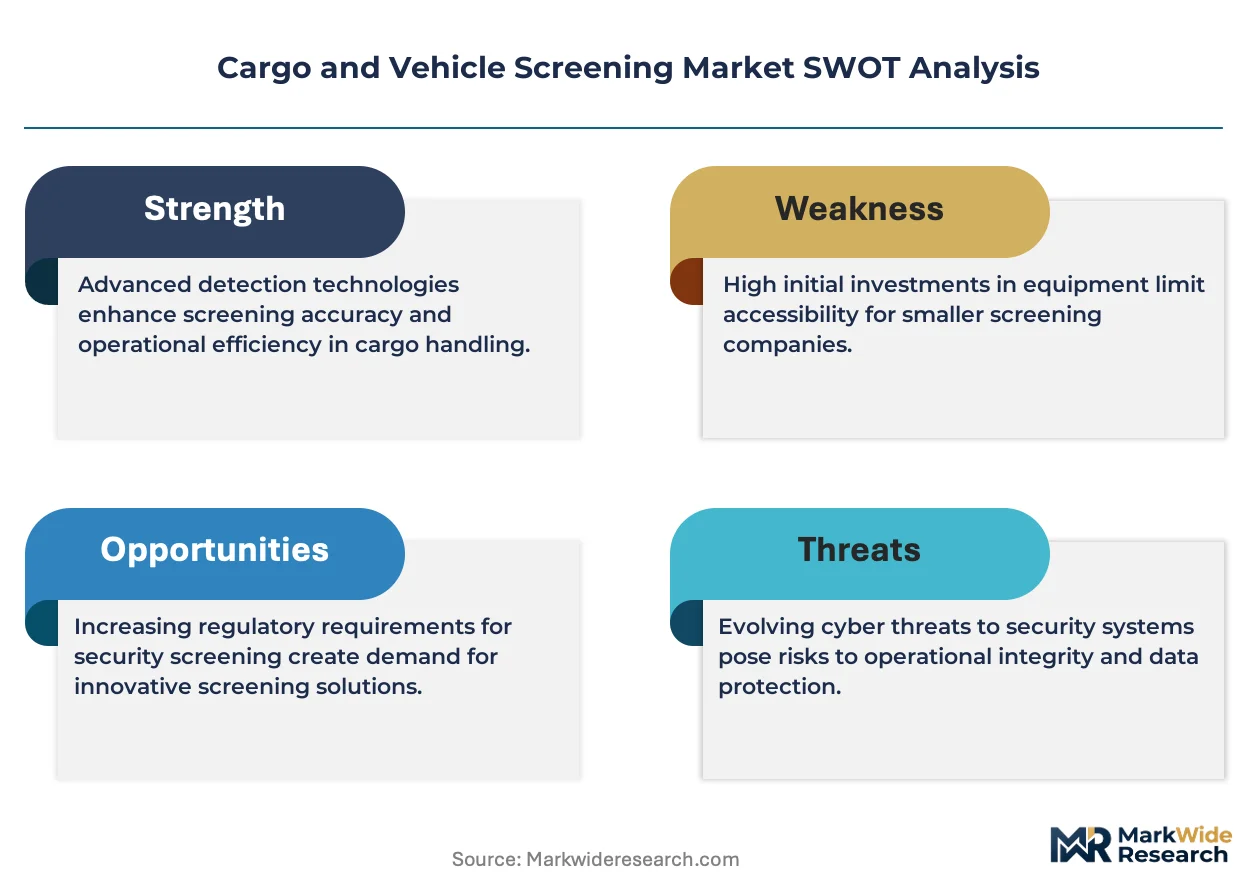
For Market Incumbents: Harden algorithmic accountability capabilities against EU AI Act conformity deadlines, investing in machine-learning validation expertise that emerging competitors lack. Deepen backward integration into cryocooler manufacturing to neutralize F-Gas Regulation cost pressure on superconducting sensor maintenance contracts. Lock in long-term service agreements at Rotterdam and Hamburg before replacement cycles peak. For New Entrants and Emerging Players: Build out AI retrofit kit deployment targeting Spanish and Italian port authorities facing compressed replacement timelines under algorithmic accountability mandates. Capture white-space in railway mobile screening units, where lower capital intensity and fragmented procurement reduce incumbent lock-in. Pursue joint venture structures with Indian component suppliers to satisfy BIS and DGFT domestic content rules for Mumbai and Chennai tenders. For Investors and Strategic Acquirers: The EU AI Act reshapes the acquisition landscape by elevating machine-learning validation capabilities above hardware manufacturing scale as valuation drivers. Target software-layer specialists with convolutional neural network expertise and existing customs authority pilot deployments. Monitor ANSI N42.45 certification timeline extensions as signal for U.S. market entry window compression.| Strategic Initiative | Industry Significance |
|---|---|
| AI Retrofit Kit Deployment | Captures margin from budget-constrained European port authorities facing compressed replacement cycles. |
| Domestic Manufacturing Joint Venture | Satisfies Indian PLI scheme incentives and BIS localization requirements for port modernization tenders. |
| Cryocooler Supply Integration | Neutralizes EU F-Gas Regulation cost pressure on superconducting sensor maintenance contracts. |
| Outcome-Based Service Contract | Transfers operational risk to vendors at Dutch and Danish terminals with guaranteed availability clauses. |
| Algorithmic Conformity Certification | Creates defensible positioning under EU AI Act mandates for automated threat-recognition systems. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with port authority procurement directors, customs technology officers, and aftermarket service managers at major European and Asian terminals; and secondary validation through U.S. Customs and Border Protection procurement disclosures, EU Tenders Electronic Daily records, and BIS certification registries. Bottom-up triangulation against top-down trade flow analysis ensured volume estimates reconciled with actual container throughput at screened terminals.
Forecast inputs span product type segmentation across X-ray, chemical detection, and explosive detection systems; technology tiers from manual screening through AI-based solutions; and end-use environments including seaports, airports, and land border crossings. CAGRs were derived from regression analysis of historical procurement cycles against regulatory deadline clustering. Industry-specific inputs incorporated EU AI Act implementation timelines, Indian PLI scheme incentive phase structures, and helium-3 supply stockpile depletion trajectories.
Sensitivities concentrate around regulatory deadline extensions, alternative neutron source technology maturation, and port authority budget reallocation toward cybersecurity infrastructure. Cross-checking against UN Comtrade screening equipment import statistics and national customs modernization budget disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Lawful Interception Market
Security and Surveillance
Speed Limit Radar Signs Market
Security and Surveillance
Smart Home Security Market
Security and Surveillance
Security System Integrators Market
Security and Surveillance
Night Vision Binoculars Market
Security and Surveillance
Stadium Security Market
Security and Surveillance
Security Analytics Market
Security and Surveillance
Europe Baggage and Parcel Screening Market
Security and Surveillance
Global Acoustic Hailing Devices Market
Security and Surveillance
Global Integration Security Services Market
Security and Surveillance
Security Holograms Market
Security and Surveillance
Swimming Pool Alarm Market
Security and Surveillance
Explosive Vapour Detector Market
Security and Surveillance
Global Manned Security Service Market
Security and Surveillance
Private Military Security Services Market
Security and Surveillance
Global Threat Intelligence Management Market