
 Physical Security Market | 2026-2036
Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
Physical Security Market Analysis
China's domestic semiconductor foundry expansion is reconfiguring component sourcing for surveillance OEMs across Asia-Pacific. Axis Communications leverages its Swedish engineering heritage to sustain premium positioning in network camera architectures. Hanwha Vision anchors its competitive stance through vertically integrated sensor manufacturing in South Korea. Securitas competes on service density, operating manned guarding networks that complement electronic systems in European commercial districts.
Physical security encompasses electronic and mechanical systems designed to protect personnel, assets, and facilities from unauthorized access, theft, sabotage, or violence. Surveillance cameras typically integrate CMOS sensors with edge-based video analytics, processing motion detection and facial recognition at the device level to reduce bandwidth loads on central servers. Access control systems represent the fastest-growing product category, as enterprise buyers migrate from magnetic stripe credentials to mobile-enabled biometric authentication that eliminates credential cloning risks. CCTV technology retains the largest installed base, though RFID and smart lock segments are expanding fastest in residential and small commercial deployments where cloud-managed architectures reduce capital expenditure.
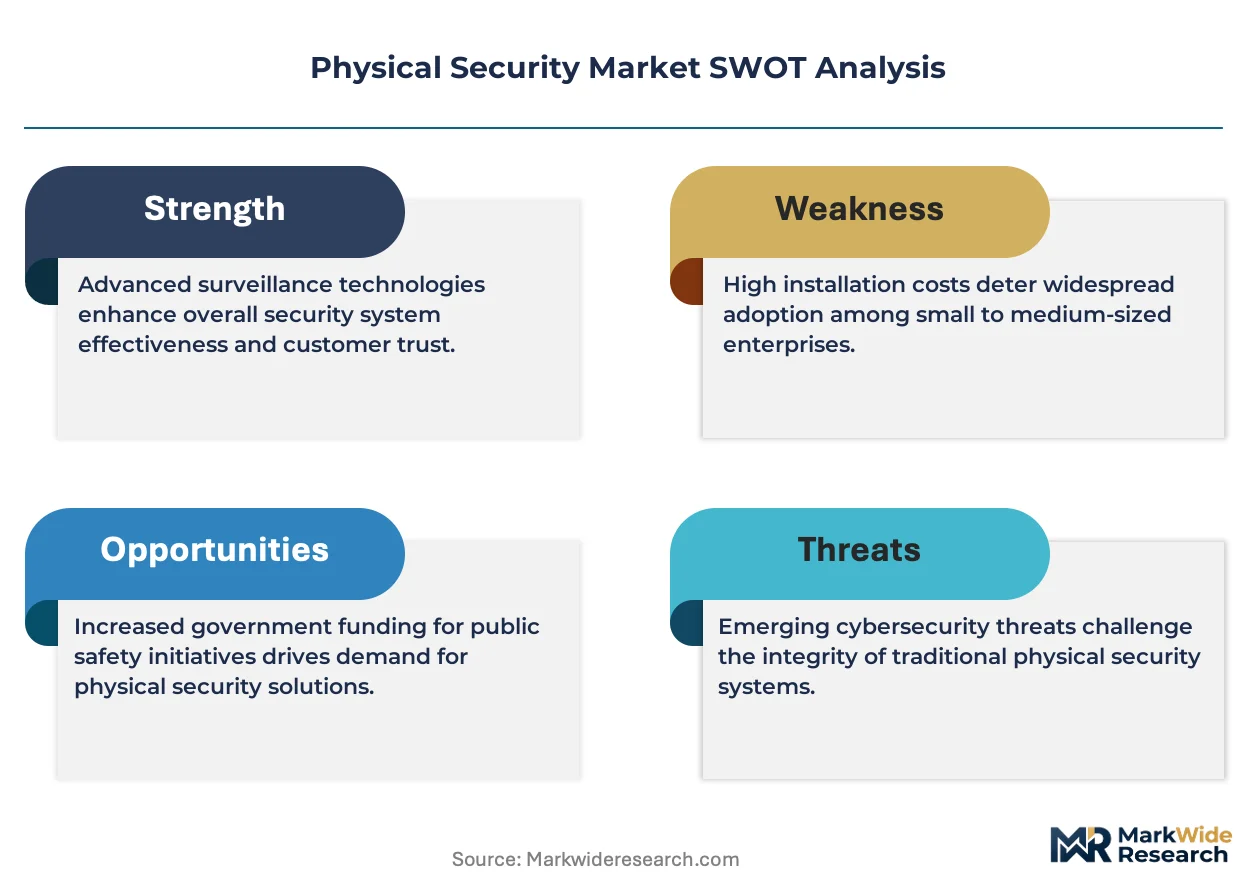
The US Department of Homeland Security issues SAFETY Act certifications that shape liability frameworks for anti-terrorism technologies, while the EU's GDPR imposes strict constraints on biometric data retention that limit facial recognition deployments in public spaces. China's GB standards for video surveillance mandate domestic encryption protocols that foreign suppliers must adapt for government and critical infrastructure tenders. Stakeholders must weigh compliance investments against market access trade-offs as regulatory fragmentation deepens between democratic and authoritarian technology governance models.
Market Dynamics
Enterprise migration toward cloud-managed access control is compressing hardware refresh cycles while forcing incumbent OEMs to rebuild recurring revenue streams through subscription licensing rather than perpetual device sales.
Growth Catalysts
- Critical infrastructure mandates:US Department of Homeland Security SAFETY Act certifications accelerate procurement of anti-terrorism perimeter systems for data centers and transportation hubs.
- Smart city video analytics:Singapore's integrated command-and-control platforms demonstrate operational value of AI-enhanced surveillance for traffic management and public safety coordination.
- Mobile biometric authentication:Enterprise buyers eliminate credential cloning risks by replacing magnetic stripe systems with smartphone-enabled facial and fingerprint readers.
Market Restraints
- CMOS sensor supply concentration:Taiwan and South Korea dominate image sensor fabrication, exposing surveillance OEMs to geopolitical disruption in semiconductor supply chains.
- GDPR biometric constraints:European Union data retention limits restrict facial recognition deployment in public spaces, forcing vendors to architect privacy-by-design architectures.
- Legacy CCTV sunk costs:Analog camera installed bases exceeding 500 million units globally delay full IP migration in cost-sensitive municipal and retail segments.
Strategic Opportunities
- Residential cloud-managed locks:Small commercial and multi-family housing units in India adopt subscription-based smart lock platforms that eliminate on-premise server requirements.
- EU Cyber Resilience Act compliance:IoT hardening mandates create first-mover advantage for manufacturers certifying access control devices against network intrusion standards.
- Edge AI convergence:On-device video analytics processing reduces bandwidth costs while enabling real-time threat detection without cloud dependency.
Industry Challenges
- Cyber-physical security integration:Facilities teams lack personnel trained to manage converged IT-OT networks, slowing unified platform deployment.
- China GB standard adaptation:Foreign suppliers must re-engineer encryption protocols to meet domestic video surveillance requirements for government tenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Physical Security Market |
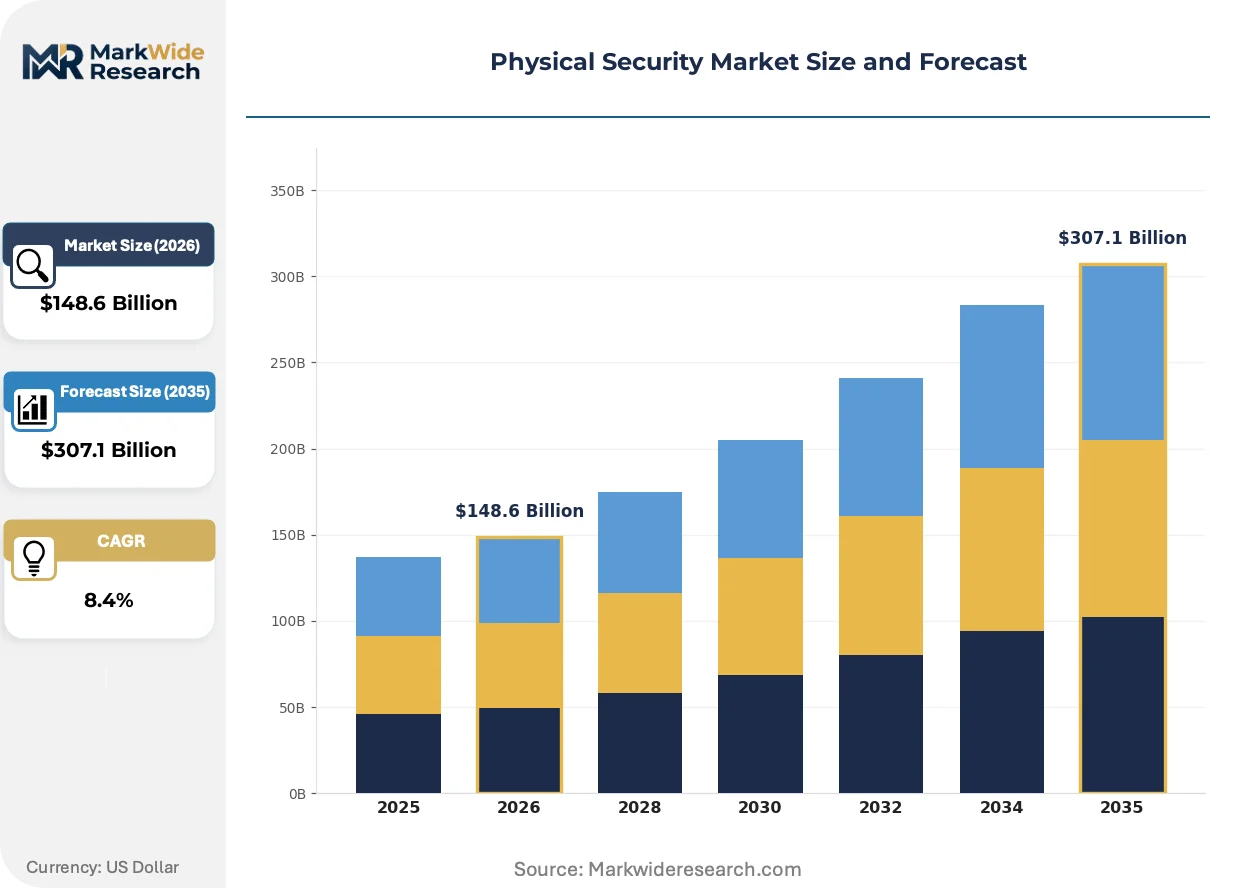
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $307.1 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
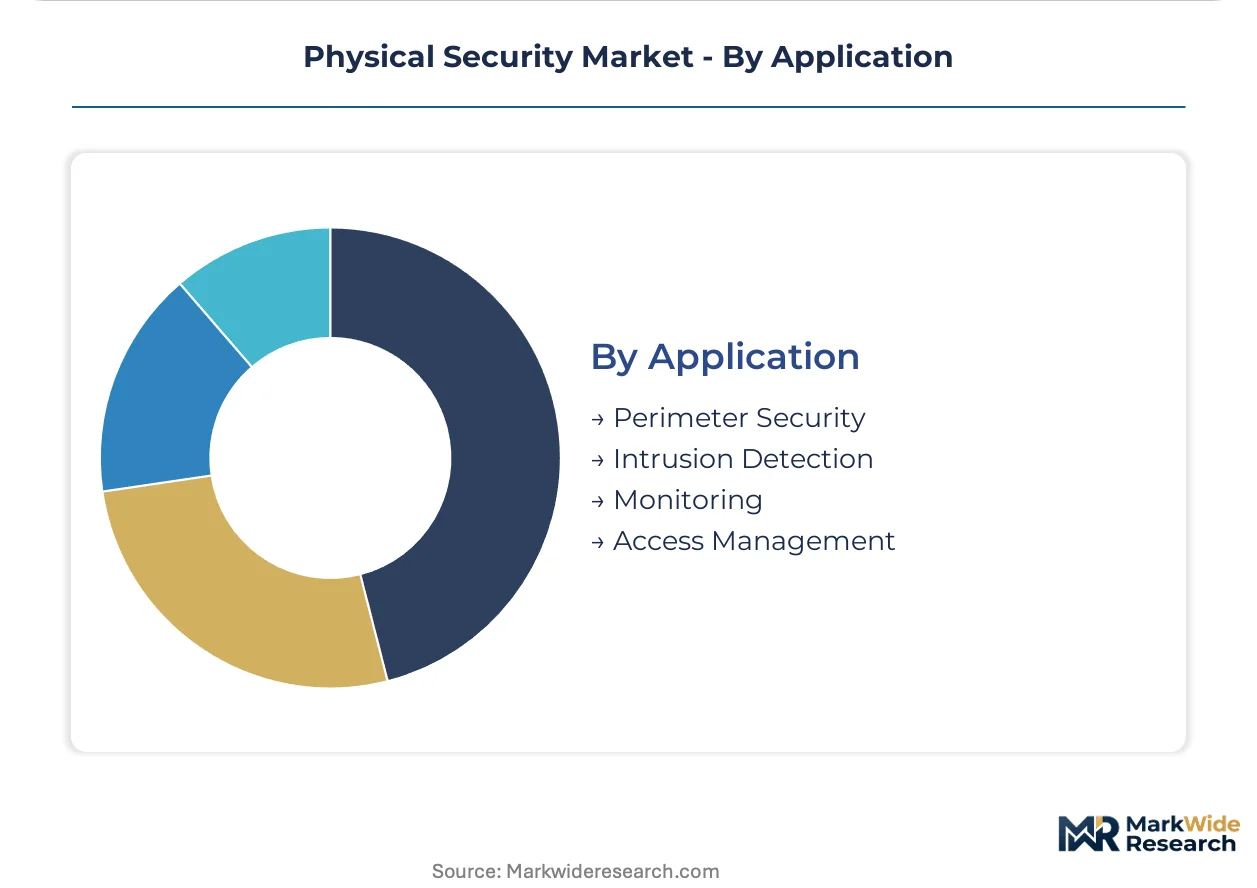
| Segmentation | Product Type: Surveillance Cameras, Access Control Systems, Alarms, Fencing Technology: CCTV, Biometric, RFID, Smart Locks End User: Government, Commercial, Residential, Industrial Application: Perimeter Security, Intrusion Detection, Monitoring, Access Management |
| Companies Covered | ADT Commercial, Axis Communications, Allied Universal, Hanwha Vision, Genetec, Securitas, Pinkerton, Gallagher Security, GardaWorld, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Physical Security Market Emerging Trajectories
Video surveillance architecture is migrating intelligence from centralized servers to network edge devices, compressing response latency while fragmenting competitive advantage across silicon, software, and systems integration layers.
Edge-based video analytics processors embedded directly into network cameras is digitizing how security operations detect anomalies and allocate human attention. Large campus operators and critical infrastructure sites in the United States deploy these systems to filter false alarms before human review. The shift is digitizing traditional central monitoring station economics by reducing headcount-per-camera ratios and enabling tiered response protocols.
The European Union's Cyber Resilience Act imposes mandatory security-by-design requirements on IoT-enabled access control hardware entering the single market. Manufacturers must demonstrate vulnerability management processes and software update guarantees across product lifecycles. Access control OEMs serving European commercial real estate are restructuring engineering roadmaps to achieve CE marking under the new cybersecurity framework ahead of enforcement deadlines.
Subscription-based service contracts are displacing capital-intensive equipment purchases across mid-market enterprise accounts. Security integrators in Germany and France bundle hardware, installation, and remote monitoring into per-door monthly fees. This model is most visible in logistics and light manufacturing verticals where CFOs prefer operational expenditure treatment for compliance-driven security investments.
Physical Security Market Segmentation
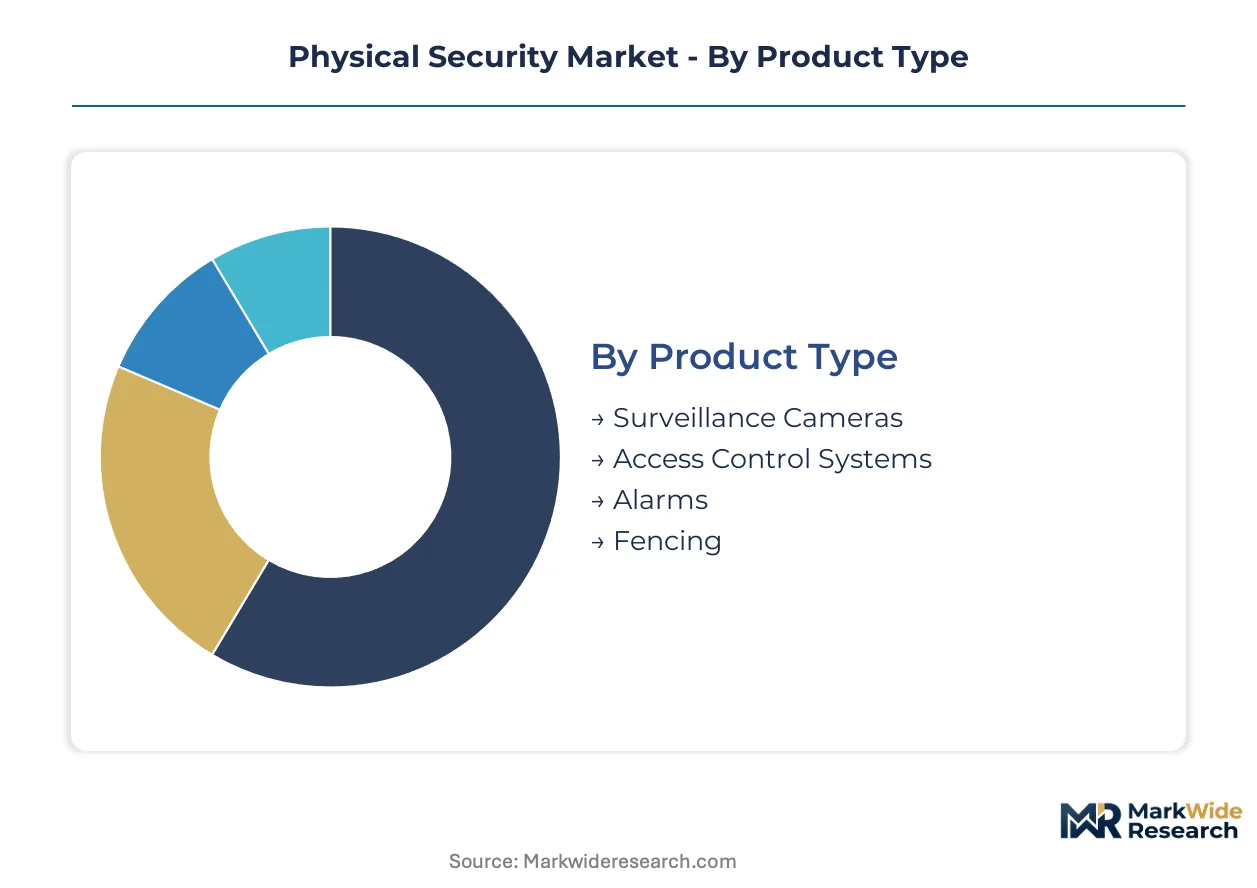
Physical security procurement patterns diverge sharply across product architectures, authentication technologies, and facility risk profiles. Buyers segment investments by threat model sophistication, with critical infrastructure operators prioritizing perimeter hardening while commercial tenants favor cloud-managed credential systems.
Product Type:
Mature hardware categories dominate installed value, though emerging integrated platforms are capturing replacement cycles.
- Surveillance Cameras:CMOS sensor arrays with edge-based video analytics process motion detection and facial recognition at the device level. Data center operators in the United States deploy these for perimeter detection to satisfy critical infrastructure protection mandates while reducing bandwidth loads on central servers.
- Access Control Systems:Mobile-enabled biometric authentication eliminates credential cloning risks through smartphone-integrated facial and fingerprint readers. Enterprise buyers across Singapore and Germany are migrating from magnetic stripe credentials to these architectures, compressing hardware refresh cycles toward subscription licensing models.
- Alarms:Sensor networks detect intrusion, fire, and environmental anomalies through hardwired and wireless configurations.
- Fencing:Physical perimeter barriers incorporate detection cables and vibration sensors for critical infrastructure sites.
Surveillance Cameras retain volume leadership; Access Control Systems hold the steepest expansion curve.
Technology:
Cost tier stratification separates legacy analog investments from premium IP-based and biometric deployments.
- CCTV:Analog and IP video surveillance retains the largest installed base globally, though full migration delays persist in cost-sensitive municipal segments. Retail chains in India maintain hybrid architectures to protect legacy camera investments while selectively upgrading high-traffic zones.
- Biometric:Fingerprint, iris, and facial recognition systems authenticate identity through unique physiological markers. GDPR constraints in France and Germany limit public space deployments, forcing vendors to architect privacy-by-design architectures with localized data processing.
- RFID:Radio-frequency identification credentials enable contactless access through card and tag formats.
- Smart Locks:Cloud-managed residential and small commercial platforms eliminate on-premise server requirements through subscription models.
CCTV maintains the deepest installed footprint; Smart Locks are climbing the fastest as cloud-managed architectures reduce capital expenditure barriers.
End User:
Application context drives procurement specifications, with threat severity determining technology sophistication and integration depth.
- Government:Critical infrastructure and public safety deployments mandate hardened encryption and domestic certification compliance. China's GB standards require foreign suppliers to re-engineer protocols for government tenders, creating compliance investment trade-offs against market access.
- Commercial:Office, retail, and hospitality facilities prioritize credential convenience and operational expenditure treatment. German and French security integrators bundle hardware and remote monitoring into per-door monthly fees for logistics and light manufacturing verticals.
- Residential:Multi-family housing and single-family homes adopt DIY and professionally installed smart lock platforms.
- Industrial:Manufacturing and logistics sites integrate physical security with operational technology networks for unified threat visibility.
Commercial end users command the largest revenue pool; Residential applications are expanding most quickly through cloud-managed service adoption.
Application:
Functional purpose determines sensor placement, response protocols, and integration complexity across facility types.
- Perimeter Security:Fence-mounted sensors, ground radar, and video analytics detect unauthorized approach before facility entry. US transportation hubs and data centers deploy these systems under Department of Homeland Security SAFETY Act certification frameworks that shape liability structures.
- Intrusion Detection:Interior motion sensors, glass break detectors, and door contacts trigger alerts upon unauthorized entry. Singapore's integrated command-and-control platforms demonstrate operational value of AI-enhanced detection for tiered response protocols.
- Monitoring:Continuous video surveillance and environmental sensing provide situational awareness for security operations centers.
- Access Management:Credential verification and entry control govern personnel movement through defined security zones.
Perimeter Security retains the highest average project value; Access Management is gaining share fastest through mobile biometric adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites the Netherlands' role in European security infrastructure procurement, while Singapore's Tuas mega-port anchors Asia-Pacific demand for integrated command systems.
United States
Data center construction in Northern Virginia and Dallas-Fort Worth drives perimeter detection procurement. The Department of Homeland Security's SAFETY Act certification shapes liability frameworks for anti-terrorism technologies deployed at transportation hubs. Critical infrastructure operators in Houston's energy corridor integrate these systems with operational technology networks.
Germany
Logistics and light manufacturing verticals in the Ruhr region adopt subscription-based access control models. The EU Cyber Resilience Act compels manufacturers to harden IoT-enabled devices against network intrusions. Security integrators in Frankfurt bundle hardware and remote monitoring into per-door monthly fees for commercial real estate.
Singapore
Smart city infrastructure rollouts accelerate adoption of integrated video analytics platforms for traffic management. The national cybersecurity agency mandates security-by-design requirements for government tenders. Command-and-control deployments in the Jurong Lake District demonstrate operational value of AI-enhanced surveillance coordination.
China
Domestic semiconductor foundry expansion reconfigures component sourcing for surveillance OEMs. GB standards mandate domestic encryption protocols that foreign suppliers must adapt for government and critical infrastructure tenders. Manufacturing clusters in Shenzhen and Hangzhou drive sensor fabrication capacity.
United Kingdom
GDPR constraints limit facial recognition deployment in public spaces, forcing privacy-by-design architectures. London's financial district prioritizes credential convenience and operational expenditure treatment for compliance-driven investments. Security operations in the City integrate mobile biometric authentication with legacy infrastructure.
Physical Security Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in sensor and silicon fabrication. The market structures around three layers: manned guarding networks with service density, vertically integrated hardware OEMs, and pure-play software platforms. Two strategic archetypes dominate competitive positioning: Nordic engineering heritage sustaining premium network camera architectures, and Asian conglomerates leveraging captive sensor manufacturing. Consolidation pressures intensify as cloud-managed service models compress hardware refresh cycles and force subscription licensing transitions.
Within the premium hardware tier, Axis Communications and Hanwha Vision exemplify divergent sourcing strategies. Axis leverages Swedish engineering heritage to sustain positioning in network camera architectures. Hanwha anchors its stance through vertically integrated sensor manufacturing in South Korea. Securitas occupies a distinct service-density position, operating manned guarding networks that complement electronic systems in European commercial districts. Genetec represents the software-centric archetype, with Montreal-based development anchoring platform integration capabilities.
| Leading Market Players |
|---|
| ADT Commercial |
| Axis Communications |
| Allied Universal |
| Hanwha Vision |
| Genetec |
| Securitas |
| Pinkerton |
| Gallagher Security |
| GardaWorld |
| Others |
Supply Flow & Price Mechanics
Overcapacity in South Korean CMOS sensor fabrication is compressing component pricing while forcing Taiwanese foundries to idle capacity, creating divergent supplier behaviors that reshape procurement negotiations for surveillance OEMs across Asia-Pacific and North America.
Pricing Analysis
The EU Cyber Resilience Act dictates the pricing tier structure for IoT-enabled access control devices entering European markets. Three-tier pricing structure across premium certified, standard compliant, and economy non-connected levels separates vendors by cybersecurity certification depth and software update guarantees. Cost compression in the economy tier is intensifying because municipal buyers in India and Southeast Asia prioritize upfront hardware costs over lifecycle security. Data center operators in the United States demonstrate the least price sensitivity, absorbing premium tiers to satisfy SAFETY Act liability frameworks.
Supply Chain Analysis
CMOS image sensors, edge AI processors, and biometric sensor modules feed from concentrated upstream bases. Taiwan, South Korea, and China dominate semiconductor fabrication for surveillance and access control electronics. Single-source vulnerability in advanced node CMOS production exposes OEMs to geopolitical disruption. Distribution runs through authorized security integrators and direct enterprise sales channels, with cloud-managed platforms increasingly disintermediating traditional hardware distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Physical security is undergoing a platform-economics inflection as cloud-managed service models displace perpetual licensing, with interoperability standards between access control and video management systems determining ecosystem capture rates.
For Market Incumbents: Entrench recurring revenue streams by accelerating subscription licensing transitions before hardware refresh cycles compress further. Axis Communications and Hanwha Vision must defend against pure-play software platforms by deepening captive sensor supply and certifying edge AI processors under emerging EU cybersecurity frameworks. Channel control through authorized integrator networks remains the critical defensive lever against disintermediation.
For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, where legacy CCTV infrastructure and limited IT security staffing create whitespace for cloud-native platforms. Residential multi-family housing in India offers secondary expansion terrain through smartphone-integrated smart lock subscriptions. A direct-to-installer go-to-market angle bypasses entrenched distributor relationships that favor incumbents.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-managed software layers while edge hardware fabrication retains high fixed-cost structures. Five-to-ten year viability favors platform integrators with recurring revenue bases over pure hardware OEMs dependent on refresh cycles. Acquisition targets should demonstrate API-first architectures enabling third-party integration. The signal to watch is attach rates of software subscriptions to hardware deployments.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies access control and video management under single-pane command interfaces for enterprise buyers. |
| EU Cyber Resilience Act Certification | Enables CE marking for IoT devices and unlocks procurement pipelines in German and French commercial real estate. |
| Edge AI Processor Development | Reduces bandwidth costs for Singapore smart city deployments while enabling real-time threat detection. |
| Subscription Licensing Transition | Converts one-time hardware sales into recurring revenue streams preferred by CFOs in logistics verticals. |
| Strategic Partnership with Hyperscalers | Accelerates cloud-native security platform distribution through AWS and Azure marketplace channels. |
Methodological Framework
Operator-level perspectives from security operations center directors, physical security integrators, enterprise facility managers, and government procurement officers anchored the qualitative base. Primary interviews triangulated with secondary validation from SEC filings of listed security OEMs, EU Cyber Resilience Act regulatory texts, and customs data on CMOS sensor trade flows. Bottom-up deployment modeling across product categories converged with top-down macroeconomic scaling.
Scenario-bracketing framed analytical outputs across the projection horizon, with sensitivity testing on semiconductor supply disruption and regulatory enforcement timing. Segmentation dimensions modeled include product architecture, authentication technology, facility risk tier, and regional regulatory cluster. CAGRs derived from installed base growth rates, replacement cycle compression, and pricing trajectory assumptions. Edge AI adoption curves and cloud migration rates served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in data center construction pipelines, semiconductor capital expenditure cycles, or EU cybersecurity enforcement intensity would shift the trajectory. Cross-checking against Department of Homeland Security procurement disclosures and Singapore government technology tenders is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Physical Security
Physical Security Equipment Market
Physical Security
South America Data Center Physical Security Market
Physical Security
Smart Police Helmet Market
Physical Security
North America Physical Security Market
Physical Security
Persistent Threat Detection System (PTDS) Market
Physical Security
Europe Cargo Inspection Market
Physical Security
France Data Center Physical Security Market
Physical Security
Bespoke Safe Rooms and Panic Rooms Market
Physical Security
Global Wearable Security Device Market
Physical Security
Security Guard Market
Physical Security
Poland Data Center Physical Security Market
Physical Security
Security Market
Physical Security
Body Armor Plates Market
Physical Security
Border Security Technologies Market
Physical Security
Europe Physical Security Market
Physical Security
Asia-Pacific (APAC) Physical Security Market