
 Global Firearm Sight Market | 2026-2036
Global Firearm Sight Market Size, Share, and Industry Trends Forecast 2026-2036
Global Firearm Sight Market Analysis
Modular sight systems bundling magnifiers with red dot bases is broadening buyer choice across price tiers. Aimpoint AB leverages its Swedish manufacturing base to sustain premium positioning in military procurement channels. Trijicon, Inc. anchors its competitive standing through tritium illumination technology that dominates low-light operational segments. Vortex Optics competes aggressively on warranty terms and direct-to-consumer channel control, extending its reach beyond traditional specialty retail.
A firearm sight is an optical or electro-optical aiming device mounted to a weapon platform, typically incorporating coated lenses, LED emitters, or holographic gratings to project an illuminated reticle onto the target plane. These devices serve the primary commercial purpose of enabling rapid target acquisition and precision engagement across military, law enforcement, and civilian shooting applications. Red dot sights and holographic sights command the fastest expansion as reflex technologies displace iron sights in close-quarters training protocols. Telescopic sights retain mature margin pools in long-range precision segments where optical clarity and adjustment precision determine procurement decisions. Electronic technology layers are capturing disproportionate investment as laser and digital overlay functions integrate with night vision and thermal fusion systems.
The US Bureau of Alcohol, Tobacco, Firearms and Explosives regulates sight classification under firearm accessory frameworks, while the International Traffic in Arms Regulations controls export licensing for military-designated units. Germany's KBA enforces CE marking and pressure-resistance standards that shape European product certification pathways. China's SAMR and GB standards govern domestic manufacturing compliance for optical components entering both military and civilian supply chains. Stakeholders must monitor evolving ITAR threshold adjustments and EU Green Deal material restrictions on rare-earth phosphors and battery chemistries that could disrupt current illumination technology roadmaps.
Market Dynamics
Electronic reflex technologies are compressing replacement cycles across military training programs while civilian competitive shooting federations mandate faster sight acquisition standards that privilege red dot architectures over iron sight proficiency.
Growth Catalysts
- ITAR Export Licensing Threshold Adjustments:The US International Traffic in Arms Regulations streamlines licensing for non-lethal accessories, accelerating military sight transfers to allied procurement programs.
- Reflex Sight Training Mandates:Law enforcement academies in Germany and Australia now require electronic sight certification for close-quarters combat modules, institutionalizing technology transition.
- Tritium Illumination Longevity:Extended half-life phosphor formulations reduce lifecycle replacement frequency, improving total cost metrics for institutional buyers.
Market Restraints
- Rare-Earth Phosphor Supply Concentration:Chinese SAMR export controls on europium and terbium compounds constrain tritium sight production capacity outside Asia-Pacific manufacturing clusters.
- CE Marking Pressure-Resistance Testing:Germany's KBA certification protocols impose 12-18 month validation timelines that delay European product launches against faster US regulatory pathways.
- Optical Glass Input Volatility:Germanium and sapphire substrate costs fluctuate with semiconductor demand cycles, compressing margin pools for precision telescopic sight manufacturers.
Strategic Opportunities
- Australian Civilian Competitive Shooting Expansion:National pistol and practical rifle federations report membership growth exceeding infrastructure capacity, creating aftermarket sight upgrade demand.
- EU Green Deal Battery Chemistry Restrictions:Proposed limitations on lithium-thionyl chloride cells incentivize development of rechargeable LED emitter architectures with domestic European supply chains.
- Thermal-Night Vision Fusion Convergence:Digital overlay platforms integrating SWIR sensors with conventional reflex bases open premium pricing tiers for hog hunting and tactical training verticals.
Industry Challenges
- Optical Coating Technician Scarcity:Vacuum deposition specialists with ion-beam sputtering expertise command wage premiums that strain mid-tier manufacturer staffing models.
- Multi-Standard Certification Parallelism:Simultaneous pursuit of US ITAR, German KBA, and Australian TGA compliance creates documentation redundancy and timeline misalignment.
- Legacy Mount Interface Fragmentation:Proprietary rail systems across NATO, Warsaw Pact, and commercial platforms necessitate SKU proliferation that complicates inventory forecasting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Firearm Sight Market |
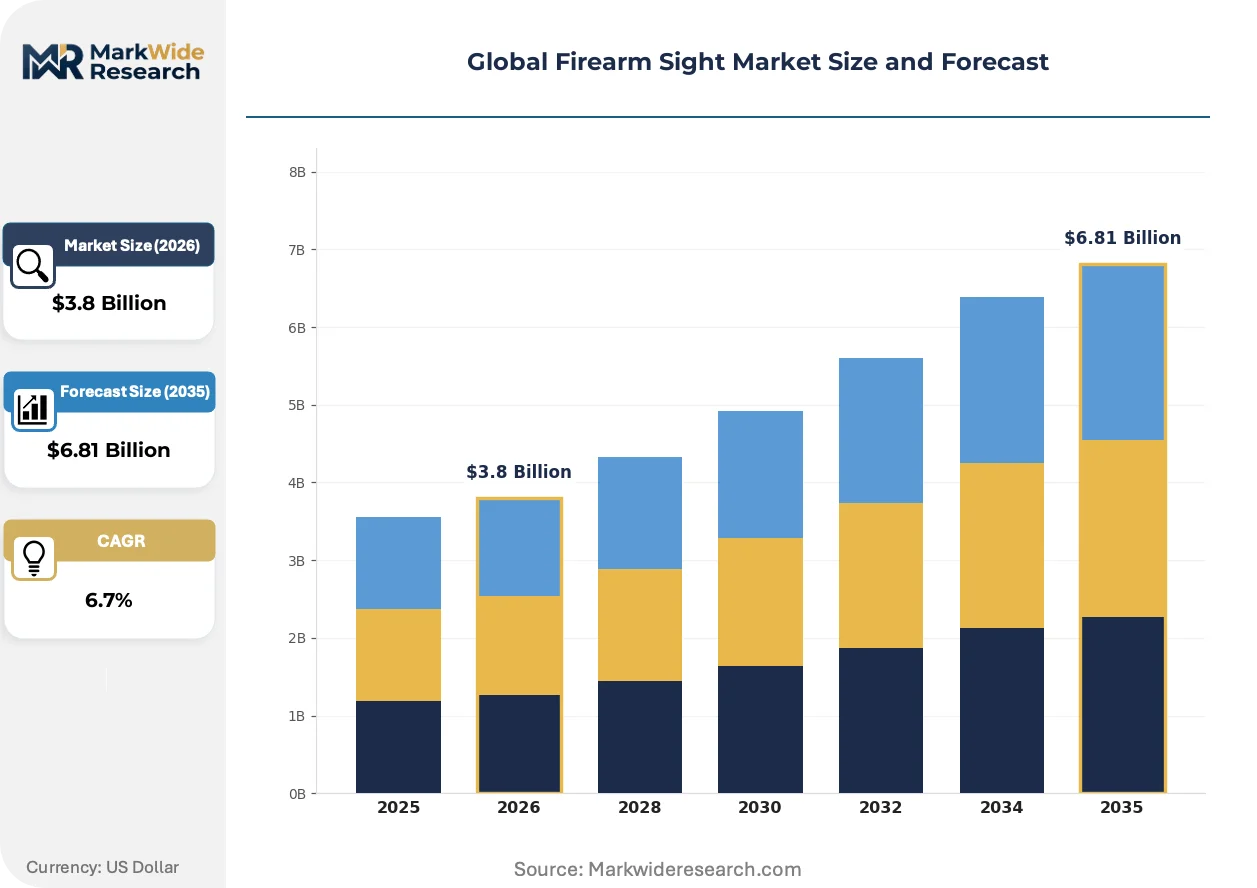
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Red Dot Sights, Holographic Sights, Telescopic Sights, Iron Sights Technology: Optical, Electronic, Laser, Reflex End User: Military, Law Enforcement, Civilian, Sports Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Distributors |
| Companies Covered | Aimpoint AB, Trijicon, Inc., Bushnell (Revelyst, Inc.), Leupold & Stevens, Inc., EOTECH, LLC, Leonardo DRS, Inc., SIG SAUER, Inc., Vortex Optics (Sheltered Wings, Inc.), Beretta Holding S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Firearm Sight Market Emerging Trajectories
Digital sensor fusion is collapsing the historical separation between day optics and thermal imaging, forcing sight architecture redesign around unified data processing cores rather than discrete optical paths.
Holographic waveguide technology is unifying reticle projection with transparent display layers, eliminating the mechanical emitter assemblies that dominate red dot construction. Special operations units in the United States and Germany are fielding prototype systems that integrate ballistic calculators directly into the sight picture. This convergence is compressing the supplier base toward electro-optics specialists with semiconductor packaging capabilities rather than traditional lens grinding heritage.
The EU Green Deal material restrictions on rare-earth phosphors and battery chemistries are forcing illumination technology roadmaps toward rechargeable solid-state architectures. Manufacturers serving European military and law enforcement channels must redesign tritium-dependent products before 2027 compliance deadlines. German KBA certification pathways now prioritize LED-based systems with documented recyclability profiles, advantaging domestic producers with established circular economy partnerships.
Direct-to-consumer channel control is displacing specialty retail intermediaries as primary buyer education venues. Vortex Optics and comparable brands invest in video content infrastructure that replicates in-store reticle demonstration functions. This shift concentrates marketing expenditure toward digital acquisition rather than distributor cooperative programs, with strongest penetration in United States civilian sporting segments where online firearm accessory purchase regulations permit streamlined fulfillment.
Global Firearm Sight Market Segmentation
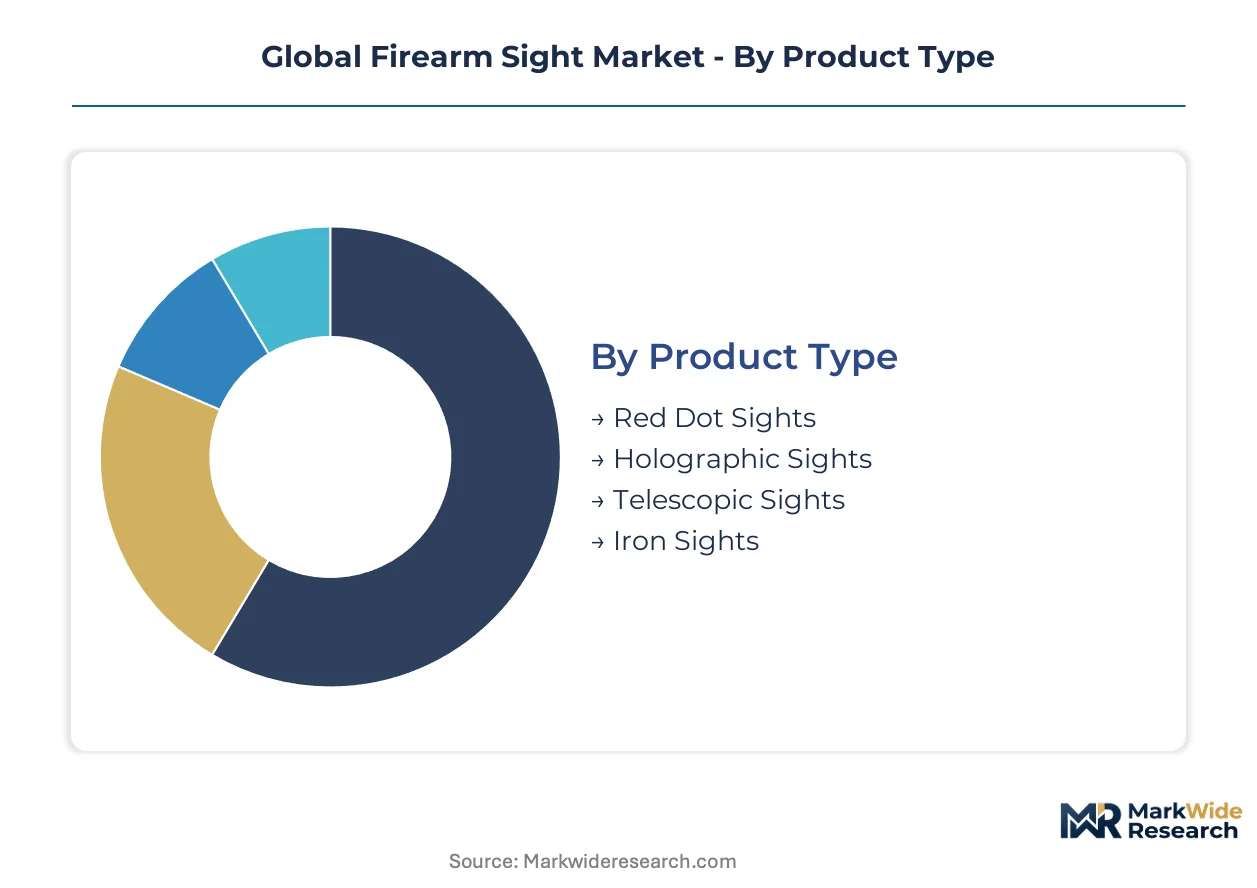
Firearm sight procurement divides sharply between institutional buyers demanding MIL-STD durability and civilian shooters prioritizing rapid target acquisition. Technology choices cascade through mounting systems, power architectures, and reticle designs that resist standardization across NATO, Warsaw Pact, and commercial rail interfaces.
Product Type:
Standardization pressures from military procurement programs clash with civilian demand for modular, multi-platform compatibility across this category.
- Red Dot Sights:LED emitter architectures project illuminated reticles through coated lenses onto spherical mirrors, eliminating parallax error at close quarters. Law enforcement training academies in Germany and Australia now mandate electronic sight certification, institutionalizing reflex technology adoption for CQB protocols.
- Holographic Sights:Laser-illuminated holographic gratings embed reticle patterns within glass layers, permitting heads-up engagement with both eyes open. United States special operations units field prototype systems integrating ballistic calculators directly into the sight picture, compressing supplier selection toward semiconductor packaging specialists.
- Telescopic Sights:Multi-element lens assemblies with coated optics deliver magnification for precision engagement beyond 300 meters.
- Iron Sights:Mechanical aperture and post configurations persist as backup systems and entry-level training platforms.
Leading the category by volume: Telescopic Sights. Growing fastest: Holographic Sights.
Technology:
Power consumption profiles and battery chemistry regulations in Europe are forcing divergence between rechargeable LED architectures and legacy tritium illumination systems.
- Optical:Passive lens systems relying on ambient light transmission through coated glass elements dominate long-range precision segments where battery dependency creates operational risk.
- Electronic:Active emitter circuits with intensity-adjustable LEDs now dominate close-quarters training protocols. EU Green Deal restrictions on lithium-thionyl chloride cells incentivize development of rechargeable architectures with domestic European supply chains.
- Laser:Coherent light projection enables visible and infrared aiming points for night vision fusion applications.
- Reflex:Unlimited eye relief and parallax-free operation accelerate target acquisition speed for dynamic shooting scenarios.
Highest shipment volumes concentrate in Electronic. Steepest expansion trajectory belongs to Laser.
End User:
Budget cycles and replacement timelines stretch institutional procurement over 5-10 year horizons while civilian aftermarket demand responds to competitive shooting federation rule changes.
- Military:ITAR-controlled procurement programs prioritize tritium longevity and night vision compatibility. Extended phosphor half-life formulations reduce lifecycle replacement frequency, improving total cost metrics for allied defense ministries.
- Civilian:Sporting and hunting applications drive reflex sight adoption as practical shooting federations mandate faster sight acquisition standards. Australian national pistol and rifle federations report membership growth exceeding infrastructure capacity, creating sustained aftermarket upgrade demand.
- Law Enforcement:Academy training mandates now require electronic sight proficiency for close-quarters combat certification.
- Sports:Three-gun and IPSC competition formats privilege rapid transition speed over magnification range.
Dominant volume share: Military. Climbing fastest: Civilian.
Distribution Channel:
Channel control strategies diverge between brands investing in direct digital education infrastructure and those defending specialty retail relationships.
- Online Retail:Video content infrastructure replicates in-store reticle demonstration functions, concentrating marketing expenditure toward digital acquisition. United States regulations permitting streamlined firearm accessory fulfillment enable strongest penetration in civilian sporting segments.
- Specialty Stores:Hands-on mounting and zeroing services retain importance for precision telescopic sight selection where optical clarity testing requires physical inspection.
- Direct Sales:Military and law enforcement procurement channels bypass retail intermediaries for volume contract negotiation.
- Distributors:Inventory pooling across proprietary rail systems necessitates SKU proliferation that complicates forecasting for multi-platform accessory lines.
Volume leadership: Specialty Stores. Fastest channel shift: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Sweden and Germany while consumption tilts toward the United States and Australia, creating transatlantic trade flows in precision optical components.
United States
Civilian sporting demand and special operations procurement drive volume. The Bureau of Alcohol, Tobacco, Firearms and Explosives regulates sight classification under firearm accessory frameworks. Wisconsin and Arizona host precision manufacturing clusters where tritium illumination systems undergo assembly for military contract fulfillment.
Germany
Law enforcement academy mandates now require electronic sight certification for close-quarters combat modules. The Kraftfahrt-Bundesamt enforces CE marking and pressure-resistance standards that shape European product certification pathways. Thuringia's optical heritage region sustains vacuum deposition expertise for ion-beam sputtering operations serving defense ministries.
Australia
National pistol and practical rifle federations report membership growth exceeding infrastructure capacity, creating aftermarket sight upgrade demand. The Therapeutic Goods Administration oversees device compliance for law enforcement procurement channels. Queensland and Victoria host competitive shooting facilities that drive reflex sight adoption among civilian marksmen.
Sweden
Military procurement programs prioritize extended phosphor half-life formulations that reduce lifecycle replacement frequency. The Swedish Defence Materiel Administration coordinates NATO-aligned sight standardization initiatives. Stockholm's electro-optics corridor maintains premium positioning in allied defense ministry supply chains.
China
Domestic manufacturing compliance for optical components serves both military and civilian supply chains under SAMR and GB standards. The State Administration for Market Regulation controls rare-earth phosphor exports that constrain tritium sight production capacity outside Asia-Pacific clusters. Guangdong and Jiangsu provinces concentrate lens grinding and LED emitter assembly operations.
Global Firearm Sight Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers. The vendor base clusters around three strategic archetypes: premium military contractors with tritium and night-vision heritage, mid-tier warranty innovators with direct-to-consumer channel control, and diversified defense conglomerates with vertical integration into firearm platforms. M&A activity targets electro-optics packaging capabilities while geographic expansion focuses on Australian and German law enforcement certification pathways.
Among Nordic precision specialists, Aimpoint AB exemplifies premium military positioning through Swedish manufacturing heritage. Trijicon, Inc. and Vortex Optics occupy distinct competitive vectors—one anchored in tritium illumination longevity for institutional buyers, the other in aggressive warranty terms and digital channel control for civilian sporting segments. These three represent the archetype spectrum from defense-pure to consumer-scaled operations.
| Leading Market Players |
|---|
| Aimpoint AB |
| Trijicon, Inc. |
| Bushnell (Revelyst, Inc.) |
| Leupold & Stevens, Inc. |
| EOTECH, LLC |
| Leonardo DRS, Inc. |
| SIG SAUER, Inc. |
| Vortex Optics (Sheltered Wings, Inc.) |
| Beretta Holding S.A. |
| Others |
Supply Flow & Price Mechanics
Germanium and sapphire substrate price indices cascade through precision telescopic sight manufacturing into three-tier pricing structures across premium, standard, and economy levels. Input volatility from semiconductor demand cycles compresses margin pools for manufacturers while procurement officers at allied defense ministries negotiate multi-year contracts that lock in volume discounts.
Pricing Analysis
Margin tightening in mid-tier electronic sight segments reflects rare-earth phosphor supply concentration under Chinese SAMR export controls. Pricing stratifies across premium tritium-illuminated military units, standard LED-based law enforcement systems, and economy reflex sights for civilian sporting applications. Cost-down pressure on standard-tier products accelerates as Vortex Optics and comparable brands compete aggressively on warranty terms. Civilian competitive shooters exhibit highest price sensitivity, while special operations procurement programs prioritize phosphor longevity over unit cost.
Supply Chain Analysis
Regional distribution centers in Wisconsin and Arizona coordinate hub-and-spoke fulfillment patterns for tritium illumination assembly operations. Manufacturing concentrates in Sweden, Germany, and the United States, with vacuum deposition expertise concentrated in Thuringia and Stockholm's electro-optics corridor. Supply chains draw from Chinese rare-earth processing for europium and terbium compounds, German optical glass substrates, and Taiwanese LED emitter components. Single-source vulnerability around Chinese phosphor exports constrains tritium sight production capacity outside Asia-Pacific clusters. Distribution runs through direct-to-consumer digital channels and specialty retail intermediaries with hands-on mounting services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into semiconductor packaging capabilities and captive LED emitter production is reshaping competitive positioning as holographic waveguide technologies displace mechanical emitter assemblies. Players are racing upstream to secure electro-optics expertise that fuses digital processing cores with conventional optical paths.
For Market Incumbents: Deepen backward integration into ion-beam sputtering operations and rare-earth phosphor recycling partnerships to defend against supply concentration risks. Secure German KBA certification pathways ahead of EU Green Deal battery chemistry deadlines. Reinforce direct-to-consumer channel control with video content infrastructure that replicates in-store reticle demonstration functions. For New Entrants and Emerging Players: Launch via Australian law enforcement and civilian competitive shooting federations where membership growth exceeds infrastructure capacity. Target aftermarket sight upgrade demand in Queensland and Victoria practical rifle facilities. Enter through digital-native distribution models that bypass legacy specialty retail relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier warranty innovators with established direct-to-consumer infrastructure in United States civilian sporting segments. Acquire electro-optics specialists with semiconductor packaging capabilities rather than traditional lens grinding heritage. Watch ITAR threshold adjustments and EU Green Deal compliance deadlines as inflection indicators for technology transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Emitter Production | Captive supply of rechargeable architectures reduces dependency on lithium-thionyl chloride cell imports restricted by EU Green Deal regulations. |
| German KBA Certification Pathway Investment | CE marking and pressure-resistance validation opens institutional procurement channels across European defense ministries and law enforcement academies. |
| Direct-to-Consumer Channel Expansion | Video content infrastructure replicates in-store reticle demonstration functions while concentrating marketing expenditure toward digital acquisition. |
| Thermal-Night Vision Fusion Platform Development | Digital overlay integration with SWIR sensors commands premium pricing tiers for hog hunting and tactical training verticals. |
| Rare-Earth Phosphor Recycling Partnership | Circular economy alliances with European domestic producers address material restrictions while securing supply chain resilience. |
Methodological Framework
Document review covered ITAR licensing databases, German KBA certification registries, and Australian TGA device compliance records, complemented by interviews with electro-optics R&D directors, defense ministry procurement officers, law enforcement training academy instructors, and specialty retail channel managers. Secondary validation drew from Bureau of Alcohol, Tobacco, Firearms and Explosives accessory classification frameworks, EU Green Deal material restriction proposals, and Chinese SAMR export control filings. Bottom-up shipment estimates by product type and technology tier were triangulated against top-down military procurement budget allocations and civilian competitive shooting federation membership data.
Unit shipment and revenue outputs across the analysis window reflect a structured analytical framework incorporating product type segmentation by sight architecture, technology tier by power and illumination source, end-user category by institutional versus civilian demand, and distribution channel by digital versus physical fulfillment. CAGRs were derived from regression analysis against historical replacement cycle compression in military training programs and civilian federation rule changes. Forecast inputs included rare-earth phosphor supply elasticity, ITAR licensing velocity, and EU battery chemistry compliance timelines.
ITAR threshold adjustments, Chinese SAMR export control tightening, and EU Green Deal enforcement acceleration are the dominant revision risks that could alter trajectory assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Electronic Alarms Market
Security and Surveillance
Europe Border Security Market
Security and Surveillance
Global School and Campus Security Market
Security and Surveillance
North America Security Services Market
Security and Surveillance
Global Contraband Detector Market
Security and Surveillance
Global Threat Intelligence Management Market
Security and Surveillance
Home Security Solution Market
Security and Surveillance
Security Holograms Market
Security and Surveillance
Consumer Security Market
Security and Surveillance
Airport Baggage Screening Systems Market
Security and Surveillance
Private Security Market
Security and Surveillance
Signal Jamming Systems Market
Security and Surveillance
Middle East and Africa Baggage and Parcel Screening Market
Security and Surveillance
Global Bot Security Market
Security and Surveillance
Global Manned Security Service Market
Security and Surveillance
Middle East and Africa Cargo Inspection Market