
 Air Cargo Security and Screening Systems Market | 2026-2036
Air Cargo Security and Screening Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Air Cargo Security and Screening Systems Market Intelligence
Certified explosive detection standards is bifurcating the competitive landscape into Tier 1 integrators and specialized subsystem vendors. L3Harris Technologies leverages its TSA-certified platform portfolio to dominate North American airport installations. Smiths Detection anchors European demand through its hold baggage and cargo screening certifications under EASA frameworks. Rapiscan Systems competes aggressively in emerging markets with modular checkpoint configurations that reduce deployment lead times.
Air cargo security and screening systems comprise integrated hardware-software platforms designed to detect prohibited items, explosives, and contraband in aviation freight using multi-energy X-ray transmission, computed tomography density analysis, and automated threat recognition algorithms with throughput rates exceeding 1,000 parcels per hour. CT Scan technology leads the technology segment due to its three-dimensional imaging capability that reduces false alarm rates below five percent, while integrated solutions command the highest margin pools in the offering category by bundling hardware, AI-powered analytics, and multi-year maintenance contracts. Freight forwarding applications represent the fastest-growing application segment as third-party logistics providers assume screening liability from airlines under new security programs.
The Transportation Security Administration mandates 100 percent cargo screening on passenger aircraft through its Certified Cargo Screening Program, while the European Union Aviation Safety Agency enforces Regulation 2015/1998 standards for air cargo and mail security. The International Civil Aviation Organization's Annex 17 framework shapes baseline requirements that national regulators adapt into binding legislation. Stakeholders must monitor divergence between TSA-certified and EASA-approved detection thresholds as dual-certification costs reshape vendor selection criteria for multinational logistics networks.
Market Dynamics
Dual-certification mandates from TSA and EASA are fragmenting vendor economics and forcing logistics networks to consolidate screening infrastructure around fewer, multi-qualified integrators.
Growth Catalysts
- E-commerce parcel volumes:Third-party logistics providers in the United Arab Emirates are expanding dedicated cargo terminals at Dubai International and Al Maktoum International to handle cross-border freight screening.
- EU Regulation 2015/1998:Updated explosive detection standards for all-cargo aircraft operations mandate enhanced screening protocols across European freight forwarding networks.
- Computed tomography density analysis:Three-dimensional imaging capability reduces false alarm rates below five percent, accelerating throughput at high-volume express hubs.
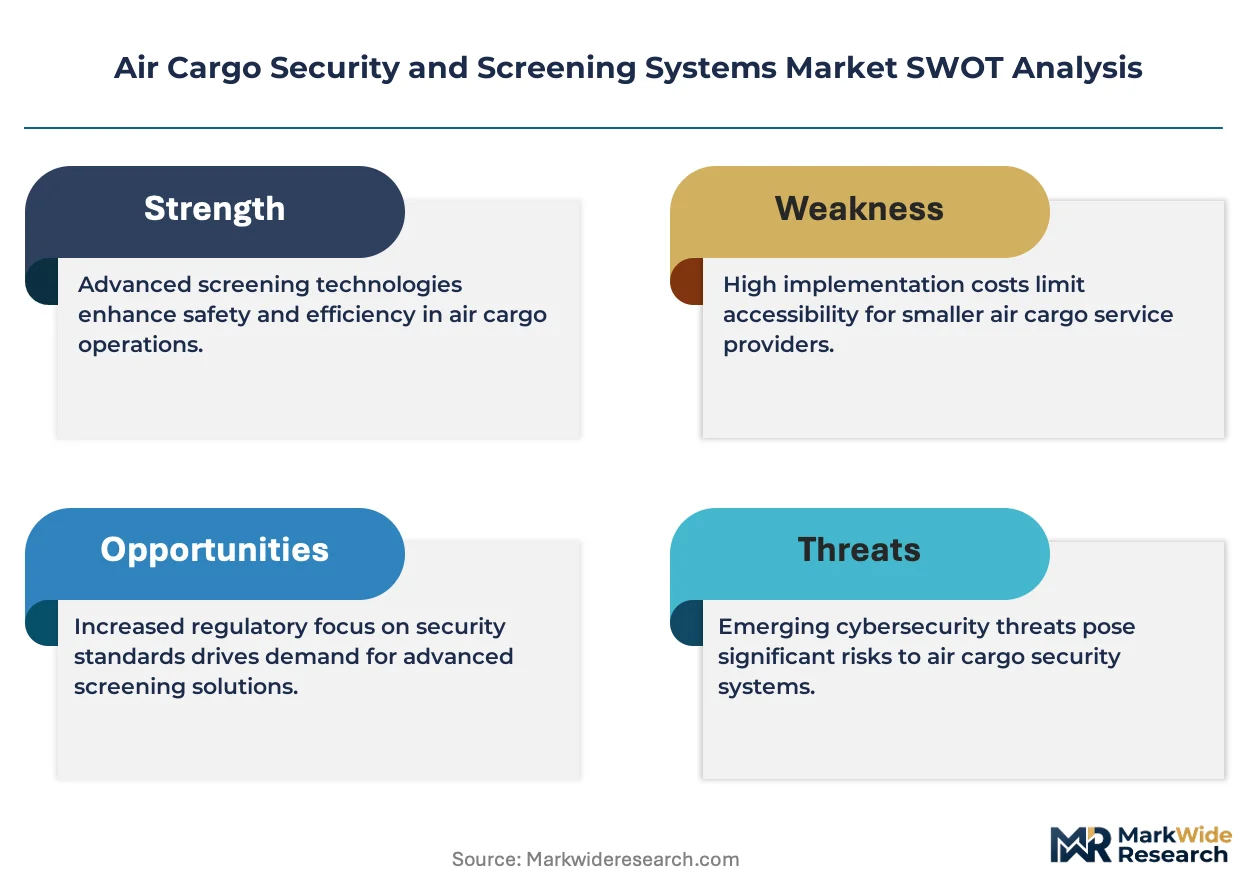
Market Restraints
- Dual-certification cost burden:Vendors must maintain parallel TSA-certified and EASA-approved detection thresholds, compressing margins on multinational deployments.
- Specialized component concentration:X-ray tube and detector module supply concentrates among German and Japanese precision manufacturers, creating input bottlenecks.
- Legacy system integration friction:Automated threat recognition algorithms require extensive retrofitting to interface with existing baggage handling infrastructure.
Strategic Opportunities
- Freight forwarding liability transfer:Third-party logistics providers assuming screening responsibility from airlines under new security programs creates demand for modular checkpoint configurations.
- AI-powered analytics bundling:Integrated solutions combining hardware, machine learning threat detection, and multi-year maintenance contracts command premium positioning.
- Throughput rate optimization:Systems exceeding 1,000 parcels per hour address capacity constraints at express carrier sortation facilities in Germany and the Netherlands.
Industry Challenges
- Certification timeline compression:TSA's Certified Cargo Screening Program and EASA framework updates require simultaneous compliance documentation, straining engineering resources.
- Threat recognition algorithm training:Automated detection systems require continuous dataset expansion to address emerging explosive device configurations and contraband concealment methods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Cargo Security and Screening Systems Market |
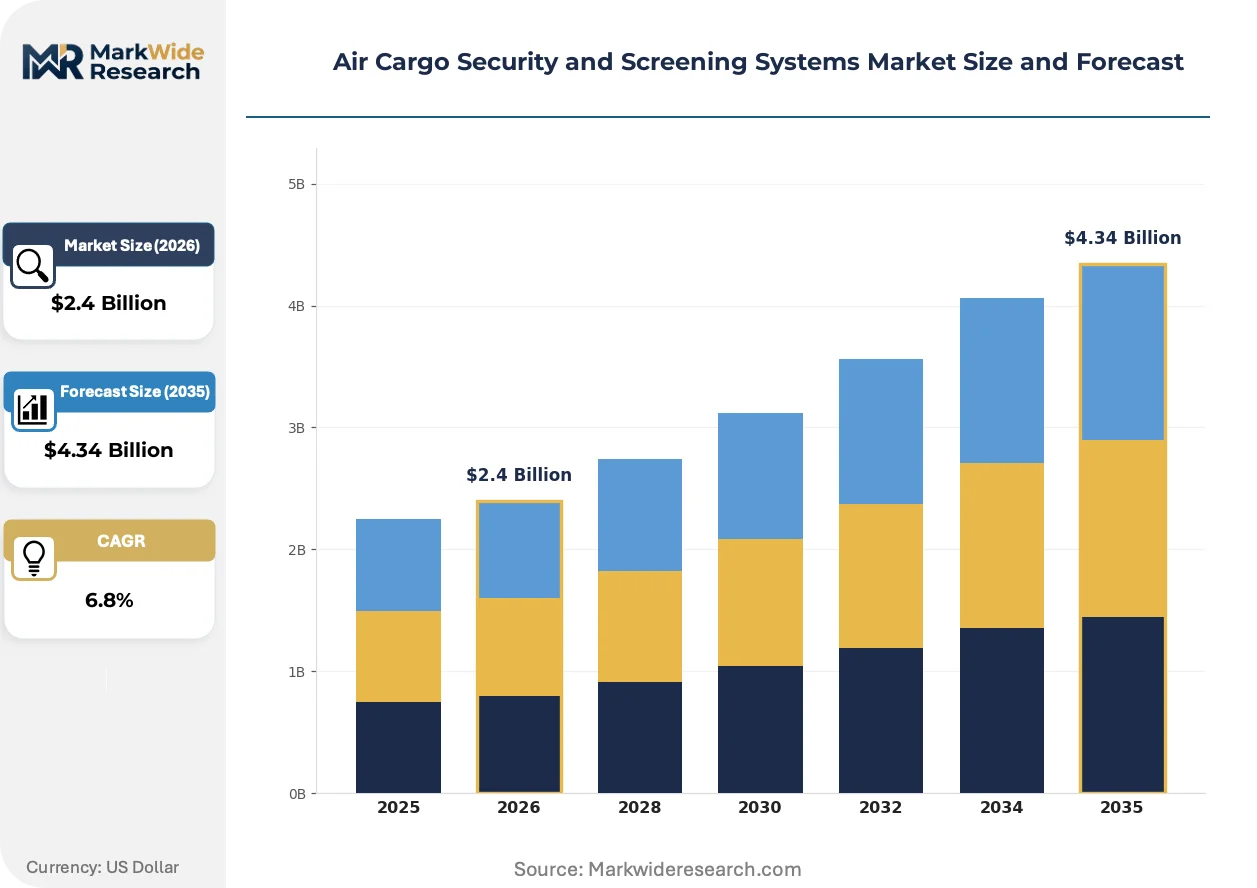
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: X-Ray, CT Scan, Metal Detection, Infrared Application: Airports, Freight Forwarding, Cargo Terminals, Military Offering: Hardware, Software, Integrated Solutions, Services End User: Aviation Authorities, Shipping Companies, Government Agencies, Logistics Providers |
| Companies Covered | L3Harris Technologies, Smiths Detection, Rapiscan Systems, Nuctech Company Limited, Leidos, OSI Systems, Analogic Corporation, Thales, Gilardoni S.P.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Cargo Security and Screening Systems Market Strategic Shifts & Innovations
Multi-energy X-ray transmission architectures are converging with machine learning inference engines to enable real-time threat classification without human operator intervention at high-throughput cargo terminals.
Computed tomography screening is supplanting conventional two-dimensional X-ray systems in European express hubs and Middle Eastern cargo terminals. DHL and FedEx ground operations in Germany and the UAE are deploying CT-based hold baggage and cargo screening units to meet EASA certification requirements. This technology shift is compressing deployment timelines for modular checkpoint configurations that reduce installation lead times.
ICAO's Annex 17 framework is shaping baseline security requirements that national regulators adapt into binding legislation across multiple jurisdictions. The divergence between TSA-certified and EASA-approved detection thresholds is forcing multinational logistics networks to standardize on dual-qualified equipment platforms. Freight forwarders operating across the Atlantic corridor face the steepest compliance burden as they reconcile divergent explosive detection sensitivity specifications.
Buyer procurement patterns are pivoting from capital equipment purchases toward performance-based service agreements that bundle hardware, software maintenance, and throughput guarantees. Major cargo carriers at Amsterdam Schiphol and Frankfurt airports are unbundling after-sales service from initial equipment contracts, favoring vendors with captive technical support networks. This shift is most pronounced in the Netherlands and Germany, where ground handlers face penalty structures for screening delays.
Air Cargo Security and Screening Systems Market Segmentation
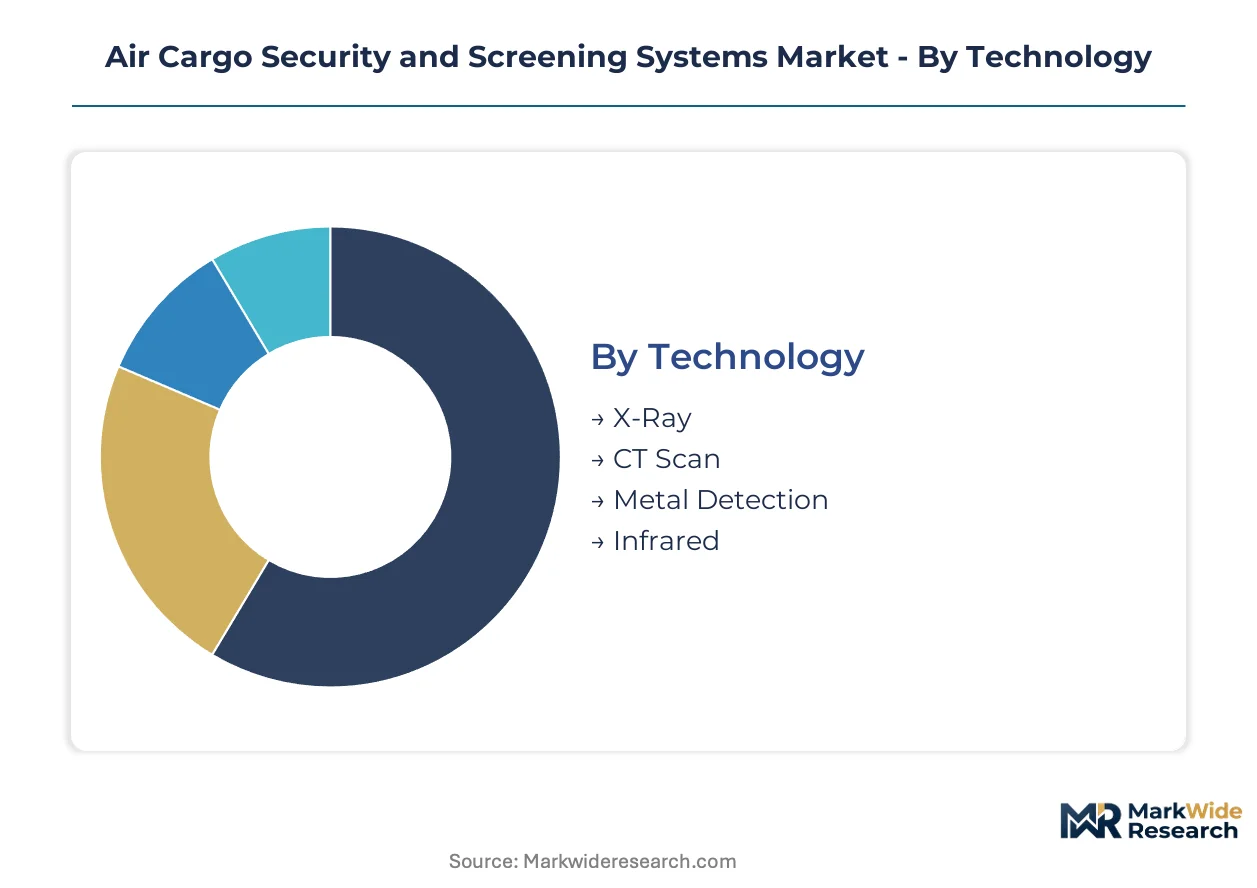
Technology substitution pressures and regulatory certification requirements create divergent growth trajectories across screening system categories. End-user liability transfers and throughput demands reshape procurement patterns toward bundled service models.
Technology:
CT Scan architectures face substitution pressure from next-generation multi-energy X-ray platforms that narrow the performance gap at lower capital intensity.
- CT Scan:Three-dimensional imaging systems deploy computed tomography density analysis to achieve false alarm rates below five percent. Demand concentrates at Dubai International Airport and Al Maktoum International cargo terminals where EASA-compliant explosive detection standards mandate enhanced screening protocols.
- X-Ray:Multi-energy transmission systems integrate automated threat recognition algorithms with throughput rates exceeding 1,000 parcels per hour. German and Dutch express carrier sortation facilities deploy these units to address capacity constraints while managing dual-certification cost burdens.
- Metal Detection:Electromagnetic screening platforms supplement primary explosive detection systems in legacy cargo terminal retrofits.
- Infrared:Thermal imaging technologies address specialized contraband detection applications in military logistics networks.
CT Scan retains volume leadership; X-Ray holds the steepest expansion curve.
Application:
Cost tier stratification separates capital-intensive airport installations from modular freight forwarding deployments that reduce deployment lead times.
- Freight Forwarding:Third-party logistics providers assume screening liability from airlines under TSA Certified Cargo Screening Program and EASA Regulation 2015/1998 frameworks. Cross-border e-commerce volumes in the United Arab Emirates drive dedicated cargo terminal expansion at Dubai International and Al Maktoum International.
- Airports:Integrated hold baggage and cargo screening systems serve passenger aircraft operations under TSA 100 percent cargo screening mandates. Amsterdam Schiphol and Frankfurt procurement patterns pivot toward performance-based service agreements bundling hardware and multi-year maintenance.
- Cargo Terminals:Dedicated all-cargo aircraft screening infrastructure addresses EU updated explosive detection standards.
- Military:Specialized threat recognition configurations address emerging explosive device configurations in defense logistics networks.
Airports command the premium tier; Freight Forwarding climbs fastest on liability transfer momentum.
Offering:
Margin concentration pools in integrated solutions that combine hardware, AI-powered analytics, and multi-year maintenance contracts.
- Integrated Solutions:Bundled hardware-software platforms combine CT Scan or X-Ray transmission systems with machine learning inference engines and captive technical support networks. Major cargo carriers at Amsterdam Schiphol and Frankfurt unbundle after-sales service from initial equipment contracts.
- Hardware:Standalone screening units face margin compression from X-ray tube and detector module supply concentration among German and Japanese precision manufacturers.
- Software:Automated threat recognition algorithms require continuous dataset expansion to address emerging concealment methods.
- Services:Throughput guarantee contracts and penalty structures for screening delays reshape ground handler procurement in the Netherlands and Germany.
Integrated Solutions capture the margin pool; Services expands most quickly on outcome-based contracting adoption.
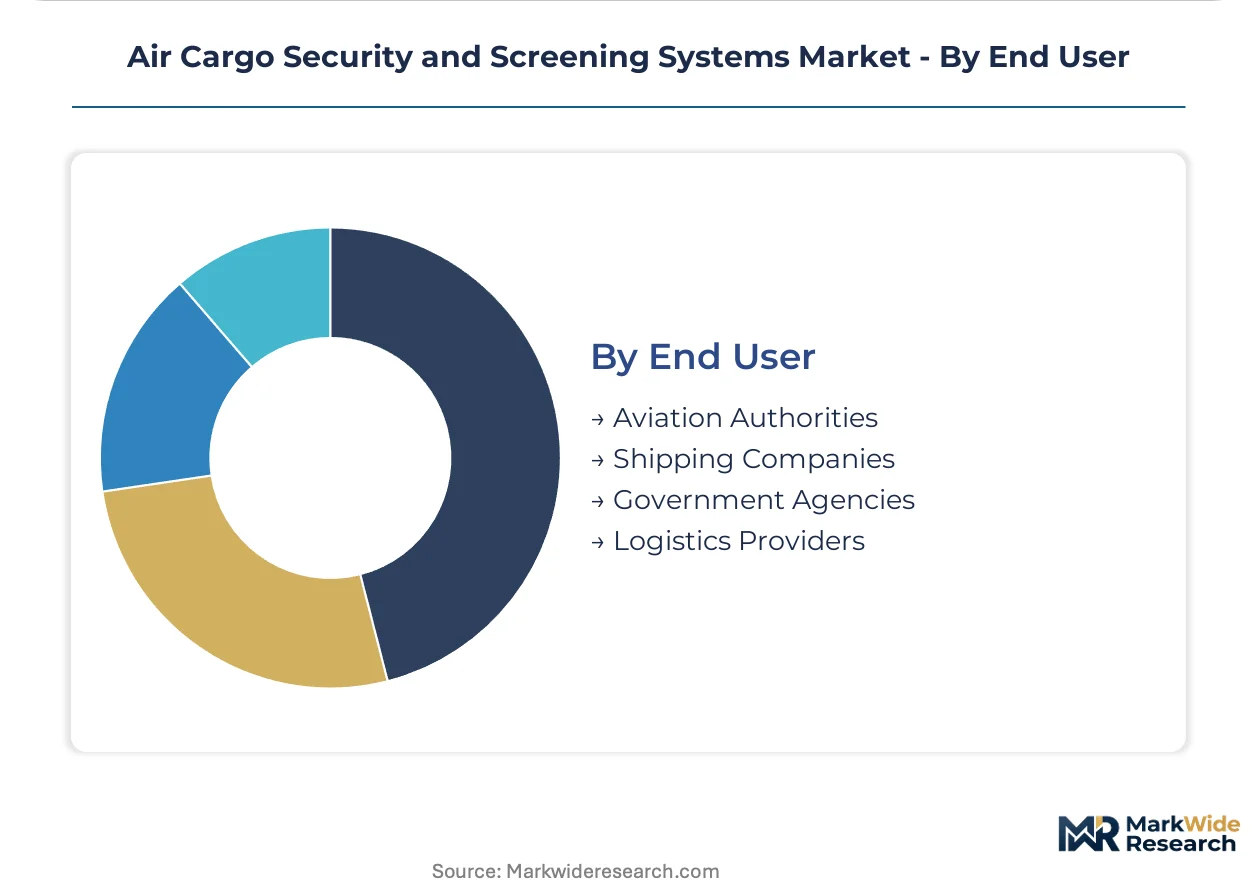
End User:
Customer type fragmentation splits procurement authority between regulatory-mandated aviation authorities and commercial logistics providers absorbing screening liability.
- Logistics Providers:DHL and FedEx ground operations in Germany and the UAE deploy CT-based screening units to meet EASA certification requirements while managing divergent TSA-certified detection thresholds. Third-party logistics networks consolidate screening infrastructure around fewer multi-qualified integrators.
- Aviation Authorities:National regulators adapt ICAO Annex 17 frameworks into binding legislation across multiple jurisdictions, enforcing compliance documentation that strains vendor engineering resources.
- Shipping Companies:Maritime-air intermodal operators face dual-certification costs for multinational freight networks.
- Government Agencies:Defense and customs authorities mandate specialized threat recognition configurations for contraband interdiction.
Logistics Providers drive commercial volume; Aviation Authorities anchor regulatory compliance spending.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement contexts. Ground handlers at European express hubs face penalty structures for screening delays, while emerging market cargo terminals prioritize capital efficiency over throughput guarantees.
United States
The Transportation Security Administration mandates 100 percent cargo screening on passenger aircraft through its Certified Cargo Screening Program. Third-party logistics providers assume screening liability from airlines under this framework, consolidating demand around multi-qualified integrators. Memphis and Louisville express hubs drive replacement cycles for legacy X-ray systems.
Germany
European Union Aviation Safety Agency Regulation 2015/1998 enforces updated explosive detection standards for all-cargo aircraft operations. Frankfurt and Leipzig cargo terminals deploy CT-based screening units to meet EASA certification requirements. German precision manufacturers concentrate supply of X-ray tube and detector modules, creating input bottlenecks for downstream integrators.
United Arab Emirates
Cross-border e-commerce volumes expand dedicated cargo terminals at Dubai International and Al Maktoum International. The country's national aviation regulator adapts ICAO Annex 17 frameworks into binding legislation for freight forwarding networks. Dubai South logistics district anchors regional screening infrastructure investment.
Netherlands
Amsterdam Schiphol procurement patterns pivot toward performance-based service agreements bundling hardware and multi-year maintenance. Dutch ground handlers face penalty structures for screening delays, reshaping vendor selection criteria. The Randstad logistics corridor concentrates demand for throughput-optimized systems exceeding 1,000 parcels per hour.
China
Domestic e-commerce logistics providers expand screening infrastructure to handle rising parcel volumes. The country's national aviation security regulator implements standards aligned with ICAO baseline requirements. Zhengzhou and Shanghai Pudong cargo terminals represent primary installation sites for integrated hardware-software platforms.
Air Cargo Security and Screening Systems Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Tier 1 integrators dominate procurement at regulated aviation hubs through certified platform portfolios, while specialized subsystem vendors capture retrofit opportunities with modular configurations. The vendor base separates into certification-heavy integrators, component specialists, and emerging-market cost optimizers. Consolidation pressure intensifies around dual-qualified equipment platforms, with strategic partnerships and geographic licensing agreements displacing pure organic expansion.
Among North American integrators, L3Harris Technologies and Leidos occupy positions within the certification-dependent tier, anchoring demand at TSA-regulated installations. Smiths Detection represents European archetype specialization, with its corporate structure reflecting continental regulatory alignment. Rapiscan Systems and Nuctech Company Limited exemplify divergent geographic positioning, with the latter's naming convention indicating Chinese operational origins.
| Leading Market Players |
|---|
| L3Harris Technologies |
| Smiths Detection |
| Rapiscan Systems |
| Nuctech Company Limited |
| Leidos |
| OSI Systems |
| Analogic Corporation |
| Thales |
| Gilardoni S.P.A. |
| Others |
Cost & Logistics Intelligence
Ninety-day procurement lead times for CT detector modules concentrate pricing power among German and Japanese precision manufacturers, compressing margins for downstream integrators while amplifying cost pass-through to freight forwarders absorbing screening liability under TSA and EASA frameworks.
Pricing Analysis
Multi-year maintenance and throughput guarantee contracts drive lifetime value for integrated solution vendors. Three-tier pricing structure across certified-premium, dual-qualified-standard, and single-certification-economy levels separates TSA-EASA dual-certified platforms from regional-only alternatives. Pricing pressure stems from freight forwarders consolidating procurement around fewer multi-qualified integrators. Logistics providers in the United Arab Emirates exhibit highest price sensitivity, while Amsterdam Schiphol ground handlers prioritize penalty-avoidance over capital efficiency.
Supply Chain Analysis
X-ray tube fabrication chokepoints in Germany and Japan concentrate supply risk for CT and multi-energy X-ray platforms. German precision manufacturers and Japanese detector specialists anchor component sourcing, with downstream integration drawing from Taiwanese electronics and Chinese structural fabrication. Single-source vulnerability in high-voltage X-ray tube supply exposes integrators to input bottlenecks. Distribution runs through authorized regional service networks with captive technical support capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted toward consolidated logistics networks that bundle screening procurement across multiple jurisdictions, fragmenting vendor economics and forcing standardization on dual-qualified equipment platforms.
For Market Incumbents: Secure TSA-EASA dual-certification moats by accelerating parallel compliance documentation before regulatory timeline compression intensifies. Backward integration into X-ray tube supply through strategic partnerships with German precision manufacturers reduces single-source vulnerability. Lock in freight forwarding networks with performance-based service agreements that bundle hardware, AI-powered analytics, and captive maintenance networks. For New Entrants and Emerging Players: EASA fast-track certification for modular checkpoint configurations opens white-space in emerging market cargo terminals where deployment lead times dominate procurement criteria. Target Middle Eastern express hubs in Dubai South logistics district where cross-border e-commerce volumes outpace incumbent installation capacity. Pursue channel partnerships with third-party logistics providers assuming screening liability from airlines under new security programs. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compression play because divergent TSA-EASA detection thresholds force perpetual certification investment that favors scaled integrators over component specialists. Acquisition targets should display captive technical support networks and existing dual-certification portfolios. Watch for ICAO Annex 17 framework harmonization initiatives as the signal for margin expansion or further vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Investment | Parallel TSA-EASA compliance documentation secures access to transatlantic logistics networks. |
| AI-Powered Analytics Bundling | Machine learning threat detection integration commands premium positioning in integrated solutions. |
| Throughput Optimization Partnership | Systems exceeding 1,000 parcels per hour address capacity constraints at German express hubs. |
| Regional Service Network Expansion | Captive technical support in the Netherlands and UAE reduces penalty exposure for ground handlers. |
| Component Supply Agreement | Strategic sourcing from German X-ray tube manufacturers mitigates input bottleneck risk. |
Research Approach
A standing panel of cargo terminal operations directors, aviation security compliance officers, freight forwarding procurement leads, and ground handler maintenance managers provided ongoing calibration against regulatory implementation timelines. Primary fieldwork combined structured interviews with secondary validation through TSA Certified Cargo Screening Program documentation, EASA Regulation 2015/1998 compliance filings, ICAO Annex 17 national adaptation records, and customs data on screening equipment imports. Bottom-up installation tracking and top-down logistics spend analysis were triangulated against vendor shipment disclosures.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. The analytical framework modeled technology substitution curves, application liability transfers, offering bundling trajectories, and end-user procurement consolidation patterns. CAGRs were derived from segmented growth rate reconciliation against baseline regulatory mandate implementation schedules. Forecast inputs incorporated e-commerce parcel volume trajectories and dual-certification cost burden projections.
Decision-makers should treat outputs as directional under stable regulatory divergence assumptions; material harmonization between TSA and EASA detection thresholds would warrant model refresh. Practitioners should keep alternative scenarios live as freight forwarding liability transfer momentum and CT technology substitution rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Home Security Sensors Market
Security and Surveillance
Europe Security Assurance Market
Security and Surveillance
North America Wireless Monitoring and Surveillance Market
Security and Surveillance
Security Intelligence Market
Security and Surveillance
Global Manned Security Service Market
Security and Surveillance
Explosive Vapour Detector Market
Security and Surveillance
North America Cargo and Vehicle Screening Market
Security and Surveillance
Global Container Security Market
Security and Surveillance
North America Security Screening Market
Security and Surveillance
Latin America Security Services Market
Security and Surveillance
Global School and Campus Security Market
Security and Surveillance
Security Analytics Market
Security and Surveillance
Commercial Security Market
Security and Surveillance
Consumer Security Market
Security and Surveillance
Global X-Ray Security Scanner Market
Security and Surveillance
Global Physical Security Software Market