
 US Video Surveillance Market | 2026-2036
US Video Surveillance Market Size, Share, and Industry Trends Forecast 2026-2036
US Video Surveillance Market Analytics
Multi-source component procurement is pivoting toward vertically integrated domestic manufacturing as supply chain resilience becomes a priority for security-sensitive installations. Honeywell International Inc. leverages its aerospace and building automation heritage to anchor integrated command-and-control platforms for critical infrastructure clients. Axis Communications specializes in open-architecture IP camera systems that sustain interoperability across heterogeneous network environments. Bosch Security Systems competes through precision-engineered image sensors manufactured at its North American facilities.
Video surveillance encompasses networked camera systems, digital video recorders, and video management software that capture, transmit, store, and analyze visual data for security monitoring and operational intelligence, typically operating at resolutions from 1080p to 4K with frame rates between 15 and 60 fps for forensic-quality evidence capture. The technology dimension shows IP-based systems displacing legacy analog infrastructure as enterprise customers prioritize Power-over-Ethernet deployment and edge-computing analytics. Cameras dominate product value pools where AI-enabled units command premium positioning, while cloud-based installation models are expanding fastest among mid-market retail and healthcare adopters seeking subscription-based operational expenditure structures.
The Federal Communications Commission governs wireless spectrum allocation for transmission systems, while the National Defense Authorization Act restricts procurement of specified foreign-manufactured equipment for federal installations, directly altering vendor eligibility and supply chain certification requirements. State legislatures in Illinois, Texas, and California have enacted biometric privacy statutes that mandate consent protocols and data retention limits for facial recognition deployments, creating fragmented compliance obligations across multi-jurisdictional operator networks. Stakeholders must monitor emerging algorithmic accountability rules and federal procurement blacklists that will determine eligible supplier pools and technology architecture decisions.
Market Dynamics
The US video surveillance market is restructuring around federal procurement mandates that blacklist foreign-manufactured components from critical infrastructure deployments. This regulatory pivot is compressing supplier pools while accelerating domestic manufacturing investments and edge-computing adoption patterns.
Growth Catalysts
- NDAA Section 889 Compliance:Federal agencies must purge specified Chinese-origin equipment from security networks by statutory deadlines, creating replacement demand across military bases, ports, and government facilities.
- Smart City Infrastructure:Metropolitan planning departments in California, Texas, and New York are bundling video analytics with traffic management and emergency response systems.
- Edge AI Chipsets:On-camera inference processors are reducing bandwidth costs for real-time facial recognition and behavioral analytics in retail loss prevention and healthcare patient monitoring.
Market Restraints
- Image Sensor Supply Concentration:Advanced CMOS sensors for low-light capture depend on concentrated Asian fabrication capacity, exposing integrators to allocation delays.
- Biometric Privacy Fragmentation:Illinois BIPA, Texas CUBI, and California CCPA create conflicting consent and retention rules that multiply compliance costs for multi-state operators.
- Cloud Storage Substitution:On-premise NVR/DVR hardware faces displacement from subscription-based cloud archival models that shift capital expenditure to operating expenditure.
Strategic Opportunities
- Rural Broadband Expansion:USDA ReConnect and NTIA BEAD program investments are extending IP camera viability to agricultural operations and tribal lands previously limited to cellular trail cameras.
- Healthcare Fall Detection:Acute care facilities and senior living operators are deploying privacy-preserving depth cameras for automated patient safety monitoring without continuous video recording.
- Converged Physical-Cyber Security:IT security teams are unifying network access control with video identity verification, opening unified vendor positions for zero-trust architecture providers.
Industry Challenges
- Video Forensics Certification:Law enforcement agencies require LEVA or IAI-certified technicians for evidence admissibility, creating talent bottlenecks in municipal procurement.
- Hybrid Cloud Integration:Enterprises running legacy on-premise VMS platforms face complex API mapping and data migration costs when adopting cloud-native analytics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Video Surveillance Market |
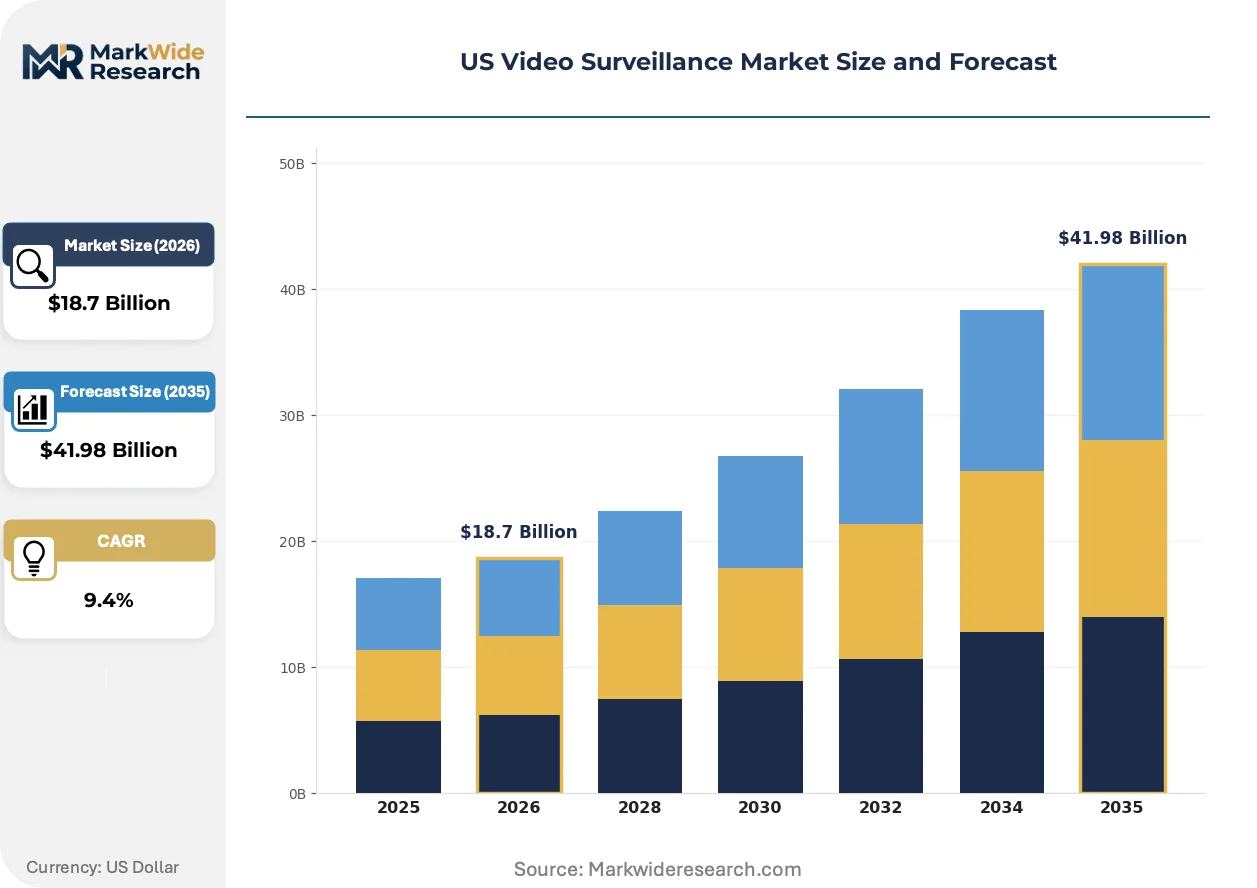
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
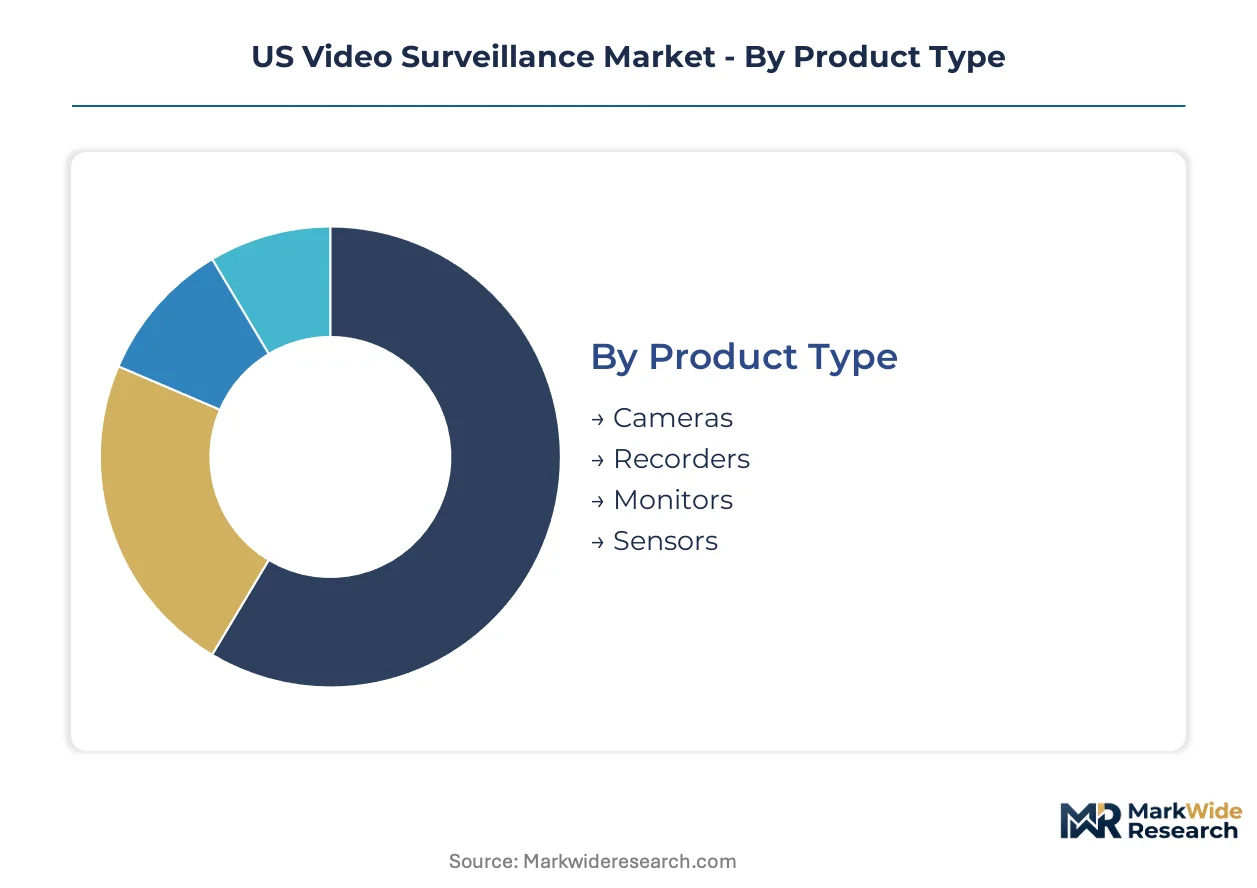
| Segmentation | Product Type: Cameras, Recorders, Monitors, Sensors Technology: Analog, IP, HD-CCTV, Wireless End User: Government, Transportation, Retail, Healthcare Installation: On-Premise, Cloud-Based, Hybrid, Managed |
| Companies Covered | Honeywell International Inc., Bosch Security Systems, Axis Communications, Hikvision, Dahua Technology, Motorola Solutions, Hanwha Vision, ADT, Teledyne FLIR, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Video Surveillance Market Evolving Landscape
Video surveillance architecture is converging toward software-defined platforms where hardware commoditization meets algorithmic differentiation. This shift is redistributing value from camera manufacturers to analytics providers and cloud infrastructure operators.
Multi-sensor fusion technology is unifying thermal, visible-light, and radar inputs into single-stream analytics for perimeter security applications. Critical infrastructure operators at power substations and chemical facilities are deploying these unified platforms to reduce false alarm rates. The technology is compressing the competitive advantage of single-modality camera specialists while elevating systems integrators with cross-sensor calibration expertise.
The FCC's 6 GHz spectrum expansion for unlicensed Wi-Fi 6E devices is enabling higher-resolution wireless camera deployments without licensed spectrum costs. Industrial facilities and construction sites are adopting these unlicensed links for temporary surveillance networks. The policy shift most benefits mobile and rapid-deployment segments previously constrained by Ethernet cabling economics.
Municipal procurement offices are consolidating video surveillance contracts into multi-year managed service agreements with outcome-based performance clauses. These arrangements displace traditional capital-purchase RFPs with subscription models covering hardware, connectivity, and analytics. The pattern is most advanced in mid-sized cities lacking internal IT security expertise for cyber-hardening camera networks.
US Video Surveillance Market Segmentation
US video surveillance procurement splits sharply between standalone security deployments and embedded systems integrated into broader building automation or IT infrastructure. Understanding these integration patterns reveals which segments command premium pricing versus commodity positioning.
Product Type:
Cameras function as standalone perimeter sentinels in most retail and municipal deployments, while recorders and sensors increasingly embed into unified command platforms for critical infrastructure.
- Cameras:AI-enabled units with on-board inference processors now dominate federal and enterprise procurement, particularly for facial recognition compliance with Illinois BIPA and Texas CUBI consent protocols. California metropolitan corridors account for disproportionate volume as smart city infrastructure investments cluster in Los Angeles, San Francisco, and San Diego metropolitan planning districts.
- Recorders:Network video recorders with edge-computing analytics are displacing legacy DVR architectures in healthcare and transportation verticals. Federal agencies under NDAA Section 889 mandates are accelerating replacement cycles for Chinese-origin equipment at military installations and port facilities.
- Monitors:Command-center display walls for fusion of multi-sensor feeds.
- Sensors:Thermal and radar inputs for perimeter detection at power substations.
Cameras lead volumes today; recorders are gaining share fastest as compliance-driven replacement cycles accelerate.
Technology:
Cost tiers separate legacy infrastructure from next-generation deployments, with federal procurement mandates compressing the mid-market analog transition window.
- IP:Power-over-Ethernet systems with 4K resolution and 60 fps capture dominate enterprise and government RFPs. Texas and New York metropolitan corridors show concentrated demand as municipal police departments expand networked camera coverage for public safety monitoring.
- Analog:Coaxial-based systems persist in cost-constrained small retail and rural agricultural operations. USDA ReConnect program investments are gradually extending IP viability to previously underserved tribal lands and farming cooperatives.
- HD-CCTV:High-definition coaxial bridge technology for incremental upgrades without full infrastructure replacement.
- Wireless:FCC 6 GHz unlicensed spectrum deployments for temporary construction and industrial site monitoring.
IP systems anchor revenue concentration; wireless installations are expanding most quickly in mobile and rapid-deployment segments.
End User:
Application-specific compliance burdens and threat models create divergent procurement patterns across verticals.
- Government:Federal agencies and municipal police departments drive NDAA-compliant procurement with mandatory domestic supply chain certification. State-level biometric privacy statutes in Illinois, Texas, and California fragment deployment protocols for facial recognition systems.
- Healthcare:Acute care facilities deploy privacy-preserving depth cameras for automated fall detection without continuous recording. Senior living operators in California and New York metropolitan areas lead adoption of patient safety monitoring systems.
- Transportation:Traffic management integration with emergency response systems in smart city bundles.
- Retail:Loss prevention analytics with behavioral recognition for shrinkage reduction.
Government verticals dominate contract value; healthcare applications are climbing the fastest as patient safety regulations tighten.
Installation:
Customer type and internal IT capability determine whether operators prefer capital expenditure ownership or operational expenditure flexibility.
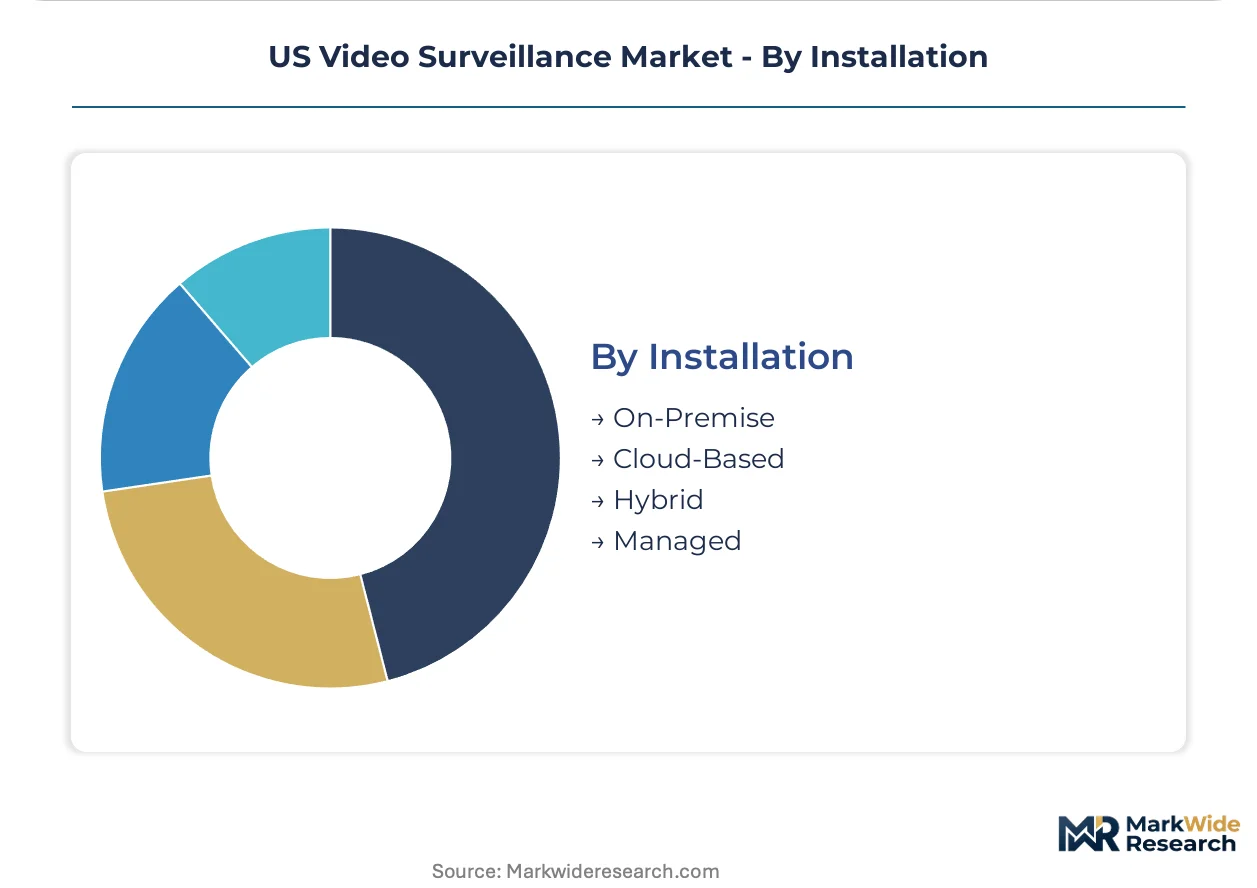
- Cloud-Based:Subscription models attract mid-market retail and healthcare adopters lacking internal cybersecurity expertise for camera network hardening. Municipal procurement offices in mid-sized cities are consolidating into multi-year managed service agreements with outcome-based performance clauses.
- Hybrid:Enterprises with legacy on-premise VMS platforms adopt cloud-native analytics through complex API mapping. Critical infrastructure operators at chemical facilities and power substations favor this architecture for sensitive perimeter data retention.
- On-Premise:Traditional NVR/DVR ownership for organizations with established security operations centers.
- Managed:Full outsourcing of hardware, connectivity, and analytics to systems integrators.
Hybrid installations hold the largest installed base; cloud-based models are gaining share fastest among IT-constrained operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's metropolitan technology corridors anchor US video surveillance procurement volume, with federal compliance mandates and state biometric privacy laws fragmenting deployment patterns across sub-regional markets.
California
Los Angeles, San Francisco, and San Diego metropolitan planning districts concentrate smart city infrastructure investments bundling traffic management with emergency response systems. The California Consumer Privacy Act imposes data retention limits on facial recognition deployments in municipal networks. Silicon Valley technology campuses and Port of Long Beach critical infrastructure drive demand for NDAA-compliant edge-computing camera systems with on-board AI inference.
Texas
Houston energy sector facilities and Dallas-Fort Worth logistics hubs deploy perimeter security networks with multi-sensor fusion capabilities. The Texas Capture or Use of Biometric Identifier Act mandates consent protocols for facial recognition systems in commercial and government installations. Austin's municipal police department expands networked camera coverage for public safety monitoring, while rural agricultural operations benefit from USDA ReConnect broadband extending IP camera viability.
New York
The New York metropolitan corridor combines financial district security requirements with metropolitan transportation authority surveillance modernization. State-level procurement guidelines restrict foreign-manufactured components in critical infrastructure, aligning with federal NDAA Section 889 mandates. Buffalo and Rochester healthcare systems deploy privacy-preserving depth cameras for patient safety monitoring in acute care facilities and senior living operations.
Illinois
Chicago's municipal camera network represents one of the largest metropolitan surveillance deployments subject to the Biometric Information Privacy Act's strict consent and retention requirements. O'Hare International Airport and regional logistics centers drive federal-compliant procurement for transportation security applications. Peoria and Springfield healthcare operators navigate BIPA compliance costs while expanding automated fall detection systems in senior care facilities.
Florida
Miami-Dade seaport security and Orlando tourism infrastructure anchor demand for thermal-visible fusion systems in perimeter protection applications. State procurement offices prioritize cyber-hardened camera networks for hurricane response coordination across emergency management agencies. Tampa Bay metropolitan planning integrates video analytics with intelligent transportation systems, while Space Coast federal facilities drive NDAA-mandated replacement cycles for Chinese-origin equipment.
US Video Surveillance Market Competitive Landscape
Global majors compete with regional champions across technology integration and compliance certification capabilities. The vendor base organizes around three tiers: diversified conglomerates with aerospace and building automation heritage, pure-play security specialists with open-architecture IP platforms, and Asian-origin manufacturers facing federal procurement restrictions. Strategic differentiation concentrates on domestic supply chain certification, edge AI chipset integration, and managed service agreement structures. Competitive moves emphasize vertical integration into sensor manufacturing and strategic partnerships with cloud infrastructure operators.
Among diversified technology conglomerates, Honeywell International Inc. and Motorola Solutions occupy positions anchoring integrated command-and-control platforms for critical infrastructure clients. Bosch Security Systems represents the precision-engineered manufacturing archetype with North American fabrication facilities. Axis Communications exemplifies open-architecture specialization sustaining interoperability across heterogeneous network environments. These three companies illustrate the competitive tension between integrated platform breadth and modular component flexibility that defines procurement decisions in federal and enterprise segments.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Bosch Security Systems |
| Axis Communications |
| Hikvision |
| Dahua Technology |
| Motorola Solutions |
| Hanwha Vision |
| ADT |
| Teledyne FLIR |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up security specialists have consolidated regional integrators across California, Texas, and New York metropolitan corridors, tightening pricing discipline through captive installation networks and NDAA-compliant component sourcing mandates that compress supplier pools and elevate certification premiums.
Pricing Analysis
CMOS sensor cost pass-through from concentrated Asian fabrication capacity anchors hardware pricing volatility, with AI-enabled edge-computing units commanding certification-grade premiums over standard IP cameras. Three-tier pricing structure across NDAA-compliant, state-privacy-certified, and baseline commercial levels separates federal procurement from municipal and retail segments. Pricing pressure stems from cloud-based subscription models displacing capital-intensive NVR ownership, compressing upfront hardware margins. Mid-market retail adopters exhibit highest price sensitivity, while critical infrastructure operators absorb premium tiers for domestic supply chain verification.
Supply Chain Analysis
Reverse-logistics flows for NDAA-mandated equipment replacement cycle through certified refurbishment centers in Texas and Arizona, extending asset life for federal agencies under compressed statutory deadlines. Advanced image sensor fabrication concentrates in Taiwan, South Korea, and Japan, while edge AI chipsets source from US and Israeli design houses. Supply chain risk centers on single-source vulnerability for low-light CMOS sensors under export control scrutiny. Distribution runs through authorized security integrators with federal contracting credentials, bypassing open-channel electronics wholesalers for compliance-sensitive installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in US video surveillance rests on edge AI chipset cost curves and the premium-tier shift toward managed service agreements with outcome-based performance clauses.
For Market Incumbents: Extend NDAA-compliant product lines into healthcare fall detection and rural broadband-enabled agricultural monitoring before emerging cloud-native analytics vendors capture subscription relationships. Deepen backward integration into domestic sensor packaging to defend against allocation delays from Asian fabrication concentration. Prioritize LEVA-certified technician training partnerships to lock municipal procurement decisions. For New Entrants and Emerging Players: Direct-to-government digital procurement portals offer lowest-friction entry for specialized analytics software vendors lacking integrator relationships. Target mid-sized cities in Illinois and Florida lacking internal cybersecurity expertise for camera network hardening. Lead with privacy-preserving depth camera solutions for senior living operators navigating BIPA and CCPA retention limits. For Investors and Strategic Acquirers: Valuations sit cheapest among regional systems integrators with federal contracting vehicles but limited analytics IP, presenting rollup candidates for platform consolidation. Long-term viability favors vendors with captive edge AI silicon and managed service revenue exceeding hardware dependency. Monitor FCC spectrum allocation decisions for 6 GHz unlicensed expansion as inflection signal for wireless camera deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| NDAA Compliance Certification | Federal procurement eligibility under Section 889 mandates domestic supply chain verification for military and port installations. |
| Edge AI Chipset Integration | On-camera inference processors reduce bandwidth costs for real-time facial recognition in Texas and California deployments. |
| Managed Service Agreement Expansion | Subscription models displace capital purchases in mid-sized cities lacking internal IT security expertise. |
| Multi-Sensor Fusion Platform Development | Thermal-visible-radar unification cuts false alarms at Houston energy facilities and New York transportation hubs. |
| Rural Broadband Partnership | USDA ReConnect program alignment extends IP camera viability to agricultural operations and tribal lands. |
Research Methodology
Direct dialogue with federal procurement officers, municipal police technology directors, healthcare facility security managers, and security systems integrators combined with secondary validation against NDAA implementation guidance, FCC spectrum allocation records, state biometric privacy statute filings, and federal contracting databases. Bottom-up equipment shipment analysis triangulated with top-down infrastructure investment tracking across smart city programs.
Installed base and revenue estimates project across the analysis window through segmented modeling of camera, recorder, and analytics software verticals by deployment architecture and end-use compliance tier. CAGRs derive from replacement cycle acceleration under federal mandates, edge AI adoption curves, and cloud subscription conversion rates in mid-market segments.
The model assumes a particular technology adoption path; alternative pathways for analog-to-IP transition timing would alter the outlook for coaxial infrastructure upgrade demand. Practitioners should monitor FCC 6 GHz device certification timelines and state-level biometric privacy enforcement actions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
United Kingdom Surveillance Camera Market
Video Surveillance Systems
Privacy Filters Market
Video Surveillance Systems
Japan Surveillance IP Cameras Market
Video Surveillance Systems
Latin America Video Surveillance Storage Market
Video Surveillance Systems
Smart Doorbell Camera Market
Video Surveillance Systems
Asia-Pacific Surveillance Storage Market
Video Surveillance Systems
Canada Surveillance IP Camera Market
Video Surveillance Systems
Germany Video Surveillance Market
Video Surveillance Systems
North America Crawler Camera System Market
Video Surveillance Systems
Integrated Video Surveillance Systems Market
Video Surveillance Systems
Hosted Video Surveillance Market
Video Surveillance Systems
Brazil Video Surveillance Market
Video Surveillance Systems
North America Surveillance Analog Camera Market
Video Surveillance Systems
Central Monitoring Station Market
Video Surveillance Systems
Europe Video Surveillance Systems Market
Video Surveillance Systems
India Video Surveillance Market