
 X-Ray Security Screening System Market | 2026-2036
X-Ray Security Screening System Market Size, Share, and Industry Trends Forecast 2026-2036
X-Ray Security Screening System Market Analysis
The gap between premium computed tomography platforms and commodity 2D conveyor units is restructuring procurement patterns across aviation and critical infrastructure sectors. Smiths Detection Inc. leverages its long-standing channel relationships with European airport authorities to sustain premium positioning. Nuctech Company Limited anchors volume manufacturing for customs and border applications across emerging economies. L3Harris Technologies, Inc. competes on integrated threat-detection software that extends hardware functionality beyond raw imaging.
An X-Ray Security Screening System employs ionizing radiation within controlled energy bands, typically 140–180 kVp for baggage and 160–200 kVp for cargo, to generate attenuation maps that algorithms classify into material categories for threat identification. Fixed systems dominate installed base across major aviation hubs, while portable and mobile units address temporary event security and remote customs checkpoints. Computed tomography technology captures the fastest expansion as regulators mandate three-dimensional threat resolution, though 2D imaging retains significant share in cost-sensitive stadium and government facility deployments where throughput requirements remain moderate.
The U.S. Transportation Security Administration and European Union Aviation Safety Agency enforce stringent detection standards that shape product certification timelines and R&D allocation across manufacturers. The U.S. FDA regulates occupational radiation exposure limits for operators, while EU CE marking under the Machinery Directive governs electromagnetic compatibility and safety interlocks. Stakeholders must monitor evolving algorithm classification requirements from aviation regulators, as software-defined detection thresholds increasingly determine hardware refresh cycles and competitive differentiation.
Market Dynamics
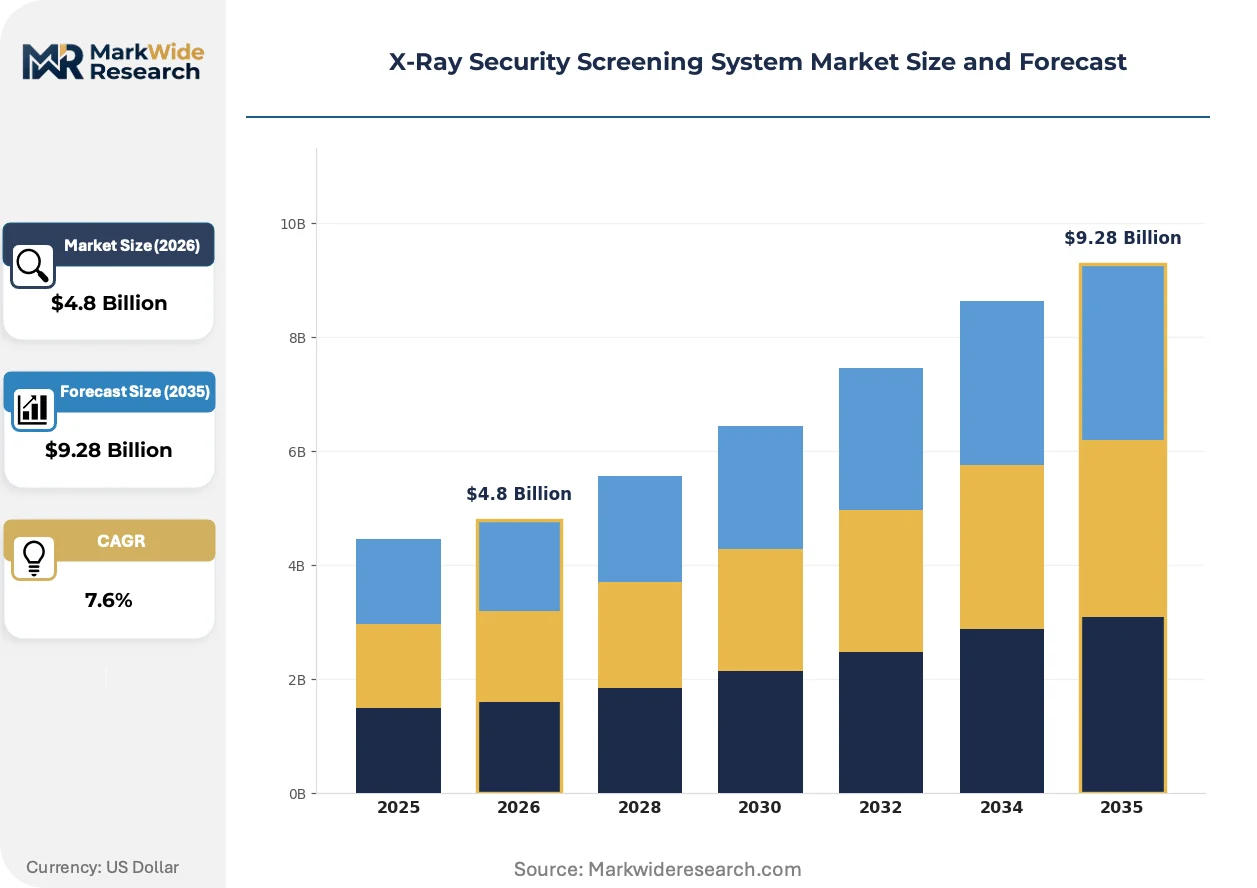
The transition from 2D to 3D imaging architectures is compressing equipment refresh cycles across aviation security infrastructure. Regulatory mandates for computed tomography resolution are forcing simultaneous upgrades of hardware platforms and detection algorithms.
Growth Catalysts
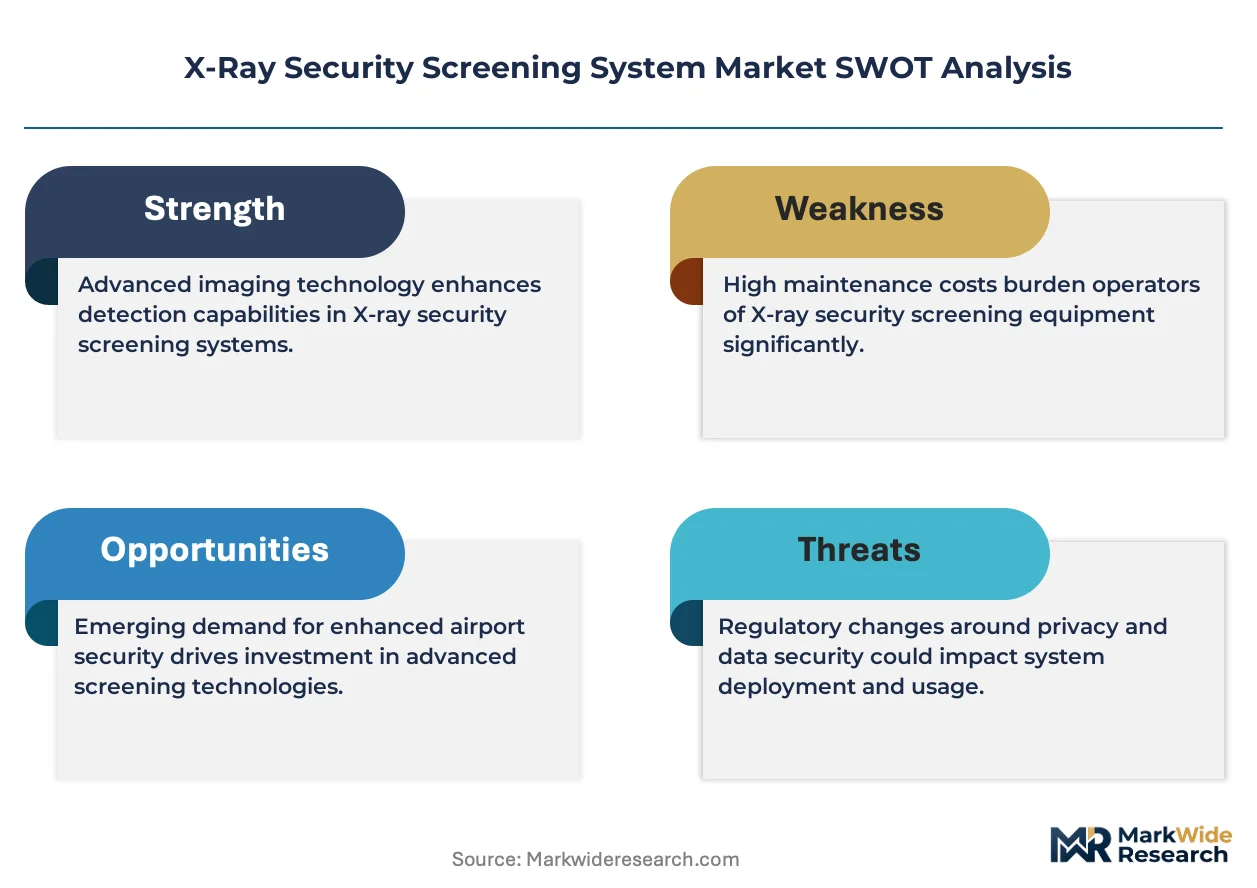
- EU Aviation Safety Agency computed tomography mandates:European airports must deploy three-dimensional threat resolution systems by statutory deadlines, accelerating replacement of legacy 2D conveyor units.
- Metro rail expansion in India:Urban transit authorities in Delhi, Mumbai, and Bangalore are installing high-throughput baggage screening at new underground stations.
- Dual-view scanner technology:Aviation regulators in Southeast Asia are adopting dual-view specifications for international terminal upgrades, creating specification pull-through across procurement.
Market Restraints
- Detector crystal supply concentration:Cadmium zinc telluride substrate production concentrates among limited specialty chemical suppliers, creating input cost volatility for CT subsystem manufacturers.
- Radiation shielding material costs:Lead and tungsten alloy prices fluctuate with mining output constraints, pressuring fixed-system bill-of-materials.
- Algorithm certification timelines:FDA premarket notification requirements for software-defined detection thresholds extend product launch schedules by 18-24 months.
Strategic Opportunities
- Remote customs checkpoints:Portable X-ray units address temporary screening needs at border crossings in sub-Saharan Africa and Central Asia where permanent infrastructure remains underdeveloped.
- Stadium and event security:Sports venues and convention centers represent an emerging application segment requiring rapid-deployment mobile screening for temporary crowds.
- India PLI scheme for electronics manufacturing:Production-linked incentives for domestic component sourcing are attracting subsystem assembly investment for regional supply.
Industry Challenges
- Machine learning engineer scarcity:Threat classification algorithm development requires specialized computer vision expertise that outpaces available talent pools.
- Legacy system integration complexity:New CT platforms must interface with existing baggage handling infrastructure and security operations center software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | X-Ray Security Screening System Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Systems, Portable Systems, Mobile Systems, Conveyor Systems Application: Aerospace, Transportation, Military, Critical Infrastructure End User: Airports, Customs, Stadiums, Government Facilities Technology: Computed Tomography, 2D Imaging, 3D Imaging, Advanced Detectors |
| Companies Covered | Leidos Holdings, Inc., L3Harris Technologies, Inc., Smiths Detection Inc., Rapiscan Systems, Astrophysics, Inc., OSI Systems, Inc., Analogic Corporation, Thales, Nuctech Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
X-Ray Security Screening System Market Emerging Trajectories
Software-defined detection is overtaking hardware-centric threat identification across aviation and critical infrastructure screening. Algorithm performance now determines competitive positioning more than raw imaging resolution.
Computed tomography reconstruction is unifying baggage and cargo screening architectures into common platform families. Airport authorities in Germany and the Netherlands are consolidating procurement around dual-use systems that handle cabin baggage and hold luggage through configurable tunnel dimensions. This convergence is compressing vendor R&D budgets by eliminating parallel development tracks for separate product lines.
EU AI Act algorithmic transparency requirements are reshaping detection software development cycles. Manufacturers must document training data provenance and classification decision pathways for aviation regulator audit. Fixed-system deployments at major European hubs face the steepest compliance burden, with some operators delaying CT upgrades until certification pathways clarify.
Service contract unbundling is fragmenting buyer-supplier relationships in the airport segment. Munich and Frankfurt airports now separately procure hardware, installation, and algorithm update services rather than accepting bundled ten-year agreements. This disaggregation is most visible in German-speaking Europe, where public procurement rules favor competitive tendering of maintenance and software subscriptions.
X-Ray Security Screening System Market Segmentation
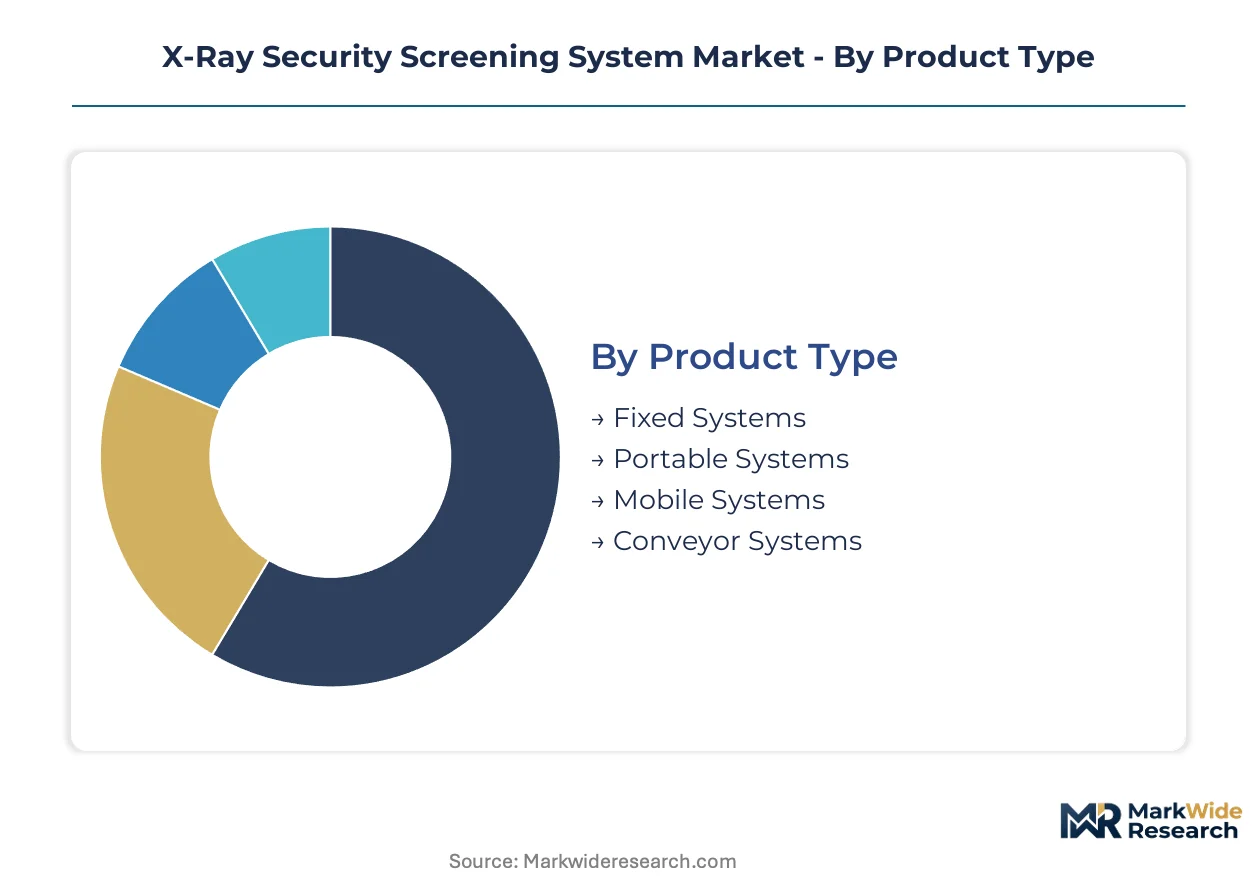
Procurement patterns across aviation and critical infrastructure diverge sharply by deployment permanence, throughput requirements, and regulatory compliance tier. Buyers optimize total cost of ownership across hardware platforms, software integration, and service unbundling.
Product Type:
Capital intensity and installation permanence drive buyer segmentation between fixed infrastructure and deployable assets.
- Fixed Systems:Permanent installations integrate with baggage handling infrastructure at major aviation hubs. Demand concentrates in Germany and the Netherlands where airports consolidate procurement around dual-use cabin and hold luggage platforms.
- Portable Systems:Battery-powered or generator-dependent units deploy to temporary checkpoints without permanent power infrastructure. Customs authorities in sub-Saharan Africa and Central Asia acquire these for remote border crossings where fixed construction remains uneconomical.
- Mobile Systems:Vehicle-mounted screening platforms serve event security and emergency response scenarios.
- Conveyor Systems:Belt-fed architectures dominate moderate-throughput government facilities and stadium checkpoints.
Volume sits with Fixed Systems; growth tilts toward Portable Systems.
Application:
Threat sophistication and passenger throughput determine technology specification and procurement budget allocation.
- Aerospace:Aviation terminals mandate computed tomography resolution for three-dimensional threat detection. EU Aviation Safety Agency deadlines compress refresh cycles for legacy 2D units at European hubs.
- Transportation:Metro rail networks in Delhi, Mumbai, and Bangalore install high-throughput baggage screening at underground stations. Indian urban transit authorities represent the steepest volume expansion.
- Military:Forward operating bases and checkpoint security require hardened, deployable screening platforms.
- Critical Infrastructure:Power plants, data centers, and government compounds apply screening to personnel and supply chain entry points.
Aerospace commands premium pricing; Transportation exhibits the steepest expansion trajectory.
End User:
Procurement authority structure—federal aviation, customs administration, municipal government, or private venue operator—shapes tender specifications and contract duration.
- Airports:Terminal operators face dual mandates from aviation regulators and security operations centers. Munich and Frankfurt airports now unbundle hardware, installation, and algorithm update services under public procurement rules.
- Customs:Border agencies balance permanent infrastructure at major crossings with portable deployments at remote checkpoints.
- Stadiums:Sports venues and convention centers deploy rapid-deployment mobile screening for temporary crowds.
- Government Facilities:Administrative buildings and courthouses apply moderate-throughput 2D imaging where threat profiles and passenger volumes remain constrained.
Airports anchor installed value; Stadiums are climbing the fastest as event security budgets expand.
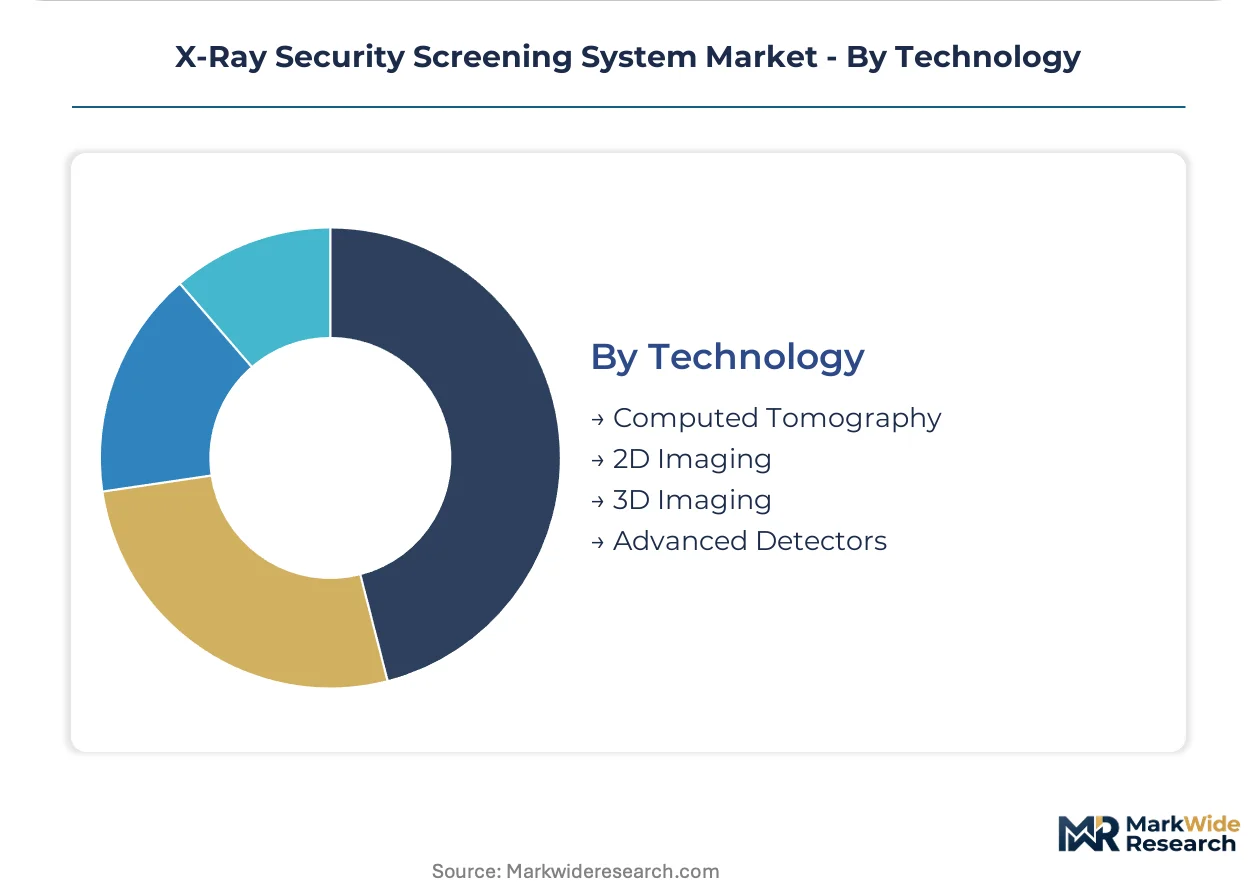
Technology:
Software-defined detection thresholds now determine competitive differentiation more than raw imaging resolution.
- Computed Tomography:Three-dimensional reconstruction algorithms classify material density and geometry for automated threat identification. EU AI Act transparency requirements extend certification timelines for European deployments.
- 2D Imaging:Conventional attenuation mapping retains significant share in cost-sensitive stadium and government facility deployments where throughput requirements remain moderate.
- 3D Imaging:Stereoscopic dual-view architectures satisfy emerging aviation mandates in Southeast Asia without full CT computational overhead.
- Advanced Detectors:Cadmium zinc telluride substrates and direct-conversion sensors improve energy resolution for material discrimination.
2D Imaging holds volume share; Computed Tomography gains share fastest on regulatory mandate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt and Munich airports anchor European aviation security procurement, while Delhi Metro and Bangalore's suburban rail networks drive Asia's fastest equipment deployment cycles.
United States
The Transportation Security Administration mandates computed tomography resolution for checked baggage screening at Category X airports. FDA premarket notification requirements for software-defined detection thresholds extend product certification timelines. Los Angeles International and Atlanta Hartsfield-Jackson anchor the largest installed base of legacy 2D conveyor replacements.
Germany
Munich and Frankfurt airports unbundle hardware procurement from algorithm update services under public tendering rules. EU AI Act transparency requirements for training data documentation reshape detection software development cycles. The Rhine-Main cluster concentrates CT subsystem engineering talent for aviation applications.
India
Delhi Metro Rail Corporation and Bangalore Metro install high-throughput baggage screening at underground stations across Phase III expansions. The PLI scheme for electronics manufacturing attracts subsystem assembly investment for regional supply chains. Mumbai's suburban rail network plans screening infrastructure at 200+ stations under the Mumbai Urban Transport Project.
Netherlands
Schiphol Airport consolidates procurement around dual-use cabin and hold luggage platforms with configurable tunnel dimensions. CE marking under the Machinery Directive governs electromagnetic compatibility for integrated baggage handling systems. The Amsterdam-Rotterdam corridor hosts European headquarters for several detection technology vendors.
United Arab Emirates
Dubai International and Abu Dhabi Zayed International deploy premium CT platforms for high-volume transit passenger screening. The country's civil aviation regulator aligns with EU Aviation Safety Agency standards for three-dimensional threat resolution. Jebel Ali port customs operates mobile screening units for containerized cargo inspection.
X-Ray Security Screening System Market Vendor Landscape
Premium-margin players sit above commodity-margin players across algorithm sophistication and certification depth, with aviation-grade CT systems commanding three-tier pricing separation from stadium and government facility deployments. The vendor base stratifies between integrated threat-detection platforms, volume manufacturing specialists, and regional subsystem suppliers. Three archetypes dominate: software-centric integrators extending hardware functionality through AI classification, scale manufacturers optimizing for customs and border throughput, and component specialists supplying detector crystals and radiation shielding assemblies. Competitive moves concentrate on algorithm licensing partnerships and backward integration into detector substrate production.
Among US-based defense-technology conglomerates, Leidos Holdings, Inc. and L3Harris Technologies, Inc. occupy positions within the software-centric integrator archetype, leveraging long-standing channel relationships with federal aviation authorities. Smiths Detection Inc. represents the European premium-tier specialist, while Nuctech Company Limited anchors volume manufacturing for emerging economy customs applications.
| Leading Market Players |
|---|
| Leidos Holdings, Inc. |
| L3Harris Technologies, Inc. |
| Smiths Detection Inc. |
| Rapiscan Systems |
| Astrophysics, Inc. |
| OSI Systems, Inc. |
| Analogic Corporation |
| Thales |
| Nuctech Company Limited |
| Others |
Supply Flow & Price Mechanics
CT algorithm engineering talent clustering in the Rhine-Main corridor and Bangalore feeds labor-cost differentials that widen pricing-tier spreads between aviation-grade and facility-grade screening platforms. European airports absorbing EU AI Act compliance costs face steeper procurement premiums than Indian metro authorities sourcing standardized 2D units.
Pricing Analysis
Throughput-guarantee contracts anchor pricing for computed tomography platforms, with aviation authorities paying premium rates for detection uptime commitments above 99.5%. Three-tier pricing structure across premium, standard, and economy levels separates EU-mandated CT systems from dual-view configurations and commodity 2D conveyor units. Cost compression in the standard tier is intensifying because customs agencies in emerging economies are consolidating volume purchases. Stadium operators and municipal government facilities exhibit the highest price sensitivity, while Category X airports under TSA jurisdiction show minimal elasticity.
Supply Chain Analysis
Freight costs for radiation shielding assemblies and detector subsystems constrain procurement flexibility for remote customs checkpoints in sub-Saharan Africa and Central Asia. Cadmium zinc telluride substrate production concentrates in Japan and the United States, while lead and tungsten alloy sourcing draws from Chinese and Russian mining operations. Single-source vulnerability in specialty crystal growth furnaces threatens CT subsystem manufacturers. Distribution runs through authorized regional integrators who bundle installation with algorithm calibration services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Detector crystal supply scarcity props pricing for CT platforms, with cadmium zinc telluride furnace capacity constraints limiting output expansion across subsystem vendors.
For Market Incumbents: Anchor market position through backward integration into detector substrate production and captive algorithm certification pipelines. Smiths Detection and L3Harris face emerging competition from Chinese volume manufacturers penetrating EU aviation procurement through price-competitive dual-view offerings. Certification investment in EU AI Act documentation capabilities represents the critical defensive lever. For New Entrants and Emerging Players: Begin with portable system deployments at remote customs checkpoints in sub-Saharan Africa and Central Asia where fixed infrastructure economics fail. Stadium and event security exhibits the most penetrable demand profile, with temporary crowd screening creating recurring replacement cycles absent in permanent aviation installations. Direct sales to municipal venue operators bypass entrenched channel relationships dominating airport procurement. For Investors and Strategic Acquirers: Re-rating potential sits with algorithm-centric software vendors given EU AI Act transparency requirements extending certification timelines and deepening customer switching costs. Long-term viability favors suppliers with in-house CT reconstruction capabilities and established aviation regulator relationships. Monitor cadmium zinc telluride furnace capacity announcements as the inflection signal for CT subsystem pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Detector Substrates | Captive cadmium zinc telluride supply secures margin protection against specialty chemical volatility. |
| Algorithm Certification Pipeline Investment | EU AI Act documentation capabilities accelerate aviation regulator approval timelines. |
| Portable System Platform Development | Battery-powered architectures address customs demand at remote border crossings lacking grid infrastructure. |
| Dual-Use Platform Consolidation | Configurable tunnel dimensions reduce R&D duplication across cabin and hold luggage product lines. |
| Service Contract Unbundling Response | Separate algorithm subscription offerings align with German public procurement tendering requirements. |
Methodological Framework
Aviation regulatory filings, customs procurement databases, and SEC 10-K disclosures formed the secondary backbone, supplemented by primary interviews with airport security operations directors, CT subsystem engineering leads, customs procurement officers, and algorithm development specialists. Bottom-up equipment deployment tallies triangulated against top-down market sizing from trade flow analysis and component shipment tracking.
Historical trendline analysis across installed base refresh cycles and regulatory mandate timelines informed projection modeling. Segmentation dimensions included product permanence, application threat sophistication, end-user procurement authority, and technology compliance tier. CAGRs derived from curve-fitting observed replacement velocities against statutory deadline clustering. Forecast inputs incorporated detector crystal supply constraints and aviation regulator certification queue lengths.
Underlying measurement precision varies by segment; aerospace and transportation deployments carry tighter precision than military and stadium applications due to public procurement transparency. Forecasts reflect assumptions about regulatory deadline adherence and supply chain disruption frequency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
North America Security Testing Market
Security and Surveillance
Europe Security Services Market
Security and Surveillance
Situational Awareness System Market
Security and Surveillance
North America Security Services Market
Security and Surveillance
Europe Security Assurance Market
Security and Surveillance
Global Firearm Sight Market
Security and Surveillance
Global Threat Intelligence Management Market
Security and Surveillance
India Electronic Security Market
Security and Surveillance
Resale Authentication Services Market
Security and Surveillance
Global Law Enforcement Software Market
Security and Surveillance
Global Physical Security Software Market
Security and Surveillance
Consumer Security Market
Security and Surveillance
Global Acoustic Hailing Devices Market
Security and Surveillance
Private Security Market
Security and Surveillance
Global Security Policy Management Market
Security and Surveillance
Security Operations Center Market