
 Bespoke Safe Rooms and Panic Rooms Market | 2026-2036
Bespoke Safe Rooms and Panic Rooms Market Size, Share, and Industry Trends Forecast 2026-2036
Bespoke Safe Rooms and Panic Rooms Market Insights
Fiberglass-reinforced polymer is decoupling bespoke safe room construction from legacy steel-and-concrete economics, enabling faster retrofit timelines and reduced floor-loading requirements. US Safe Room leverages vertically integrated ballistic testing to sustain premium positioning across residential and government channels. The Panic Room Company anchors its competitiveness in custom architectural integration, while Atlas Safe Rooms dominates prefabricated modular systems through controlled distribution networks.
Bespoke safe rooms and panic rooms are hardened interior enclosures engineered to resist forced entry, ballistic impact, and environmental threats, typically incorporating steel-composite wall assemblies rated to UL 752 or NIJ standards with independent ventilation and communication systems. Their primary purpose is to provide occupant protection during targeted intrusion, severe weather, or civil disturbance events. Custom Designs command the deepest margin pools where architectural concealment and finish-grade interior specifications justify substantial premiums, while Modular Systems represent the fastest-growing installation category as retrofit demand accelerates in existing luxury residential stock. Bullet-Resistant Materials segment growth outpaces conventional steel as multi-threat rated composites achieve broader commercial acceptance.
FEMA guidelines and ICC 500 storm shelter standards shape residential safe room specifications across the United States, while European CE marking requirements under the Construction Products Regulation govern ballistic resistance claims in EU member states. The National Institute of Justice maintains the dominant testing protocol for forced-entry and ballistic performance, effectively controlling market access for imported enclosure systems. Stakeholders must monitor evolving municipal amendments to residential building codes that mandate or incentivize hardened shelter provisions, as these local ordinances increasingly determine addressable market breadth.
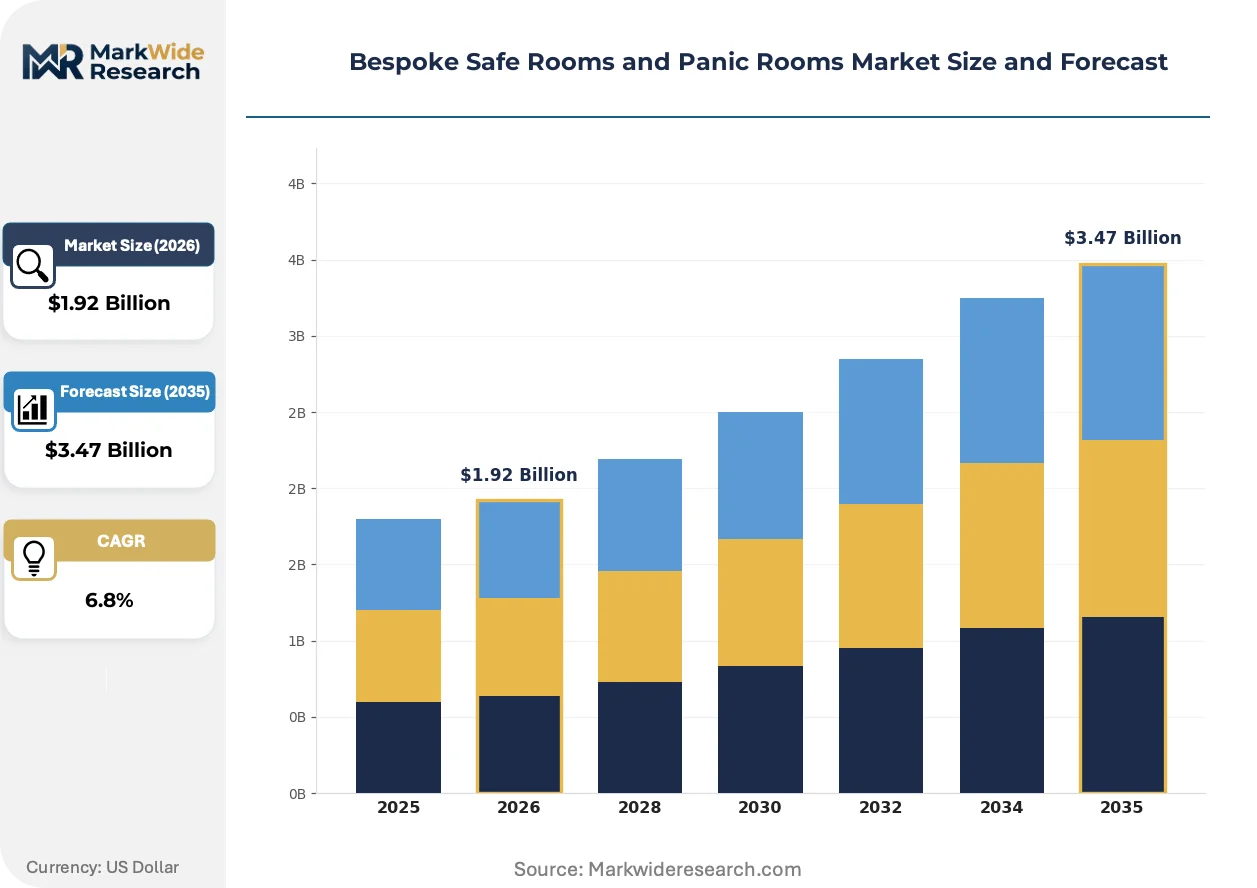
Market Dynamics
Ballistic-rated composite materials are rewriting the economics of safe room construction by slashing structural load requirements and enabling retrofit installations in existing luxury residential stock without foundation reinforcement.
Growth Catalysts
- FEMA P-361 Guidelines:US residential building codes increasingly mandate hardened shelter provisions in tornado-prone counties, expanding addressable demand for certified safe room installations.
- Carbon-fiber reinforced polymers:These advanced composites cut panel weight by sixty percent versus traditional steel-concrete assemblies, reducing crane requirements and installation timelines.
- Ultra-high-net-worth residential construction:Estate developers in coastal Florida and Texas are specifying concealed panic rooms as standard amenities in new luxury builds.
Market Restraints
- Aramid fiber supply concentration:Ballistic fabric production clusters in a handful of specialized textile facilities, creating input vulnerability for composite panel manufacturers.
- ICC 500 certification timelines:Third-party storm shelter validation requires six-to-nine month testing cycles, constraining rapid scaling for emerging suppliers.
- Reinforced concrete substitutes:Legacy contractors continue pitching poured-concrete vaults at lower upfront cost, delaying composite adoption in budget-sensitive segments.
Strategic Opportunities
- Smart home integration:Convergence of biometric access control with whole-home automation systems creates premium positioning for concealed entry mechanisms.
- Texas Hill Country estate belt:Underpenetrated demand exists among ranch property owners seeking storm and security dual-function shelters outside major metropolitan code jurisdictions.
- CE marking pathway expansion:The EU Construction Products Regulation's evolving ballistic resistance categories open certification routes for US and Asian manufacturers targeting European luxury residential.
Industry Challenges
- Ballistic welding certification scarcity:Qualified technicians capable of UL 752-rated seam welding command premium wages and limited geographic availability.
- Multi-threat testing complexity:Simultaneous NIJ forced-entry and FEMA wind-load certification requires redundant engineering cycles that compress margins on fixed-price contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bespoke Safe Rooms and Panic Rooms Market |
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $3.47 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Custom Designs, Modular Systems, Integrated Solutions, Expandable Rooms Material: Steel, Concrete, Fiberglass, Bullet-Resistant Materials End User: Residential Customers, Corporates, Government Facilities, Luxury Estates Installation Type: Site-Built, Prefabricated, Retrofit, Modular Installations |
| Companies Covered | US Safe Room, The Panic Room Company, Ultimate Bunker, Atlas Safe Rooms, Panic Room Builders, SAFEROOM, FORTRESS, Fortified Estate, Stronghold Safe Rooms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bespoke Safe Rooms and Panic Rooms Market Trends and Innovations
Active concealment engineering and modular assembly systems are converging to transform how protective enclosures integrate with residential architecture, compressing installation windows while elevating finish-grade specifications.
Fiberglass-reinforced polymer sandwich panels are rewriting installation economics for retrofit applications. These composite assemblies achieve UL 752 Level 8 ballistic ratings at one-third the weight of conventional steel plate, enabling ceiling-mounted safe rooms in multi-story residences without structural reinforcement. High-end residential contractors in California and Florida are specifying these systems for projects where foundation access is restricted, compressing what were six-week concrete pours into seventy-two-hour modular installations.
The ICC 500 storm shelter standard's 2024 revision tightens debris impact requirements for above-ground residential installations. This regulatory compression forces manufacturers to redesign ventilation intake geometries and door seal mechanisms, particularly affecting suppliers serving Oklahoma and Kansas where municipal amendments adopt the standard automatically. Prefabricated modular providers are responding with factory-tested integrated systems that bundle certification documentation with physical delivery.
Concealment-driven procurement now dominates ultra-luxury residential specifications, with buyers prioritizing architectural integration over raw ballistic ratings. Estate architects in the Hamptons and Aspen are specifying book-case entry systems and subfloor lift mechanisms that render safe rooms invisible to casual inspection. This behavioral shift elevates finish carpentry and millwork capabilities to coequal status with ballistic engineering in supplier selection criteria, rewarding firms with in-house custom fabrication capacity.
Bespoke Safe Rooms and Panic Rooms Market Segmentation
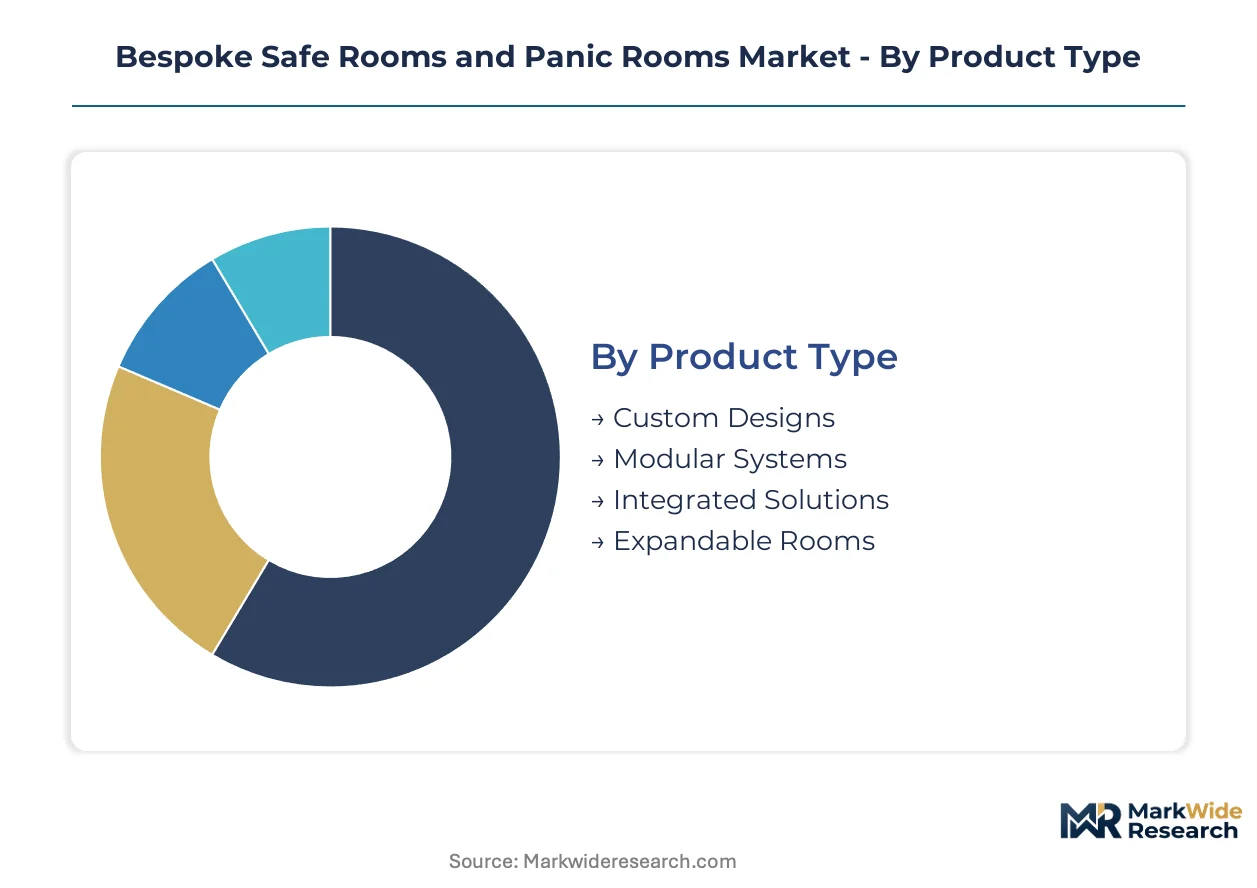
Segmentation in the bespoke safe rooms and panic rooms market reveals distinct engineering and procurement logics across product architecture, material science, client risk profiles, and construction methodology. Each axis carries different margin structures, certification requirements, and competitive dynamics that shape supplier positioning and addressable market breadth.
Product Type:
Product architecture determines engineering cycles, certification pathways, and revenue recognition timing across the installation spectrum.
- Custom Designs:Architectural concealment and finish-grade millwork specifications command substantial premiums. Estate developers in coastal Florida specify these for new luxury builds where seamless integration with interior design is paramount.
- Modular Systems:Factory-engineered assemblies compress installation windows and enable retrofit applications in existing residential stock without structural reinforcement. Demand concentrates in tornado-prone counties where FEMA P-361 compliance accelerates procurement decisions.
- Integrated Solutions:Bundled safe room and whole-home security systems with biometric access control and automated concealment mechanisms. High-net-worth residential clients prioritize these for unified threat response protocols.
- Expandable Rooms:Scalable footprint designs accommodating variable occupancy loads and multi-threat scenarios. Government facilities specify these for flexible operational requirements.
Mature deployment sits with Custom Designs. Newer deployment is concentrated in Modular Systems.
Material:
Material selection governs structural load calculations, ballistic rating achievements, and installation economics across residential and institutional applications.
- Bullet-Resistant Materials:Multi-threat rated composites including aramid fiber and carbon-fiber reinforced polymers achieve UL 752 and NIJ standards at reduced weight. These materials are displacing legacy steel-and-concrete assemblies in retrofit-focused segments.
- Fiberglass:Fiberglass-reinforced polymer sandwich panels enable ceiling-mounted installations in multi-story residences without foundation reinforcement. California contractors specify these where structural access is restricted.
- Steel:Conventional steel plate and welded frame assemblies remain prevalent in government and institutional specifications requiring documented UL 752 seam welding certification.
- Concrete:Legacy reinforced concrete vault construction persists in budget-sensitive segments and below-ground applications where structural mass is advantageous.
Established specifications favor Steel. Material innovation is accelerating fastest in Bullet-Resistant Materials.
End User:
End user categories reflect distinct threat models, procurement authority structures, and compliance frameworks that shape supplier go-to-market approaches.
- Luxury Estates:Ultra-high-net-worth residential properties where concealed panic rooms function as standard amenities. Estate architects in the Hamptons and Aspen prioritize architectural integration over raw ballistic ratings.
- Residential Customers:Individual homeowners in tornado-prone regions seeking FEMA-compliant storm shelters. Municipal code amendments in Oklahoma and Kansas drive adoption through mandated or incentivized provisions.
- Government Facilities:Federal, state, and local installations requiring NIJ forced-entry certification and redundant communication systems. Procurement runs through specified contractor networks with established security clearances.
- Corporates:Executive protection rooms and secure communication facilities in headquarters buildings. Risk management departments drive specifications with emphasis on business continuity planning.
Volume concentration rests with Residential Customers. Premium margin pools are deepest in Luxury Estates.
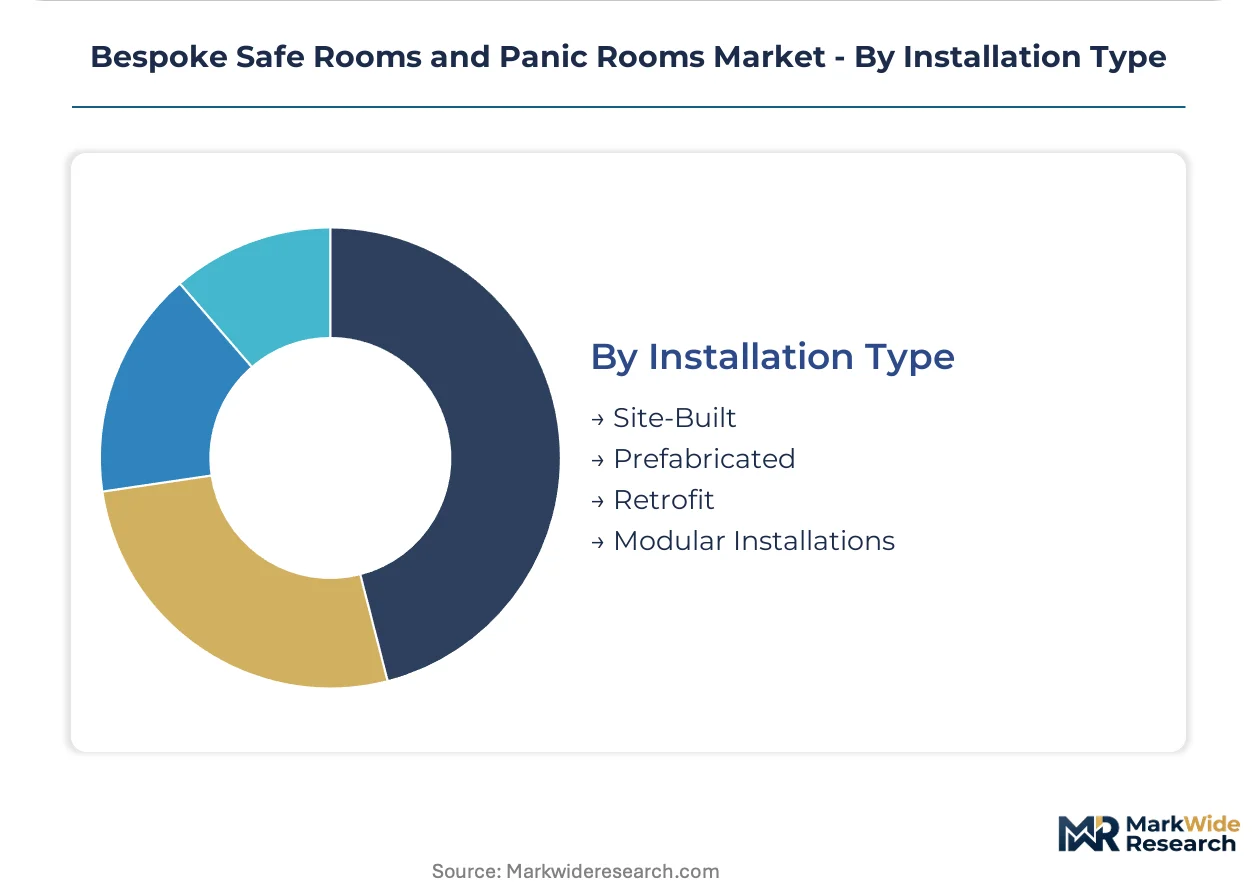
Installation Type:
Installation methodology determines project timelines, labor skill requirements, and regulatory compliance sequencing across new construction and existing building stock.
- Prefabricated:Factory-complete modules delivered with bundled ICC 500 certification documentation. Providers serving Oklahoma and Kansas leverage these to compress six-to-nine month validation cycles.
- Retrofit:Installation within existing structures without foundation modification. Carbon-fiber composite panels enable these projects by cutting structural load requirements sixty percent versus traditional assemblies.
- Site-Built:Custom fabrication and assembly at the installation location. Legacy contractors with ballistic welding certification dominate this segment despite longer project timelines.
- Modular Installations:Hybrid approach combining factory-engineered components with on-site assembly. This method balances quality control with architectural flexibility for concealed entry specifications.
Traditional practice centers on Site-Built. Market expansion is climbing the fastest in Retrofit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity zones in tornado-prone counties concentrate residential safe room demand across the United States, while European luxury residential clusters drive premium panic room specifications. Municipal code amendments and estate development patterns shape regional deployment trajectories.
United States
FEMA P-361 guidelines and ICC 500 storm shelter standards drive certified installations across Oklahoma and Kansas. Municipal amendments in tornado-prone counties mandate or incentivize hardened shelter provisions, expanding addressable demand. Dallas-Fort Worth contractors report accelerating retrofit inquiries from existing luxury residential stock seeking dual-function storm and security shelters.
Germany
CE marking requirements under the EU Construction Products Regulation govern ballistic resistance claims for luxury residential developments. High-net-worth property owners in Berlin and Munich specify concealed panic rooms as standard amenities in new estate construction. Bavarian fabricators specialize in custom architectural integration for finish-grade interior specifications.
United Kingdom
Estate architects in London and the Home Counties prioritize concealment engineering over raw ballistic ratings for ultra-luxury residential clients. The National Institute of Justice testing protocol controls market access for imported enclosure systems. Surrey-based contractors dominate concealed entry mechanism installations for heritage property retrofits.
United Arab Emirates
Executive protection rooms in headquarters buildings and secure residential compounds drive corporate and government facility specifications. MOHAP and local building authorities enforce construction standards for hardened shelters in critical infrastructure. Dubai developers specify integrated biometric access control systems for unified threat response protocols in premium residential towers.
Australia
Severe weather resilience requirements and executive protection demand converge in Sydney and Melbourne luxury residential markets. State-level building code amendments reference storm shelter provisions for coastal properties facing cyclone exposure. Queensland contractors specialize in modular prefabricated systems for remote ranch property installations outside metropolitan code jurisdictions.
Bespoke Safe Rooms and Panic Rooms Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated positioning in government channels and fragmented competition in residential retrofit markets. The vendor base organizes around three strategic archetypes: vertically integrated ballistic testers, custom architectural integrators, and prefabricated modular system providers. Capacity expansion and certification documentation bundling represent dominant competitive moves as suppliers compress ICC 500 validation cycles.
Within the vertically integrated tier, US Safe Room anchors premium positioning through captive ballistic testing capabilities. The Panic Room Company and Atlas Safe Rooms exemplify divergent specialization vectors—architectural concealment versus controlled distribution networks for modular systems. These three fabricators occupy distinct competitive positions without overlapping core competencies, enabling segmented market coexistence rather than direct price competition.
| Leading Market Players |
|---|
| US Safe Room |
| The Panic Room Company |
| Ultimate Bunker |
| Atlas Safe Rooms |
| Panic Room Builders |
| SAFEROOM |
| FORTRESS |
| Fortified Estate |
| Stronghold Safe Rooms |
| Others |
Pricing and Supply Chain Analysis
Captive ballistic testing capabilities anchor premium positioning for incumbent fabricators while compressing margin pools for competitors dependent on third-party UL 752 validation. This integration choice separates price-setters from price-takers across FEMA-compliant residential installations and NIJ-certified government channels.
Pricing Analysis
Volume concentration in modular storm shelters runs opposite to margin depth in custom architectural concealment. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and finish specification, with ICC 500 documentation bundling commanding substantial premiums. Cost compression in economy-tier steel assemblies intensifies as legacy contractors underbid composite alternatives. Residential customers in tornado-prone counties exhibit highest price sensitivity, while estate developers in coastal Florida prioritize concealment engineering over unit economics.
Supply Chain Analysis
Regional distribution centers in Oklahoma and Kansas maintain hub-and-spoke patterns for prefabricated modular delivery to tornado-belt counties. Aramid fiber production clusters in the United States and Germany, with carbon-fiber reinforced polymer feedstock drawing from Japanese and South Korean chemical conglomerates. Single-source vulnerability in ballistic fabric supply creates input risk for composite panel manufacturers. Distribution runs through controlled contractor networks with ICC 500 certification authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ICC 500 storm shelter standards erect a cost-of-compliance barrier that rewards incumbents with captive testing infrastructure while filtering out undercapitalized entrants. This regulatory moat deepens as the 2024 revision tightens debris impact requirements.
For Market Incumbents: To counter aramid fiber supply concentration, secure long-term offtake agreements with Texan and Bavarian textile facilities while expanding in-house carbon-fiber polymer production. Backward integration into ballistic welding certification programs addresses technician scarcity constraining site-built capacity. For New Entrants and Emerging Players: Launch via direct-to-estate-developer channels in Texas Hill Country ranch properties outside municipal code jurisdictions. Concealment-driven procurement in Aspen and Hamptons residential clusters offers penetrable white-space, with biometric access integration as the differentiated go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by whole-home security integrators seeking ballistic enclosure capabilities. Five-to-ten year viability favors fabricators with bundled certification documentation and factory-tested modular platforms. Monitor municipal amendment adoption rates in Oklahoma and Kansas as inflection indicators for addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| ICC 500 Certification Bundling | Factory-tested documentation compresses six-to-nine month validation cycles for Oklahoma and Kansas contractors. |
| Carbon-Fiber Composite Scale-Up | Lightweight panel production reduces crane requirements and expands retrofit addressability in multi-story residences. |
| Biometric Access Integration | Concealed entry mechanisms with whole-home automation command premium positioning in Hamptons estate specifications. |
| Ballistic Welding Certification Programs | In-house technician training addresses UL 752 seam welding scarcity constraining site-built project timelines. |
| European CE Marking Pathway | EU Construction Products Regulation compliance opens Bavarian and Berlin luxury residential channels for US manufacturers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with safe room fabricators, estate architects, municipal code officials, and FEMA regional coordinators combined with ICC 500 certification databases and NIJ testing protocols. Bottom-up installation volume estimates triangulated against top-down construction spending allocations across tornado-prone counties.
Granularity-level modeling tracked product architecture, material science, end-user risk profiles, and installation methodology across the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macro construction indicators. Ballistic composite adoption curves and municipal code amendment timelines served as industry-specific forecast inputs.
Regulatory revision timing, aramid fiber supply disruptions, and municipal enforcement variance are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding ICC 500 adoption velocity and composite material cost curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Physical Security
Hong Kong Data Center Physical Security Market
Physical Security
Security Guard Market
Physical Security
North America Physical Security Market
Physical Security
Malaysia Data Center Physical Security Market
Physical Security
Active Geofencing Market
Physical Security
South America Data Center Physical Security Market
Physical Security
Europe Physical Security Market
Physical Security
Tactical Vests Market
Physical Security
Physical Security Equipment Market
Physical Security
Airport Full Body Scanner Market
Physical Security
Security Market
Physical Security
Persistent Threat Detection System (PTDS) Market
Physical Security
Global Data Center Physical Security Market
Physical Security
Asia-Pacific (APAC) Physical Security Market
Physical Security
Global Wearable Security Device Market
Physical Security
Physical Security Services Market