
 Locomotive Pantographs Market | 2026-2036
Locomotive Pantographs Market Size, Share, and Industry Trends Forecast 2026-2036
Locomotive Pantographs Market Foresight
Freight rail electrification is pivoting toward higher-speed corridors and intermodal terminals. CRRC Corporation Limited leverages integrated manufacturing scale across carbon-strip and frame assemblies. Siemens Mobility sustains technology leadership in sensor-integrated automatic pantograph systems for European corridors. Alstom SA anchors its position through R&D intensity in aerodynamic single-arm designs for TGV and regional networks.
A locomotive pantograph is a current-collecting apparatus mounted on electric train roofs, typically comprising a hinged frame with carbon or copper-alloy contact strips engineered to maintain consistent pressure against overhead catenary wires at speeds exceeding 300 km/h. Its primary purpose is to transfer electrical power from traction infrastructure to onboard propulsion and auxiliary systems without arcing or mechanical wear. Aluminum-frame single-arm configurations dominate new-build installations due to weight reduction and aerodynamic efficiency, while composite-material segments represent the fastest-growing category as operators seek longer service intervals and reduced catenary wire abrasion. Aftermarket suppliers occupy concentrated margin pools in carbon-strip replacement cycles, whereas OEM channel control tightens around integrated modular installation packages for next-generation rolling stock.
EU Green Deal frameworks and F-Gas Regulation standards shape material selection and contact-strip chemistry across European procurement specifications. China's MIIT enforces GB standards for pantograph-catenary dynamic interaction that filter market access for foreign suppliers. India's CEA and RDSO mandate localized testing protocols for 25 kV AC systems on dedicated freight corridors. Stakeholders must monitor evolving interoperability standards between national rail networks and assess captive supply strategies for carbon-composite contact materials.
Market Dynamics
Rail operators are consolidating procurement around integrated pantograph-catenary systems that reduce lifecycle cost through predictive wear monitoring and standardized component architectures.
Growth Catalysts
- EU Green Deal mandates:Carbon-neutral rail infrastructure targets in Germany and France are accelerating fleet electrification programs and pantograph modernization cycles.
- China's MIIT GB standards:Enforcement of dynamic interaction protocols for 25 kV AC systems is filtering market access and elevating technical barriers for domestic suppliers.
- Carbon-composite contact strips:Extended service intervals and reduced catenary wire abrasion are displacing traditional copper-alloy configurations in high-speed corridors.
Market Restraints
- Raw material concentration:High-purity carbon and specialized aluminum alloys face supply bottlenecks concentrated in Chinese and Russian extraction operations.
- F-Gas Regulation compliance:European manufacturing of pneumatic damping systems incurs material substitution costs and redesign cycles.
- Technical ceiling at 400 km/h:Aerodynamic instability and contact force variation limit pantograph performance in next-generation maglev-adjacent corridors.
Strategic Opportunities
- India's dedicated freight corridors:CEA and RDSO localized testing protocols for 25 kV AC systems create captive demand for pantograph suppliers establishing domestic assembly.
- Sensor-integrated automatic systems:Convergence of IoT diagnostics with carbon-strip wear prediction enables outcome-based maintenance contracts.
- Aftermarket unbundling:Direct-to-operator carbon-strip replacement channels are bypassing OEM service networks in Japan and South Korea.
Industry Challenges
- Pantograph-catenary simulation expertise:Finite-element modeling of dynamic interaction at speed requires specialized talent scarce outside CRRC, Siemens, and Alstom engineering centers.
- Interoperability certification timelines:Cross-border acceptance of EN 50206-1 test reports delays product launches by 18-24 months in fragmented European networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Locomotive Pantographs Market |
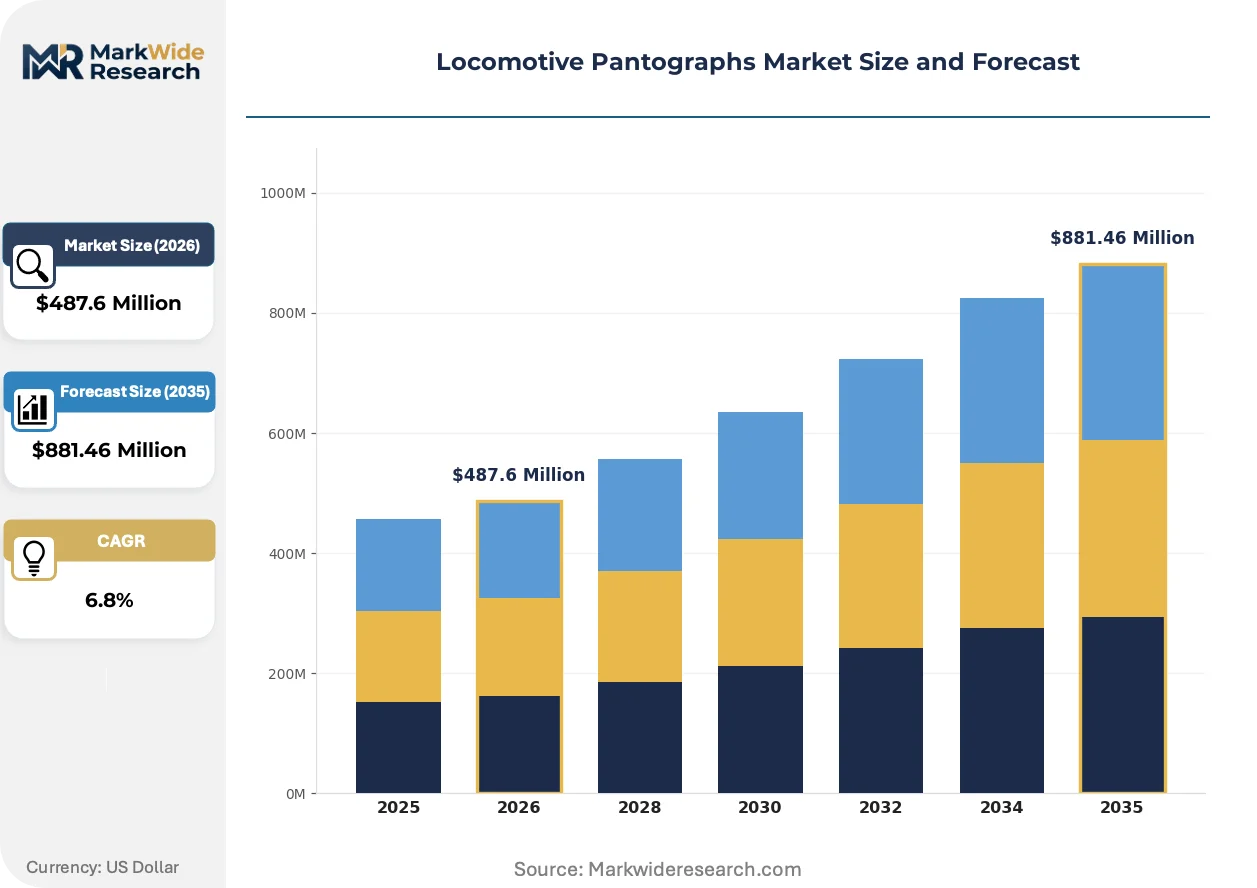
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Arm, Double Arm, Manual, Automatic Material: Aluminum, Steel, Composite, Plastic Installation Type: Fixed, Removable, Integrated, Modular End User: Rail Operators, OEMs, Maintenance Providers, Aftermarket Suppliers |
| Companies Covered | CRRC Corporation Limited, Hitachi Rail, Alstom SA, G&Z Enterprises Ltd, Knorr-Bremse AG, SCHUNK GmbH & Co. KG, Siemens Mobility, Mersen Group, Wabtec Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Locomotive Pantographs Market Shifts & Advancements
Digitalization of condition monitoring and material science advances are compressing maintenance intervals while expanding operational envelopes for electric traction systems.
Composite-material pantograph frames incorporating carbon-fiber reinforced polymers are modularizing field-repair protocols. Deutsche Bahn and SNCF are phasing these into TGV and ICE fleets during mid-life refurbishment cycles. The technology is modularizing supplier relationships by decoupling frame manufacturing from contact-strip chemistry expertise.
REACH and RoHS amendments are restricting heavy-metal content in contact-strip alloys across European procurement specifications. Manufacturers must reformulate copper-tungsten and copper-chromium compositions to maintain conductivity while eliminating restricted substances. High-speed operators in Spain and Italy are prioritizing certified-compliant suppliers in tender evaluations.
Long-term service agreements are displacing transactional component sales among major rail operators. SNCF Réseau and JR East are contracting 15-year availability guarantees that bundle pantograph supply with predictive replacement scheduling. This restructuring concentrates margin pools with integrated system providers in France and Japan.
Locomotive Pantographs Market Segmentation
Pantograph procurement patterns diverge sharply between integrated rolling-stock programs and standalone replacement cycles. Segment boundaries determine margin capture, with embedded installations commanding system-level pricing and aftermarket channels competing on carbon-strip chemistry and logistics velocity.
Product Type:
Single-arm configurations dominate embedded installations on new high-speed builds, while double-arm variants persist in retrofit markets and heavy-haul corridors requiring redundant contact redundancy.
- Single Arm:Aluminum-frame single-arm pantographs reduce aerodynamic drag and unsprung mass for operations above 250 km/h. Deutsche Bahn and SNCF specify these for ICE and TGV fleet renewals, with procurement tied to 15-year availability contracts bundling predictive maintenance.
- Double Arm:Hinged double-arm designs maintain contact force stability across wider catenary sway envelopes in freight corridors. Russian Railways and Indian Railways deploy these on 25 kV AC dedicated freight routes where speed consistency matters less than mechanical durability.
- Manual:Hand-operated pantographs serve depot shunting and heritage rail preservation fleets with minimal electrification infrastructure.
- Automatic:Sensor-integrated automatic systems adjust contact force in real-time for JR East and SNCF Réseau high-density corridors.
Volume placements concentrate in Single Arm; the faster expansion belongs to Automatic.
Material:
Material selection determines service intervals, catenary wire wear rates, and compliance with evolving environmental regulations across procurement jurisdictions.
- Aluminum:Extruded aluminum alloys deliver the strength-to-weight ratio required for high-speed aerodynamic frames. CRRC and Siemens specify 6000-series alloys with anodized finishes for corrosion resistance in coastal Chinese and Mediterranean deployments.
- Composite:Carbon-fiber reinforced polymer frames modularize field-repair protocols and extend structural life cycles. Deutsche Bahn's mid-life ICE refurbishments are phasing these in to reduce depot turnaround times.
- Steel:Fabricated steel frames persist in price-sensitive regional rail markets and emerging economy procurements.
- Plastic:Injection-molded polymer components serve non-structural fairings and insulating elements in lower-voltage DC systems.
Aluminum captures current volume leadership; composites are climbing the fastest on replacement-cycle demand.
Installation Type:
Installation architecture shapes supplier relationships, with integrated packages tightening OEM channel control and modular designs enabling operator-direct procurement flexibility.
- Integrated:Factory-installed pantograph-catenary systems bundle frame, contact strip, and diagnostic hardware under single-source accountability. Alstom and Siemens Mobility structure these offerings around EN 50206-1 certification packages for cross-border European acceptance.
- Modular:Field-swappable module architectures decouple frame replacement from contact-strip chemistry decisions. Japanese and South Korean operators leverage these to bypass OEM service networks for carbon-strip procurement.
- Fixed:Permanent roof-mounted installations dominate legacy fleet configurations with limited upgrade pathways.
- Removable:Quick-detach mounting systems support multi-voltage corridor operations and emergency swap protocols.
Integrated installations command the premium tier; modular formats are gaining share fastest via aftermarket unbundling.
End User:
End-user category determines pricing power, contract structure, and technical specification authority in procurement negotiations.
- Rail Operators:State-owned and privatized rail operators consolidate purchasing around lifecycle cost optimization and predictive availability guarantees. SNCF Réseau and JR East structure 15-year service agreements that displace transactional component sales.
- OEMs:Rolling-stock manufacturers integrate pantograph supply into turnkey trainset deliveries, capturing margin through captive specification authority over contact-strip chemistry and frame design.
- Maintenance Providers:Third-party depot operators and refurbishment specialists procure replacement units for mid-life fleet upgrades.
- Aftermarket Suppliers:Independent distributors and carbon-strip specialists serve direct-to-operator channels, concentrated in Japan, South Korea, and Germany.
Rail Operators drive procurement volume; Aftermarket Suppliers are expanding most quickly as direct channels fragment traditional OEM service networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's national rail equipment industrial parks concentrate pantograph manufacturing capacity near Changchun and Qingdao, with MIIT-mandated GB standards filtering supplier access. Germany's Ruhr Valley hosts Siemens Mobility and Knorr-Bremse engineering centers serving TGV and ICE electrification programs. Japan's Kanto region anchors JR East's 15-year service agreement structures for sensor-integrated systems.
China
CRRC Corporation Limited leverages integrated manufacturing scale across carbon-strip and frame assemblies. MIIT enforces GB standards for pantograph-catenary dynamic interaction that elevate technical barriers for domestic suppliers. Changchun and Qingdao industrial clusters host captive carbon-composite processing facilities for high-speed rail fleets.
Germany
Deutsche Bahn's fleet renewal programs drive demand for aluminum-frame single-arm configurations. EU Green Deal mandates accelerate carbon-neutral rail infrastructure investments across federal corridors. Siemens Mobility and Knorr-Bremse anchor engineering centers in Munich and Berlin serving cross-border European acceptance protocols.
Japan
JR East structures 15-year availability guarantees that displace transactional component sales. METI standards govern contact-strip chemistry for Shinkansen corridor interoperability. Kanto region suppliers concentrate sensor-integrated automatic system production for high-density Tokyo-Osaka operations.
India
Dedicated freight corridors create captive demand for 25 kV AC pantograph testing under CEA and RDSO protocols. PLI scheme incentives attract domestic assembly investments from foreign suppliers. Gujarat and Maharashtra industrial zones host emerging frame fabrication capacity for Western Dedicated Freight Corridor deployments.
France
SNCF Réseau contracts long-term service agreements bundling pantograph supply with predictive replacement scheduling. EU F-Gas Regulation compliance shapes pneumatic damping system material selection. Alstom SA anchors R&D intensity in aerodynamic single-arm designs through Saint-Ouen and La Rochelle engineering facilities.
Locomotive Pantographs Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated system providers tightening OEM channel control and aftermarket specialists capturing carbon-strip replacement margins. The vendor base concentrates around three strategic archetypes: state-affiliated rail equipment conglomerates with captive manufacturing scale, European engineering houses with sensor-integrated technology leadership, and specialized contact-material suppliers with chemistry expertise. Competitive positioning hardens through backward integration into carbon-composite supply chains and geographic expansion via localized assembly partnerships.
Among state-affiliated conglomerates, CRRC Corporation Limited exemplifies scale-driven vertical integration spanning frame extrusion through contact-strip formulation. European engineering specialists Siemens Mobility and Alstom SA occupy positions defined by EN 50206-1 certification authority and aerodynamic single-arm design leadership. German fabricators Knorr-Bremse AG and SCHUNK GmbH & Co. KG represent precision-component archetypes with concentrated expertise in pneumatic damping and carbon-strip metallurgy.
| Leading Market Players |
|---|
| CRRC Corporation Limited |
| Hitachi Rail |
| Alstom SA |
| G&Z Enterprises Ltd |
| Knorr-Bremse AG |
| SCHUNK GmbH & Co. KG |
| Siemens Mobility |
| Mersen Group |
| Wabtec Corporation |
| Others |
Supply & Pricing Matrix
Sovereign-backed rail equipment conglomerates with captive manufacturing scale anchor supply discipline and pricing power across the locomotive pantographs market. CRRC Corporation Limited's integrated Changchun and Qingdao facilities compress cost structures for domestic Chinese operators while elevating technical barriers for foreign entrants under MIIT GB standards. This ownership pattern concentrates margin capture in frame extrusion and carbon-strip formulation, forcing independent suppliers to compete on aftermarket logistics velocity rather than system-level pricing.
Pricing Analysis
Short lead-time premiums command substantial markups as Deutsche Bahn and SNCF Réseau enforce 15-year availability contracts with predictive replacement scheduling. Pricing stratifies across premium, standard, and economy tiers based on EN 50206-1 certification authority and sensor-integrated diagnostic bundling. Cost compression in economy-grade aluminum frames is intensifying because Indian and Russian freight operators prioritize mechanical durability over aerodynamic efficiency. Aftermarket suppliers serving direct-to-operator carbon-strip channels in Japan and South Korea exhibit the highest price sensitivity, while integrated OEM packages for TGV and ICE renewals sustain premium positioning.
Supply Chain Analysis
High-purity carbon and specialized aluminum alloys rest on extraction and processing operations concentrated in China, Russia, and select European metallurgical centers. CRRC and Siemens Mobility source 6000-series aluminum with anodized finishes and carbon-fiber reinforced polymers from captive or tightly contracted suppliers. Single-source vulnerability in Chinese carbon-composite processing creates exposure for Western operators dependent on imported contact-strip materials. Distribution runs through rolling-stock OEM channels for new-build installations and independent aftermarket networks for replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The locomotive pantographs market is consolidating as EU Green Deal mandates and MIIT GB standards force capital-intensive certification investments that weaker regional fabricators cannot absorb.
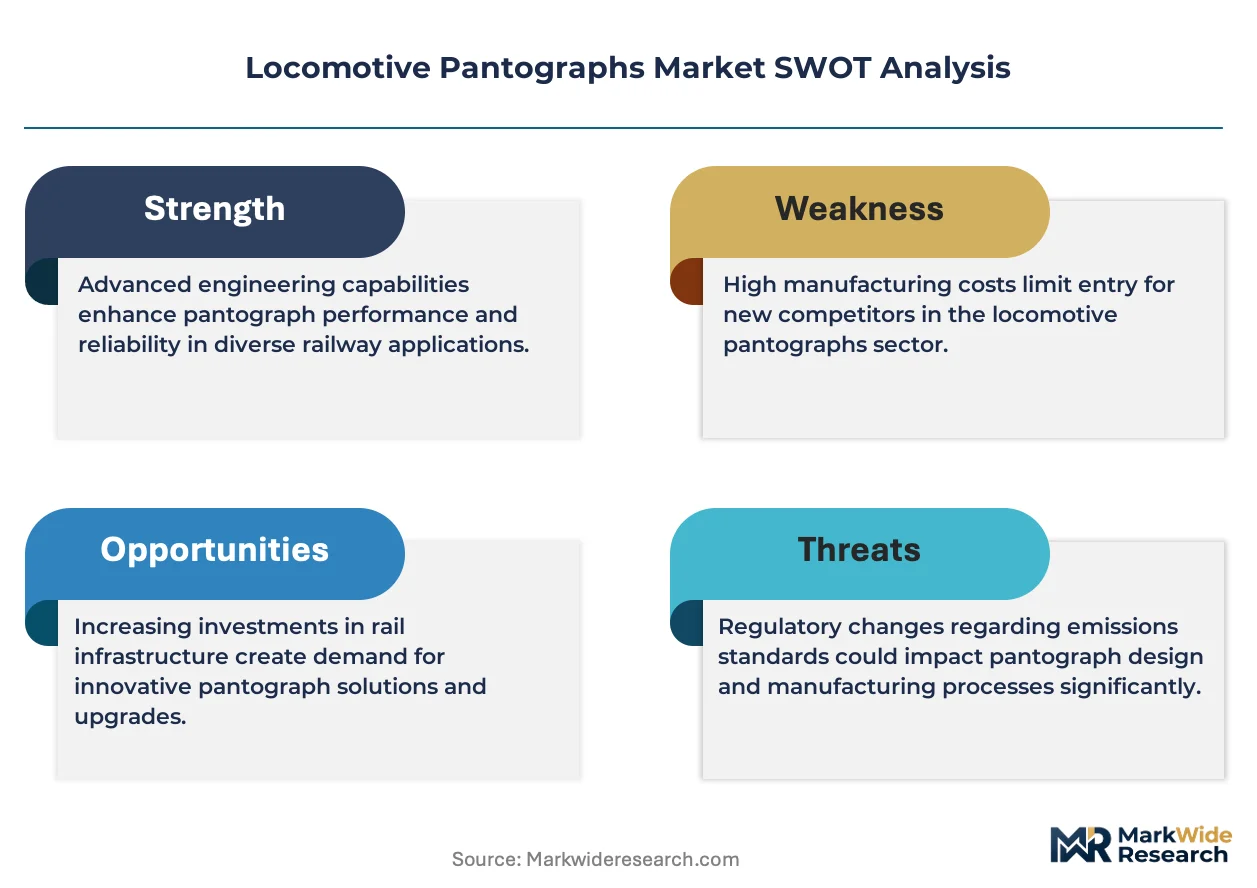
For Market Incumbents: Cement technology leadership in sensor-integrated automatic systems through R&D intensity in aerodynamic single-arm designs. Alstom SA and Siemens Mobility should deepen backward integration into carbon-composite supply chains to secure contact-strip chemistry expertise against emerging Asian competitors. Channel control over EN 50206-1 certification packages for cross-border European acceptance remains the critical defensive lever. For New Entrants and Emerging Players: Direct-to-operator digital procurement platforms offer the most penetrable route into aftermarket carbon-strip replacement channels fragmented across Japan, South Korea, and Germany. India's dedicated freight corridors under CEA and RDSO protocols present white-space demand for suppliers establishing domestic assembly partnerships. Target modular field-swappable architectures that decouple frame replacement from contact-strip decisions, bypassing OEM service networks. For Investors and Strategic Acquirers: JR East's 15-year service agreement structures with predictive replacement scheduling are the leading indicator that long-term availability contracts will displace transactional component sales across the analysis window. Acquisition targets should concentrate on specialized contact-material suppliers with chemistry expertise and sensor-integrated technology specialists outside the CRRC-Siemens-Alstom engineering center triangle. Watch for PLI scheme incentive announcements in Indian industrial zones as inflection signals for domestic assembly investment viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon-Composite Supply | Secures contact-strip chemistry expertise against supply bottlenecks concentrated in Chinese extraction operations. |
| Sensor-Integrated Automatic System Development | Captures predictive maintenance margins through IoT diagnostics convergence with carbon-strip wear prediction. |
| Domestic Assembly Partnership in India | Positions suppliers for CEA and RDSO-mandated localized testing protocols on 25 kV AC freight corridors. |
| EN 50206-1 Certification Authority Investment | Accelerates cross-border product acceptance in fragmented European networks facing 18-24 month interoperability delays. |
| Direct-to-Operator Aftermarket Channel | Bypasses OEM service networks in Japan and South Korea where carbon-strip replacement cycles concentrate margin pools. |
Research Methodology
Trade databases, customs filings, and rolling-stock OEM technical documentation formed the secondary backbone of this analysis. Primary interviews with rail operator procurement directors, pantograph engineering leads at Tier 1 suppliers, aftermarket service managers, and regulatory compliance officers at national rail safety bodies combined with secondary validation through bottom-up and top-down triangulation. The study synthesized EN 50206-1 test report archives, MIIT GB standard enforcement records, and EU Green Deal implementation timelines across the analysis window.
Historical trendline analysis of fleet electrification programs and pantograph replacement cycles anchored the quantitative framework. Segmentation modeling incorporated product type, material composition, installation architecture, and end-user category across the projection horizon. CAGRs were derived from rolling-stock delivery schedules, mid-life refurbishment timelines, and aftermarket replacement velocity patterns. Carbon-composite adoption curves and sensor-integrated system penetration rates served as industry-specific forecast inputs.
Inputs from rail operator procurement databases and OEM technical specifications were available through the study window; gaps in real-time carbon-strip inventory positioning and confidential contract pricing introduce uncertainty bands around aftermarket share estimates. Forecasts reflect assumptions regarding MIIT GB standard enforcement intensity and EU F-Gas Regulation compliance timelines. A small set of triggers—including PLI scheme disbursement announcements in India, REACH amendment finalizations, and JR East service agreement renewals—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
South Africa Automotive Carbon Fiber Composites Market
Vehicle Components
Motor Lamination Market
Vehicle Components
2 Wheeler Fuel Injection System Market
Vehicle Components
Car Sunshade Market
Vehicle Components
Wheel Loaders Market
Vehicle Components
Composite Bearings Market
Vehicle Components
5th Wheel Hitches Market
Vehicle Components
Bicycle Components Aftermarket Market
Vehicle Components
Steer-by-Wire Road Wheel Actuator Modules Market
Vehicle Components
High Efficiency Rolling Bearings Market
Vehicle Components
Two-Wheeled Containers Market
Vehicle Components
Front Forks Market
Vehicle Components
Refrigerated Trailer Door Lock Market
Vehicle Components
Anchorage Connector Market
Vehicle Components
Vehicle Air Deflector Market
Vehicle Components
Saudi Arabia Car Rental and Leasing Market