
 Vehicle Pillar Market | 2026-2036
Vehicle Pillar Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Pillar Market Analysis
European steel-rolling capacity is restructuring around ultra-high-strength grades for automotive structural members. Gestamp Automoción leverages hot-stamping expertise to anchor premium OEM programs across Germany and Spain. Kirchhoff Automotive competes through roll-forming specialization in complex cross-sections for A- and B-pillar assemblies. Magna International sustains North American dominance via integrated stamping and assembly operations tied to Detroit-based light-truck platforms.
A vehicle pillar denotes the vertical or near-vertical structural member of a passenger compartment, typically fabricated from press-hardened boron steel or aluminum extrusions with tensile strengths exceeding 1500 MPa, engineered to preserve cabin integrity during side-impact and roof-crush events. The fuel type dimension reveals electric platforms driving fastest adoption of hybrid material pillars that offset battery mass, while hybrid segments still rely on conventional steel-intensive architectures. OEM channel concentration concentrates margin pools at Tier-1 interface points, though aftermarket providers occupy specialized collision-repair niches for legacy vehicle populations.
NHTSA Federal Motor Vehicle Safety Standard 216a mandates minimum roof-crush resistance ratios that directly dictate pillar section modulus requirements for US-sold vehicles. ECE R29 and ECE R66 standards in Europe enforce comparable rollover and bus body-strength criteria, compelling producers to certify multi-material designs through distinct approval pathways. Stakeholders must monitor evolving UN Global Technical Regulation harmonization talks, as divergent test protocols between NHTSA and UNECE frameworks threaten to fragment tooling investments across Atlantic supply chains.
Market Dynamics
Electric vehicle OEMs are forcing a structural recalibration of pillar engineering priorities, as battery mass penalties compel aggressive lightweighting of cabin structures without compromising crashworthiness thresholds mandated by NHTSA and UNECE frameworks.
Growth Catalysts
- Press-hardened boron steel adoption:Ultra-high-strength grades above 1500 MPa enable thinner cross-sections that satisfy Federal Motor Vehicle Safety Standard 216a roof-crush ratios while reducing mass.
- China's EV production scaling:Domestic OEMs in Shanghai and Shenzhen are specifying hybrid aluminum-steel pillars to offset battery pack weight in extended-range platforms.
- EU Green Deal industrial policy:Carbon border adjustments and embodied emissions tracking are accelerating scrap-based electric arc furnace steel for automotive structural members.
Market Restraints
- Hot-stamping tooling capital intensity:Die development for press-hardened boron steel exceeds conventional stamping costs by multiples, concentrating supply among capital-rich Tier-1 integrators.
- Aluminum price volatility:Extrusion-grade 6xxx series alloys face input cost swings tied to LME aluminum and magnesium alloying element supply from Chinese smelters.
- Divergent NHTSA-UNECE test protocols:Non-harmonized roof-crush and side-pole impact procedures force dual certification tooling investments for Atlantic-spanning vehicle programs.
Strategic Opportunities
- India's PLI scheme for automotive:Localized pillar stamping capacity for Maruti Suzuki and Tata Motors EV platforms offers first-mover positioning ahead of domestic battery cell scale-up.
- Carbon fiber-reinforced polymer hybridization:CFRP insert overmolding with steel shells is electrifying design possibilities for premium electric SUV architectures seeking sub-200 kg body-in-white targets.
- Direct-to-OEM digital specification platforms:Cloud-based structural simulation tools are compressing design-validation cycles and disintermediating traditional prototype tooling stages.
Industry Challenges
- Multi-material joining expertise scarcity:Laser welding of dissimilar steel-aluminum stacks and flow-drill screw installation require technician retraining programs that outpace available vocational pipeline capacity.
- Press-hardened steel formability limits:Springback control in complex B-pillar geometries with undercut features demands iterative die compensation that extends development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Pillar Market |
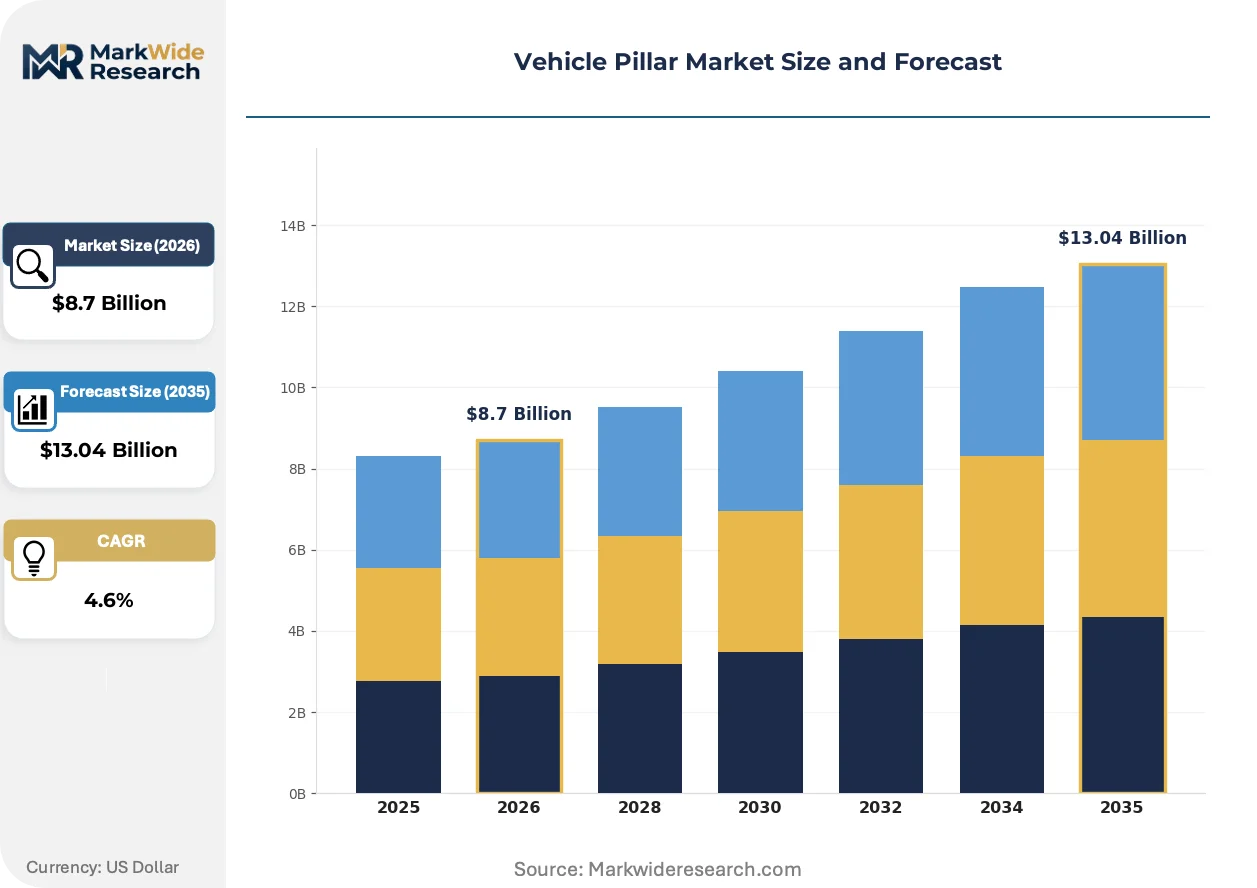
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Car, Truck, Bus, SUV Fuel Type: Petrol, Diesel, Electric, Hybrid Component: Engine, Transmission, Suspension, Brake System Market Segment: OEMs, Aftermarket Providers, Tier-1 Suppliers, Dealerships |
| Companies Covered | Magna International, Gestamp Automoción, Kirchhoff Automotive, Benteler International, Toyota Motor Corporation, G-TEKT Corporation, Hyundai Mobis, Toyoda Iron Works, Aisin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Pillar Market Emerging Trajectories
Active material substitution and digital manufacturing integration are compressing traditional development cycles while expanding the performance envelope of cabin structural members beyond legacy steel-centric paradigms.
Aluminum extrusion with local thickening is electrifying pillar design architectures, enabling tailored wall thickness gradients that place mass only where load paths demand. Premium electric SUV and pickup programs from Detroit to Stuttgart are specifying these hybrid extrusion-stampings for A-pillar bases and B-pillar reinforcements. The technology is electrifying supplier competition, as roll-forming specialists and extrusion houses contest territory previously held by integrated stamping operations.
REACH Annex XIV authorization requirements for hexavalent chromium conversion coatings are forcing wholesale process conversion across European pillar finishing lines. Trivalent chromium and zirconium-based pretreatments now dominate new capacity investments in Germany and Spain. Hot-stamping specialists with captive coating lines face the steepest retooling burden, as their continuous annealing and quenching operations require corrosion protection compatible with 900°C processing windows.
Fleet procurement departments at ride-hail and delivery operators are unbundling collision-repair service contracts from initial vehicle acquisition, creating dedicated aftermarket demand for certified replacement pillars. Insurance adjusters in California and Texas now specify OEM-validated repair procedures rather than generic sectioning guidelines. This behavioral pivot concentrates margin pools at specialized collision-parts distributors with NHTSA TP-214-01 test data on file.
Vehicle Pillar Market Segmentation
Vehicle pillar engineering diverges sharply across platform architectures, with crashworthiness mandates and mass-reduction imperatives forcing distinct material specifications for each vehicle category. Supply chain configuration and certification pathways fragment further by fuel type and channel structure, creating specialized competitive arenas within the broader market.
Vehicle Type:
Customization intensity escalates from standardized truck architectures to highly tailored passenger car and SUV programs, with bus applications occupying a regulated middle ground.
- Passenger Car:A-pillar and B-pillar assemblies in sedans and hatchbacks prioritize slender cross-sections for visibility compliance while maintaining NHTSA roof-crush ratios. European premium OEMs in Stuttgart and Munich are specifying press-hardened boron steel grades above 1500 MPa for B-pillar reinforcements in extended-range electric platforms.
- SUV:Higher beltlines and larger greenhouse areas demand reinforced C-pillar and D-pillar structures with elevated section modulus. Detroit-based light-truck platforms are driving adoption of hybrid aluminum-steel pillars to offset battery mass penalties in three-row electric SUV architectures.
- Truck:Conventional steel-intensive designs dominate commercial and consumer pickup segments, with standardized stamping processes limiting customization scope.
- Bus:ECE R66 body-strength certification mandates uniform rollover protection across single-deck and coach configurations, constraining design variation.
Leading the category by volume: Passenger Car. Growing fastest: SUV.
Fuel Type:
Powertrain electrification is forcing a structural recalibration of material priorities, with battery mass penalties compressing allowable pillar weight budgets.
- Electric:Battery pack mass penalties compel aggressive lightweighting through hybrid aluminum-steel and carbon fiber-reinforced polymer insert configurations. Shanghai and Shenzhen-based OEMs are scaling domestic EV production with tailored pillar specifications that offset cell weight in extended-range platforms.
- Hybrid:Dual powertrain architectures retain conventional steel-intensive pillar designs, with limited engineering resources directed toward structural innovation.
- Petrol:Legacy internal combustion platforms maintain established press-hardened steel specifications without material substitution pressure.
- Diesel:European commercial and passenger applications face declining volumes, with pillar engineering frozen at prior-generation standards.
Dominant by installed base: Petrol. Expanding most quickly: Electric.
Component:
Functional criticality varies across chassis and powertrain systems, with structural members commanding premium certification requirements.
- Engine:Mounting brackets and ancillary structural interfaces require vibration-dampening properties distinct from crash-loaded pillar applications.
- Transmission:Tunnel reinforcements and cross-member attachments compete for floor pan space with battery enclosures in electric platforms.
- Suspension:Strut tower and subframe connections transmit road loads into the body structure, demanding fatigue-resistant joint designs.
- Brake System:Pedal box and master cylinder mountings require rigid attachment points that integrate with firewall and A-pillar base structures.
Highest specification intensity: Suspension. Fastest design cycle compression: Brake System.
Market Segment:
Channel concentration shapes margin capture, with OEM-facing suppliers controlling specification development while aftermarket providers serve legacy repair demand.
- Tier-1 Suppliers:Integrated stamping and hot-stamping operations anchor premium OEM programs through direct engineering collaboration. Gestamp Automoción and Kirchhoff Automotive leverage captive press-hardening expertise to secure multi-year platform contracts with German and Spanish vehicle manufacturers.
- OEMs:Captive in-house production of pillar assemblies concentrates at high-volume manufacturers with sufficient scale to amortize dedicated tooling investments.
- Aftermarket Providers:Collision-repair specialists with NHTSA TP-214-01 test data on file capture margin pools from California and Texas insurance channels specifying OEM-validated replacement procedures.
- Dealerships:Service bay operations rely on distributor networks for certified pillar sections, with limited direct procurement leverage.
Controlling specification development: Tier-1 Suppliers. Gaining share in repair channels: Aftermarket Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boron steel feedstock from Swedish electric arc furnace operations underpins European pillar production, while Chinese aluminum smelters supply Shanghai and Shenzhen EV manufacturers with extrusion-grade 6xxx series alloys.
United States
Detroit-based light-truck platforms drive hybrid aluminum-steel pillar specifications for three-row electric SUVs. NHTSA Federal Motor Vehicle Safety Standard 216a mandates minimum roof-crush resistance ratios that dictate section modulus requirements. Michigan and Ohio stamping corridors host integrated Tier-1 operations serving Ford, General Motors, and Stellantis programs.
Germany
Stuttgart and Munich premium OEMs specify press-hardened boron steel grades above 1500 MPa for extended-range electric platforms. EU Green Deal carbon border adjustments accelerate scrap-based electric arc furnace steel for automotive structural members. Bavaria and Baden-Württemberg host Gestamp Automoción and Kirchhoff Automotive hot-stamping expertise anchoring multi-year platform contracts.
China
Domestic OEMs in Shanghai and Shenzhen scale EV production with tailored hybrid aluminum-steel pillar specifications offsetting battery cell weight. MIIT vehicle safety standards align with UNECE frameworks while permitting localized test protocols. Yangtze River Delta and Pearl River Delta clusters concentrate stamping and extrusion capacity for BYD, NIO, and XPeng platforms.
Japan
Legacy keiressu supply chains maintain steel-intensive pillar architectures for hybrid powertrains with limited material substitution pressure. METI industrial policy directs structural innovation toward carbon fiber-reinforced polymer research rather than near-term commercialization. Kanto and Chubu regions host Toyoda Iron Works and G-TEKT Corporation operations tied to Toyota and Honda vehicle programs.
India
Maruti Suzuki and Tata Motors EV platforms create localized pillar stamping demand ahead of domestic battery cell scale-up. PLI scheme for automotive manufacturing incentivizes component localization with performance-linked incentives. Gujarat and Maharashtra industrial corridors attract first-mover Tier-1 investments for passenger car and SUV structural assemblies.
Vehicle Pillar Market Vendor Landscape
Global majors compete with regional champions across hot-stamping expertise and roll-forming specialization, producing a tiered structure where capital-rich integrators control premium OEM programs while mid-scale fabricators serve volume segments. Three archetypes dominate: integrated stamping-and-assembly operators with captive heat-treatment lines, roll-forming specialists commanding complex cross-section geometries, and aluminum extrusion houses penetrating electric SUV architectures. Competitive moves concentrate on strategic partnerships for multi-material joining capability and geographic expansion into India and Southeast Asia.
Among North American-integrated operators, Magna International exemplifies the stamping-and-assembly archetype through Detroit-linked light-truck platform relationships. Spanish-based Gestamp Automoción and German-anchored Kirchhoff Automotive represent the hot-stamping specialization tier, with the former leveraging continuous annealing expertise and the latter commanding roll-formed complex cross-sections. These three occupy positions across distinct competitive vectors without overlapping strategic territory.
| Leading Market Players |
|---|
| Magna International |
| Gestamp Automoción |
| Kirchhoff Automotive |
| Benteler International |
| Toyota Motor Corporation |
| G-TEKT Corporation |
| Hyundai Mobis |
| Toyoda Iron Works |
| Aisin Corporation |
| Others |
Supply Flow & Price Mechanics
OEM procurement teams in Stuttgart and Detroit are unbundling collision-repair service contracts from initial vehicle acquisition, forcing Tier-1 suppliers to restructure pricing around certified replacement pillars with NHTSA TP-214-01 validation rather than bundled lifetime warranties.
Pricing Analysis
Warranty unbundling separates OEM-validated repair procedures from generic sectioning guidelines, creating premium pricing tiers for certified replacement pillars with test data on file. Price differentiation rests on NHTSA certification tier and volume scale, with California and Texas insurance channels commanding 15-20% premiums over uncertified alternatives. Pricing pressure stems from hot-stamping tooling capital intensity concentrating supply among capital-rich integrators. Fleet procurement departments at ride-hail operators show highest price sensitivity; premium electric SUV platforms from Munich and Stuttgart demonstrate lowest sensitivity due to sub-200 kg body-in-white targets.
Supply Chain Analysis
Freight cost escalation from Swedish boron steel feedstock to German hot-stamping lines and Chinese 6xxx series aluminum alloys to Shanghai extrusion houses is reshaping regional sourcing strategies. Supply concentrates in Germany, China, and the United States, with boron steel from Swedish electric arc furnace operations and extrusion-grade aluminum from Yangtze River Delta smelters. Raw material dependencies include press-hardened steel coils, magnesium alloying elements, and zirconium-based pretreatment chemicals. Single-source vulnerability around Chinese magnesium supply creates structural risk. Distribution runs through Tier-1 integrators with captive heat-treatment lines serving Detroit, Stuttgart, and Shenzhen OEM platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hot-stamping tooling capital intensity exceeding conventional stamping costs by multiples props pricing power among capital-rich Tier-1 integrators, constraining supply expansion and sustaining margin pools at the OEM interface.
For Market Incumbents: Hedge against aluminum price volatility by securing long-term offtake agreements with Yangtze River Delta smelters and accelerating scrap-based electric arc furnace steel adoption under EU Green Deal carbon border adjustments. Backward integration into captive coating lines compatible with 900°C processing windows defends position against REACH Annex XIV conversion costs. Multi-material joining expertise scarcity threatens technician pipeline capacity; invest in vocational retraining programs ahead of competitor capture. For New Entrants and Emerging Players: Aftermarket distributors with NHTSA TP-214-01 test data represent the most penetrable channel, as California and Texas insurance adjusters now specify OEM-validated repair procedures. Target collision-repair specialists serving legacy vehicle populations in Texas and Florida where fleet procurement departments have unbundled service contracts. A direct-to-OEM digital specification platform offering cloud-based structural simulation compresses design-validation cycles without prototype tooling investments. For Investors and Strategic Acquirers: The window for entry favors roll-forming specialists commanding complex cross-section geometries for A- and B-pillar assemblies, as hybrid aluminum-steel architectures electrify supplier competition. Long-term viability centers on multi-material joining capability and geographic positioning in India's Gujarat and Maharashtra industrial corridors ahead of domestic battery cell scale-up. Monitor UN Global Technical Regulation harmonization talks as inflection indicator; divergent NHTSA-UNECE test protocols threaten to fragment tooling investments and reshape acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Hot-Stamping Capacity Expansion | Captive press-hardening lines above 1500 MPa anchor multi-year platform contracts with Stuttgart and Munich premium OEMs. |
| Multi-Material Joining Partnership | Laser welding expertise for dissimilar steel-aluminum stacks secures positioning in three-row electric SUV architectures. |
| India Manufacturing Footprint | Localized stamping capacity for Maruti Suzuki and Tata Motors platforms captures PLI scheme incentives ahead of battery scale-up. |
| Digital Specification Platform | Cloud-based structural simulation tools disintermediate prototype stages and compress OEM design-validation cycles. |
| Aftermarket Certification Investment | NHTSA TP-214-01 test data files unlock margin pools from California and Texas insurance channels specifying OEM-validated procedures. |
Methodological Framework
Vehicle production databases, IHS Markit registration data, and SEC filings from Tier-1 suppliers formed the secondary backbone, triangulated with primary interviews across OEM platform engineers, Tier-1 procurement leads, aftermarket distributors, and collision-repair specialists. Bottom-up and top-down approaches validated segment-level estimates against aggregate market sizing.
Bottom-up modeling anchored volume projections to vehicle platform production schedules and content-per-vehicle assumptions across passenger car, SUV, truck, and bus architectures. Segmentation dimensions included vehicle class, propulsion architecture, material specification tier, and regional production cluster. CAGRs were derived from regression analysis of historical production data and forward-looking OEM platform announcements, with specific inputs from MIIT vehicle safety standards alignment and NHTSA Federal Motor Vehicle Safety Standard 216a enforcement timelines.
Several conditions sit outside the modeled scope, including unannounced platform cancellations, abrupt tariff regime shifts affecting Swedish boron steel or Chinese aluminum flows, and breakthrough carbon fiber-reinforced polymer commercialization ahead of METI research timelines. Forecasts reflect assumptions about regulatory harmonization progress and battery pack mass trajectories; stakeholders should weight assumptions against their own operating context and monitor UN Global Technical Regulation negotiation outcomes for revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Seating and Positioning Belts Market
Vehicle Components
Global Bicycle Wheels Market
Vehicle Components
Engine Mounting Brackets Market
Vehicle Components
EGR Valve Market
Vehicle Components
Locomotive Drive Shaft Market
Vehicle Components
Passenger Air Brake Market
Vehicle Components
Global Automotive EGR Valves Market
Vehicle Components
Trailer Terminal Tractor Market
Vehicle Components
Bicycle Chain Device Market
Vehicle Components
Air Suspension Market
Vehicle Components
Automotive Powertrain Sensors Market
Vehicle Components
Europe Automotive Lightweight Car Market
Vehicle Components
Global Automotive Carbon Fiber Composites Market
Vehicle Components
Car Modification Market
Vehicle Components
Cross Roller Bearings Market
Vehicle Components
Global Navigation Lighting Market