
 Injector Deposit-Resistant Fuel Injection Component Platforms Market | 2026-2036
Injector Deposit-Resistant Fuel Injection Component Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Injector Deposit-Resistant Fuel Injection Component Platforms Market Insights
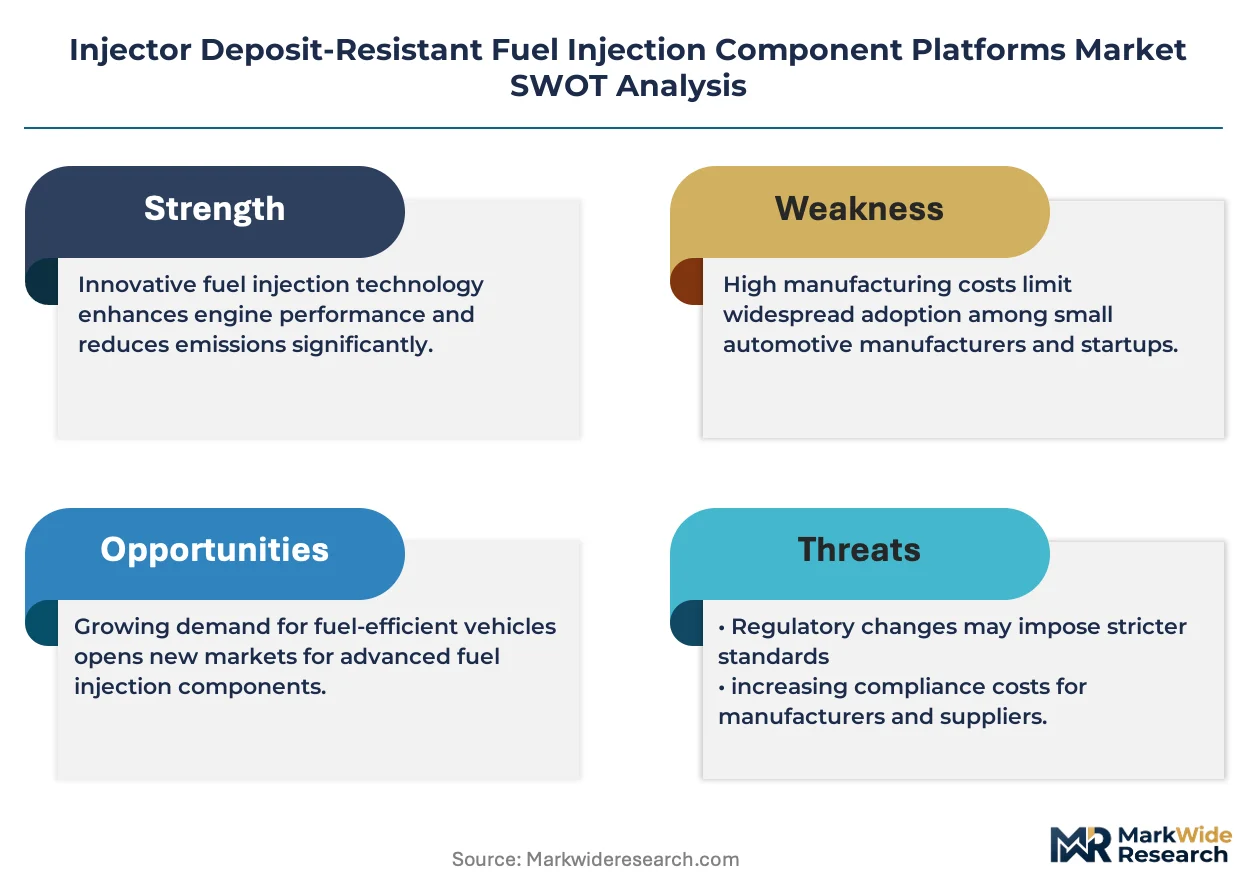
The EU Green Deal's transport decarbonization targets is rebalancing procurement criteria across European OEMs toward injector platforms engineered for biofuel compatibility and extended deposit resistance. Robert Bosch leverages its Stuttgart engineering base to sustain leadership in common-rail systems with integrated deposit-mitigation coatings. DENSO anchors Asian supply chains through specialized piezoelectric actuator production for Japanese and Korean manufacturers. Continental competes on manufacturing scale across its German and Romanian facilities, offering modular injector families that span light-duty through heavy-duty engine applications.
Injector deposit-resistant fuel injection component platforms comprise precision-engineered nozzle assemblies, valve bodies, and control elements fabricated from stainless steel, ceramic, or nickel alloy substrates, with surface treatments such as diamond-like carbon coatings or optimized spray-hole geometries that maintain fuel flow characteristics across extended service intervals under variable fuel quality conditions. The technology segment shows solenoid and piezoelectric architectures dominating current OEM fitment, while common-rail platforms capture the deepest margin pools due to their integration complexity and calibration service attach rates. Stainless steel and nickel alloy material categories lead volume, though ceramic nozzle tips represent the fastest-growing subset for high-pressure direct-injection engines where thermal shock resistance governs component life.
The EPA enforces Tier 3 emission standards that mandate reduced particulate matter from gasoline direct-injection engines, directly shaping injector cleanliness specifications for US-bound vehicles. EMA, REACH, and the EU F-Gas Regulation collectively constrain material choices and manufacturing chemistries across European production, while China's MEE implements Stage VIb standards that accelerate domestic adoption of deposit-resistant hardware. Stakeholders must monitor regulatory divergence between California's LEV IV framework and federal EPA rules, as this fragmentation threatens to splinter platform standardization and force parallel certification investments.
Market Dynamics
Deposit-resistant injector platforms face structural pressure from Euro 7 and China's Stage VIb emission standards, which mandate hardware redesigns that integrate particulate control directly into fuel delivery architecture rather than treating it as an after-treatment add-on.
Growth Catalysts
- Common-rail integration complexity:High-pressure direct-injection architectures now require deposit-mitigation coatings as standard fitment, expanding addressable hardware sets across light and heavy-duty applications.
- Euro 7 particulate limits:The regulation forces gasoline direct-injection engines to adopt ceramic nozzle tips and diamond-like carbon surface treatments to maintain flow characteristics under extended service intervals.
- Stuttgart precision manufacturing cluster:Concentrated supplier engineering capability in Germany accelerates prototype-to-production cycles for biofuel-compatible injector families.
Market Restraints
- Nickel alloy input volatility:Specialized superalloy feedstock for high-temperature nozzle assemblies exposes manufacturers to aerospace and energy sector demand competition.
- Supply concentration in Baden-Württemberg:Dependence on a single German state for precision machining capacity creates geographic vulnerability to logistics disruptions or labor actions.
- Piezoelectric actuator technical ceiling:Current ceramic stack architectures face thermal degradation thresholds that limit peak pressure capability in next-generation combustion cycles.
Strategic Opportunities
- India's Stage VI implementation:The country's national automotive regulator is accelerating hardware upgrade timelines that mirror European emission trajectories, opening procurement windows for deposit-resistant platforms.
- Dual-fuel compatibility convergence:Injector architectures engineered for simultaneous gasoline and bioethanol operation capture fleet procurement criteria under the EU Green Deal transport decarbonization framework.
- Direct OEM calibration services:Bypassing traditional tier-one integrators to offer engine-control-unit-matched injector sets creates margin capture opportunities in Japanese and Korean supply chains.
Industry Challenges
- Multi-physics simulation talent scarcity:Computational fluid dynamics expertise combining fuel spray behavior with thermal-mechanical stress modeling commands premium compensation and extended recruitment cycles.
- Parallel certification investments:Divergence between California's LEV IV framework and federal EPA Tier 3 rules forces duplicate validation testing for US-bound platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Injector Deposit-Resistant Fuel Injection Component Platforms Market |
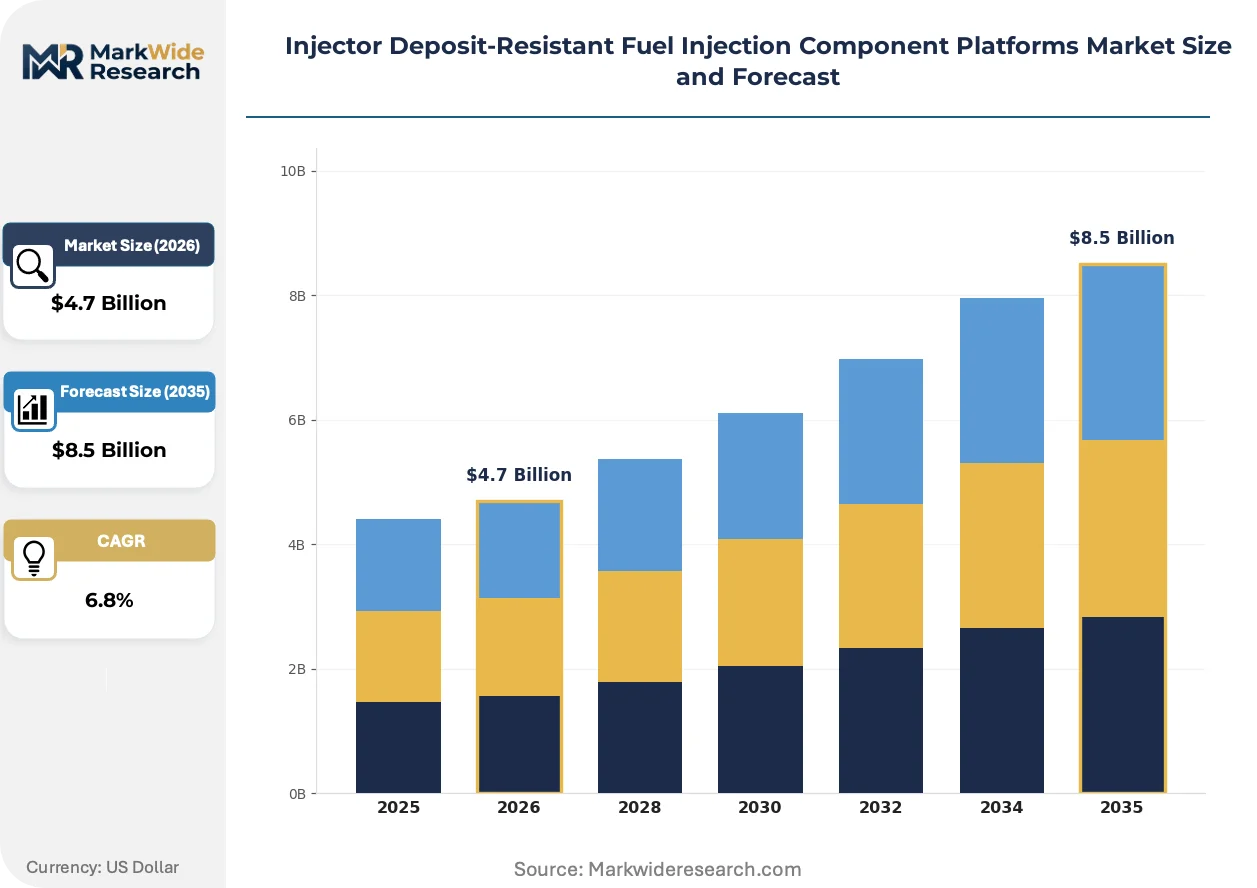
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $8.5 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Stainless Steel, Ceramic, Titanium, Aluminum Alloy, Nickel Alloy Technology: Piezoelectric, Solenoid, Common Rail, Multi-Hole, Distributor Type Application: Heavy-Duty Engines, Light Commercial Vehicles, Agricultural Equipment, Construction Machinery, Marine Engines End User: OEM Manufacturers, Aftermarket Suppliers, Fleet Operators, Engine Rebuilders |
| Companies Covered | Robert Bosch, DENSO, Continental, PHINIA, Hitachi Astemo, Magneti Marelli, Valeo, Cummins, Westport Fuel Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Injector Deposit-Resistant Fuel Injection Component Platforms Market Trends and Innovations
Ceramic nozzle tip architectures are displacing conventional metal alloys in high-pressure direct-injection applications, while regulatory fragmentation between California and federal standards is fragmenting platform standardization. Fleet procurement criteria increasingly weight total cost of ownership over unit hardware pricing.
Diamond-like carbon coating deposition is consolidating as the dominant surface treatment for deposit-resistant injector orifices. The technology maintains precise spray-hole geometries across variable fuel quality conditions, including high-olefin gasoline and hydrotreated vegetable oil blends. Tier-one suppliers in Germany and Japan are adopting plasma-enhanced chemical vapor deposition at scale, compressing the performance gap between premium and standard injector tiers.
REACH and the EU F-Gas Regulation are constraining material choices across European production, specifically limiting chromium-based hard coatings and certain fluorinated process chemistries. The industrial consequence is accelerated qualification of alternative ceramic matrices and physical vapor deposition routes. Common-rail platforms for heavy-duty engines face the steepest reformulation timelines, with manufacturers in Romania and Germany requalifying supply chains ahead of enforcement deadlines.
After-sales service unbundling is reshaping how fleet operators acquire injector maintenance. Large commercial vehicle operators in Japan and Germany now separate hardware procurement from calibration and refurbishment services, pressuring traditional bundled pricing models. This pattern is most visible in light commercial vehicle segments where telematics-enabled condition monitoring enables predictive replacement scheduling rather than interval-based maintenance.
Injector Deposit-Resistant Fuel Injection Component Platforms Market Segmentation
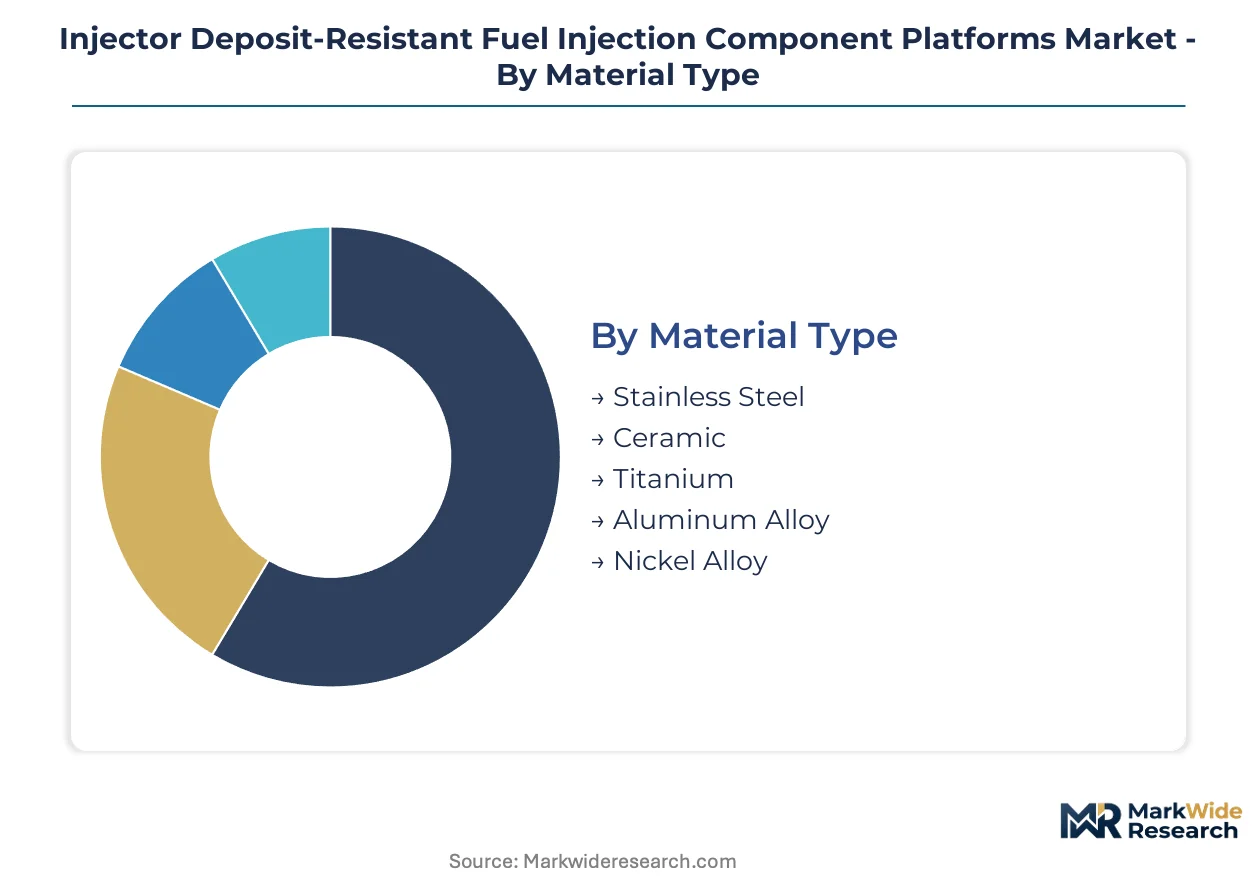
Injector platform procurement cycles diverge sharply across material grades and duty cycles. Fleet operators and OEMs now segment hardware investments by thermal stress thresholds and fuel compatibility horizons rather than unit cost alone.
Material Type:
Upgrade timelines for Euro 7 and Stage VIb compliance are compressing replacement windows for legacy alloy substrates.
- Stainless Steel:Austenitic and martensitic grades dominate volume manufacturing for solenoid valve bodies and injector sleeves. German precision clusters in Baden-Württemberg anchor capacity for high-volume common-rail production serving European OEMs.
- Ceramic:Zirconia-toughened alumina formulations withstand thermal shock in gasoline direct-injection nozzles exceeding 200 bar. Japanese suppliers in Aichi Prefecture drive qualification for piezoelectric actuator integration where dimensional stability governs spray precision.
- Titanium:Beta-alloy variants reduce reciprocating mass in high-frequency piezoelectric stacks for racing and premium passenger applications.
- Aluminum Alloy:A356 and similar cast grades serve cost-sensitive distributor-type injector housings in emerging market agricultural equipment.
- Nickel Alloy:Inconel and Haynes superalloys retain creep resistance for heavy-duty marine and locomotive injectors operating at sustained 1800°C flame temperatures.
Stainless steel sits at the top of the volume ranking, with ceramic climbing the fastest.
Technology:
Cost tier stratification separates integrated common-rail systems from standalone actuator architectures.
- Piezoelectric:Lead zirconate titanate ceramic stacks enable sub-millisecond response for multiple injection events per cycle. Korean and Japanese OEM procurement concentrates on Aichi and Gyeonggi-do supplier bases for gasoline direct-injection platforms.
- Solenoid:Electromagnetic actuators retain cost advantage in heavy-duty diesel where injection frequency demands are moderate. Romanian manufacturing clusters supply modular families spanning light through heavy-duty engine ratings.
- Common Rail:Integrated high-pressure accumulator and injector modules capture the deepest margin pools through calibration service attach rates and proprietary rail geometries.
- Multi-Hole:Six to twelve-hole nozzle configurations optimize spray atomization for particulate reduction in Euro 7 gasoline engines.
- Distributor Type:Rotary pump-fed injector lines persist in retrofit markets and developing economy agricultural fleets.
Common rail commands the premium tier by margin contribution, while piezoelectric architectures gain share fastest in passenger car direct-injection fitment.
Application:
Customer type differentiation separates fleet-scale procurement from unit replacement demand.
- Heavy-Duty Engines:Class 8 truck and locomotive injectors require 800,000-kilometer service intervals with diamond-like carbon coatings. German and US fleet operators now unbundle hardware from calibration services.
- Light Commercial Vehicles:Van and pickup applications drive ceramic nozzle tip adoption under EPA Tier 3 particulate mandates. Telematics-enabled condition monitoring enables predictive replacement scheduling.
- Agricultural Equipment:Tractor and combine harvester injectors face biofuel compatibility requirements under EU Green Deal decarbonization targets.
- Construction Machinery:Off-road engines in excavators and loaders transition to Stage V and China Stage IV emission hardware.
- Marine Engines:IMO Tier III compliance forces high-pressure common-rail retrofits in coastal and inland vessel fleets.
Light commercial vehicles lead by unit volume, with marine engines expanding most quickly on regulatory retrofit timelines.
End User:
Supply concentration shapes procurement leverage across integrated versus fragmented demand bases.
- OEM Manufacturers:Volkswagen, Toyota, and Hyundai Motor Group captive procurement drives platform standardization for deposit-resistant injector families. Direct ECU-matched injector sets bypass traditional tier-one integrators.
- Aftermarket Suppliers:Independent distributors face margin compression as OEMs extend certified remanufacturing programs.
- Fleet Operators:Large German and Japanese commercial vehicle operators separate hardware procurement from refurbishment services.
- Engine Rebuilders:Remanufacturing specialists in India and Mexico concentrate on cost-optimized solenoid injector refurbishment for secondary markets.
OEM manufacturers dominate absolute demand value, with fleet operators gaining procurement sophistication fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision machining talent clusters in Stuttgart, Aichi Prefecture, and Detroit anchor injector platform engineering capacity across three continents. These workforce concentrations sustain prototype-to-production cycles for deposit-resistant hardware serving Euro 7, EPA Tier 3, and China Stage VIb compliance timelines.
Germany
Baden-Württemberg's precision manufacturing cluster supplies common-rail injector families to Volkswagen and BMW. The KBA enforces Euro 7 pre-certification testing that accelerates ceramic nozzle tip adoption. Stuttgart engineering bases sustain Bosch and Continental leadership in diamond-like carbon coating deposition for gasoline direct-injection platforms.
Japan
Aichi Prefecture piezoelectric actuator specialists serve Toyota and Hyundai Motor Group procurement for Asian OEM supply chains. METI coordinates domestic Stage VI-equivalent standards alignment with export market requirements. Nagoya-area facilities concentrate high-frequency ceramic stack production where dimensional stability governs spray precision.
United States
Michigan and Ohio-based Tier-1 integrators face EPA Tier 3 particulate mandates for light commercial vehicle fleets. The EPA enforces reduced particulate matter limits from gasoline direct-injection engines that shape injector cleanliness specifications. Detroit engineering centers calibrate injector sets for Ford and General Motors powertrain divisions.
China
Yangtze River Delta manufacturing bases produce Stage VIb-compliant hardware for domestic heavy-duty engine retrofits. The MEE implements emission standards that accelerate adoption of deposit-resistant nozzle assemblies. Shanghai and Jiangsu Province facilities concentrate solenoid actuator volume production for local OEM procurement.
India
Tamil Nadu and Maharashtra automotive corridors prepare Stage VI hardware upgrade timelines mirroring European emission trajectories. The country's national automotive regulator compresses replacement windows for legacy injector substrates. Pune and Chennai manufacturing clusters qualify ceramic nozzle tips for Maruti Suzuki and Tata Motors supply chains.
Injector Deposit-Resistant Fuel Injection Component Platforms Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across injector platform supply tiers. The market structure concentrates around integrated common-rail system architects, specialized piezoelectric component fabricators, and regional solenoid valve assemblers. Three archetypes dominate: full-system integrators capturing calibration service attach rates, ceramic stack specialists commanding premium positioning, and scale-driven manufacturers serving cost-optimized distributor-type segments. Competitive moves center on backward integration into superalloy feedstock sourcing and geographic expansion through Romanian and Mexican production bases.
Within the full-system integrator tier, Robert Bosch and Continental represent German engineering-centric positioning anchored in Baden-Württemberg precision clusters. DENSO occupies a distinct position as a Japanese Co., Ltd. structure exemplifying piezoelectric specialization for Asian OEM supply chains. These three entities collectively illustrate how geographic concentration in Stuttgart and Aichi Prefecture translates into prototype-to-production cycle advantages for deposit-resistant hardware families.
| Leading Market Players |
|---|
| Robert Bosch |
| DENSO |
| Continental |
| PHINIA |
| Hitachi Astemo |
| Magneti Marelli |
| Valeo |
| Cummins |
| Westport Fuel Systems |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal transport decarbonization targets gate qualified supply and premium-tier pricing access, as biofuel-compatible injector families require REACH-compliant ceramic matrices and diamond-like carbon coating deposition that only Stuttgart and Aichi Prefecture precision clusters currently certify at scale.
Pricing Analysis
The bundled-vs-unbundled service split now defines margin capture across fleet procurement. Three-tier pricing structure across premium, standard, and economy levels separates OEM-matched ECU calibration services from standalone hardware transactions. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in economy-tier solenoid architectures intensifies because Romanian and Mexican manufacturers expand modular family production. Fleet operators exhibit highest price sensitivity, while captive OEM procurement shows lowest sensitivity due to total cost of ownership frameworks.
Supply Chain Analysis
Precision machining talent scarcity in Baden-Württemberg, Aichi Prefecture, and Yangtze River Delta manufacturing bases constrains throughput expansion for ceramic nozzle tip and piezoelectric actuator output. Supply draws from Germany, Japan, and China for finished injector assemblies, with nickel alloy superalloy feedstock sourcing from aerospace-certified foundries in the US and Europe. Single-source vulnerability concentrates in Baden-Württemberg for high-pressure common-rail rail geometries. Distribution runs through Tier 1 integrator channels to OEM engine plants, with direct fleet procurement bypassing traditional intermediaries in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as Euro 7 and Stage VIb particulate mandates shift procurement criteria toward ceramic nozzle tips and diamond-like carbon coatings that command sustained premium positioning.
For Market Incumbents: Extend calibration service attach rates by capturing direct ECU-matched injector set procurement from Japanese and Korean OEMs, countering margin erosion from unbundled fleet maintenance contracts. Deepen backward integration into nickel alloy superalloy feedstock to secure capacity against aerospace sector demand competition. Add ceramic stack production capacity in Aichi Prefecture to meet piezoelectric actuator qualification timelines for gasoline direct-injection platforms. For New Entrants and Emerging Players: Begin with India's Stage VI hardware upgrade corridor, where compressed replacement windows for legacy injector substrates outpace domestic qualification capacity. Target agricultural equipment retrofit demand under EU Green Deal biofuel compatibility requirements, as this segment lacks integrated common-rail system incumbents. Pursue calibration-as-a-service partnerships with telematics-enabled fleet operators to bypass traditional Tier 1 integration barriers. For Investors and Strategic Acquirers: Roll-up economics work for regional solenoid valve assemblers with captive remanufacturing capabilities because aftermarket service unbundling creates margin capture opportunities in India and Mexico secondary markets. Long-term viability centers on 5-10 year emission regulatory trajectories that entrench deposit-resistant hardware as standard fitment. Monitor ceramic nozzle tip adoption rates in light commercial vehicle segments as inflection indicator for technology displacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Superalloy Feedstock | Secures nickel alloy supply against aerospace and energy sector demand competition. |
| Ceramic Nozzle Tip Capacity Expansion | Captures Euro 7 gasoline direct-injection hardware redesign procurement from Volkswagen and BMW. |
| Direct OEM Calibration Services | Bypasses Tier 1 integrators to capture margin pools in Toyota and Hyundai Motor Group supply chains. |
| Telematics-Enabled Predictive Maintenance | Enables fleet operators in Germany and Japan to unbundle hardware from refurbishment services. |
| Romanian Manufacturing Footprint Expansion | Serves modular injector families across light through heavy-duty engine ratings for European OEMs. |
Research Methodology
Direct dialogue with OEM platform engineers, Tier 1 supplier procurement leads, fleet maintenance directors, and precision machining facility managers grounded qualitative assessment in operational reality. Secondary validation drew from KBA Euro 7 pre-certification filings, EPA Tier 3 enforcement documentation, MEE Stage VIb implementation notices, vehicle production databases, and SEC filings from listed automotive component suppliers. Bottom-up segment sizing triangulated against top-down macroeconomic and regulatory scenario analysis.
Segment-level projections across material type, technology architecture, application duty cycle, and end-user procurement channel fed into an integrated analytical framework across the analysis window. CAGRs derived from regression analysis against emission standard implementation timelines, fleet replacement cycles, and biofuel blend penetration assumptions. Industry-specific inputs included ceramic thermal shock resistance qualification data and piezoelectric actuator response degradation curves under sustained high-pressure operation.
Several conditions sit outside the modeled scope, including abrupt regulatory divergence between California LEV IV and federal EPA rules, nickel alloy commodity price spikes from aerospace sector demand surges, and breakthroughs in alternative combustion architectures that bypass high-pressure direct-injection hardware. Forecasts reflect assumptions about emission standard enforcement consistency and OEM platform standardization trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Vehicle Pillar Market
Vehicle Components
Wheel Seals Market
Vehicle Components
Mining Vehicle AC Kits Market
Vehicle Components
Bicycle Front Hub Market
Vehicle Components
Italy Automotive Glass Fiber Composites Market
Vehicle Components
Trailer Stabilizer Market
Vehicle Components
Global Undercarriage Components Market
Vehicle Components
Automotive Exhaust Gas Sensor Market
Vehicle Components
Engine Components Market
Vehicle Components
Car Diffuser Market
Vehicle Components
Vehicle-To-X Products Market
Vehicle Components
Rail Wheel Market
Vehicle Components
Gas-Powered Chainsaw Market
Vehicle Components
Automotive Position Sensor Market
Vehicle Components
Bicycle Frames Market
Vehicle Components
EGR Coolers Market