
 Swamp Boat Market | 2026-2036
Swamp Boat Market Size, Share, and Industry Trends Forecast 2026-2036
Swamp Boat Market Analytics
EPA marine engine emissions standards is hardening compliance requirements for shallow-water propulsion systems. Gator Tail leverages its surface-drive expertise to sustain market presence across Gulf Coast wetlands. Pro-Drive anchors its position through specialized mud motor engineering for extreme vegetation environments.
Swamp boats are shallow-draft vessels engineered with flat or near-flat hull configurations, typically constructed from welded aluminum with draft measurements below eight inches to traverse submerged vegetation and soft-bottom wetlands. Airboats employ aircraft-style propellers mounted on elevated cages, generating thrust without submerged drive components that would foul in aquatic plant matter. Flat-bottomed boats dominate current procurement volumes among commercial operators navigating timber-laden backwaters. Electric motors represent the fastest-growing engine type segment as wildlife agencies prioritize acoustic stealth for biological monitoring operations. Small boats command the largest share of recreational transactions, while extra-large configurations capture premium pricing from law enforcement and search-and-rescue applications.
US Coast Guard small vessel safety regulations and EPA Tier 3 marine emissions standards constrain engine specifications and hull certification requirements for swamp boat manufacturers. The US Fish and Wildlife Service fleet procurement protocols further shape demand patterns through specified performance benchmarks for federal wetland management contracts. Stakeholders must weigh propulsion technology bets against evolving electrification mandates while maintaining operational reliability in debris-heavy environments.
Market Dynamics
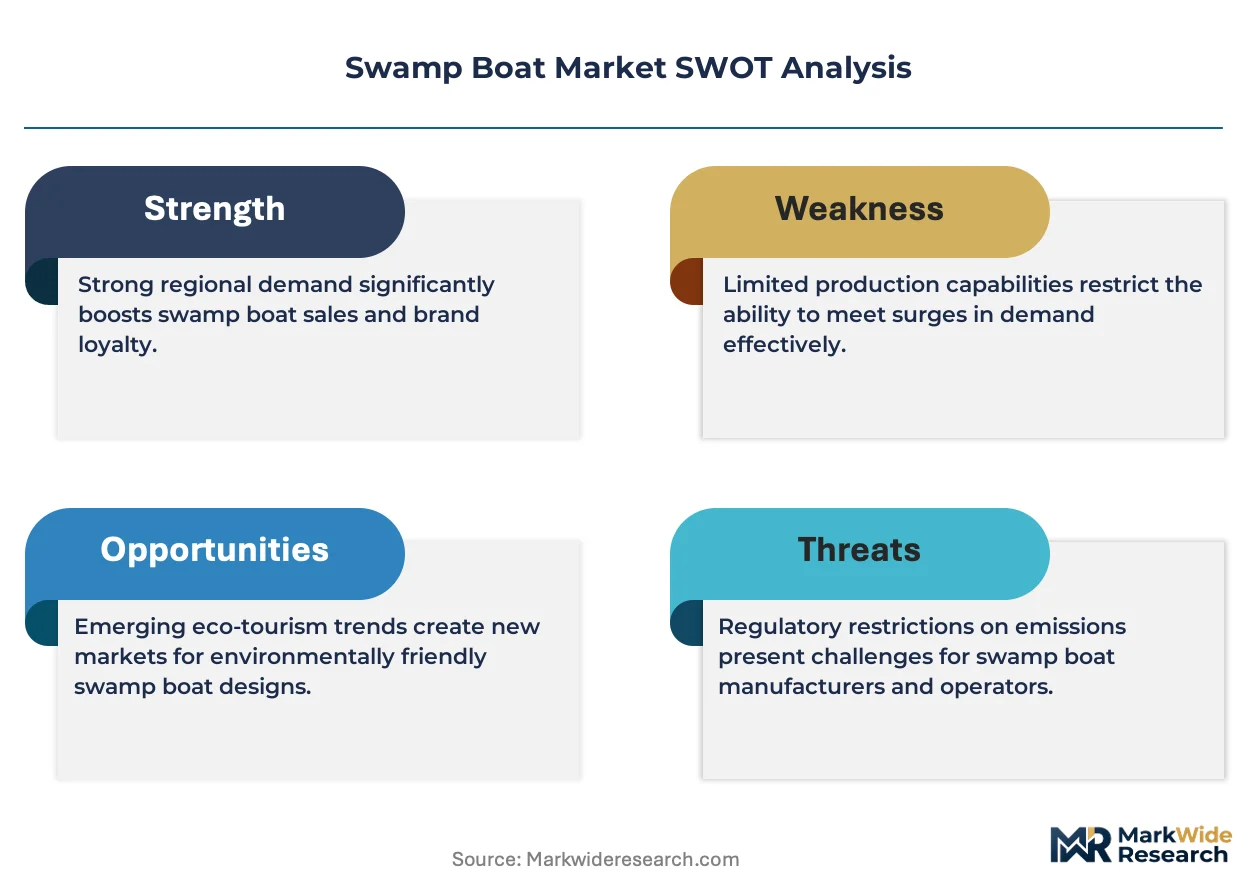
EPA Tier 3 marine emissions standards are compressing engine supplier margins while forcing propulsion architecture redesigns across the shallow-water vessel category. Wildlife management agencies now specify acoustic signature thresholds in procurement documents, redirecting R&D budgets toward electrification pathways.
Growth Catalysts
- Electric Propulsion Mandates:Federal wetland management contracts now prioritize zero-emission propulsion systems for biological monitoring operations, creating specification pull-through from US Fish and Wildlife Service procurement protocols.
- Louisiana Bayou Infrastructure:State-funded waterway maintenance programs are expanding navigable channel networks, extending operational range for commercial fishing and eco-tourism operators across the Atchafalaya Basin.
- Surface-Drive Engineering Advances:Improved mud motor designs with vegetation-cutting capabilities are reducing fouling downtime in hydrilla-choked environments, extending daily patrol hours for law enforcement fleets.
Market Restraints
- Aluminum Sheet Volatility:Hull fabrication depends on 5083 marine-grade aluminum, with price swings tied to energy-intensive smelting operations concentrated in Gulf Coast processing facilities.
- Engine Certification Bottlenecks:EPA compliance testing timelines for small-batch marine powertrains extend 18-24 months, freezing product launch schedules for specialized propulsion manufacturers.
- Airboat Noise Restrictions:Municipal ordinances in Florida's Everglades corridor are capping decibel limits below aircraft-propeller operating thresholds, threatening core airboat functionality in high-value tourism zones.
Strategic Opportunities
- Swamp Restoration Contracts:Army Corps of Engineers ecosystem rehabilitation projects in the Mississippi River Delta require shallow-draft survey platforms with minimal bottom disturbance, opening specification windows for extra-large electric configurations.
- Solar-Assisted Charging Infrastructure:Remote dock installations with photovoltaic arrays are enabling extended-range electric operations beyond grid-connected marinas, penetrating Florida's Ten Thousand Islands backcountry.
- Modular Hull Systems:Interchangeable deck configurations allowing rapid conversion between patrol, research, and cargo layouts are attracting multi-mission buyers from state environmental agencies.
Industry Challenges
- Composite Welding Certification:Aluminum hull fabrication requires specialized MIG/TIG credentials scarce in rural Gulf Coast labor markets, constraining production scaling for emerging manufacturers.
- Propulsion Integration Complexity:Electric drivetrain retrofits into legacy flat-bottom hulls demand custom shaft alignment and battery ballast redistribution, extending shop time and warranty exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Swamp Boat Market |
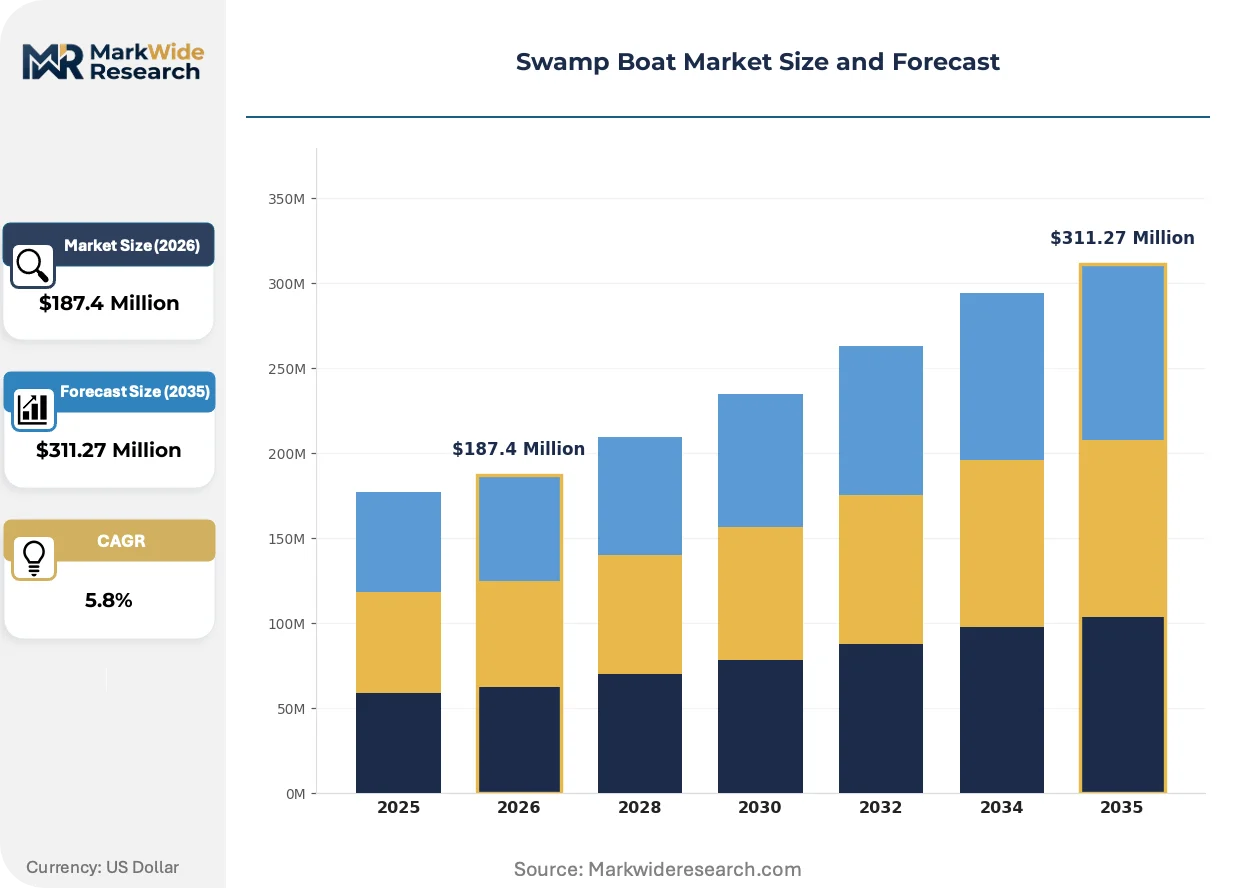
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat-bottomed Boats, Airboats, Jon Boats, Deck Boats End User: Government Agencies, Wildlife Enthusiasts, Recreational Users, Commercial Operators Engine Type: Gasoline Engines, Diesel Engines, Hybrid Engines, Electric Motors Size: Small Boats, Medium Boats, Large Boats, Extra-large Boats |
| Companies Covered | Gator Tail, Mud Buddy, Pro-Drive, Beavertail, Airboat Corporation, Muddy Water Airboats, American Airboat Corporation, Florida Airboats, B & M Airboats, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Swamp Boat Market Evolving Landscape
Propulsion electrification is compressing the competitive set around battery chemistry choices and thermal management architectures. Hull design is converging with autonomous navigation packages. Procurement specifications are hardening around whole-life operating cost models rather than upfront capital expenditure.
Lithium-iron-phosphate battery packs with integrated liquid cooling are automating thermal regulation in high-ambient-temperature wetland environments. Wildlife research divisions at Louisiana State University and Florida Fish and Wildlife Conservation Commission are piloting these systems for extended silent-observation transects. The technology is automating crew fatigue management while compressing maintenance intervals previously consumed by combustion engine servicing.
EPA Tier 3 compliance deadlines for non-road spark-ignition engines are eliminating carbureted powertrain options below 19 kW output. Manufacturers must retool for electronic fuel injection and catalytic aftertreatment, adding cost and complexity to small-boat propulsion. The recreational segment faces the steepest price escalation, with entry-level buyers delaying replacement cycles or migrating to used vessel markets.
State environmental agencies are consolidating fleet procurement through cooperative purchasing agreements, concentrating volume with fewer vendors and demanding standardized maintenance training protocols. Louisiana's Office of State Procurement and Florida's Department of Management Services now coordinate multi-agency buys, displacing fragmented municipal purchasing. The shift is most visible in search-and-rescue fleet renewals across coastal parishes and counties, where interoperability requirements now dominate specification development.
Swamp Boat Market Segmentation
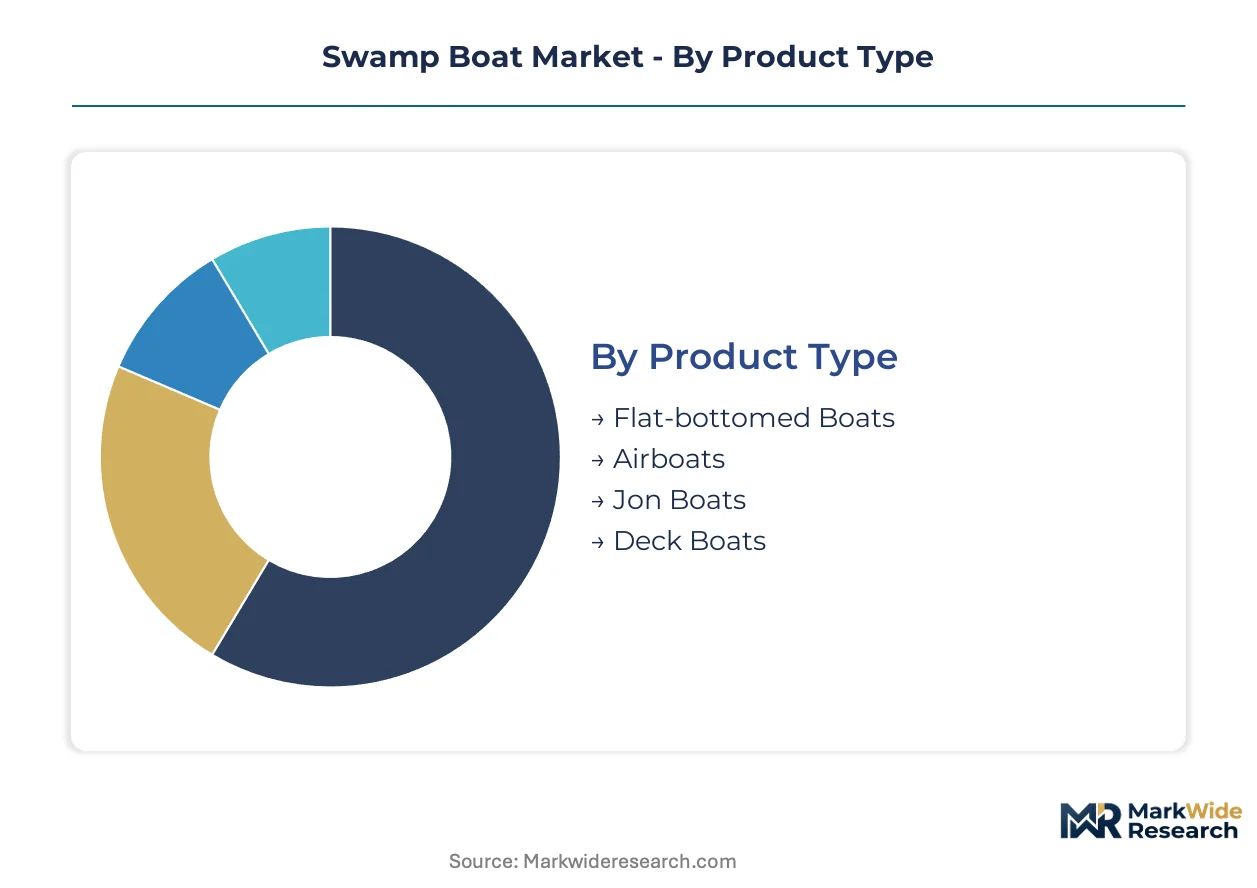
Swamp boat procurement patterns diver sharply across user missions and operating environments. Flat-bottomed hull configurations serve vegetation-dense backwaters where submerged propulsion would foul. Electric drivetrain specifications now appear in federal wetland management contracts, redirecting manufacturer development priorities.
Product Type:
Standalone hull platforms dominate commercial procurement, while modular configurations embed into multi-mission fleet systems. Integration depth varies with operational tempo and vegetation density.
- Flat-bottomed Boats:Welded aluminum hulls with draft below eight inches traverse soft-bottom wetlands without hull damage. Demand concentrates among Louisiana commercial fishing operators navigating timber-laden Atchafalaya Basin channels where submerged vegetation fouls conventional propulsion.
- Airboats:Aircraft-style propellers mounted on elevated cages generate thrust without submerged drive components. Florida Everglades eco-tourism operators specify these for daily passenger loads across hydrilla-choked waters, though municipal noise ordinances now constrain operational zones.
- Jon Boats:Simple riveted or welded aluminum utility hulls with bench seating configurations serve cost-sensitive recreational buyers.
- Deck Boats:Expanded beam width and flat casting platforms accommodate multi-angler layouts for tournament fishing applications.
Flat-bottomed boats lead volumes today; airboats command premium pricing in tourism corridors.
End User:
Procurement sophistication stratifies sharply across customer types, with institutional buyers demanding whole-life cost models and recreational purchasers prioritizing upfront capital thresholds.
- Government Agencies:Federal wetland management contracts through US Fish and Wildlife Service specify acoustic signature thresholds and zero-emission propulsion for biological monitoring. State environmental agencies in Louisiana and Florida now coordinate multi-agency fleet purchases through cooperative procurement agreements.
- Wildlife Enthusiasts:Individual researchers and nature photographers prioritize silent-running electric configurations for extended observation transects without disturbing target species.
- Recreational Users:Weekend anglers and hunters drive volume in small-boat gasoline configurations, though EPA Tier 3 compliance costs are compressing replacement cycles.
- Commercial Operators:Fishing guides and cargo haulers demand surface-drive mud motors for daily operations across debris-heavy channels.
Government agencies anchor premium pricing; wildlife enthusiasts represent the steepest expansion trajectory as research funding increases.
Engine Type:
Propulsion architecture choices now hinge on regulatory compliance timelines rather than pure performance metrics, with electrification pathways diverging from legacy combustion supply chains.
- Electric Motors:Lithium-iron-phosphate battery packs with integrated liquid cooling automate thermal regulation in high-ambient-temperature wetland environments. Louisiana State University wildlife research divisions pilot these for extended silent-observation transects.
- Gasoline Engines:Carbureted powertrains below 19 kW face EPA Tier 3 elimination, forcing retooling toward electronic fuel injection and catalytic aftertreatment.
- Diesel Engines:Compression-ignition architectures persist in extra-large search-and-rescue configurations requiring extended range.
- Hybrid Engines:Dual-mode systems blend combustion range with electric stealth for law enforcement patrol applications.
Gasoline engines retain volume dominance; electric motors are climbing the fastest as federal procurement specifications harden.
Size:
Hull dimension selection tracks mission duration and crew complement requirements, with scale economies concentrating in mid-size commercial configurations.
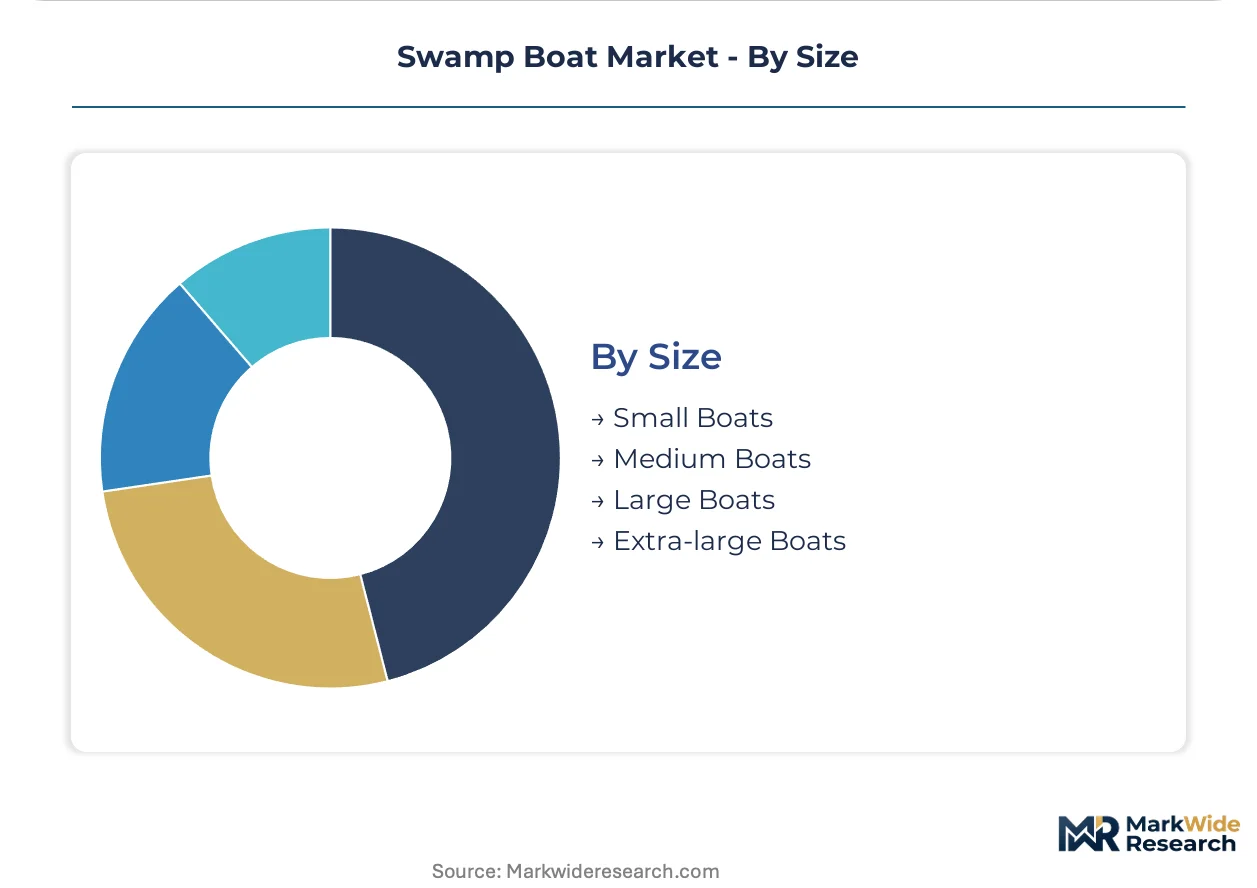
- Small Boats:Single-operator layouts with minimal draft serve backcountry hunters and solo anglers accessing remote launch points.
- Medium Boats:Two-to-four-person capacity with expanded cargo decks supports commercial fishing partnerships and guide services.
- Large Boats:Multi-agency patrol configurations accommodate search-and-rescue teams with medical equipment and diver support.
- Extra-large Boats:Army Corps of Engineers ecosystem rehabilitation projects in the Mississippi River Delta specify these shallow-draft survey platforms with minimal bottom disturbance for precision bathymetric mapping.
Small boats dominate recreational transactions; extra-large configurations capture infrastructure contract premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Welding-certified aluminum fabricators concentrate along the Gulf Coast corridor, anchoring production capacity within a two-hour radius of major wetland systems. This workforce distribution shapes where hull manufacturing scales and where propulsion integration occurs.
United States
Louisiana's bayou regions and Florida's Everglades corridor generate concentrated demand from commercial fishing and eco-tourism operators. EPA Tier 3 marine emissions standards constrain engine specifications for shallow-water vessels operating in these wetlands. Lafayette, Louisiana hosts surface-drive engineering clusters where mud motor manufacturers refine vegetation-cutting propulsion systems.
Canada
Wildlife research stations across the Prairie provinces and Ontario's wetland reserves deploy shallow-draft vessels for waterfowl population surveys. Transport Canada small vessel safety regulations parallel US Coast Guard certification requirements for aluminum hull construction. Manitoba's Interlake region supports seasonal manufacturing operations serving northern lake systems.
Brazil
Pantanal wetland conservation programs and Amazon basin patrol operations drive institutional procurement of flat-bottomed configurations. ANVISA environmental licensing requirements intersect with naval registry protocols for commercial vessel operation. Manaus industrial zones fabricate riveted aluminum hulls for regional cargo transport across flooded forest ecosystems.
Australia
Kakadu National Park management and Queensland coastal wetland research generate specialized demand for low-draft survey platforms. Australian Maritime Safety Authority domestic commercial vessel standards govern hull certification for northern territory operations. Darwin marine fabrication yards supply patrol configurations for crocodile management and flood rescue protocols.
Indonesia
Sumatran peatland restoration projects and Kalimantan swamp agriculture operations require shallow-water transport for equipment and personnel. The country's national environmental ministry issues permits for commercial vessel operation in protected wetland zones. Surabaya shipbuilding clusters adapt flat-bottom designs for tropical vegetation densities and monsoon flood conditions.
Swamp Boat Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the swamp boat category. Welded aluminum hull fabrication demands substantial workshop infrastructure and certified labor pools, while propulsion system integrators operate with lighter asset bases. The competitive set stratifies into three archetypes: vertically integrated hull-and-motor manufacturers, specialized propulsion engineering houses, and regional fabrication shops serving localized wetland systems. Consolidation pressures concentrate among mid-tier hull builders seeking EPA compliance expertise, while technology licensing agreements spread surface-drive innovations across geographic markets.
Within the integrated manufacturing tier, Gator Tail and Pro-Drive exemplify Gulf Coast-based operations that combine hull welding with proprietary propulsion development. Mud Buddy represents the specialized engineering archetype, focusing exclusively on extreme-environment drive systems without captive hull production. These three companies anchor the competitive structure, with Gator Tail and Pro-Drive representing scale-driven positions and Mud Buddy occupying the technical specialization vector. Regional competitors including Beavertail, Airboat Corporation, and American Airboat Corporation fragment the remainder of the market across sub-regional wetland corridors.
| Leading Market Players |
|---|
| Gator Tail |
| Mud Buddy |
| Pro-Drive |
| Beavertail |
| Airboat Corporation |
| Muddy Water Airboats |
| American Airboat Corporation |
| Florida Airboats |
| B & M Airboats |
| Others |
Value Network & Pricing Analysis
Federal wetland management procurement programs anchor pricing power through multi-year fleet contracts, compressing margin flexibility for manufacturers serving institutional buyers while recreational purchasers face sharper sticker shock from EPA compliance costs. The market bifurcates between specification-driven institutional sales and price-sensitive consumer transactions.
Pricing Analysis
Hull-and-motor bundles dominate institutional procurement while unbundled component sales persist in aftermarket channels. Three-tier pricing structure across premium, standard, and economy levels separates extra-large electric survey platforms from mid-size patrol configurations and entry-level gasoline hulls. EPA Tier 3 engine certification costs are intensifying price pressure in the recreational segment, where weekend anglers exhibit the highest sensitivity to upfront capital thresholds.
Supply Chain Analysis
Specialized MIG/TIG welding credentials for 5083 marine-grade aluminum hull fabrication gate supply chain participation, concentrating production capacity in Louisiana, Florida, and Texas Gulf Coast fabrication clusters. Raw material inputs draw from energy-intensive aluminum smelting operations, electronic fuel injection powertrain components, and lithium-iron-phosphate battery cell supply. Single-source vulnerability in certified welder labor pools threatens production scaling. Distribution runs through direct institutional contracting and regional dealer networks serving backcountry launch points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The swamp boat market functions as a stable compounder, with federal ecosystem rehabilitation funding providing durable demand visibility across multi-year procurement cycles.
For Market Incumbents: Acquire specialized welding certification programs and EPA compliance engineering capabilities to consolidate technical talent scarcity. Surface-drive propulsion patents and battery thermal management IP represent critical defensive assets against emerging electric drivetrain specialists. Capacity addition in Lafayette and Mobile fabrication corridors reinforces geographic moats. For New Entrants and Emerging Players: Autonomous navigation packages for precision bathymetric mapping offer a technology-first wedge into Army Corps of Engineers survey contracts. Solar-assisted charging infrastructure for remote dock installations represents the most penetrable white-space target in Florida's Ten Thousand Islands backcountry. Partner with state cooperative purchasing agreements for streamlined institutional access. For Investors and Strategic Acquirers: Defense contractors and environmental engineering conglomerates are the most active acquirer in this space, seeking shallow-water platform capabilities for coastal resilience contracts. Mid-tier hull builders with captive EPA certification expertise represent the optimal acquisition archetype. Watch for lithium-iron-phosphate battery cost curves as the inflection indicator for electric propulsion share acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Propulsion Retrofit Program | EPA Tier 3 compliance deadlines eliminate carbureted options below 19 kW output. |
| Cooperative Procurement Agreement | Louisiana and Florida state agencies consolidate fleet buying through standardized maintenance protocols. |
| Modular Hull System Development | Interchangeable deck configurations attract multi-mission buyers from environmental agencies. |
| Surface-Drive Engineering Licensing | Vegetation-cutting propulsion designs spread across Gulf Coast wetland markets. |
| Solar Charging Infrastructure Deployment | Photovoltaic dock arrays enable extended-range electric operations beyond grid-connected marinas. |
Research Methodology
Bottom-up end-use procurement modeling reconciled against top-down hull fabrication capacity tracking forms the analytical core of this study. Primary interviews with wildlife agency fleet managers, surface-drive engineering directors, aluminum fabrication shop owners, and EPA compliance officers combined with secondary validation from US Fish and Wildlife Service procurement databases, US Coast Guard small vessel safety filings, and state cooperative purchasing agreement records. Triangulation across supply-side certification bottlenecks and demand-side specification evolution ensures coverage integrity.
The input-output matrix maps hull dimension, propulsion architecture, and end-use mission requirements against regional wetland access patterns and regulatory compliance timelines across the modeling period. Segmentation dimensions include product type, engine technology tier, size category, and institutional versus recreational buyer archetype. CAGRs derive from procurement pipeline visibility and replacement cycle compression in the gasoline-powered recreational segment, with battery chemistry cost curves and federal restoration funding appropriations serving as key forecast inputs.
The model holds under steady EPA enforcement timelines and stable aluminum pricing; deviation in welding labor availability or lithium-iron-phosphate supply constraints would shift volume trajectories. Forecasts reflect documented assumptions regarding institutional procurement acceleration and electrification mandate adoption curves. A model refresh is warranted upon material change in Army Corps of Engineers ecosystem rehabilitation appropriations or municipal airboat noise ordinance expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Europe ROV Market
Marine
Marine LED Lights Market
Marine
Global Submarine Market
Marine
Marine Fender Market
Marine
Marine Elevators Market
Marine
Tele-Operated Marine Drone Market
Marine
Europe Recreational Boating Market
Marine
North Sea Offshore Support Vessels Market
Marine
Rigid Inflatable Boats (RIB) Market
Marine
Shipbuilding Market
Marine
Jack-Up Vessels Market
Marine
Global Marine Gearbox Market
Marine
Unmanned Marine Vehicles Market
Marine
Marine AIS Monitoring System Market
Marine
Marine Dynamic Positioning System Market
Marine
Marine Growth Removal Tool Market