
 Sliding Fender Market | 2026-2036
Sliding Fender Market Size, Share, and Industry Trends Forecast 2026-2036
Sliding Fender Market Insights
The EU Green Deal is recalibrating procurement standards across European port authorities, forcing lifecycle emissions into fender selection criteria. Trelleborg Marine & Infrastructure leverages integrated rubber compounding capabilities to dominate premium composite fender supply. Yokohama Rubber Company anchors its position through proprietary pneumatic fender technology developed for ultra-large container vessels. Jerryborg Marine competes on cost-optimized manufacturing scale across Southeast Asian shipyard channels.
A sliding fender is a marine protection device mounted on dock structures or vessel hulls that absorbs kinetic energy during berthing through controlled deformation and lateral displacement, typically rated for reaction forces between 100 and 3,000 kN depending on vessel tonnage. Its primary purpose is preventing structural damage to both ship and quay infrastructure during mooring operations in commercial ports and offshore logistics hubs. Rubber sliding fenders sustain the largest installed base due to proven durability in high-cycle commercial environments, while composite sliding fenders represent the fastest-growing category as ports pursue lighter, corrosion-resistant alternatives with lower maintenance intervals. Foam sliding fenders occupy a specialized niche in recreational and mid-size craft mooring where weight reduction and simple installation outweigh capital cost sensitivity.
EMA's MDR framework and the EU F-Gas Regulation shape material compliance pathways for European port infrastructure investments, while China's GB standards and MEE environmental directives enforce domestic manufacturing quality and recyclability thresholds. The US Coast Guard and OSHA berth safety requirements further constrain product design for North American terminal operators. Stakeholders must monitor how evolving lifecycle assessment mandates alter material substitution timelines and supplier qualification criteria across major port development programs.
Market Dynamics
EU Green Deal mandates on lifecycle emissions are forcing port authorities to retire timber fender systems and source recyclable rubber and composite alternatives, compressing replacement cycles and rewiring supplier qualification criteria across European terminal infrastructure.
Growth Catalysts
- Ultra-large vessel proliferation:Port authorities in Singapore and Rotterdam are expanding berthing capacity to accommodate 24,000+ TEU container ships, requiring fender systems rated for higher reaction forces and extended stroke lengths.
- EU F-Gas Regulation:Restrictions on fluorinated greenhouse gases in manufacturing processes are accelerating adoption of water-based rubber compounding technologies for marine fender production.
- East Asian shipyard concentration:Dense clusters in South Korea's Geoje region and China's Jiangsu and Zhejiang provinces sustain continuous demand for high-cycle commercial fender installations.
Market Restraints
- Natural rubber price volatility:Raw material costs fluctuate with Southeast Asian supply disruptions and climate-induced yield variability, squeezing margin stability for compounders.
- Supplier concentration risk:Integrated rubber compounding capabilities concentrate among a handful of specialty chemical groups, creating bottleneck exposure for premium composite fender supply.
- Timber fender residual stock:Existing timber installations in legacy European ports face extended replacement timelines due to capital budget fragmentation across municipal authorities.
Strategic Opportunities
- Modular composite systems:Lighter, corrosion-resistant fender designs enable retrofit installations in tidal zones where heavy equipment access is restricted, opening underserved maintenance channels.
- Lifecycle assessment integration:EU CSRD reporting requirements create premium positioning for suppliers offering certified carbon footprint documentation alongside product warranties.
- Offshore logistics hub expansion:Floating production and transshipment terminals in West African and Southeast Asian waters require specialized foam and pneumatic fender configurations for dynamic mooring conditions.
Industry Challenges
- Marine polymer engineering talent scarcity:Specialized expertise in rubber-metal bonding and hydrodynamic modeling concentrates among aging workforce cohorts in established manufacturing regions.
- Certification timeline compression:Port authorities demand accelerated type-approval cycles for new fender designs, straining testing laboratory capacity and engineering validation resources.
- Legacy quay structural incompatibility:Pre-stressed concrete berths built for older vessel classes require costly reinforcement modifications to anchor modern high-performance fender systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sliding Fender Market |
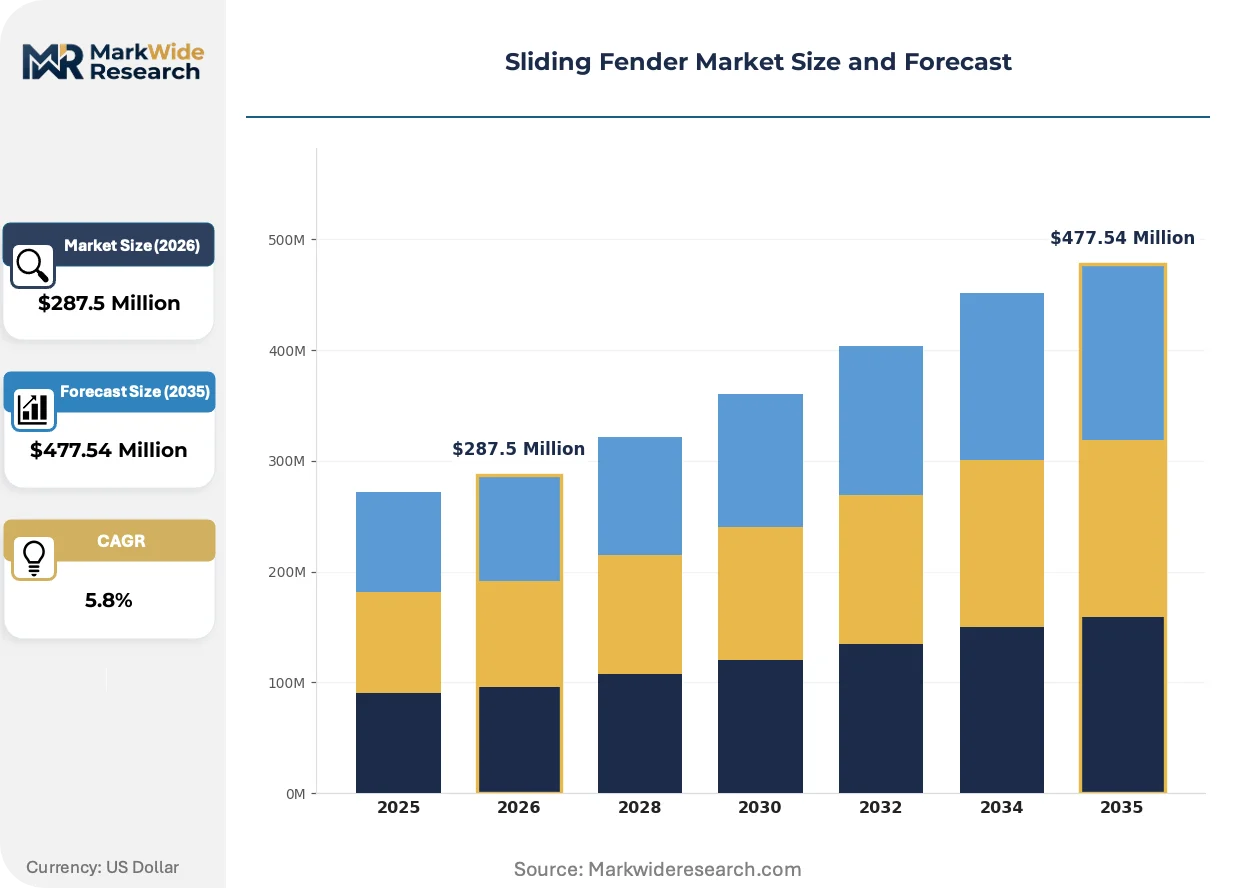
| Market Size in 2026 | $287.5 Million |
| Market Size in 2035 | $477.54 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Timber Sliding Fenders, Rubber Sliding Fenders, Foam Sliding Fenders, Pneumatic Sliding Fenders, Composite Sliding Fenders Material Composition: Natural Rubber, Synthetic Rubber, Polyurethane, EVA Foam, Marine Grade Timber Application: Ship Berthing, Port Infrastructure, Dock Protection, Offshore Platforms, Boat Mooring End User Type: Shipyards, Port Authorities, Ship Repair Facilities, Offshore Contractors, Harbor Agencies |
| Companies Covered | YT Marine Fender, Jerryborg Marine, Trelleborg Marine & Infrastructure, Polyform US, Fendertec, ShibataFenderTeam Group, Marine Fenders International, Fender Innovations, Yokohama Rubber Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sliding Fender Market Trends and Innovations
Material science breakthroughs and regulatory disclosure mandates are converging to transform how port infrastructure specifies, procures, and maintains marine protection systems over multi-decade asset horizons.
Advanced rubber compounding with recycled content is rewriting procurement specifications for commercial fender installations. Port authorities in the Netherlands and Belgium now require minimum recycled rubber percentages in public tender documents. This material shift is compressing demand for virgin compound formulations and elevating suppliers with integrated recycling capabilities.
REACH substance restrictions on polycyclic aromatic hydrocarbons in rubber manufacturing are forcing reformulation of traditional fender compounds. European compounders must certify PAH levels below regulatory thresholds for products installed in EU waters. Composite fender categories gain relative advantage as they bypass these hydrocarbon constraints entirely.
Long-term performance contracting is displacing traditional capital purchase models for major terminal operators. Port authorities in Hamburg and Antwerp now contract fender system availability over 15-year terms rather than owning assets outright. This shift concentrates supplier risk on durability forecasting and compresses pricing transparency across the value chain.
Sliding Fender Market Segmentation
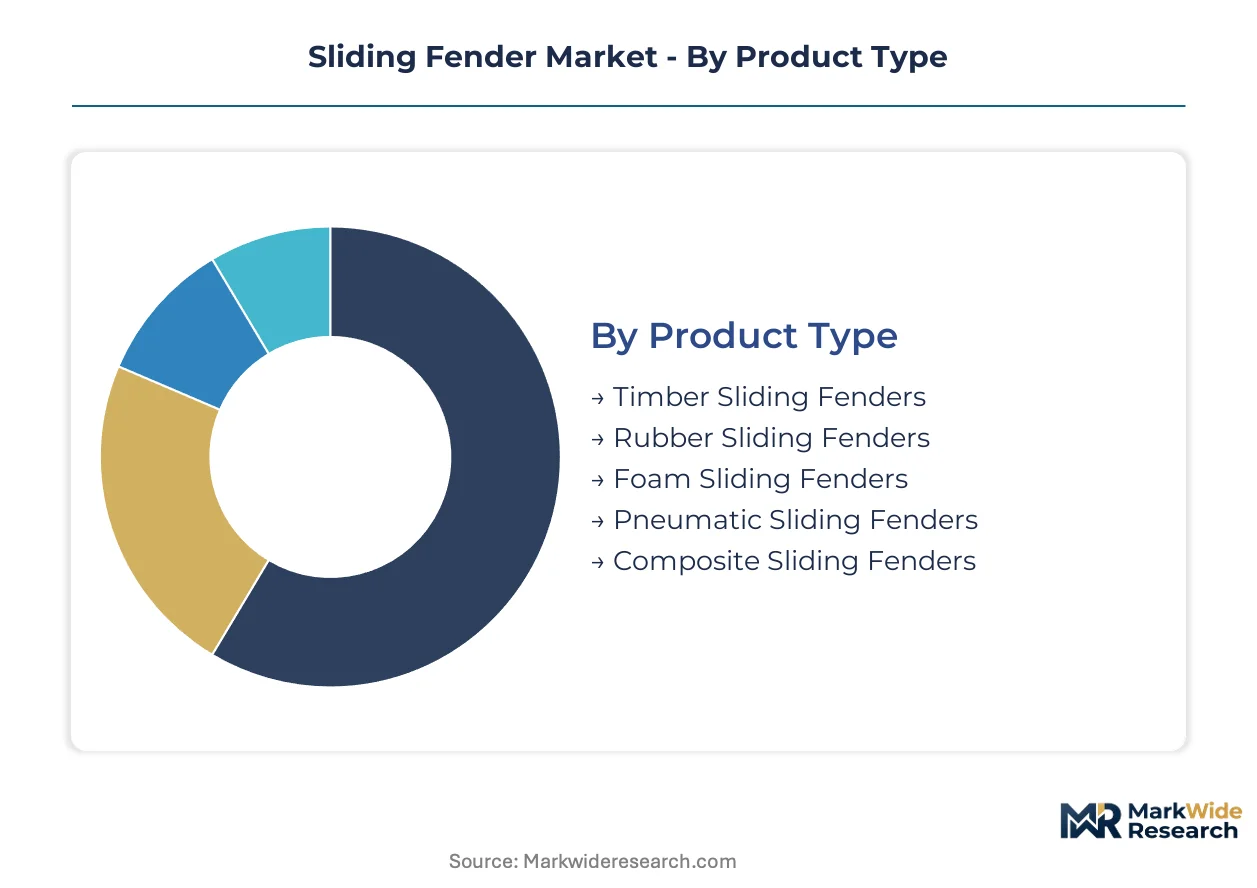
Sliding fender procurement follows distinct technical and operational logics across vessel classes, infrastructure types, and regulatory environments. Specification engineers weight reaction force ratings, stroke absorption, and lifecycle maintenance differently depending on berth throughput and vessel size distribution.
Product Type:
Reaction force capacity and deformation mechanics separate commercial-grade systems from specialized configurations.
- Rubber Sliding Fenders:Engineered from high-tensile natural and synthetic rubber compounds with steel reinforcement plates, these systems absorb 100-3,000 kN reaction forces through controlled compression and shear deformation. Demand concentrates in Singapore's Tuas megaport and Rotterdam's Maasvlakte expansion, driven by 24,000+ TEU vessel calls requiring extended stroke lengths and high-cycle durability.
- Composite Sliding Fenders:Hybrid constructions combining fiberglass-reinforced polymer shells with elastomeric cores deliver corrosion resistance and 40-60% weight reduction versus rubber equivalents. Jiangsu and Zhejiang province shipyards specify these for tidal zone installations where crane access is restricted, with EU Green Deal procurement mandates accelerating substitution for timber systems.
- Pneumatic Sliding Fenders:Yokohama-type floating systems using pressurized air chambers for energy absorption in dynamic mooring conditions.
- Foam Sliding Fenders:Closed-cell polyethylene or EVA cores encased in polyurethane skin for recreational craft and mid-size vessel protection.
- Timber Sliding Fenders:Traditional hardwood installations retained in legacy European municipal ports facing capital budget fragmentation.
Rubber sliding fenders lead on installed scale; composite sliding fenders lead on specification momentum.
Material Composition:
Raw material selection traces regulatory compliance pathways and supply security priorities.
- Natural Rubber:Sourced predominantly from Southeast Asian plantations, this material delivers superior elasticity and fatigue resistance for high-cycle commercial berths. Price volatility from Thai and Indonesian supply disruptions creates margin pressure for compounders serving South Korean Geoje shipyard clusters.
- Synthetic Rubber:Styrene-butadiene and polyisoprene formulations offer supply security alternatives with consistent performance specifications. Chinese GB standards and MEE environmental directives enforce recyclability thresholds that favor domestically produced synthetic compounds in Jiangsu and Shandong manufacturing bases.
- Polyurethane:Cast elastomer systems for specialized high-wear applications requiring abrasion resistance.
- EVA Foam:Lightweight closed-cell material for recreational and temporary mooring configurations.
- Marine Grade Timber:Hardwood species facing phased retirement under EU sustainable procurement mandates.
Natural rubber dominates volume throughput; synthetic rubber is gaining share fastest on supply security and regulatory alignment.
Application:
Operational intensity and vessel traffic patterns dictate fender system specification tiers.
- Ship Berthing:High-energy absorption systems rated for container vessel impact velocities and displacement tonnages, with Singapore and Rotterdam port authorities specifying modular replacement capabilities for 24,000+ TEU classes.
- Port Infrastructure:Quay wall and dolphin installations requiring corrosion-resistant anchoring systems for multi-decade asset horizons.
- Dock Protection:Secondary fender lines for vessel maneuvering zones and tug-assisted positioning.
- Offshore Platforms:Dynamic positioning support for floating production and transshipment terminals in West African waters.
- Boat Mooring:Low-reaction systems for recreational marinas and small-craft facilities.
Ship berthing commands specification intensity; offshore platforms show steepest expansion trajectory on floating logistics hub development.
End User Type:
Procurement authority and technical capability shape vendor relationship structures.
- Port Authorities:Municipal and state-owned terminal operators in Hamburg and Antwerp contracting availability-based service agreements over 15-year terms rather than capital purchase, concentrating supplier risk on durability forecasting.
- Shipyards:Construction and repair facilities in South Korea's Geoje region and China's coastal provinces sustaining continuous demand for new-installation fender systems.
- Ship Repair Facilities:Maintenance-focused operators requiring rapid replacement capabilities and standardized mounting interfaces.
- Offshore Contractors:Floating production specialists specifying dynamic mooring configurations for West African and Southeast Asian waters.
- Harbor Agencies:Municipal authorities managing recreational and small-commercial vessel infrastructure.
Port authorities lead on contract value concentration; shipyards lead on installation velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sliding fender manufacturing originated in Japanese shipyards during the 1960s containerization boom, then migrated to South Korean and Chinese coastal provinces as East Asian shipbuilding consolidated. Port infrastructure investment patterns now trace three distinct regulatory and industrial ecosystems.
China
Jiangsu and Zhejiang province shipyards sustain the densest fender installation velocity globally, driven by state-owned port expansion along the Yangtze River Delta. GB standards and MEE environmental directives enforce domestic recyclability thresholds that favor synthetic rubber compounds in Shandong manufacturing bases. Qingdao and Nantong clusters specialize in composite fender production for tidal zone retrofit applications.
South Korea
Geoje region shipbuilders specify high-reaction rubber systems for ultra-large container vessels, with Hyundai Heavy Industries and Samsung Heavy Industries driving continuous replacement cycles. The country's national maritime regulator enforces strict type-approval protocols for fender systems in commercial berths. Busan-Ulsan corridor manufacturers dominate pneumatic fender exports to Southeast Asian transshipment terminals.
Singapore
Tuas megaport development commands modular fender systems rated for 24,000+ TEU vessel calls, with port authority procurement favoring suppliers offering lifecycle carbon documentation. The Maritime and Port Authority's sustainable infrastructure mandates accelerate composite substitution for legacy timber installations. Jurong Island petrochemical terminals require specialized foam configurations for dynamic mooring of product tankers.
Netherlands
Rotterdam's Maasvlakte expansion specifies extended-stroke fender systems for mega-container vessel berthing, with port authority contracts shifting to 15-year availability-based service agreements. EU Green Deal procurement standards require minimum recycled rubber percentages in public tenders. Delfzijl and Vlissingen secondary terminals drive demand for lightweight composite retrofits in tidal access zones.
Germany
Hamburg port authority pioneered long-term performance contracting for fender system availability, concentrating supplier risk on durability forecasting. REACH substance restrictions on polycyclic aromatic hydrocarbons force compound reformulation for rubber fenders in EU waters. Bremerhaven and Wilhelmshaven container terminals anchor specification intensity for high-cycle commercial installations.
Sliding Fender Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across distinct capability tiers. Integrated rubber compounders with captive polymer processing dominate premium supply, while specialized fabricators compete on modular system customization. Three archetypes define competitive positioning: integrated chemical conglomerates controlling upstream compounding, regional shipyard-channel specialists optimizing manufacturing scale, and niche composite engineers targeting retrofit applications. Dominant competitive moves include backward integration into recycled rubber sourcing and geographic expansion through port authority framework agreements.
Within the integrated chemical tier, Trelleborg Marine & Infrastructure and Yokohama Rubber Company occupy positions defined by proprietary compounding capabilities and pneumatic technology heritage respectively. Jerryborg Marine exemplifies the scale-driven specialist archetype, competing through cost-optimized manufacturing across Southeast Asian shipyard channels. These three anchors demonstrate how supplier qualification criteria increasingly weight lifecycle emissions documentation alongside traditional performance specifications.
| Leading Market Players |
|---|
| YT Marine Fender |
| Jerryborg Marine |
| Trelleborg Marine & Infrastructure |
| Polyform US |
| Fendertec |
| ShibataFenderTeam Group |
| Marine Fenders International |
| Fender Innovations |
| Yokohama Rubber Company |
| Others |
Pricing and Supply Chain Analysis
Captive rubber compounding capabilities anchor supply positioning and pricing power for integrated chemical conglomerates serving premium composite fender demand, while outsourced manufacturing networks in Southeast Asian shipyard channels compete on cost-optimized scale for standard-grade installations. This integration choice separates lifecycle-carbon-certified suppliers commanding availability-based contracts from commodity compounders facing margin compression.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling. Premium tiers attach to EU Green Deal-compliant lifecycle documentation and 15-year performance warranties, while economy tiers serve municipal harbor agencies with capital purchase constraints. Cost compression in standard-grade rubber compounds is intensifying because of Thai and Indonesian natural rubber supply disruptions. Municipal port authorities in legacy European markets show highest price sensitivity; Singapore's Tuas megaport authority shows lowest sensitivity due to availability-based contracting models.
Supply Chain Analysis
Domestic-content mandates in China's GB standards and MEE environmental directives are reshaping sourcing patterns toward Shandong and Jiangsu synthetic rubber manufacturing bases. Geographic supply concentrates in China, South Korea, and Thailand, with raw material dependencies drawing from Southeast Asian natural rubber plantations, Chinese synthetic polymer production, and Japanese specialty chemical additives. Single-source vulnerability concentrates in integrated rubber-metal bonding capabilities among aging workforce cohorts in established manufacturing regions. Distribution runs through shipyard-channel specialists and port authority framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU Green Deal lifecycle emissions mandates are forcing replacement cycles and rewiring supplier qualification criteria across European terminal infrastructure.
For Market Incumbents: Acquire recycled rubber processing capabilities to defend against REACH substance restrictions and PAH compliance thresholds that disadvantage virgin compound formulations. Secure backward integration into tire-recycling feedstock streams in Netherlands and Belgium port procurement zones. Cement port authority framework agreements in Hamburg and Antwerp before long-term performance contracting models fully mature. For New Entrants and Emerging Players: Tidal zone retrofit specialists represent the most penetrable buyer archetype for modular composite systems requiring lightweight installation without heavy crane access. Target secondary European terminals in Delfzijl and Vlissingen where EU Green Deal timber replacement mandates create specification momentum. Lead with lifecycle assessment documentation and rapid type-approval capabilities to bypass incumbent certification timelines. For Investors and Strategic Acquirers: Roll-up economics work for regional composite fabricators because port authority procurement is fragmenting across municipal budget authorities and creating sub-scale vendors. Five-to-ten-year viability hinges on carbon-border-adjustment alignment and circular material certification penetration. Watch for accelerated type-approval demand as a signal that testing laboratory capacity constraints are creating acquisition premiums for validated engineering resources.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Rubber Sourcing | REACH PAH restrictions and EU Green Deal procurement standards favor compounders with captive tire-recycling feedstock in Netherlands and Belgium. |
| Long-term Performance Contracting | Hamburg and Antwerp port authorities are displacing capital purchase models with 15-year availability agreements concentrating supplier risk. |
| Modular Composite System Development | Lightweight corrosion-resistant designs enable retrofit installations in tidal zones where heavy equipment access is restricted across European secondary terminals. |
| Geographic Expansion via Framework Agreements | Singapore's Tuas megaport and Rotterdam's Maasvlakte expansion create anchor demand for suppliers offering certified carbon footprint documentation. |
| Rapid Type-Approval Capability Investment | Port authority demands for accelerated certification cycles strain testing laboratory capacity and create defensive moats for validated engineering resources. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with port authority procurement directors, shipyard specification engineers, rubber compound technical directors, and marine polymer R&D leads with secondary validation. Customs and trade data, port authority tender documentation, SEC filings from listed chemical conglomerates, and national maritime regulator type-approval databases anchored the quantitative foundation. Bottom-up installation velocity estimates across Jiangsu, Zhejiang, and Geoje shipyard clusters triangulated against top-down port infrastructure investment forecasts.
Historical reference periods anchored the projection horizon to documented replacement cycles and new-build berthing capacity expansion across the analysis window. Segmentation dimensions modeled include product type tier, material composition grade, application intensity, and end-user procurement authority structure. CAGRs derived from vessel size class proliferation curves and regulatory substitution timelines. Forecast inputs incorporated ultra-large container vessel deployment schedules and EU CSRD reporting requirement phase-ins.
Underlying measurement precision varies by segment; composite sliding fender specification momentum and pneumatic system export flows carry tighter precision than timber fender residual stock estimates. Forecasts reflect assumptions on natural rubber price stabilization and REACH enforcement consistency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Global Marine Gearbox Market
Marine
Marine Chronometers Market
Marine
Integrated All-Electric Propulsion System for Ships Market
Marine
Integrated Bridge System for Ships Market
Marine
Autonomous Ships Market
Marine
GCC ROV Market
Marine
Marine Base Steering Gear Market
Marine
Boat Ladder Market
Marine
Marine Auxiliary Engine Market
Marine
Boat Steering Systems Market
Marine
Military Marine Engine Market
Marine
Hydrofoil Market
Marine
Global Discount-Marine Trenchers Market
Marine
Marine Chartplotter Market
Marine
Marine Shackle Market
Marine
Marine Pipes Market