
 Sea Skimmer Market | 2026-2036
Sea Skimmer Market Size, Share, and Industry Trends Forecast 2026-2036
Sea Skimmer Market Analysis
Propulsion miniaturization is narrowing the performance gap between turbojet and ramjet sea skimmers for terminal attack profiles. MBDA leverages European supply chain integration to sustain production throughput for coastal defense batteries. Saab AB anchors Nordic maritime patrol requirements through its RBS15 family, while BrahMos Aerospace dominates Indo-Pacific hypersonic skimmer development with Indo-Russian joint manufacturing.
Sea skimmers are guided munitions or unmanned aerial vehicles engineered to fly within ten meters of the water surface, exploiting radar clutter and terrain masking to evade detection during terminal approach phases. Fixed-wing architectures currently occupy the majority of defense procurement budgets due to proven range-payload economics, though hybrid propulsion configurations are capturing investment as navies demand multi-mission flexibility across surveillance and strike roles. Sensor fusion technology is deepening platform autonomy, reducing operator burden in contested electromagnetic environments where remote-controlled links face jamming.
The U.S. Department of Defense, through NAVAIR and OSD R&E, shapes platform requirements via the Navy Integrated Fire Control-Counter Air architecture and emerging unmanned systems roadmaps. European procurement aligns with OCCAR coordination and national industrial base protections under EU defense fund guidelines. Stakeholders must monitor how counter-skimmer directed energy programs alter survivability requirements and force design trade-offs between speed and stealth.
Market Dynamics
The distributed maritime operations doctrine is fragmenting platform requirements across multiple threat axes, forcing suppliers to reconcile low-observable signatures with hypersonic terminal velocities in single-weapon architectures.
Growth Catalysts
- Indo-Pacific Theater Prioritization:Contested chokepoint defense is accelerating procurement cycles for coastal batteries in Vietnam, Philippines, and Indonesia.
- EU Defense Fund Alignment:OCCAR coordination mechanisms are streamlining cross-border acquisition of modular sea skimmer systems for NATO littoral readiness.
- Sensor Fusion Maturation:Autonomous terminal guidance algorithms are reducing operator dependency in GPS-denied electromagnetic environments.
Market Restraints
- Rare Earth Magnet Supply Concentration:Neodymium and samarium procurement bottlenecks in Chinese processing facilities constrain solid-fuel motor production scalability.
- Technical Limitation in Sea State Tolerance:Wave-height restrictions above Sea State 5 degrade terminal accuracy for subsonic architectures.
- ITAR Regulatory Friction:U.S. State Department export licensing timelines extend delivery schedules for allied coastal defense programs by 18-24 months.
Strategic Opportunities
- Underpenetrated Nordic Markets:Norway and Finland are expanding Arctic-capable mobile launcher procurement for contested northern approaches.
- Technology Convergence:Integration of loitering munition architectures with anti-ship profiles is creating multi-mission platform demand.
- Indian PLI Scheme Tailwinds:Domestic manufacturing incentives for precision-guided munitions are attracting joint venture structures for BrahMos derivative production.
Industry Challenges
- Systems Integration Talent Scarcity:Cross-domain expertise spanning aerodynamics, RF engineering, and maritime targeting algorithms commands premium compensation.
- Legacy Platform Interoperability:NATO STANAG 4569 compliance requirements complicate integration with pre-2010 fire control networks.
- Hypersonic Thermal Protection Certification:Extended timeline for airframe material qualification under MIL-STD-810H environmental testing protocols delays fielding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sea Skimmer Market |
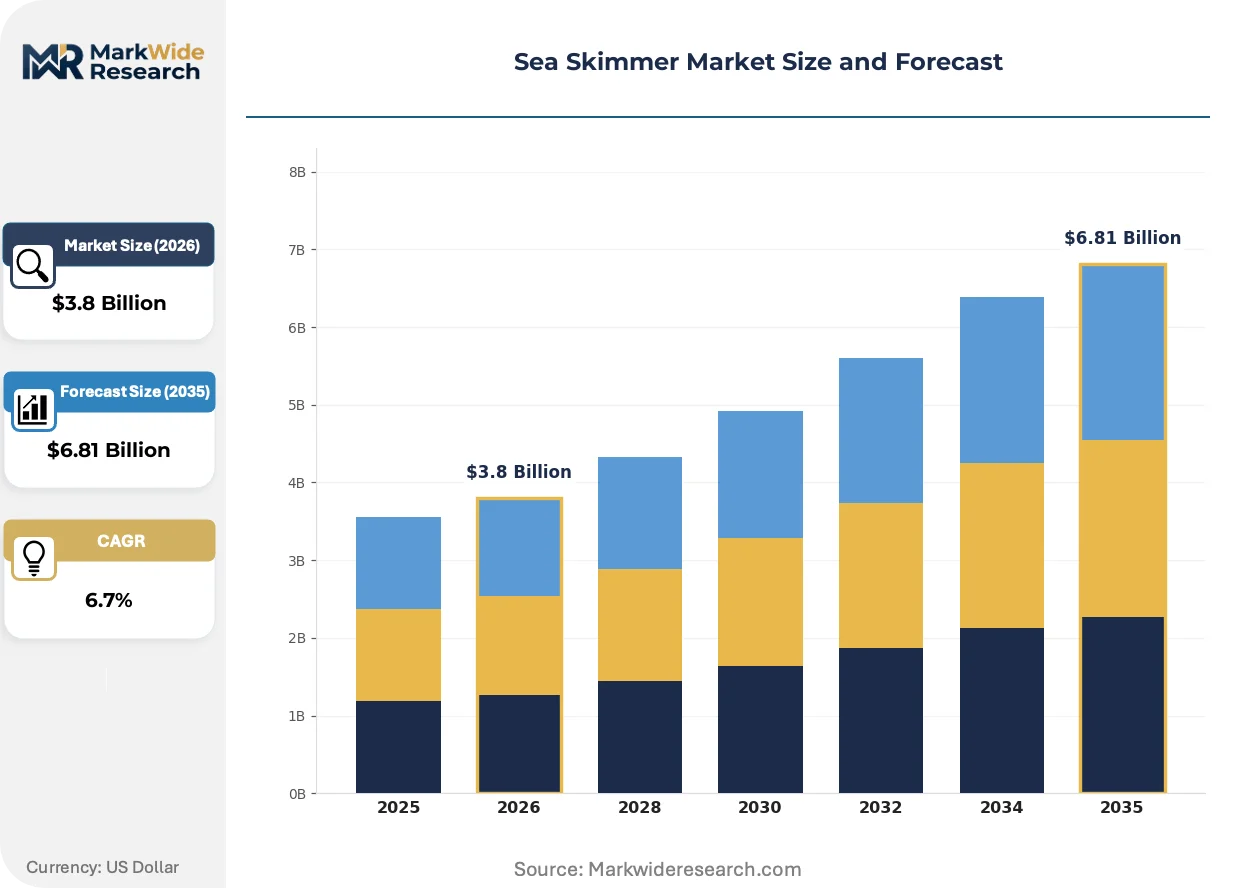
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing, Multirotor, Hybrid, Cargo Technology: Autonomous Navigation, Remote-Controlled, AI Integration, Sensor Fusion Application: Environmental Monitoring, Search and Rescue, Surveillance, Transport End User: Government Agencies, Environmental Organizations, Private Companies, Research Institutions |
| Companies Covered | MBDA, Saab AB, Israel Aerospace Industries Ltd, RTX Corporation, Northrop Grumman Corporation, Boeing Company, BrahMos Aerospace, Kongsberg Gruppen AS, Raytheon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sea Skimmer Market Emerging Trajectories
Propulsion architecture selection is becoming the decisive design variable as turbojet efficiency curves intersect with ramjet thrust density at critical mission profiles.
Ramjet-integrated boost-sustain configurations are collapsing the historical trade-off between cruise efficiency and terminal sprint capability. Naval procurement offices in Australia and Japan are specifying dual-mode propulsion for next-generation coastal defense batteries. The performance envelope compression is eliminating pure turbojet architectures from contested littoral requirements.
EU AI Act risk classification frameworks are mandating human-in-the-loop verification for autonomous target classification algorithms. MBDA and Saab AB are restructuring software development workflows to accommodate explainability audit requirements. European naval procurement is experiencing 12-18 month program delays while certification pathways stabilize.
Consolidated fleet procurement is displacing national siloed acquisition across Five Eyes navies. The U.S. Navy's NAVAIR is harmonizing specifications with Royal Australian Navy and Royal Canadian Navy requirements through AUKUS Pillar Two structures. Indo-Pacific theater coordination is the primary beneficiary of this standardization push.
Sea Skimmer Market Segmentation
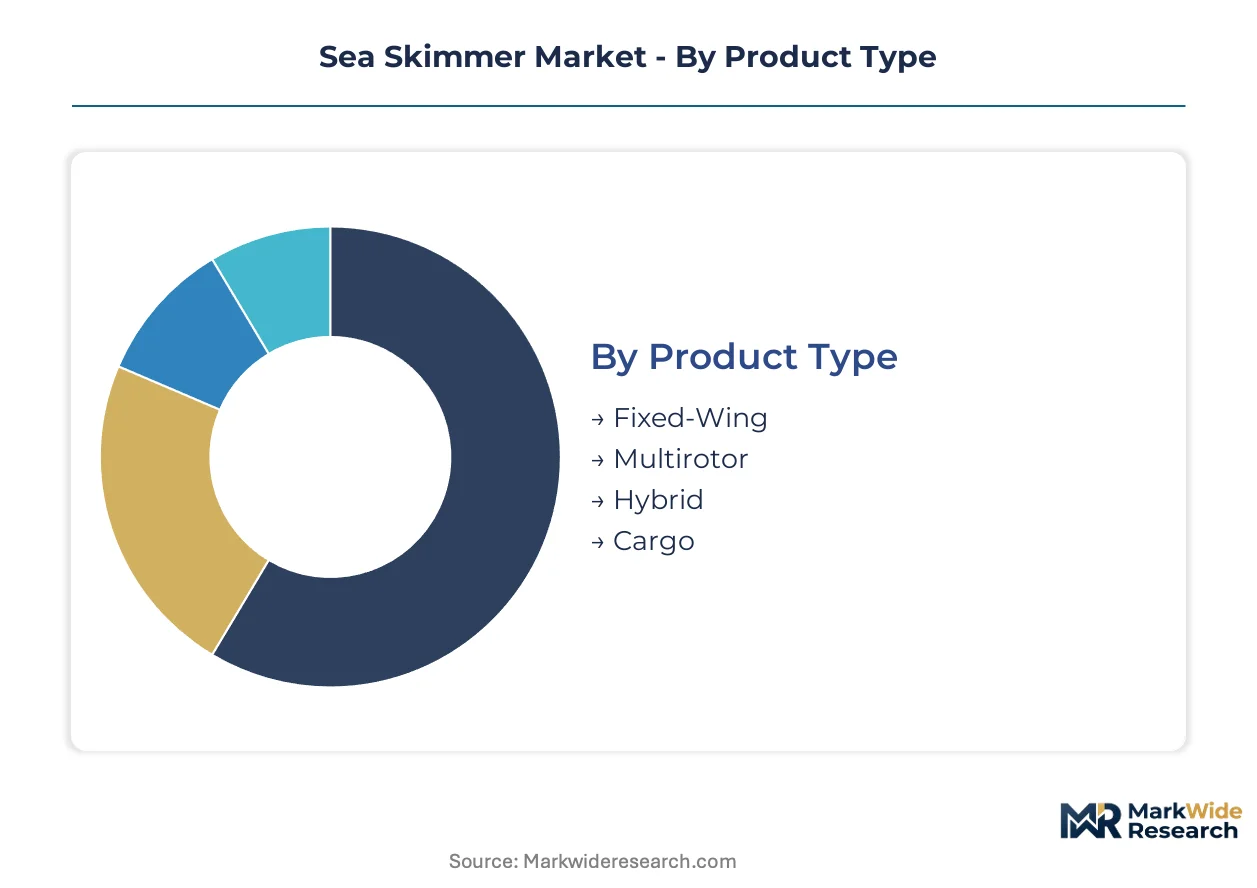
Segmentation in the Sea Skimmer Market reveals how mission profiles dictate platform architecture trade-offs. Defense procurement offices and commercial operators prioritize different performance envelopes, creating distinct supply chain and service requirements across each category.
Product Type:
After-sales service intensity varies sharply by airframe complexity, with multirotor platforms demanding frequent component replacement and fixed-wing systems requiring specialized depot-level maintenance.
- Fixed-Wing:Aerodynamic designs with rigid lifting surfaces optimize range-payload economics for long-endurance maritime patrol. Procurement concentrates in littoral defense batteries across Vietnam, Indonesia, and the Philippines where coastal chokepoint surveillance drives demand. Thermal protection and corrosion-resistant coatings extend field service intervals.
- Multirotor:Vertical takeoff and landing architectures enable dispersed launch from small-deck vessels without catapult systems. Search and rescue operators in Nordic waters favor these platforms for rapid deployment in Arctic conditions. Battery-swapping logistics and motor replacement cycles generate recurring revenue streams for service providers.
- Hybrid:Combines fixed-wing cruise efficiency with multirotor landing flexibility. Emerging demand from customs enforcement agencies requiring runway-independent operations.
- Cargo:Heavy-lift configurations for ship-to-shore logistics in contested environments. Limited procurement to date; development programs active in Australia and Japan.
Fixed-Wing holds the largest share; momentum sits with Hybrid architectures as operators seek operational flexibility without dedicated infrastructure.
Technology:
Cost tier stratification separates premium autonomous systems from baseline remote-controlled platforms, with AI Integration commanding price multiples due to software development and certification overhead.
- Autonomous Navigation:GPS-denied waypoint following using inertial measurement units and terrain-relative navigation. Coastal defense batteries in the Indo-Pacific specify these capabilities for operations in jammed electromagnetic environments. Certification complexity under EU AI Act frameworks extends development timelines.
- Remote-Controlled:Direct operator link via RF or satellite relay for real-time target engagement. Dominates legacy fleet upgrades where budget constraints limit platform replacement. Vulnerability to electronic warfare drives gradual displacement in frontline procurement.
- AI Integration:Machine learning-based target classification and threat prioritization algorithms. MBDA and Saab AB restructuring development workflows for explainability audit compliance.
- Sensor Fusion:Multi-spectral data integration from radar, electro-optical, and signals intelligence payloads. Reduces operator cognitive burden in cluttered maritime domains.
Remote-Controlled retains installed base dominance; Sensor Fusion is expanding most quickly as navies prioritize reduced manning requirements.
Application:
Application segmentation tracks customer procurement authority, with defense budgets funding surveillance and search and rescue while environmental monitoring relies on civil agency appropriations.
- Surveillance:Continuous maritime domain awareness for exclusive economic zone enforcement and threat early warning. The U.S. Navy's distributed maritime operations doctrine fragments requirements across multiple threat axes. Platform specifications harmonize through AUKUS Pillar Two coordination with Australia and Canada.
- Search and Rescue:Rapid response to maritime distress with thermal imaging and emergency supply delivery. Norwegian and Finnish Arctic-capable procurement expanding mobile launcher networks for northern approaches.
- Environmental Monitoring:Oil spill detection, marine mammal tracking, and pollution surveillance. European Space Agency coordination with national coast guards standardizing sensor payloads.
- Transport:Logistics resupply to isolated platforms and vessels. Experimental programs in Japan exploring autonomous cargo delivery to remote island installations.
Surveillance commands procurement volume; Search and Rescue is gaining share fastest as climate-related maritime incidents intensify.
End User:
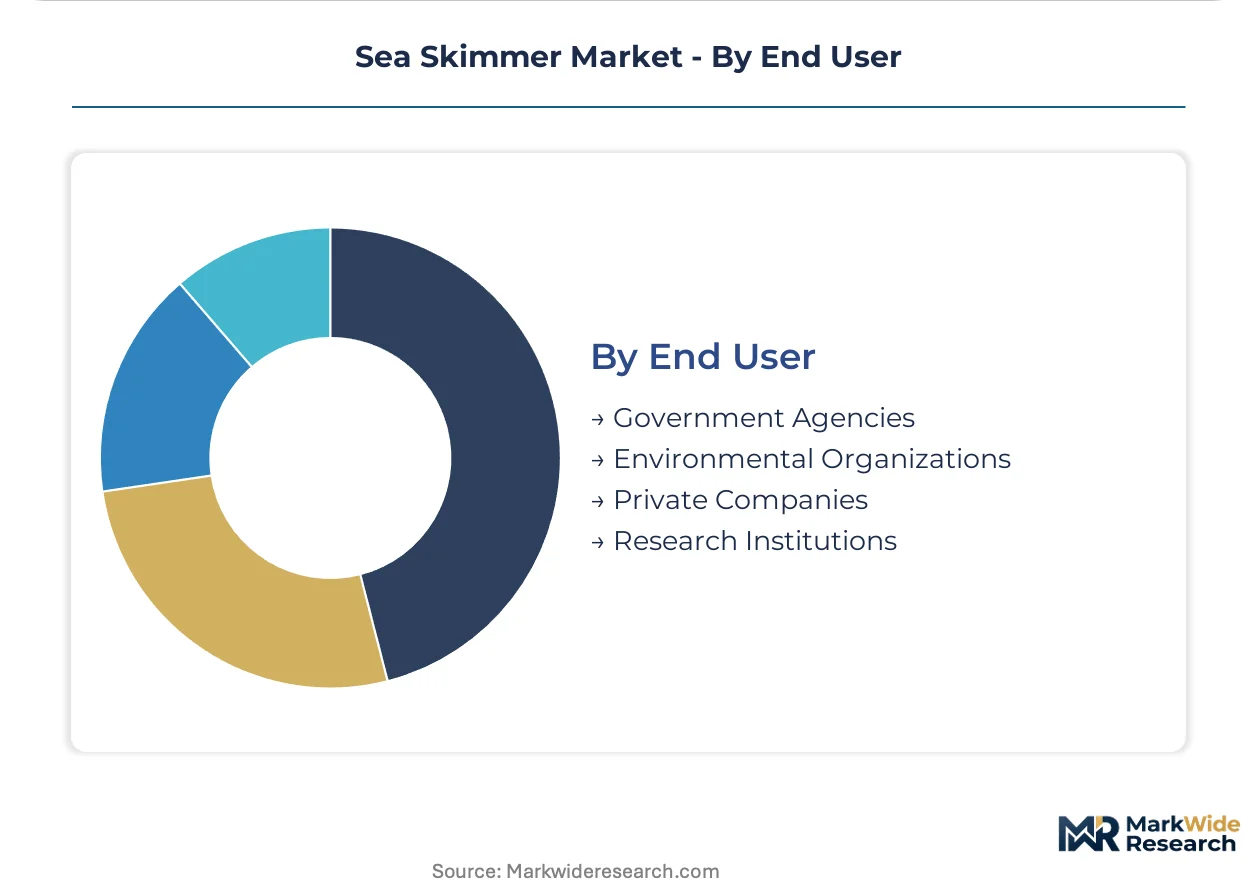
Customer type determines contracting mechanisms, with government agencies utilizing defense procurement regulations and research institutions operating under grant-funded acquisition constraints.
- Government Agencies:Naval, coast guard, and customs enforcement procurement through formal acquisition frameworks. India's PLI scheme for precision-guided munitions attracting joint venture structures for domestic manufacturing.
- Private Companies:Offshore energy operators and shipping lines purchasing for facility security and logistics. Compliance with International Maritime Organization guidelines for autonomous system deployment.
- Environmental Organizations:Non-governmental conservation groups conducting marine ecosystem monitoring. Grant-dependent funding limits fleet scale and platform sophistication.
- Research Institutions:University and national laboratory programs advancing propulsion and guidance technologies. Dual-use development pathways transitioning innovations to defense applications.
Government Agencies anchor procurement value; Private Companies show steepest expansion trajectory as commercial maritime operators adopt autonomous platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swedish defense exports supply Nordic coastal batteries while Indo-Pacific navies absorb the majority of BrahMos Aerospace production from Indo-Russian joint manufacturing facilities.
United States
NAVAIR specifications through the Navy Integrated Fire Control-Counter Air architecture drive distributed maritime operations procurement. The Department of Defense shapes platform requirements via unmanned systems roadmaps and counter-skimmer directed energy programs. San Diego and Washington State clusters concentrate systems integration talent for autonomous terminal guidance development.
India
Domestic manufacturing incentives under the PLI scheme for precision-guided munitions attract joint venture structures for BrahMos derivative production. The Ministry of Defence accelerates coastal defense battery procurement for contested chokepoint protection. Bengaluru and Hyderabad anchor hypersonic skimmer development with DRDO laboratory coordination.
Sweden
Saab AB anchors Nordic maritime patrol requirements through RBS15 family sustainment and Arctic-capable mobile launcher networks. OCCAR coordination mechanisms align national industrial base protections with EU defense fund guidelines. Linköping concentrates aerodynamic and RF engineering expertise for sensor fusion integration.
Australia
AUKUS Pillar Two structures harmonize specifications with the U.S. Navy and Royal Canadian Navy for Indo-Pacific theater coordination. The Royal Australian Navy specifies dual-mode propulsion for next-generation coastal defense batteries. Adelaide and Perth clusters focus on ramjet-integrated boost-sustain configuration testing.
Japan
METI procurement offices specify dual-mode propulsion systems for contested littoral requirements while eliminating pure turbojet architectures. Experimental programs explore autonomous cargo delivery to remote island installations. Nagoya and Kobe concentrate thermal protection material qualification under MIL-STD-810H protocols.
Sea Skimmer Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented national procurement silos. Consolidation pressure intensifies as AUKUS and OCCAR coordination mechanisms harmonize specifications across allied navies. Three archetypes dominate: state-backed aerospace conglomerates with captive defense demand, mid-tier specialists leveraging regional supply chain integration, and joint ventures exploiting domestic manufacturing incentives. Strategic moves center on technology licensing for dual-mode propulsion and backward integration into rare earth magnet processing.
Within the state-backed tier, MBDA leverages European supply chain integration while Saab AB anchors Nordic requirements. BrahMos Aerospace occupies a distinctive position through Indo-Russian joint manufacturing structures that exploit Indian PLI scheme tailwinds. These three exemplify how geopolitical alignment shapes competitive positioning more than pure technical differentiation.
| Leading Market Players |
|---|
| MBDA |
| Saab AB |
| Israel Aerospace Industries Ltd |
| RTX Corporation |
| Northrop Grumman Corporation |
| Boeing Company |
| BrahMos Aerospace |
| Kongsberg Gruppen AS |
| Raytheon Technologies |
| Others |
Supply Flow & Price Mechanics
The Singapore-Johannesburg maritime corridor's freight volatility transmits cost pressures through rare earth magnet supply chains, concentrating pricing power among solid-fuel motor producers while forcing downstream tiering between hypersonic and subsonic platform architectures.
Pricing Analysis
Next-generation ramjet-integrated boost-sustain configurations command substantial premiums over legacy turbojet architectures, while prior-generation remote-controlled platforms face accelerated price erosion. Three-tier pricing structure across hypersonic, dual-mode, and subsonic levels reflects certification complexity under MIL-STD-810H protocols and thermal protection material qualification timelines. Pricing pressure stems from ITAR licensing delays extending delivery schedules for allied programs. Government agencies exhibit lowest price sensitivity due to mission-critical procurement authority; private offshore operators demonstrate highest elasticity, deferring fleet modernization during freight cost spikes.
Supply Chain Analysis
Contract manufacturing for guidance system electronics concentrates in Taiwan and South Korea, with final assembly and solid-fuel motor integration anchored in India and Russia through BrahMos joint venture structures. Neodymium and samarium processing draws from Chinese facilities, creating single-source vulnerability for permanent magnet procurement in propulsion miniaturization. Supply chain risk centers on rare earth export licensing unpredictability. Distribution runs through national defense procurement offices with OCCAR coordination streamlining European cross-border acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Directed energy countermeasures threaten sea skimmer survivability economics, forcing incumbents to defend substitution by hypersonic loitering munitions and autonomous underwater alternatives.
For Market Incumbents: Harden terminal guidance architectures against directed energy disruption through thermal protection material investments and sensor fusion redundancy. Secure captive neodymium supply via backward integration into magnet processing or long-term offtake agreements with Australian and Vietnamese rare earth developers. Counter emerging loitering munition substitutes by emphasizing sea skimmer payload-range economics in contested littoral scenarios.
For New Entrants and Emerging Players: Arctic-capable mobile launcher procurement in Norway and Finland offers accessible entry points with less entrenched incumbent relationships than Indo-Pacific coastal defense programs. Target customs enforcement hybrid platforms requiring runway-independent operations and lower certification barriers than naval strike specifications. Pursue technology licensing partnerships with established propulsion houses to bypass MIL-STD-810H qualification timelines.
For Investors and Strategic Acquirers: Mid-tier sensor fusion specialists with explainability audit capabilities under EU AI Act frameworks represent priority acquisition targets as European procurement delays resolve. Long-term viability hinges on dual-use technology transition pathways from research institutions to defense applications. Monitor ITAR licensing velocity and Chinese rare earth export permit issuance as inflection indicators for supply-constrained platform pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Ramjet Propulsion Integration | MBDA and Saab AB collapse cruise efficiency and terminal sprint trade-offs for NATO littoral batteries. |
| Rare Earth Magnet Backward Integration | BrahMos Aerospace secures neodymium supply chains against Chinese processing bottlenecks through Indian PLI incentives. |
| EU AI Act Compliance Certification | Autonomous target classification algorithms require explainability audit restructuring, delaying European programs 12-18 months. |
| AUKUS Pillar Two Specification Harmonization | NAVAIR aligns U.S., Australian, and Canadian requirements for Indo-Pacific distributed maritime operations. |
| Arctic-Capable Launcher Network Expansion | Norwegian and Finnish procurement of mobile coastal batteries addresses underpenetrated Nordic defense markets. |
Methodological Framework
Operator-level perspectives from naval program managers, coastal defense battery commanders, propulsion systems engineers, and defense procurement officers anchored the qualitative base. Secondary validation drew from NAVAIR unmanned systems roadmaps, OCCAR coordination documents, EU defense fund guidelines, and DRDO laboratory publications. Bottom-up platform deployment estimates triangulated against top-down defense budget appropriation analysis across littoral combat zones.
Scenario-bracketing framed projections across the analysis window, modeling segmentation by propulsion architecture, guidance technology, application profile, and end-user procurement authority. CAGRs derived from deployment trajectory analysis incorporating ITAR licensing velocity, rare earth supply elasticity, and directed energy program maturation. Hypersonic thermal protection certification timelines and sensor fusion autonomy roadmaps served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by state-backed aerospace conglomerates or accelerated directed energy fielding would shift outcomes. Quarterly review of Chinese rare earth export permits, EU AI Act certification pathway updates, and AUKUS Pillar Two specification releases is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Shackle Market
Marine
Asia-Pacific Electric Boat Market
Marine
Marine Airbags Market
Marine
Marine Pipes Market
Marine
Marine Glass Market
Marine
Trim Tabs Market
Marine
Global Foldable Inflatable Boats Market
Marine
Electric Boat Market
Marine
Integrated Bridge System for Ships Market
Marine
China Controllable Pitch Marine Propeller Market
Marine
North America Naval Vessels Market
Marine
Europe Recreational Boating Market
Marine
Hydrogen Ships Market
Marine
Submarine Propulsion Systems Market
Marine
Marine Lighting Market
Marine
Marine Asset Integrity Services Market