
 Marine Propulsion Systems Market | 2026-2036
Marine Propulsion Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Propulsion Systems Market Analysis
South Korean shipyard capacity is tilting toward dual-fuel and electric propulsion packages as owners prepare for IMO 2030 compliance deadlines. Wärtsilä leverages its portfolio of methanol-compatible engines to anchor premium positions in container ship retrofits. MAN Energy Solutions sustains leadership in two-stroke low-speed engines through captive control over fuel injection technology development. ABB competes aggressively in the electric propulsion segment with its Azipod pod drive systems, which dominate cruise ship and icebreaker specifications.
Marine propulsion systems encompass the integrated machinery, power generation, and transmission assemblies that convert stored energy into thrust for vessel movement, typically operating across power ranges from below 500 HP for recreational craft to above 5,000 HP for bulk carriers and naval combatants. Diesel propulsion retains the largest installed base in commercial shipping due to its established bunkering infrastructure and technician familiarity, though hybrid configurations are capturing the fastest expansion in ferry and offshore support vessel fleets. Electric and pod drive transmission architectures concentrate margin pools in cruise and expedition segments where maneuverability and noise suppression command specification premiums.
The International Maritime Organization's Carbon Intensity Indicator and Energy Efficiency Existing Ship Index are forcing commercial operators to evaluate propulsion upgrades against charter viability thresholds. The EPA's marine diesel engine Tier 4 standards in the United States and the EU's Fit for 55 maritime provisions collectively narrow the feasible technology set for vessels trading on transatlantic routes. Stakeholders must monitor ammonia and hydrogen fuel pathway certification timelines to time capital commitments on next-generation propulsion platforms.
Market Dynamics
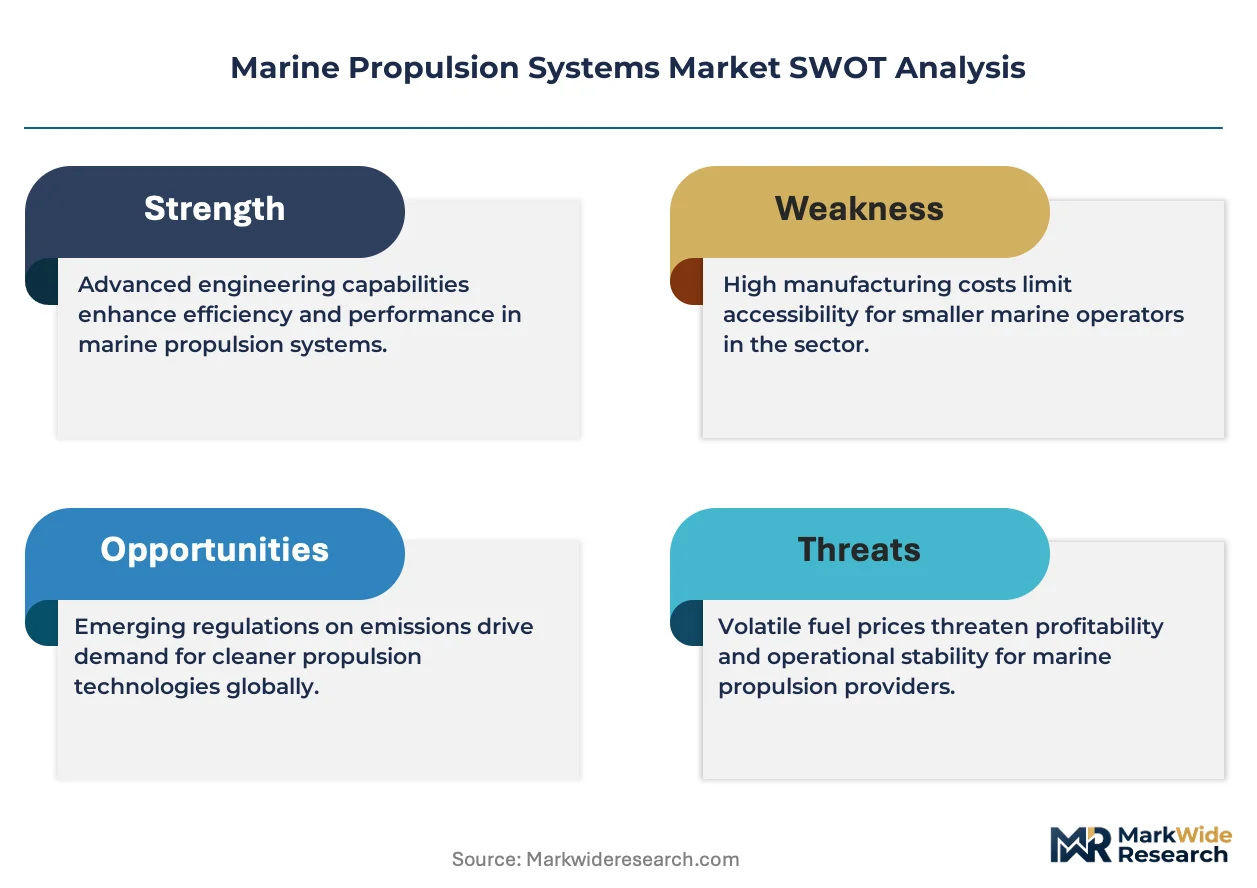
The International Maritime Organization's Carbon Intensity Indicator and Energy Efficiency Existing Ship Index are compressing vessel charter viability windows, forcing owners to accelerate propulsion retrofits or face exclusion from premium trade lanes.
Growth Catalysts
- IMO 2030 Compliance Deadlines:The revised carbon intensity regulations are compelling commercial operators to retrofit existing diesel installations with hybrid configurations across container and bulk carrier fleets.
- South Korean Shipyard Capacity:Hyundai Heavy Industries and DSME are tilting newbuild output toward dual-fuel and electric propulsion packages as owners prepare for ammonia-ready specifications.
- NATO Naval Modernization:Fleet renewal programs across member states are accelerating orders for integrated electric propulsion architectures in surface combatants and auxiliary vessels.
Market Restraints
- Bunkering Infrastructure Lock-In:Diesel propulsion retains structural advantage due to established global refueling networks and technician certification pools, slowing alternative fuel adoption.
- MEE Certification Timelines:China's Ministry of Ecology and Environment has yet to finalize ammonia and hydrogen fuel pathway standards, creating regulatory uncertainty for next-generation platform commitments.
- Two-Stroke Engine Concentration:Captive control over fuel injection technology development by dominant suppliers limits competitive entry into low-speed marine engine segments.
Strategic Opportunities
- EU Fit for 55 Maritime Provisions:The European Union's emissions trading system expansion for shipping creates premium positioning for methanol-compatible and battery-hybrid systems on transatlantic routes.
- Expedition Vessel Electrification:Noise suppression and maneuverability specifications in polar and ecotourism segments are concentrating margin pools for pod drive transmission architectures.
- Convergence of Azipod and Fuel Cell Systems:Integration of podded propulsion with hydrogen fuel cell power generation opens specification opportunities in cruise ship and icebreaker categories.
Industry Challenges
- Marine Electrician Skill Scarcity:Shortage of certified technicians capable of servicing integrated electric propulsion and high-voltage shore connection systems is extending vessel downtime during retrofits.
- Legacy Control System Integration:Hybrid propulsion retrofits require complex interfacing with existing automation architectures, increasing commissioning risk and warranty exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Propulsion Systems Market |
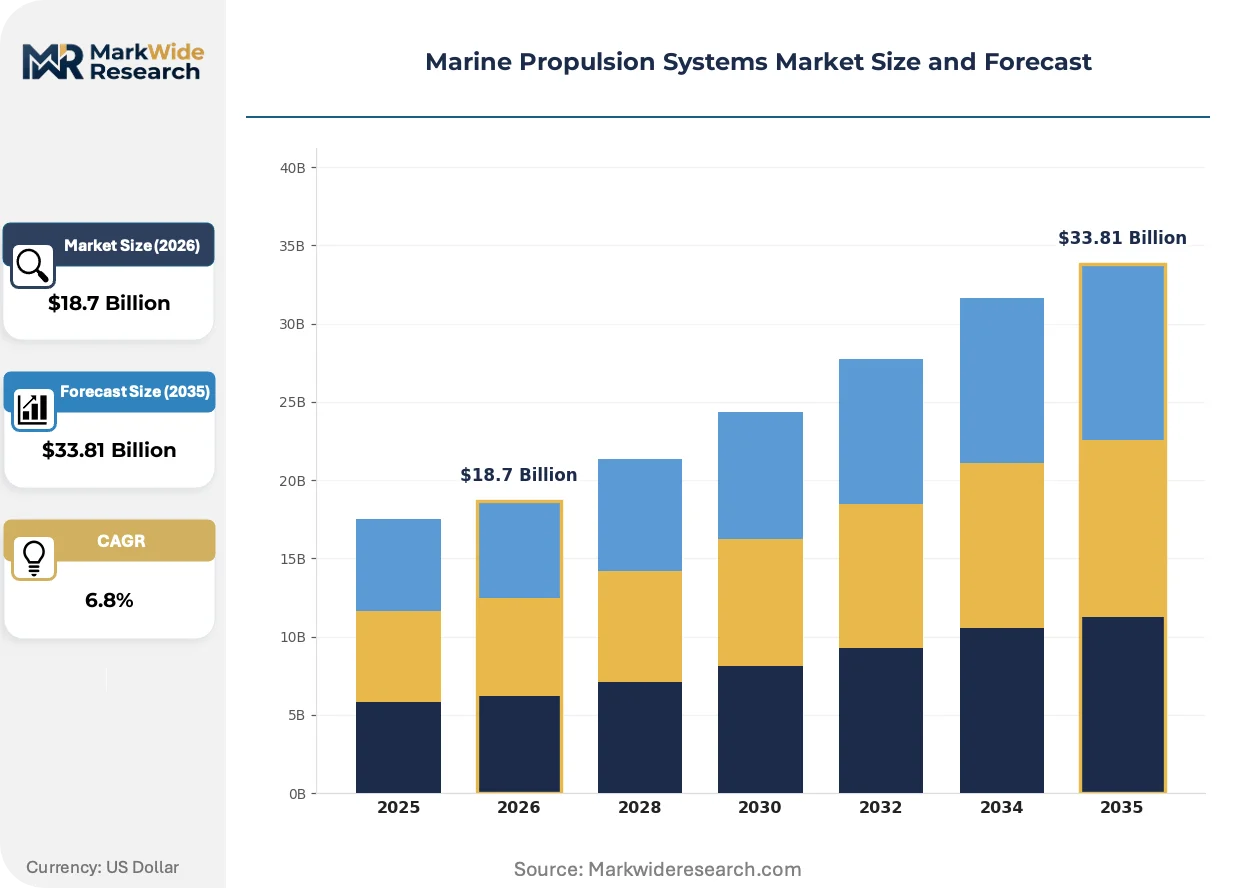
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Propulsion Type: Diesel, Gas Turbine, Electric, Hybrid Application: Commercial Shipping, Military Vessels, Recreational Boats, Fishing Fleets Power Rating: Less than 500 HP, 500-1000 HP, 1000-5000 HP, More than 5000 HP Transmission Type: Straight Shaft, Z-Drive, WaterJet, Pod Drive |
| Companies Covered | Wärtsilä, Caterpillar, Cummins, AB Volvo Penta, ABB, MAN Energy Solutions, Rolls-Royce, Hyundai Heavy Industries, Kawasaki Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Propulsion Systems Market Emerging Trajectories
Propulsion technology trajectories are diverging between evolutionary efficiency gains in conventional diesel architectures and disruptive electrification pathways that redefine vessel powertrain design.
Solid-state battery energy density improvements are rendering obsolete conventional lithium-ion configurations for short-route ferries and offshore support vessels. Norwegian and Danish operators are specifying all-electric propulsion for newbuilds under 5,000 HP. This chemistry transition is compressing battery system footprint requirements and enabling hull-integrated energy storage layouts.
The EPA's marine diesel engine Tier 4 standards in the United States are mandating selective catalytic reduction and exhaust gas recirculation on vessels trading in North American Emission Control Areas. Engine manufacturers are consolidating after-treatment system supply chains to meet compliance cost targets. Great Lakes bulk carriers and Alaska cruise operators face the steepest retrofit capital burdens under this framework.
Charterers are unbundling propulsion system performance guarantees from vessel management contracts, creating direct procurement relationships with technology suppliers. This disintermediation shifts technical risk allocation and accelerates specification decisions by end-users rather than ship managers. Container line procurement departments in Hamburg and Singapore are pioneering this contractual restructuring.
Marine Propulsion Systems Market Segmentation
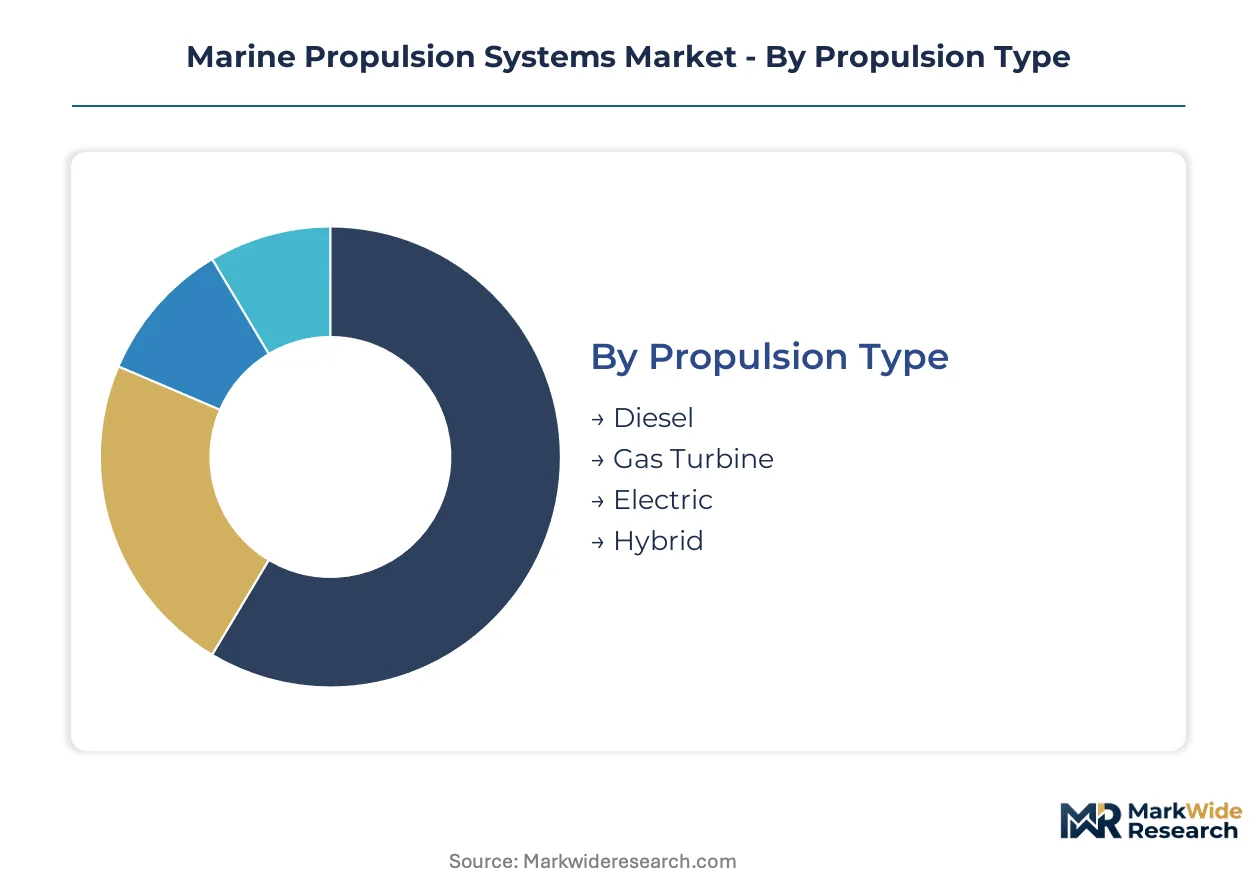
Propulsion system specifications diverge sharply across vessel categories, with powertrain architecture determining compliance pathways, fuel flexibility, and lifecycle economics. Segmentation reveals how regulatory pressure and operational profiles concentrate investment in specific technology combinations.
Propulsion Type:
Cost tier positioning separates established fuel infrastructure from emerging electrification pathways in commercial fleet procurement decisions.
- Diesel:Two-stroke and four-stroke compression-ignition engines dominate bulk carrier and tanker specifications through mature bunkering networks and technician certification pools. South Korean shipyards specify dual-fuel diesel variants to bridge ammonia-ready compliance timelines for container line operators.
- Hybrid:Battery-diesel and battery-gas turbine configurations capture ferry and offshore support vessel retrofits where port electrification infrastructure enables shore power integration. Norwegian operators lead all-electric specifications for sub-5,000 HP routes with predictable duty cycles.
- Electric:Fuel cell and battery architectures concentrate in cruise ship and icebreaker segments where noise suppression and maneuverability command specification premiums.
- Gas Turbine:Naval surface combatants specify marine gas turbines for sprint speed requirements in integrated electric propulsion architectures.
Diesel commands the established base. The steepest expansion runs through Hybrid.
Application:
Operational intensity and regulatory exposure create divergent technology adoption timelines across vessel ownership structures.
- Commercial Shipping:Container lines and bulk operators face the most compressed charter viability windows under IMO Carbon Intensity Indicator thresholds. Retrofit decisions concentrate on hybrid diesel-electric configurations for vessels under 15 years of age.
- Military Vessels:NATO fleet modernization programs specify integrated electric propulsion for surface combatants and auxiliary vessels, with Azipod pod drive architectures dominating icebreaker procurement.
- Recreational Boats:Outboard and sterndrive specifications below 500 HP are shifting toward electric propulsion in European marinas with shore power mandates.
- Fishing Fleets:Diesel retention remains strongest in artisanal and industrial fishing segments where fuel access reliability outweighs emissions compliance pressure in non-EU waters.
Commercial Shipping absorbs the largest capital deployment. Military Vessels are climbing the fastest on fleet renewal cycles.
Power Rating:
Power density requirements segment the supplier landscape between high-volume engine manufacturers and specialized electric propulsion integrators.
- More than 5000 HP:Two-stroke low-speed engines from MAN Energy Solutions and Wärtsilä dominate bulk carrier and tanker specifications above 50,000 deadweight tonnes. Fuel injection technology captive to these suppliers limits competitive entry.
- 1000-5000 HP:Medium-speed four-stroke engines service offshore support vessels, ferries, and smaller cargo ships where hybrid configurations are capturing fastest specification growth.
- 500-1000 HP:Workboat and coastal cargo segments specify this range for Z-drive and waterjet transmission pairings.
- Less than 500 HP:Outboard, sterndrive, and sail auxiliary applications concentrate volume in recreational and small commercial fishing fleets.
Above-5000 HP commands the established base. The 1000-5000 HP band is expanding most quickly on hybrid retrofit demand.
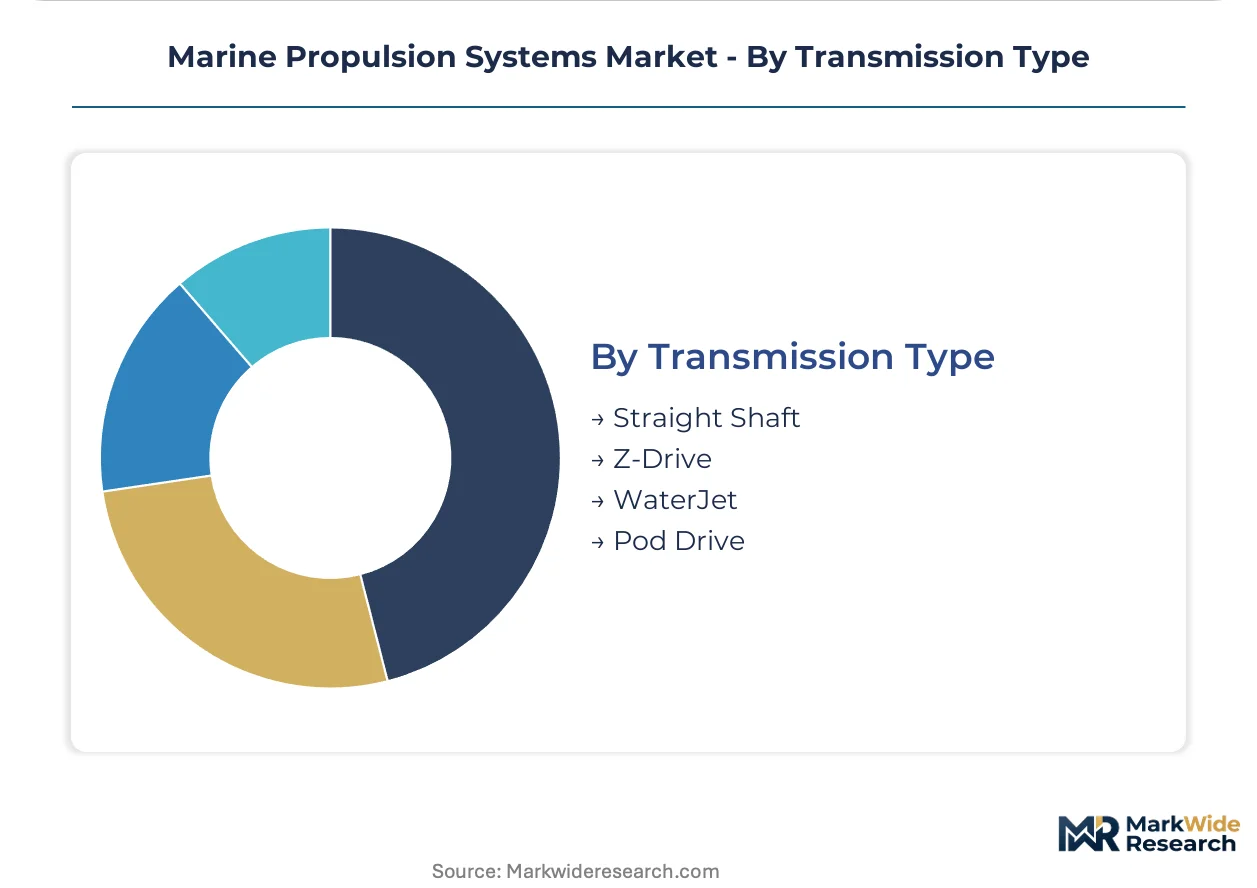
Transmission Type:
Maneuverability specifications and hull integration constraints determine transmission architecture selection across vessel categories.
- Pod Drive:ABB's Azipod systems dominate cruise ship and icebreaker specifications where 360-degree thrust vectoring and reduced machinery space enable passenger cabin optimization. Azipod integration with fuel cell power generation opens hydrogen pathway specifications.
- WaterJet:High-speed ferry and naval patrol craft specify waterjet propulsion for shallow draft operations and damage tolerance in littoral zones.
- Z-Drive:Tugboats and offshore support vessels employ Z-drive configurations for bollard pull performance and dynamic positioning precision.
- Straight Shaft:Conventional shaft-line systems retain cost advantage in bulk carrier and tanker specifications where maneuverability premiums do not justify pod drive capital expenditure.
Straight Shaft commands the established base. Pod Drive is gaining share fastest on cruise ship and expedition vessel electrification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shipyard capacity clusters in South Korea and Japan concentrate newbuild output for dual-fuel and ammonia-ready specifications. European operators face the steepest retrofit capital burdens under regional emissions frameworks. Chinese and American maritime regulators are finalizing divergent certification timelines for next-generation fuel pathways.
South Korea
Hyundai Heavy Industries and DSME dominate LNG-fueled and ammonia-ready vessel contracts as owners prepare for IMO 2030 compliance deadlines. The Ministry of Trade, Industry and Energy coordinates national hydrogen-ammonia fuel cell development programs for maritime applications. Ulsan and Geoje shipyard complexes anchor global newbuild output for container lines and bulk operators.
Norway
Coastal ferry operators specify all-electric propulsion for sub-5,000 HP routes with predictable duty cycles and shore power integration. The Norwegian Maritime Authority enforces stringent emissions standards in domestic waters ahead of international timelines. Bergen and Stavanger clusters concentrate battery system integrators and electric drivetrain engineering expertise.
United States
Great Lakes bulk carriers and Alaska cruise operators face Tier 4 retrofit mandates under EPA marine diesel standards in North American Emission Control Areas. The Coast Guard coordinates with the EPA on selective catalytic reduction certification timelines for existing fleet compliance. Seattle and New Orleans anchor aftermarket service networks for dual-fuel engine conversions.
Germany
MAN Energy Solutions sustains captive control over fuel injection technology development for two-stroke low-speed engines above 5,000 HP. The Federal Maritime and Hydrographic Agency implements EU Fit for 55 maritime provisions for vessels trading on transatlantic routes. Hamburg procurement departments pioneer direct propulsion system procurement relationships independent of vessel management contracts.
Japan
Kawasaki Heavy Industries concentrates military and commercial gas turbine specifications for integrated electric propulsion architectures. METI coordinates ammonia fuel pathway certification with shipyard partners ahead of 2030 commercial deployment targets. Nagoya and Kobe industrial corridors anchor precision manufacturing for medium-speed four-stroke engine components.
Marine Propulsion Systems Market Vendor Landscape
Engine manufacturers and electric propulsion integrators split the market between established fuel infrastructure and emerging electrification pathways. Consolidation around fuel injection technology and pod drive architectures limits competitive entry in high-horsepower segments. Two strategic archetypes dominate: captive technology developers controlling core fuel systems, and systems integrators bundling power generation with transmission hardware. Capacity expansion in South Korean shipyards and strategic partnerships for ammonia-ready specifications represent the dominant competitive moves.
Within the captive technology tier, MAN Energy Solutions and Wärtsilä exemplify fuel system specialists, while ABB occupies a position as electric transmission integrator. These three anchors span Finnish, German, and Swiss industrial origins respectively, representing the geographic spread of marine propulsion engineering concentration. Each sits within distinct competitive logics: fuel pathway development, combustion efficiency optimization, and power electronics integration. Their positioning reflects how technology control points fragment across mechanical and electrical domains rather than consolidating under single suppliers.
| Leading Market Players |
|---|
| Wärtsilä |
| Caterpillar |
| Cummins |
| AB Volvo Penta |
| ABB |
| MAN Energy Solutions |
| Rolls-Royce |
| Hyundai Heavy Industries |
| Kawasaki Heavy Industries |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Rotterdam container corridor compresses propulsion system pricing through bunker cost volatility and shipyard capacity concentration in South Korea. Freight rate fluctuations cascade into retrofit timing decisions, while dual-fuel engine premiums widen against conventional diesel configurations as IMO compliance deadlines approach.
Pricing Analysis
The EU Fit for 55 maritime provisions dictate the pricing tier structure across propulsion system procurement. Three-tier pricing structure across premium, standard, and economy levels separates methanol-compatible integrated systems from dual-fuel diesel variants and conventional single-fuel engines. Price differentiation centers on certification grade for ammonia-ready specifications and after-sales service bundling. Pricing pressure stems from South Korean shipyard overcapacity and container line procurement consolidation. Bulk carrier operators exhibit highest price sensitivity due to thin charter margins, while cruise lines accept premium positioning for noise suppression specifications.
Supply Chain Analysis
Specialized steel alloys and high-pressure fuel injection components anchor upstream feedstock dependencies for marine propulsion manufacturing. Production concentrates in Germany, South Korea, and Japan, with precision machining of crankshafts and cylinder blocks drawing from captive supplier networks. Rare earth elements for electric drivetrain magnets rest on Chinese processing capacity. Single-source vulnerability runs through MAN Energy Solutions and Wärtsilä control over two-stroke fuel injection technology. Distribution runs through shipyard direct procurement and aftermarket service networks concentrated in Rotterdam, Singapore, and Houston.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified marine electricians capable of servicing integrated electric propulsion systems remain scarce relative to fleet electrification timelines, creating a structural bottleneck that shapes competitive positioning and investment risk.
For Market Incumbents: Build regulatory certification moats around ammonia and hydrogen fuel pathway approvals ahead of IMO 2030 deadlines. MAN Energy Solutions and Wärtsilä should deepen backward integration into fuel injection component manufacturing to defend against emerging Chinese competitors. Capacity addition in South Korean shipyard clusters captures NATO naval modernization contracts. ABB must anchor Azipod service networks in polar expedition vessel segments where replacement cycles concentrate. For New Entrants and Emerging Players: Mid-market offshore support vessels in the North Sea represent the most penetrable entry point for battery-hybrid system integrators lacking established marine engine heritage. Norwegian ferry electrification retrofits below 5,000 HP offer specification influence before scaling into container ship segments. Partner with Bergen and Stavanger battery system engineering clusters to bypass incumbent service network gaps. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming marine divisions amid energy transition capital reallocation. Five-to-ten year viability hinges on fuel pathway certification timing rather than combustion technology legacy. Acquisition focus should center on electric propulsion integrators with shore power interface capabilities. The signal to watch is China's MEE finalization of ammonia fuel standards, which would unlock shipyard order acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Ammonia-Ready Engine Certification | IMO 2030 compliance deadlines force premature technology commitments without finalized fuel standards. |
| Shipyard Capacity Expansion | Hyundai Heavy Industries and DSME tilt output toward dual-fuel specifications dominating newbuild contracts. |
| Pod Drive-Fuel Cell Integration | ABB Azipod convergence with hydrogen power generation opens cruise ship and icebreaker specification opportunities. |
| Aftermarket Service Network Buildout | Certified technician scarcity in electric propulsion extends vessel downtime and shifts procurement toward bundled service contracts. |
| Direct Procurement Relationship Development | Hamburg and Singapore container lines disintermediate ship managers to accelerate specification decisions and shift technical risk allocation. |
Methodological Framework
A standing panel of shipyard procurement directors, fleet technical managers at container lines, marine classification society surveyors, and aftermarket service network heads provided ongoing calibration across the study period. Primary interview data combined with secondary validation from Lloyd's Register filings, IMO regulatory submissions, shipyard order databases, and customs trade records. Bottom-up vessel fleet analysis triangulated against top-down shipyard capacity assessments.
Scenario-bracketing around fuel pathway certification timelines and naval modernization budget cycles structured the analytical framework across the projection horizon. Segmentation dimensions modeled include propulsion architecture, power rating tier, transmission type, and vessel application category. CAGRs derived from shipyard orderbook analysis and retrofit penetration curves. Forecast inputs incorporated bunker fuel price elasticity and ETS carbon price assumptions.
Macroeconomic conditions sit as an overlay; deviation in freight rate indices and ship financing availability would shift the trajectory. Forecasts reflect stated assumptions regarding regulatory implementation schedules and fuel infrastructure deployment. Cross-checking against Clarksons newbuild order data and Baltic Exchange freight indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Global Boat Market
Marine Vehicles
Marine Electric Vehicle Market
Marine Vehicles
Pontoon Boat Market
Marine Vehicles
Marine Methanol Engine Market
Marine Vehicles
Small Boats Market
Marine Vehicles
Global Outboard Motors Market
Marine Vehicles
Global Catamaran Market
Marine Vehicles
Bass Boat Market
Marine Vehicles
Tugboat Market
Marine Vehicles
Marine Seats Market
Marine Vehicles
Global Luxury Boat Market
Marine Vehicles
Outboard Engines Market
Marine Vehicles
Marine Steering Systems Market
Marine Vehicles
Boat and Ship MRO Market
Marine Vehicles
Aluminium Fishing Boat Market
Marine Vehicles
Marine Propulsion Engine Market