
 Maple Syrup Market | 2026-2036
Maple Syrup Market Size, Share, and Industry Trends Forecast 2026-2036
Maple Syrup Market Analysis
Food service procurement is realigning toward premium single-origin syrups for menu differentiation. The J.M. Smucker Company leverages retail shelf-space dominance across North American grocers. Federation of Quebec Maple Syrup Producers anchors global bulk supply through strategic reserve management. Bascom Maple Farms specializes in organic certification tiers that command wholesale premiums.
Maple syrup denotes the concentrated sap of Acer saccharum, boiled to minimum density of 66.0 degrees Brix and graded by color and flavor intensity for commercial trade. Pure Maple Syrup dominates value capture with its premium positioning in specialty stores and direct-to-consumer channels. Food Manufacturers represent the fastest-growing end-user segment as CPG brands reformulate away from corn syrup. Supermarkets still control the highest volume throughput, though Online Retail is gaining share among subscription-based artisan brands.
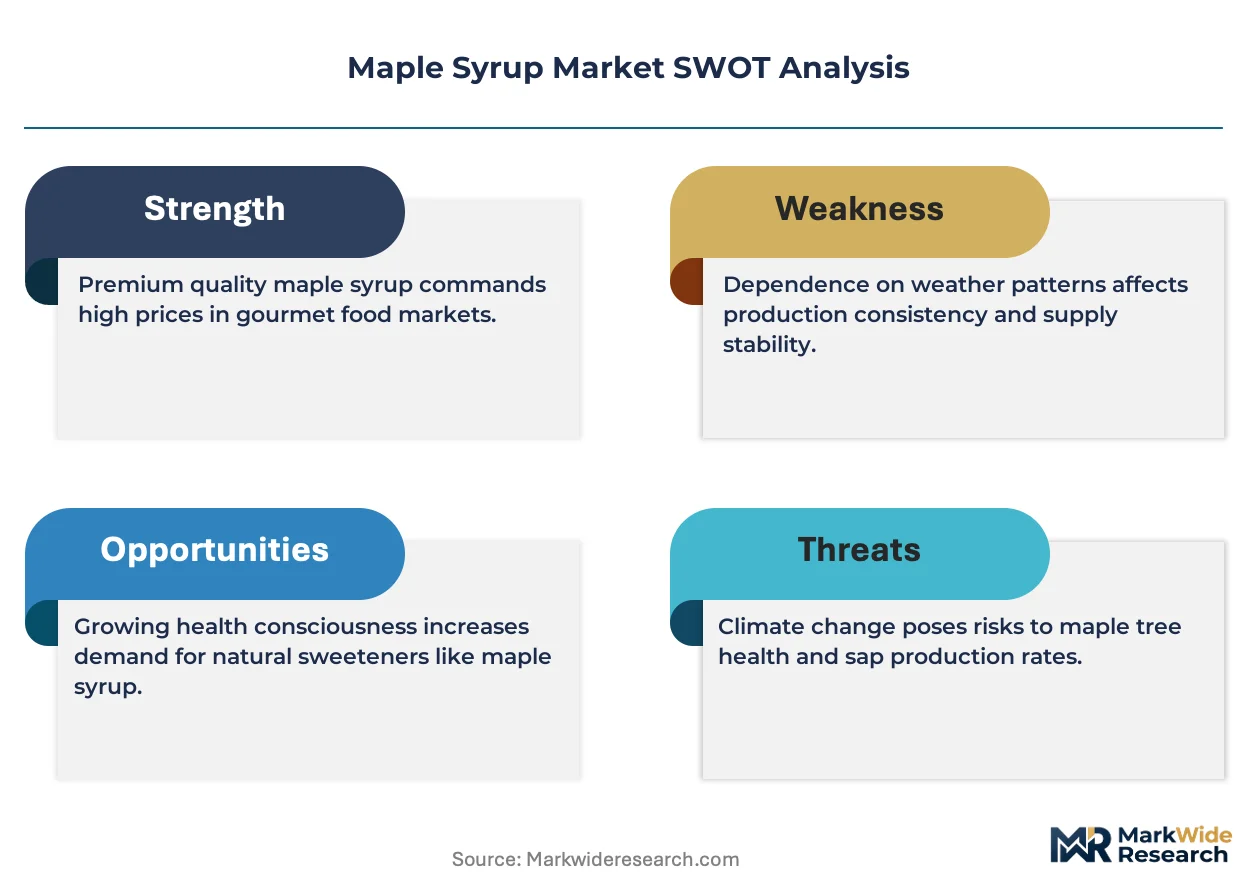
Canada's CFIA enforces Grade A processing standards that determine export eligibility into US markets, while USDA organic certification shapes price realization tiers. The FDA's added-sugar labeling rules push food manufacturers toward recognizable sweeteners like maple. Stakeholders must monitor how climate volatility affects sap flow timing and whether reserve-buffer strategies can stabilize processor margins against harvest uncertainty.
Market Dynamics
Quebec's strategic reserve management and Vermont's artisan bottling cluster are reshaping how bulk supply flows to food manufacturers seeking clean-label sweeteners. The tension between industrial-scale processing and single-origin premium positioning defines competitive strategy across the value chain.
Growth Catalysts
- CFIA Grade A modernization:Canada's updated processing standards streamline cross-border certification into US retail channels, reducing compliance friction for Quebec exporters.
- Food manufacturer reformulation:CPG brands are substituting corn syrup with recognizable maple ingredients to meet FDA added-sugar labeling transparency requirements.
- Climate adaptation infrastructure:Reverse osmosis concentration and vacuum evaporation systems extend viable sap collection windows beyond traditional freeze-thaw cycles.
Market Restraints
- Quebec supply concentration:The Federation of Quebec Maple Syrup Producers controls strategic reserve releases that buffer price volatility but create single-point dependency risks.
- Sap flow timing compression:Erratic winter warming patterns compress harvest windows, forcing capital-intensive infrastructure upgrades for consistent volume.
- Agave and date syrup substitution:Lower-cost natural sweeteners compete for clean-label positioning in price-sensitive food manufacturing applications.
Strategic Opportunities
- USDA organic certification tiers:Premium price realization for certified organic bulk supply creates margin expansion for processors investing in audit infrastructure.
- Direct-to-consumer subscription channels:Artisan bottlers bypass supermarket slotting fees through recurring revenue models targeting specialty food enthusiasts.
- Maple-based ingredient portfolios:Crystallized maple sugar and maple butter applications extend beyond breakfast into confectionery and beverage formulations.
Industry Challenges
- Sugarbush technician scarcity:Vacuum tubing installation and maintenance expertise concentrates among aging operator networks with limited apprenticeship pipelines.
- Organic certification timeline:Three-year land conversion requirements delay premium pricing access for new entrants expanding certified acreage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maple Syrup Market |
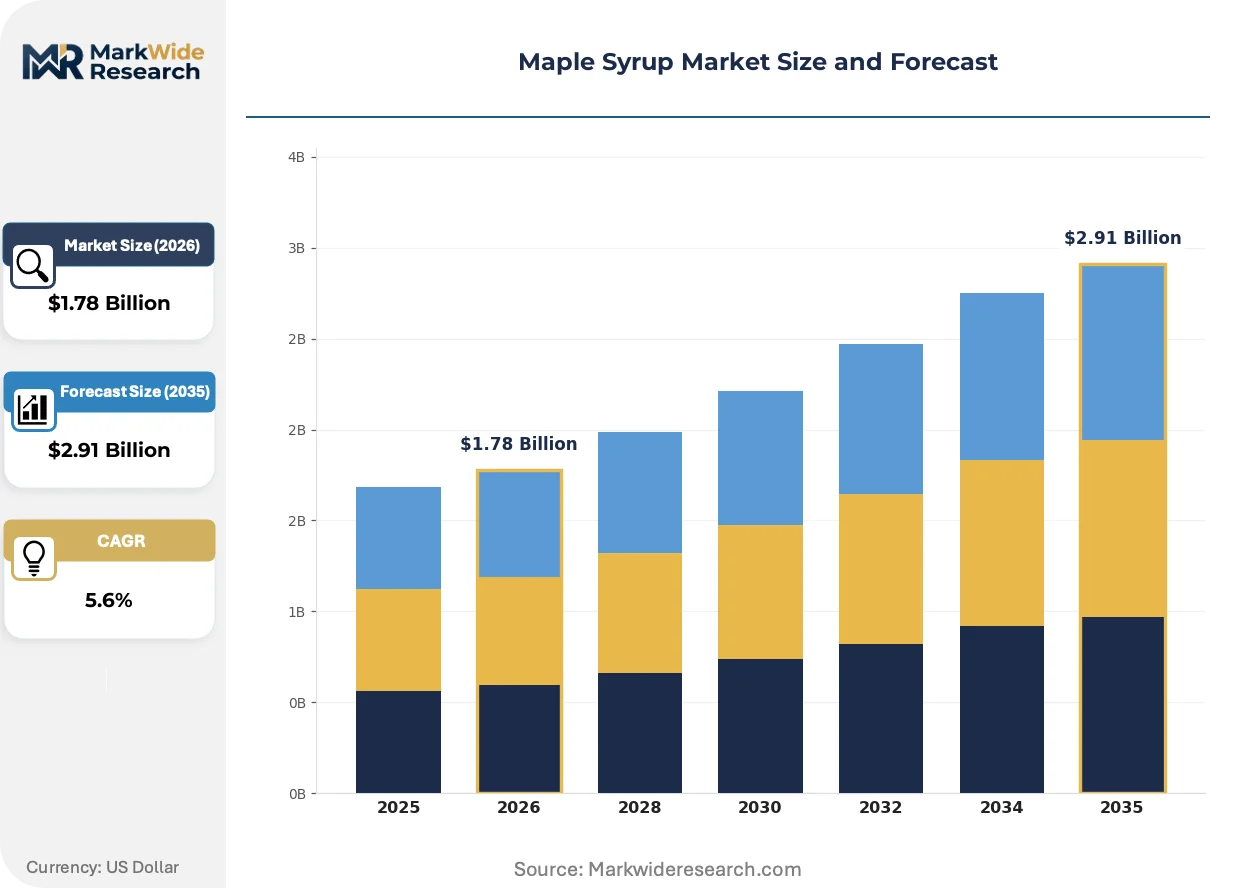
| Market Size in 2026 | $1.78 Billion |
| Market Size in 2035 | $2.91 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Maple Syrup, Maple Sugar, Maple Leaf Candy, Maple Butter End User: Households, Food Service, Food Manufacturers, Exporters Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Farmers' Markets Packaging Type: Bottles, Jars, Tubs, Pouches |
| Companies Covered | B&G Foods, The J.M. Smucker Company, Federation of Quebec Maple Syrup Producers, Les Industries Bernard et Fils, LB Maple Treat, Coombs Family Farms, Bascom Maple Farms, Butternut Mountain Farm, Maple Joe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maple Syrup Market Emerging Trajectories
Reverse osmosis concentration technology is compressing energy costs and expanding viable production geography beyond traditional sugarbush heartlands. These shifts are fragmenting the historical link between terroir and processing scale.
Membrane filtration systems are overtaking open-pan evaporation in mid-scale operations. Vermont and New York processors are adopting RO pre-concentration to reduce fuel oil consumption by half. This technology is overtaking artisan mythology as the primary determinant of facility economics, enabling non-traditional regions to achieve cost parity with established Quebec bulk suppliers.
USDA organic certification requirements are tightening audit protocols for multi-site processors. The updated National Organic Program rule mandates enhanced traceability documentation from tap to bottling. Small-scale cooperatives in Maine and Wisconsin are consolidating certification costs through shared inspector arrangements.
Food service procurement now favors single-origin syrups with documented sugarbush coordinates for menu storytelling. Independent restaurants in Portland and Austin are displacing commodity-grade supply through direct relationships with named producers. This preference shift concentrates in coastal metropolitan markets where provenance commands plate-price premiums.
Maple Syrup Market Segmentation
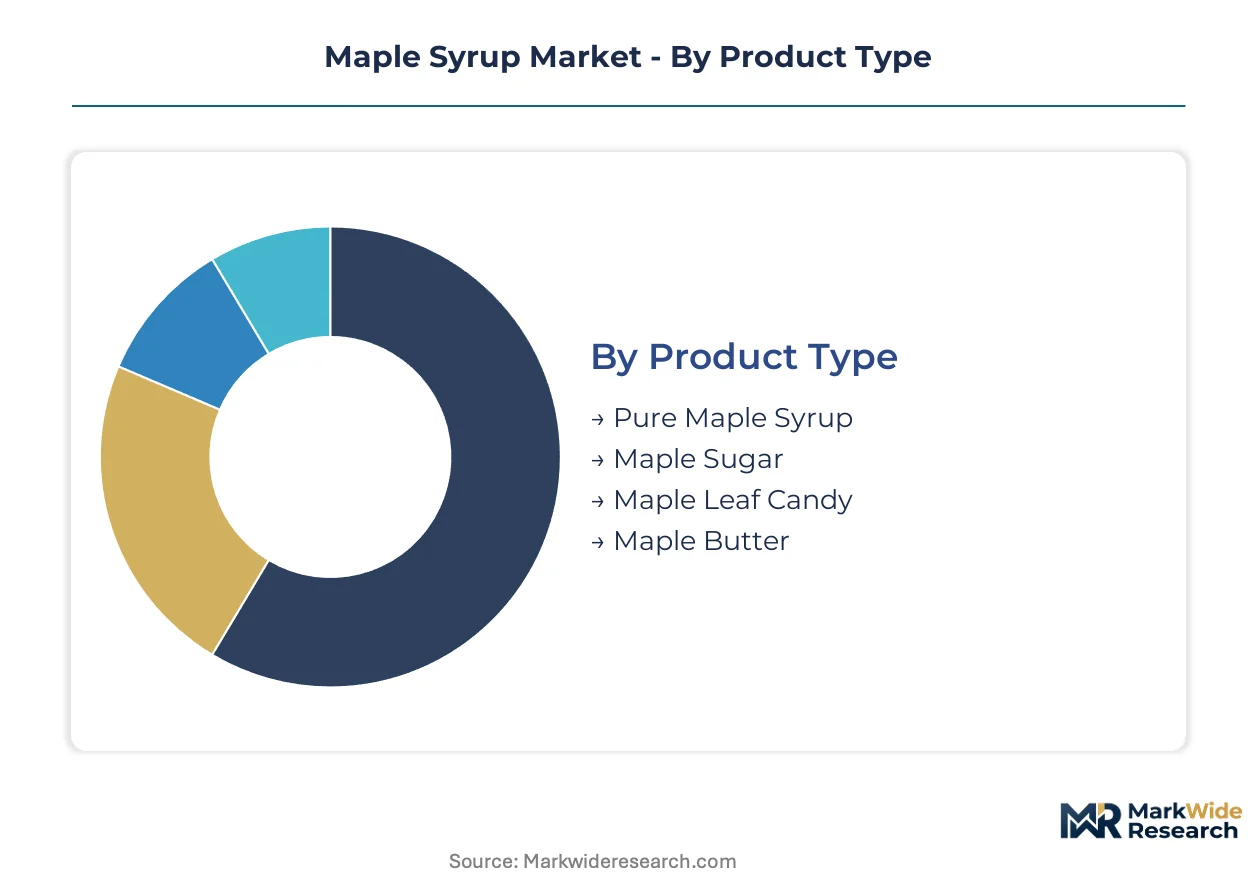
Maple syrup segmentation reveals how capital intensity, regulatory compliance, and channel economics fragment value capture across the supply chain. Processing scale and certification tiers determine which segments absorb infrastructure investment and which yield margin premiums.
Product Type:
Reverse osmosis systems and vacuum evaporation equipment require the heaviest upfront capital, concentrating investment in liquid processing segments over confectionery derivatives.
- Pure Maple Syrup:Concentrated Acer saccharum sap boiled to 66.0 degrees Brix minimum density, graded by CFIA and USDA color standards. Quebec's bulk processors and Vermont's artisan bottlers dominate volume and premium positioning respectively, with organic certification tiers commanding wholesale price premiums.
- Maple Sugar:Dehydrated syrup crystallized into granulated form for bakery and confectionery applications. Food manufacturers in the US Northeast are substituting cane sugar with maple sugar for clean-label reformulations, though energy costs for dehydration limit facility economics.
- Maple Leaf Candy:Molded crystalline confections targeting tourist retail and gift channels. Quebec sugar shacks and Vermont farm stands concentrate seasonal demand.
- Maple Butter:Whipped crystallized syrup spreadable at room temperature. Specialty stores in Ontario and New England drive niche demand for premium spreads.
Most installed capacity flows through Pure Maple Syrup. Expansion is steepest in Maple Sugar as CPG brands reformulate sweetener portfolios.
End User:
Volume throughput concentrates in segments with direct procurement scale, while margin accrues to those with specification complexity and audit requirements.
- Food Manufacturers:CPG brands and ingredient suppliers purchasing bulk syrup for reformulation into cereals, beverages, and baked goods. FDA added-sugar labeling rules are accelerating substitution away from high-fructose corn syrup toward recognizable maple ingredients, with procurement concentrating in Quebec's bulk processing corridor.
- Households:Direct consumers purchasing for home breakfast and cooking applications. Subscription-based artisan brands are displacing supermarket commodity grades in coastal metropolitan markets through documented sugarbush provenance.
- Food Service:Restaurants, cafes, and institutional kitchens. Independent operators in Portland and Austin favor single-origin syrups with named producer relationships for menu storytelling.
- Exporters:International traders shipping to Japan, Germany, and the UK. CFIA Grade A certification determines eligibility into premium retail channels abroad.
Procurement volume concentrates in Food Manufacturers. Margin expansion is sharpest in Food Service as provenance documentation commands plate-price premiums.
Distribution Channel:
Channel selection determines working capital intensity, with inventory carrying costs and slotting fee structures fragmenting go-to-market economics.
- Supermarkets:Mass retail chains controlling highest volume throughput through centralized distribution. The J.M. Smucker Company leverages shelf-space dominance across North American grocers, though slotting fees compress margins for smaller processors.
- Online Retail:Direct-to-consumer platforms and subscription services. Artisan bottlers bypass supermarket gatekeepers through recurring revenue models targeting specialty food enthusiasts in urban markets.
- Specialty Stores:Gourmet food retailers and natural product chains. Premium single-origin positioning dominates here.
- Farmers' Markets:Direct producer-to-consumer sales at seasonal venues. Vermont and Maine producers capture full retail margin through face-to-face relationships.
Supermarkets absorb the greatest inventory investment. Online Retail is climbing the fastest as subscription economics reduce customer acquisition costs.
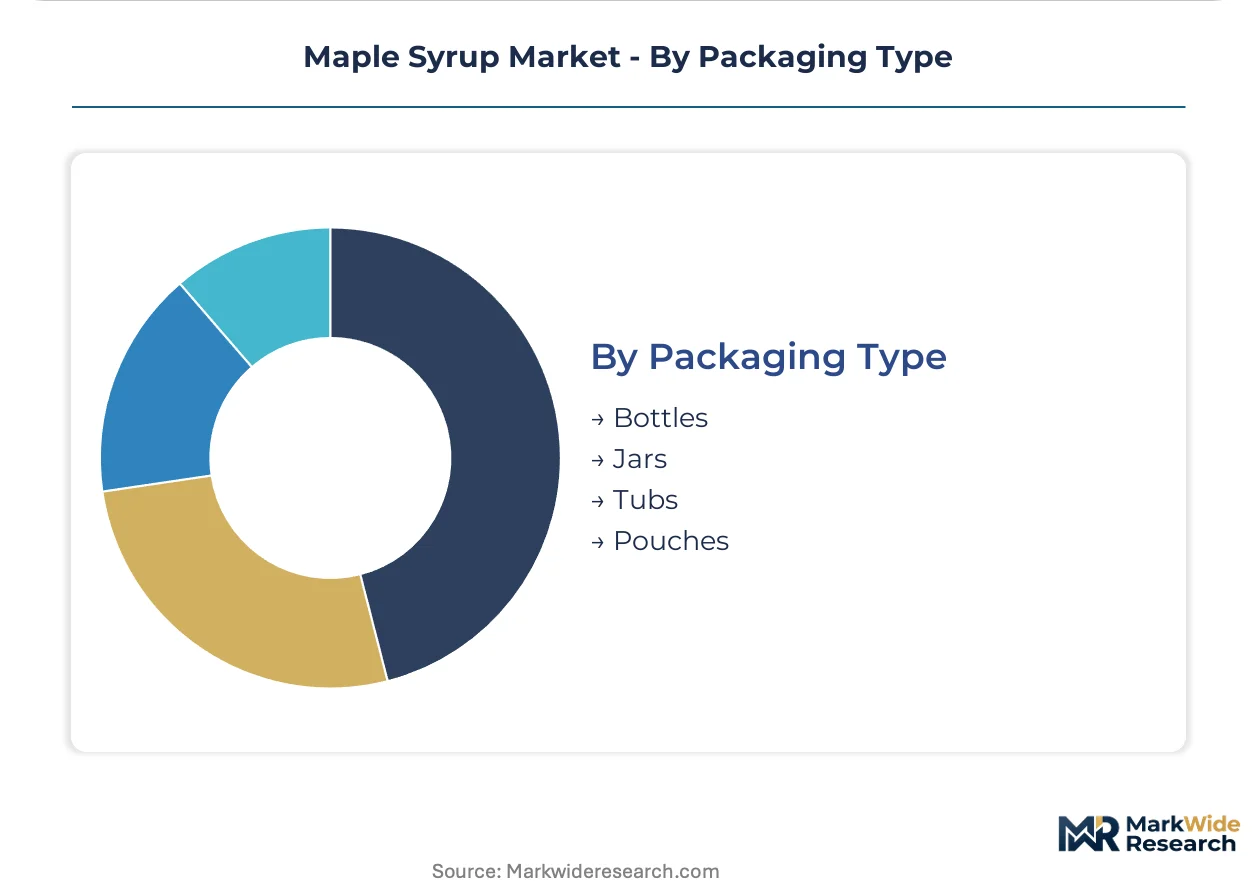
Packaging Type:
Packaging line automation and material specification drive capital allocation, with food safety compliance costs favoring standardized formats over artisan presentation.
- Bottles:Glass and plastic containers for liquid syrup retail. CFIA and FDA food contact material regulations dictate resin specifications, with hot-fill compatibility requiring capital-intensive line equipment.
- Jars:Wide-mouth glass containers for maple butter and spreads. Specialty store distribution favors premium glass presentation.
- Tubs:Plastic containers for bulk food service and manufacturing supply. Lowest per-unit packaging cost supports volume throughput.
- Pouches:Flexible film packaging for single-serve and travel formats. Emerging in airline and hospitality amenity channels.
Bottles command the most packaging line capital. Pouches are gaining share fastest as portion-control formats penetrate food service and travel retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting bulk processing capacity toward jurisdictions with streamlined organic certification pathways. Quebec's CFIA-aligned standards and Vermont's artisan-scale exemptions create divergent compliance cost structures that reshape cross-border investment flows.
Canada
Quebec's bulk processing corridor dominates global volume through Federation-managed reserve releases. CFIA Grade A modernization streamlines US export eligibility, reducing documentation friction for cross-border shipments. Montreal and surrounding regions concentrate reverse osmosis infrastructure investment.
United States
Vermont's artisan bottling cluster captures premium positioning through documented sugarbush provenance. USDA organic certification tiers command wholesale price premiums, with three-year land conversion requirements filtering new entrants. Burlington-area processors specialize in direct-to-consumer subscription channels.
Japan
Specialty retail demand concentrates in Tokyo and Osaka metropolitan markets for single-origin gift formats. METI import standards shape eligibility for premium retail placement, with documented traceability from tap to bottle. Hokkaido's emerging sugarbush operations test northern latitude viability.
Germany
Natural food retail chains in Berlin and Munich drive organic-certified import demand for bakery reformulation. EFSA-aligned labeling requirements favor recognizable sweetener declarations over additive codes. Hamburg traders coordinate bulk distribution into Central European processing facilities.
United Kingdom
London's food service procurement favors named-provenance syrups for menu differentiation in independent restaurants. Post-Brexit customs documentation complicates Quebec supply chains, creating openings for Vermont direct relationships. Edinburgh and Glasgow specialty retailers concentrate Scottish demand.
Maple Syrup Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with retail shelf-space concentration favoring scaled CPG portfolios while artisan channels reward documented provenance. The vendor base organizes around three strategic archetypes: reserve-anchored bulk suppliers, vertically integrated farm-bottlers, and organic-certified specialty processors. Consolidation pressure concentrates in mid-scale operations lacking either volume scale or certification differentiation. Dominant competitive moves include geographic expansion into non-traditional sugarbush regions and portfolio diversification into crystallized sugar and spreadable butter formats.
Within the reserve-anchored tier, Federation of Quebec Maple Syrup Producers exemplifies strategic supply management through controlled release mechanisms. Vermont-based Butternut Mountain Farm and Bascom Maple Farms occupy positions in the organic-certified specialty segment, with certification infrastructure investments that filter price-sensitive competitors. The J.M. Smucker Company represents scaled CPG shelf-space dominance across North American retail channels.
| Leading Market Players |
|---|
| B&G Foods |
| The J.M. Smucker Company |
| Federation of Quebec Maple Syrup Producers |
| Les Industries Bernard et Fils |
| LB Maple Treat |
| Coombs Family Farms |
| Bascom Maple Farms |
| Butternut Mountain Farm |
| Maple Joe |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between USDA organic and conventional bulk supply shapes both price realization and procurement routing across the maple syrup value chain. Quebec's Federation-managed reserve releases anchor commodity pricing floors while Vermont's single-origin bottlers capture provenance premiums through direct channels.
Pricing Analysis
Retailer markup layers concentrate margin capture in supermarket channels where slotting fees absorb working capital from smaller processors. Three-tier pricing structure across premium organic, standard Grade A, and economy bulk grades reflects CFIA color classification and USDA certification status. Pricing pressure stems from agave and date syrup substitution in CPG reformulation, compressing mid-tier wholesale quotations. Food manufacturers exhibit highest price sensitivity due to volume procurement scale, while independent restaurants accept premiums for documented sugarbush coordinates.
Supply Chain Analysis
Regional distribution centers in Montreal and Burlington coordinate hub-and-spoke patterns for cross-border retail fulfillment. Bulk supply concentrates in Quebec, Vermont, and New York, with reverse osmosis infrastructure expanding into Maine and Wisconsin. Raw material dependencies center on Acer saccharum sap flow, vacuum tubing systems, and fuel oil or wood pellet evaporation energy. Tariff exposure from post-Brexit UK customs documentation creates supply chain risk for Quebec exporters. Distribution runs through Federation-coordinated bulk auctions, processor-direct food service contracts, and CPG manufacturer long-term offtake agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The maple syrup market represents a late-cycle quality story as food service procurement shifts toward single-origin specifications with documented provenance. This demand migration favors processors with certification infrastructure and direct channel control over commodity bulk suppliers.
For Market Incumbents: Cement reserve-buffer strategies through controlled release mechanisms that stabilize processor margins against climate-induced harvest volatility. Deepen backward integration into sugarbush acreage to secure sap supply against Federation pricing power. Prioritize organic certification tier expansion as FDA labeling transparency requirements accelerate CPG brand reformulation toward recognizable sweeteners. For New Entrants and Emerging Players: The premium-to-economy price-point gap in crystallized maple sugar applications offers white-space opportunity for dehydration-capable processors. Target food manufacturing substitution demand in US Northeast bakery reformulation. Pursue shared organic certification cooperatives to distribute three-year land conversion audit costs across Maine and Wisconsin producer networks. For Investors and Strategic Acquirers: Asymmetric upside sits with organic-certified specialty processors possessing established direct-to-consumer subscription infrastructure. Long-term viability hinges on climate adaptation technology deployment and reserve management capabilities. Monitor sap flow timing compression indicators as inflection signals for infrastructure investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Investment | USDA audit infrastructure unlocks wholesale price premiums in CPG procurement channels. |
| Reverse Osmosis Capacity Expansion | Montreal-area processors reduce fuel oil consumption by half through membrane pre-concentration. |
| Direct-to-Consumer Subscription Launch | Burlington bottlers bypass supermarket slotting fees through recurring urban revenue models. |
| Maple Sugar Product Line Extension | Crystallized formats penetrate confectionery and beverage applications beyond breakfast segments. |
| Sugarbusch Acreage Acquisition | Vertical control over Acer saccharum tapping rights secures supply against Federation reserve pricing. |
Methodological Framework
Multiple input streams — Federation of Quebec Maple Syrup Producers auction data, CFIA export certification records, and USDA organic program audit filings — were reconciled against primary interviews with sugarbush operators, food manufacturing procurement leads, and specialty store category buyers. Secondary validation drew from customs trade databases, agricultural cooperative financial disclosures, and regional evaporator equipment installation permits. Bottom-up volume estimates from individual processor capacity were triangulated against top-down demand segmentation from CPG reformulation trends and food service menu development patterns.
Cross-referencing historical production volatility against expert panel assessments of climate adaptation infrastructure deployment shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user category, distribution channel, and packaging format, with organic certification tier as an industry-specific overlay. CAGRs were derived from regression analysis of reserve release pricing, sap flow timing correlations, and substitution elasticity estimates for natural sweetener procurement decisions.
Caveats apply where extreme weather events, regulatory shifts in FDA added-sugar labeling enforcement, or Federation reserve management policy changes could materially shift the outlook. Forecasts reflect documented assumptions regarding climate adaptation technology adoption rates and cross-border certification harmonization timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Human Grade Pet Food Market
Specialty Foods
Saw Palmetto Market
Specialty Foods
North American Jam, Jelly, and Preserve Market
Specialty Foods
Cat Food Toppings Market
Specialty Foods
Global Hispanic Foods Market
Specialty Foods
Super Foods Market
Specialty Foods
Low Salt Low Fat Meals Market
Specialty Foods
Grain Free Dog Food Market
Specialty Foods
Natural Honey Market
Specialty Foods
Cultures Market
Specialty Foods
Fermented Black Beans Market
Specialty Foods
Luxury Cigar Market
Specialty Foods
Soft Tofu Market
Specialty Foods
Cannabis-Infused Burger Market
Specialty Foods
Germany Barbeque Grill Market
Specialty Foods
Mexico Guacamole Market