
 Natural Honey Market | 2026-2036
Natural Honey Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Honey Market Analysis
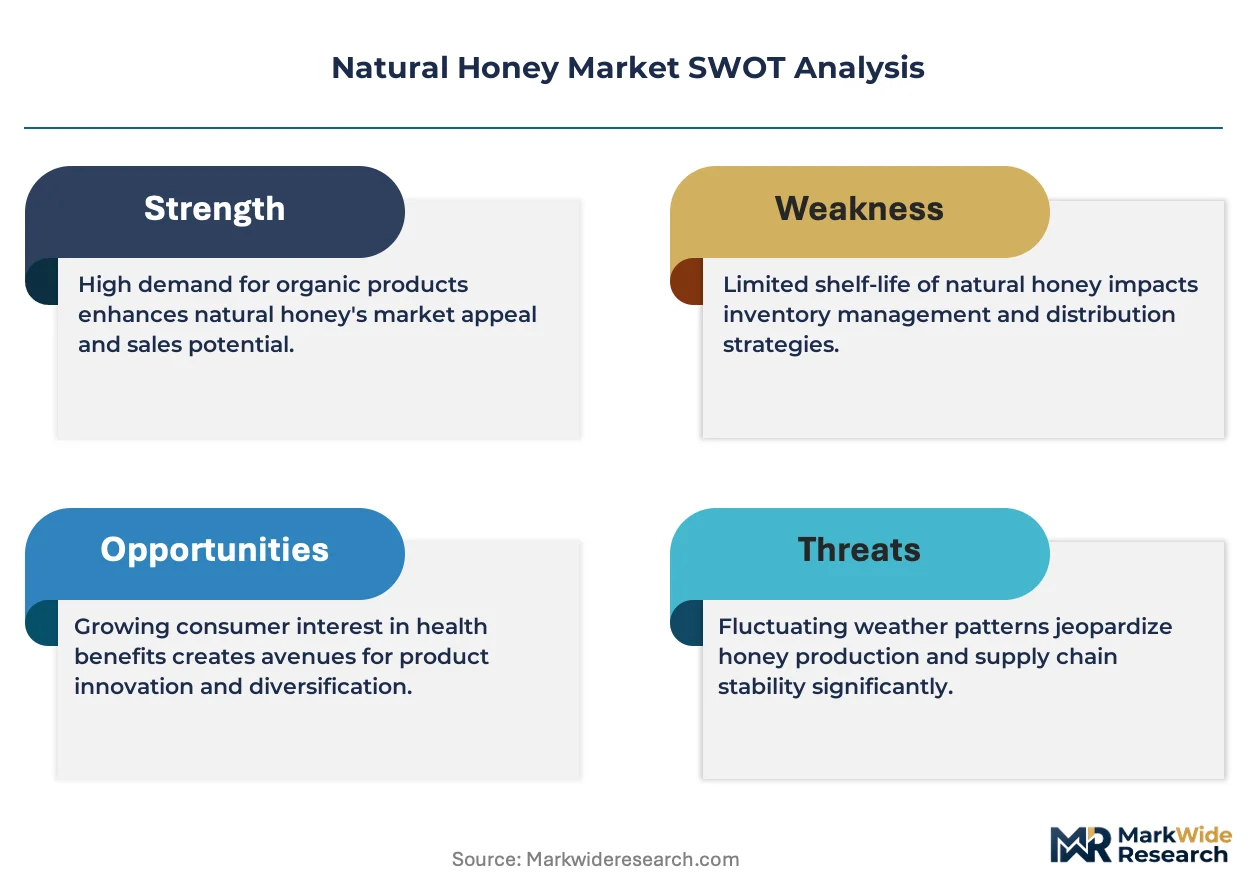
Subscription-based hive monitoring and blockchain traceability services is realigning what buyers pay for in the natural honey trade. China National Honey Corporation leverages integrated apiary-to-bottling operations across Hubei and Yunnan provinces. New Zealand Honey Company sustains premium positioning through Mānuka certification and MPI-recognized grading protocols. Argentina Honey Exporters Cooperative navigates Mercosur tariff schedules while competing on bulk clover and polyfloral supply to European processors.
Natural honey is the enzymatically processed nectar stored by Apis mellifera and related species, with moisture content typically below 20 percent and reducing sugar profiles dominated by fructose-glucose ratios. Its primary commercial purpose spans direct consumption, industrial sweetening, and antimicrobial formulation in wound care and dermatological products. Raw honey and Mānuka honey command the deepest margin pools due to therapeutic grade certification and UMF/MGO premium tiers. The food and beverage application segment anchors volume offtake, while nutraceuticals represents the fastest-growing demand channel as consumers shift from refined sweeteners toward functional ingredients.
The EU EFSA and REACH frameworks govern residue limits and botanical origin verification for honey entering European distribution channels, with third-party pollen analysis now mandatory for organic claims. The US FDA enforces identity standards under 21 CFR 101.80, while India's FSSAI mandates AGMARK certification for domestic retail sale. Stakeholders must monitor how evolving digital traceability mandates reshape procurement qualification and which origin-specific certifications become non-negotiable for supermarket and pharmacy channel access.
Market Dynamics
Blockchain-enabled provenance verification is compressing qualification timelines for natural honey entering European pharmacy and organic retail channels, forcing exporters to retrofit traceability infrastructure ahead of 2027 digital mandate deadlines.
Growth Catalysts
- REACH traceability mandates:The EU EFSA framework now requires third-party pollen analysis for organic claims, accelerating laboratory capacity expansion across German and French certification bodies.
- Nutraceutical channel expansion:Wound care and dermatological formulators in Swiss and Austrian markets are procuring therapeutic-grade Mānuka honey at volume multiples above food-grade benchmarks.
- Hive monitoring platforms:IoT-enabled apiary management systems are reducing colony loss rates among commercial pollinator services contracted by almond and blueberry growers in California and Victoria.
Market Restraints
- Monofloral supply concentration:Certified Mānuka and Sidr varietals originate from fewer than 200 registered apiaries in North Island New Zealand and Hadramaut Governorate Yemen, creating single-origin vulnerability.
- Input cost volatility:Commercial bee feed prices fluctuate with corn syrup futures and soybean meal indices, compressing margins for migratory pollination operators across the US Great Plains.
- Substitution pressure:Rice syrup adulterants and enzymatically inverted sugar blends pass basic density tests, eroding price premiums for unverified bulk honey in Asian processing hubs.
Strategic Opportunities
- Direct-to-pharmacy distribution:Specialized wound care clinics in German urban centers are bypassing wholesale importers to contract directly with MPI-graded New Zealand packers.
- Carbon credit stacking:Pollination service providers in Victoria and South Australia are registering hive density under Australian Carbon Credit Unit frameworks for agricultural offset buyers.
- Dual-use apiary models:Lavender and buckwheat honey producers in Provence and Alberta are monetizing agritourism visitation alongside bulk extraction contracts.
Industry Challenges
- Certification timeline compression:UMF and MGO grading protocols require 4-6 week laboratory turnaround, conflicting with just-in-time procurement schedules demanded by German pharmacy chains.
- Apiary labor scarcity:Commercial beekeeping requires seasonal migration competency and queen-rearing expertise that vocational programs in Argentina and Ukraine have failed to replenish.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Honey Market |
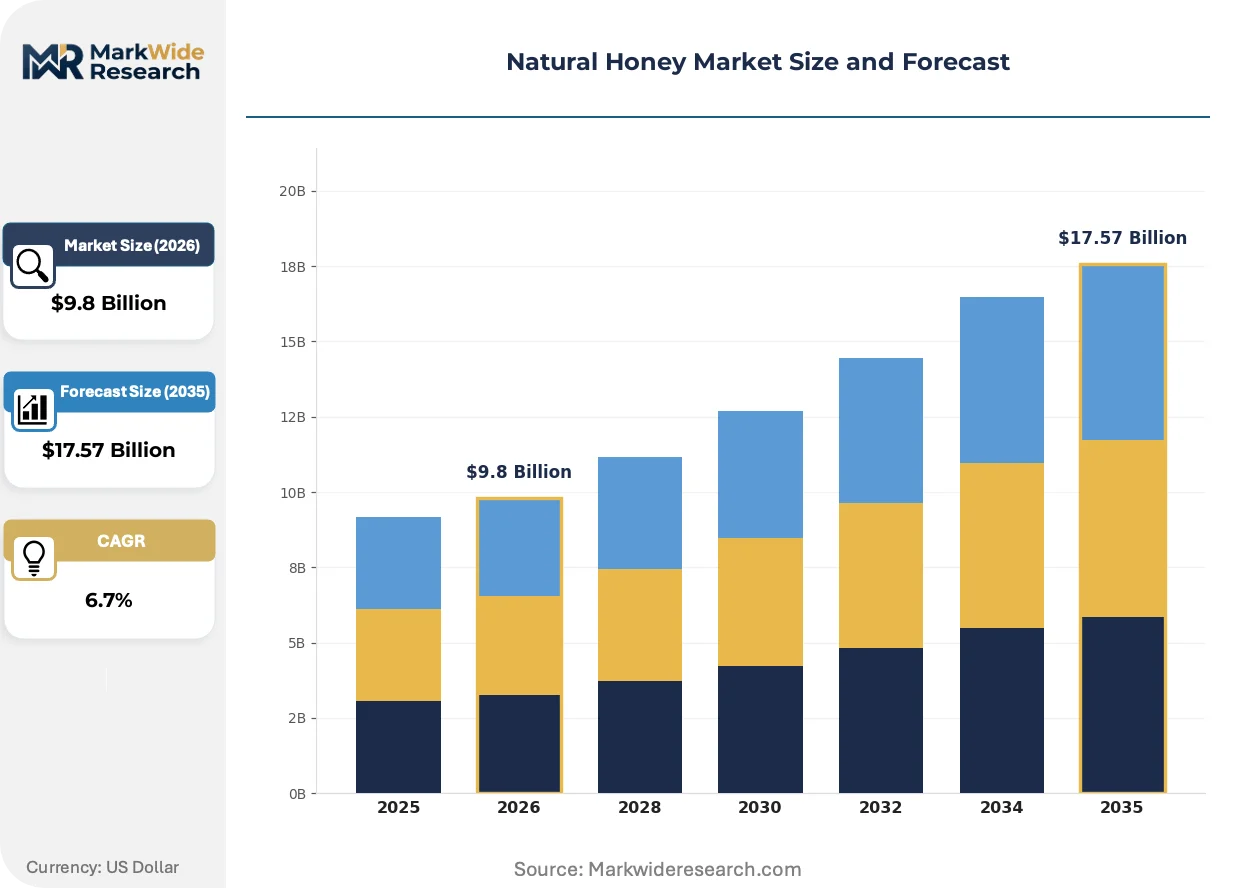
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.57 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Honey, Manuka Honey, Clover Honey, Organic Honey Application: Food & Beverage, Cosmetics, Nutraceuticals, Bakery Packaging Type: Glass Jars, Plastic Bottles, Squeeze Bottles, Bulk Containers Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Farmers' Markets |
| Companies Covered | India Honey Board, Russian Beekeeping Federation, China National Honey Corporation, Brazil Honey Industry Association, Mexico Honey Producers Union, Turkiye Honey Producers Association, Argentina Honey Exporters Cooperative, New Zealand Honey Company, Iran Honey Export Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Honey Market Emerging Trajectories
Distributed ledger infrastructure and enzymatic authentication assays are displacing paper-based chain-of-custody documentation, while consumer-facing QR traceability is becoming a non-negotiable shelf-price qualifier in premium channels.
Near-infrared spectroscopy paired with machine learning classifiers is modularizing origin verification workflows. German and Swiss importers now deploy portable devices at port-of-entry to screen for C4 plant sugar adulteration within 90 seconds per sample. This compression of testing latency is enabling dynamic release decisions that previously required 14-day laboratory queues.
The EU F-Gas Regulation and REACH frameworks are tightening residue limit enforcement for veterinary antibiotics and acaricides in imported honey. Third-country exporters to Germany, France, and Italy must now submit batch-level chromatography reports to ECHA-recognized laboratories. This regulatory stringency is disqualifying informal traders in Ukraine and Moldova from supermarket supply chains.
Pharmacy buyers are consolidating procurement around MPI-recognized grading tiers rather than generic organic certifications. Swiss and Austrian dispensaries now specify UMF 15+ or MGO 550+ minimums in tender specifications, displacing undifferentiated bulk supply. This preference compression is visible in Hamburg and Munich distribution networks where therapeutic-grade SKUs command shelf space previously allocated to commodity polyfloral varieties.
Natural Honey Market Segmentation
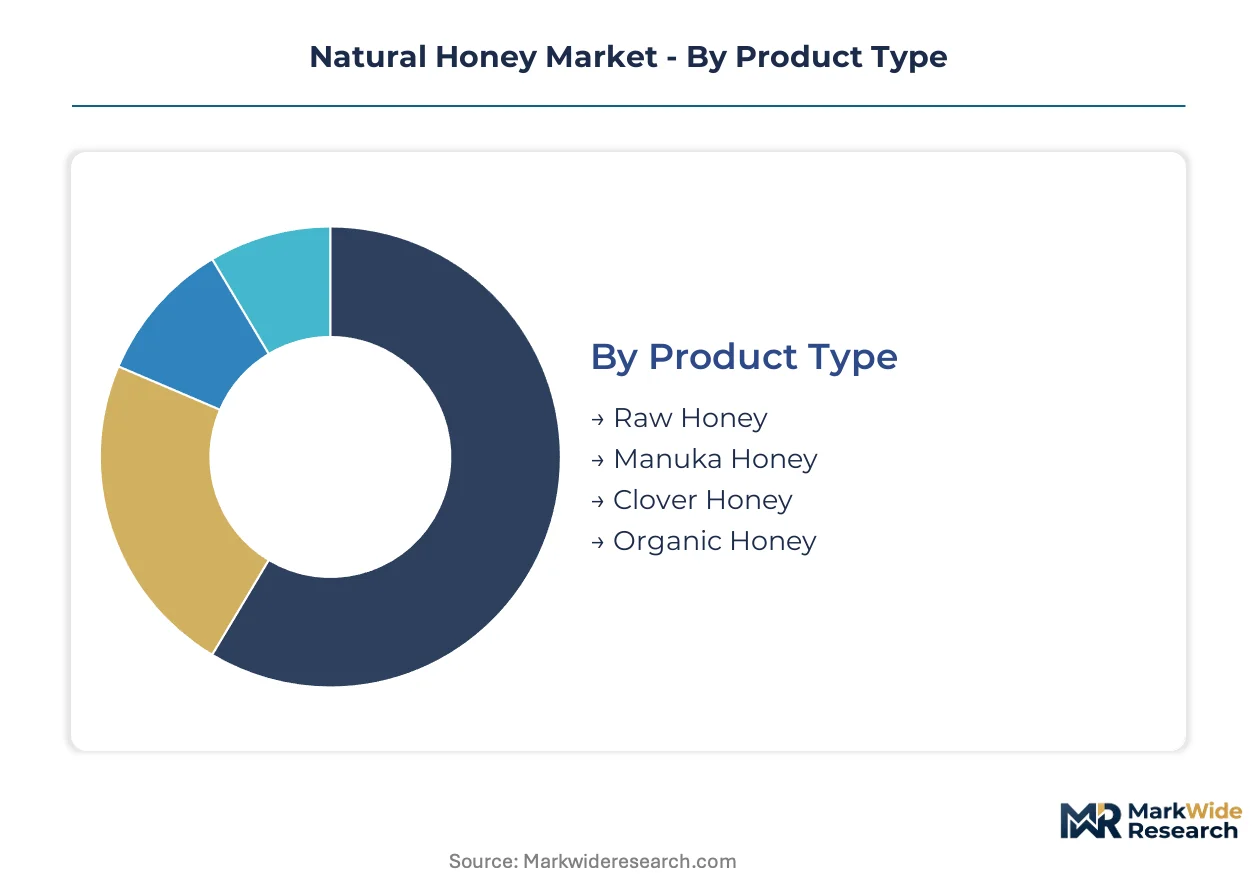
Segmentation in natural honey markets tracks how certification tiers, packaging formats, and channel access reshape procurement economics. Buyers now segment supply by traceability depth rather than origin alone, with UMF grading and blockchain verification commanding discrete price bands across German pharmacy and Swiss cosmetic formulator networks.
Product Type:
Upgrade cycles in honey procurement now center on therapeutic certification migration, as food-grade buyers shift toward bioactive-verified supply for margin protection.
- Raw Honey:Unprocessed extraction retaining pollen traces and enzymatic activity, typically packaged at 18-20% moisture. German organic retailers and Austrian direct-to-consumer channels concentrate procurement here, driven by EFSA traceability mandates that favor minimal-processing documentation.
- Manuka Honey:Leptospermum scoparium nectar with methylglyoxal concentrations graded via UMF or MGO protocols. Swiss wound care clinics and Munich pharmacy chains specify MPI-recognized tiers, creating supply scarcity for certified North Island apiaries.
- Clover Honey:Light-colored monofloral with rapid crystallization profiles, sourced heavily from Canterbury plains and Argentine pampas. Bakery and industrial sweetening applications dominate offtake.
- Organic Honey:Certified under EU 2018/848 or USDA NOP with third-party apiary audit trails. French and Italian supermarket private labels anchor volume demand.
Raw honey sits at the top of the volume ranking, with Manuka honey climbing the fastest as therapeutic-grade procurement expands beyond wound care into dermatological formulations.
Application:
Cost tier differentiation separates commodity sweetening from certified therapeutic supply, with laboratory verification expenses creating discrete margin pools.
- Food & Beverage:Industrial sweetening, table honey, and functional beverage formulations. Clover and polyfloral varieties flow through Hamburg and Rotterdam bulk terminals to European processors.
- Cosmetics:Humectant and antimicrobial ingredient for moisturizers and masks. Manuka and raw honey with low HMF levels concentrate demand from Provence and Swiss dermocosmetic formulators.
- Nutraceuticals:Probiotic support and immune modulation supplements. UMF 10+ grades from New Zealand packers supply Austrian and German pharmacy supplement lines.
- Bakery:Moisture retention and natural browning agent. Argentine clover honey dominates European industrial bakery procurement for cost-sensitive applications.
Food and beverage anchors absolute volume, while nutraceuticals gains share fastest as pharmacy channel specifications tighten around bioactive verification.
Packaging Type:
Customer type segmentation distinguishes retail-ready formats from industrial bulk, with sustainability mandates reshaping material selection across premium channels.
- Glass Jars:Premium positioning for organic and Manuka varieties with tamper-evident seals. German and Swiss supermarket shelves allocate disproportionate space to this format.
- Plastic Bottles:Lightweight PET and HDPE for mass-market table honey. Cost efficiency drives adoption across US and Australian conventional retail.
- Squeeze Bottles:Silicone valve dispensers targeting convenience-oriented households. Japanese and South Korean retail channels favor this format for breakfast table placement.
- Bulk Containers:Stainless steel drums and IBC totes for industrial bakery and beverage manufacturing. Rotterdam and Singapore port terminals handle highest throughput here.
Glass jars command the steepest price premiums, with squeeze bottles expanding most quickly in Asian convenience retail formats.
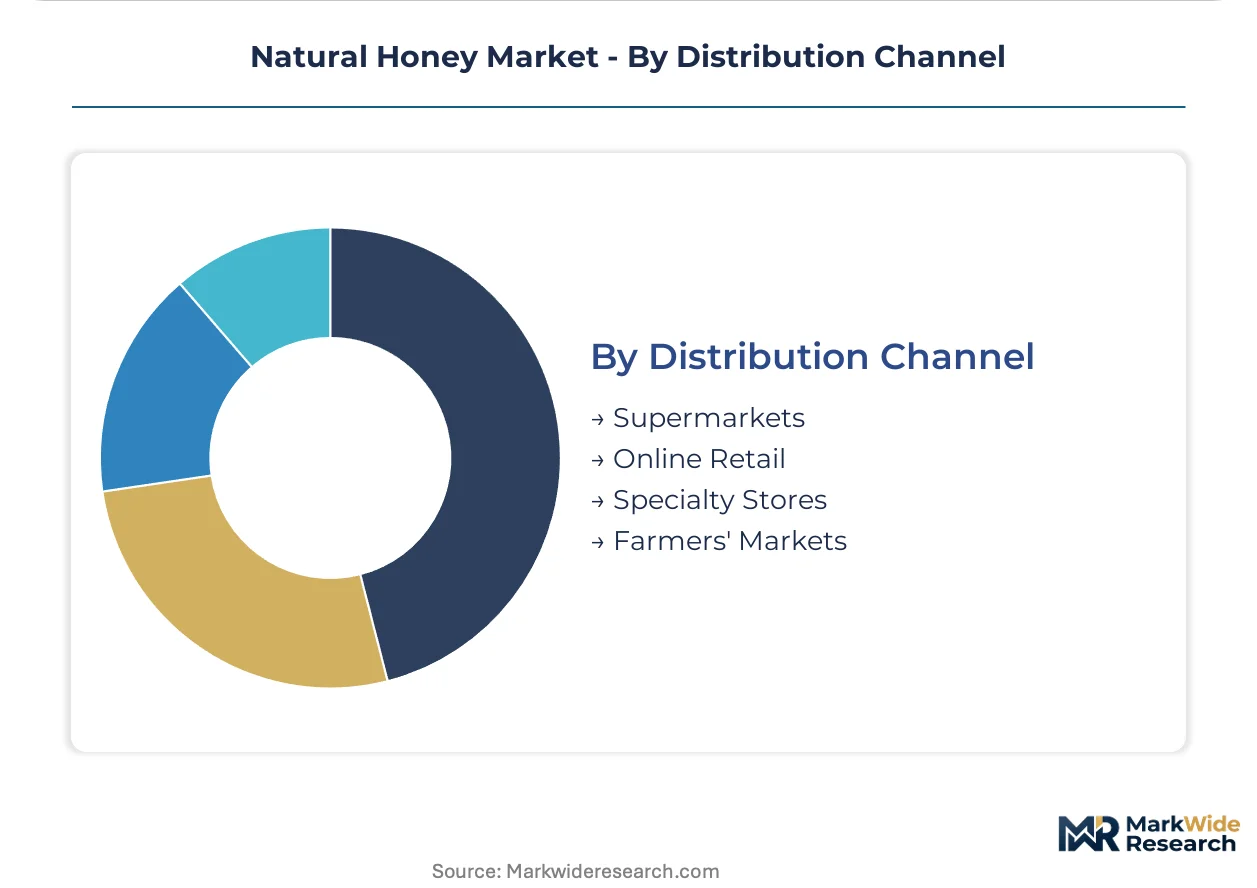
Distribution Channel:
Supply concentration patterns favor direct relationships in premium tiers, while commodity volumes flow through consolidated wholesale networks.
- Supermarkets:Mass-market penetration for private label and branded table honey. German Rewe and Edeka networks, plus French Carrefour hypermarkets, set shelf-space allocation standards.
- Online Retail:Direct-to-consumer subscription models and marketplace platforms. New Zealand packers leverage this channel to bypass European import wholesale margins.
- Specialty Stores:Delicatessen, organic shops, and pharmacy dispensaries. Swiss and Austrian urban centers concentrate demand for certified therapeutic grades.
- Farmers' Markets:Hyperlocal provenance verification and agritourism integration. Provence lavender honey and Alberta buckwheat producers monetize direct consumer relationships here.
Supermarkets retain the largest volume footprint, with specialty stores recording the steepest expansion trajectory as pharmacy procurement consolidates around MPI-recognized grading tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's pharmacy networks source therapeutic-grade supply at price multiples exceeding Argentina's bulk clover exports to European processors, revealing how certification depth splits procurement economics across origin markets.
Germany
Specialized pharmacy chains in Hamburg and Munich specify UMF 15+ or MGO 550+ minimums, displacing commodity polyfloral varieties from shelf space. The EU F-Gas Regulation and REACH frameworks mandate batch-level chromatography reports to ECHA-recognized laboratories for residue verification. Berlin-based organic retailers anchor procurement of raw honey with minimal-processing documentation under EFSA traceability mandates.
New Zealand
North Island apiaries supply MPI-recognized grading tiers to Swiss wound care clinics and Austrian dispensaries at volume multiples above food-grade benchmarks. The Ministry for Primary Industries enforces UMF and MGO protocols requiring 4-6 week laboratory turnaround. Canterbury plains operations concentrate clover honey production for industrial bakery offtake to European bulk terminals.
China
Hubei and Yunnan provinces host integrated apiary-to-bottling operations serving domestic retail and export markets. SAMR and GB standards govern identity and safety requirements for packaged honey. Shanghai port terminals handle outbound shipments to Southeast Asian processing hubs where rice syrup adulterants erode price premiums for unverified bulk supply.
Argentina
Pampas-region cooperatives navigate Mercosur tariff schedules while competing on bulk clover and polyfloral supply to Rotterdam and Hamburg processors. The national agricultural regulator enforces export certification for botanical origin claims. Buenos Aires-based exporters concentrate volume contracts for cost-sensitive European industrial bakery applications.
United States
California almond and blueberry growers contract commercial pollinator services deploying IoT-enabled hive monitoring platforms to reduce colony loss rates. The FDA enforces identity standards under 21 CFR 101.80 for honey labeling claims. Central Valley operations face margin compression from commercial bee feed price fluctuations tracking corn syrup futures and soybean meal indices.
Natural Honey Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with therapeutic-grade packers commanding discrete price bands while bulk exporters compete on volume throughput to industrial processors. The vendor base organizes around three strategic archetypes: integrated apiary-to-bottling operators with captive supply control, MPI-graded premium specialists serving pharmacy networks, and cooperative federations aggregating smallholder output for export. Dominant competitive moves include backward integration into queen-rearing and pollination service capabilities, plus geographic expansion through direct-to-pharmacy distribution bypassing wholesale import margins.
Within the cooperative federation tier, Argentina Honey Exporters Cooperative and Brazil Honey Industry Association represent aggregation models consolidating smallholder output for volume export to European bulk terminals. China National Honey Corporation anchors integrated operations spanning Hubei and Yunnan provinces with captive apiary supply chains. New Zealand Honey Company exemplifies premium-tier positioning through MPI-recognized grading protocols and Mānuka certification serving Swiss and Austrian therapeutic channels.
| Leading Market Players |
|---|
| India Honey Board |
| Russian Beekeeping Federation |
| China National Honey Corporation |
| Brazil Honey Industry Association |
| Mexico Honey Producers Union |
| Turkiye Honey Producers Association |
| Argentina Honey Exporters Cooperative |
| New Zealand Honey Company |
| Iran Honey Export Company |
| Others |
Supply Flow & Price Mechanics
Backward integration into captive apiary operations anchors both supply security and margin defense for New Zealand packers serving German pharmacy networks, while Argentine cooperatives remain exposed to commodity price swings through outsourced smallholder aggregation.
Pricing Analysis
Capacity additions in Canterbury plains clover operations are reshaping price floors for industrial bakery supply, compressing premiums that North Island Mānuka producers command through UMF grading. Three-tier pricing structure across therapeutic, certified organic, and commodity bulk levels separates MPI-recognized grades from EU organic seals from unverified polyfloral. Pricing pressure stems from rice syrup adulterants passing density tests in Asian processing hubs. Industrial bakery buyers in Rotterdam exhibit highest price sensitivity; Swiss wound care clinics show least.
Supply Chain Analysis
Direct-to-pharmacy channels handle therapeutic-grade demand from Hamburg and Munich dispensaries, bypassing wholesale import margins. Raw material flows concentrate in New Zealand, Argentina, and China, with hive equipment and commercial bee feed sourced from US and Brazilian suppliers. Supply chain risk centers on single-origin vulnerability for certified Mānuka from fewer than 200 registered North Island apiaries. Distribution runs through Rotterdam bulk terminals for industrial offtake and specialized cold-chain logistics for pharmacy-grade shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between EU REACH compliance costs and Argentine production economics creates margin capture opportunities for operators with dual-origin sourcing flexibility.
For Market Incumbents: Hedge against monofloral supply concentration by securing pollination service contracts with California almond growers that diversify revenue beyond extraction. Invest in blockchain traceability infrastructure ahead of digital mandate deadlines to defend pharmacy channel access against emerging MPI-graded competitors.
For New Entrants and Emerging Players: IoT-enabled hive monitoring platforms offer a technology-first wedge into commercial pollination services where colony loss rates drive replacement demand. Target Victorian and South Australian carbon credit registration frameworks as the most penetrable entry point, leveraging agritourism integration for dual-revenue apiary models.
For Investors and Strategic Acquirers: Roll-up economics work for fragmented smallholder cooperatives because certification capacity scarcity concentrates buyer power among ECHA-recognized laboratories. Acquire Argentine or Ukrainian aggregation platforms with existing export infrastructure rather than greenfield apiary development. Watch MPI grading protocol adoption rates as the inflection signal for therapeutic-grade margin sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Implementation | Compresses qualification timelines for EU pharmacy channel access under EFSA mandates. |
| Backward Integration into Queen Rearing | Secures genetic supply control against apiary labor scarcity in Argentina and Ukraine. |
| Carbon Credit Registration | Unlocks agricultural offset revenue streams for Victorian pollination service providers. |
| Direct-to-Pharmacy Distribution | Bypasses wholesale import margins for MPI-graded supply to German urban clinics. |
| Near-Infrared Spectroscopy Deployment | Enables 90-second adulteration screening at Rotterdam port terminals versus 14-day laboratory queues. |
Methodological Framework
Multiple input streams — primary interviews with commercial beekeepers and pharmacy procurement managers, customs trade data, EFSA regulatory filings, and MPI grading protocol documentation — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations encompassed apiary operators in North Island New Zealand and Canterbury plains, German organic retail category buyers, Swiss wound care formulators, and Argentine cooperative export managers. Secondary validation drew from ECHA residue limit databases, EU organic certification registries, and US FDA identity standard enforcement records.
Historical volume trajectories were cross-referenced against panel-based input from distribution channel participants across the projection horizon. The analytical framework modeled segmentation dimensions including product certification tier, packaging format, application end-use, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to base-year market sizing, with specific inputs from pollinator service contract values and therapeutic-grade premium tier trajectories.
The model holds under stable REACH enforcement intensity and continued MPI grading protocol recognition; deviation in EU digital traceability mandate timelines or Mānuka certification standard fragmentation would shift volume allocation assumptions. Periodic stress-testing of base assumptions against EFSA laboratory capacity expansion and commercial bee feed price volatility is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Cannabis-Infused Burger Market
Specialty Foods
Military Forces Ready to Eat Meals Market
Specialty Foods
Miso Market
Specialty Foods
Global Honey Market
Specialty Foods
Wheatgrass Products Market
Specialty Foods
Liquid Mushroom Market
Specialty Foods
Manuka Honey Market
Specialty Foods
Curculin Market
Specialty Foods
Hairball Cat Food Market
Specialty Foods
Therapeutic Dog Food Market
Specialty Foods
Wet Grain-Free Pet Food Market
Specialty Foods
Global Cordyceps Militaris Market
Specialty Foods
Mediterranean Kimchi-Style Vegetable Culture Starters Market
Specialty Foods
Carbonic Maceration Market
Specialty Foods
Middle East and Africa Free-From Food Market
Specialty Foods
Cultures Market