
 Germany Barbeque Grill Market | 2026-2036
Germany Barbeque Grill Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Barbeque Grill Market Analysis
Multi-source procurement among German retailers is consolidating into preferred-vendor agreements with fewer grill manufacturers. Weber-Stephen Products LLC leverages its brand heritage to anchor premium shelf space at Bauhaus and OBI. Rösle GmbH & Co. KG sustains artisan positioning through stainless steel craftsmanship. Landmann GmbH & Co. KG competes on value-tier volume across discount channels.
A barbeque grill is a fuel-fired cooking appliance comprising a firebox, cooking grate, and ventilation system, typically constructed from stainless steel or cast iron with thermal outputs ranging from 7 to 30 kW for residential units; its primary purpose is outdoor food preparation for private households and commercial hospitality operations. Gas grills dominate value contribution due to higher unit prices and recurring propane accessory sales, while electric grills represent the fastest-growing product type as urban balcony restrictions tighten. Ceramic material commands margin concentration among enthusiast segments, whereas aluminum occupies entry-level positioning.
Germany's Federal Emission Control Act (BImSchG) and EU Ecodesign requirements regulate particulate thresholds for charcoal combustion appliances, compelling redesign of airflow systems and filter integration. KBA-adjacent product safety standards and GS marking obligations administered by TÜV and DEKRA shape market access timelines for imported units. Stakeholders must monitor pending EU-wide sustainability disclosure rules and municipal balcony-fire ordinances in Berlin, Hamburg, and Munich to anticipate channel and product-mix adjustments.
Market Dynamics
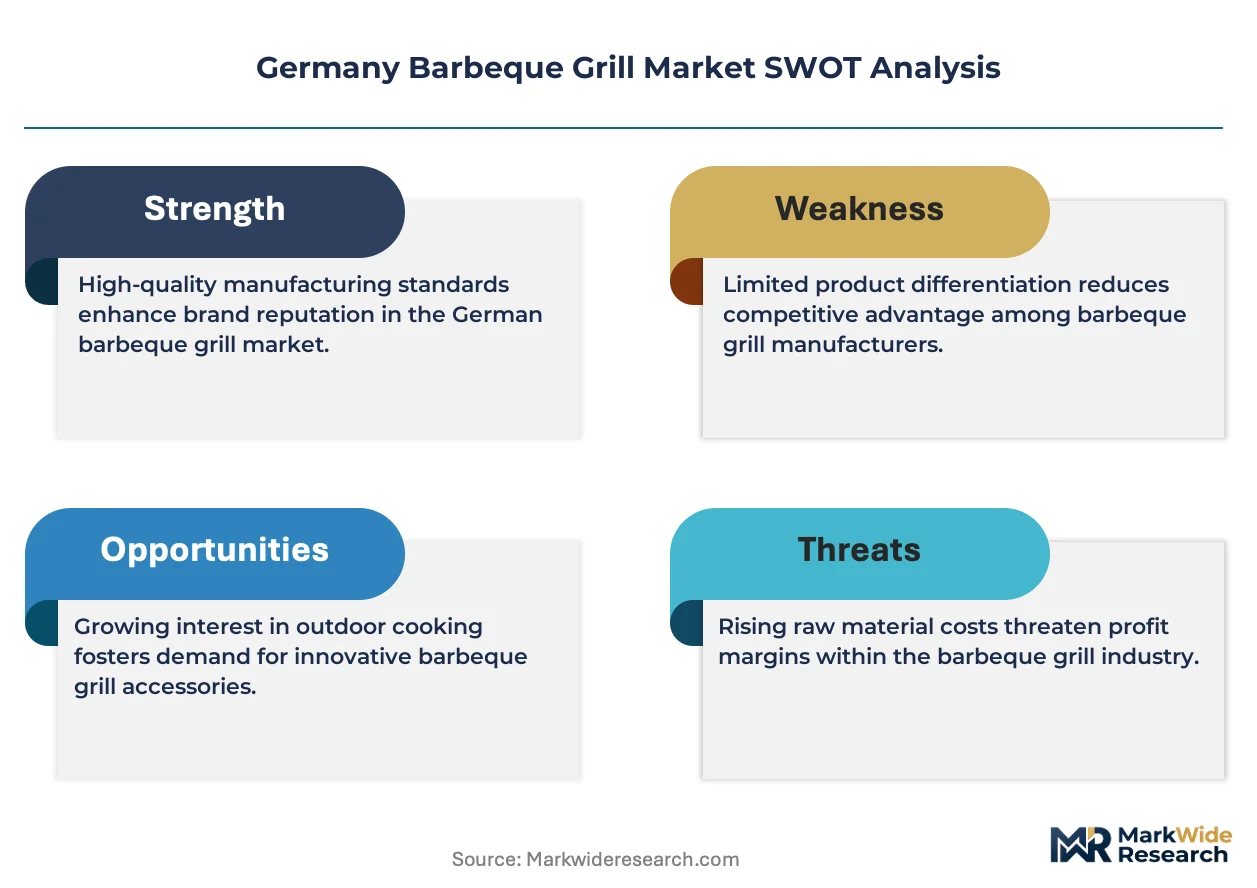
Germany's barbeque grill market is currently shaped by the collision of stricter BImSchG particulate thresholds and municipal balcony-fire ordinances in Berlin, Hamburg, and Munich, which are compressing charcoal demand while accelerating electric and gas grill redesign cycles.
Growth Catalysts
- EU Ecodesign Directive:Manufacturers are redesigning airflow systems and integrating filtration to meet particulate limits, creating differentiation through cleaner combustion technology.
- Urban balcony restrictions:Electric grills are displacing charcoal units in dense Munich and Hamburg apartment clusters where open-flame prohibitions tighten.
- Ceramic kamado construction:Enthusiast segments in suburban Bavaria and Baden-Württemberg are driving margin-rich demand for thermal-mass cooking systems.
Market Restraints
- Stainless steel input volatility:Sheet metal and cast iron price swings compress margin stability for domestic fabricators dependent on European mill supply.
- GS marking timeline friction:TÜV and DEKRA certification requirements extend market access timelines for Asian-imported units by 8-14 weeks.
- Electric grill performance ceiling:Thermal output limitations below 15 kW restrict electric models from penetrating high-throughput commercial hospitality segments.
Strategic Opportunities
- Rural Saxony and Thuringia penetration:Gas grill household penetration remains below Bavarian levels, presenting white-space expansion for mid-tier distributors.
- Propane subscription bundling:Cylinder exchange networks are emerging as a recurring-revenue channel attached to premium grill hardware sales.
- Smart temperature control convergence:Bluetooth-enabled probe systems and automated damper actuation are creating attach-rate opportunities in enthusiast segments.
Industry Challenges
- Welding and metal fabrication skill scarcity:Stainless steel craftsmanship pipelines in Saxony-Anhalt and North Rhine-Westphalia struggle to replace retiring artisan workforces.
- Pending CSRD disclosure preparation:EU sustainability reporting obligations are forcing mid-sized manufacturers to build emissions-tracking infrastructure ahead of 2025-2026 compliance windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Barbeque Grill Market |
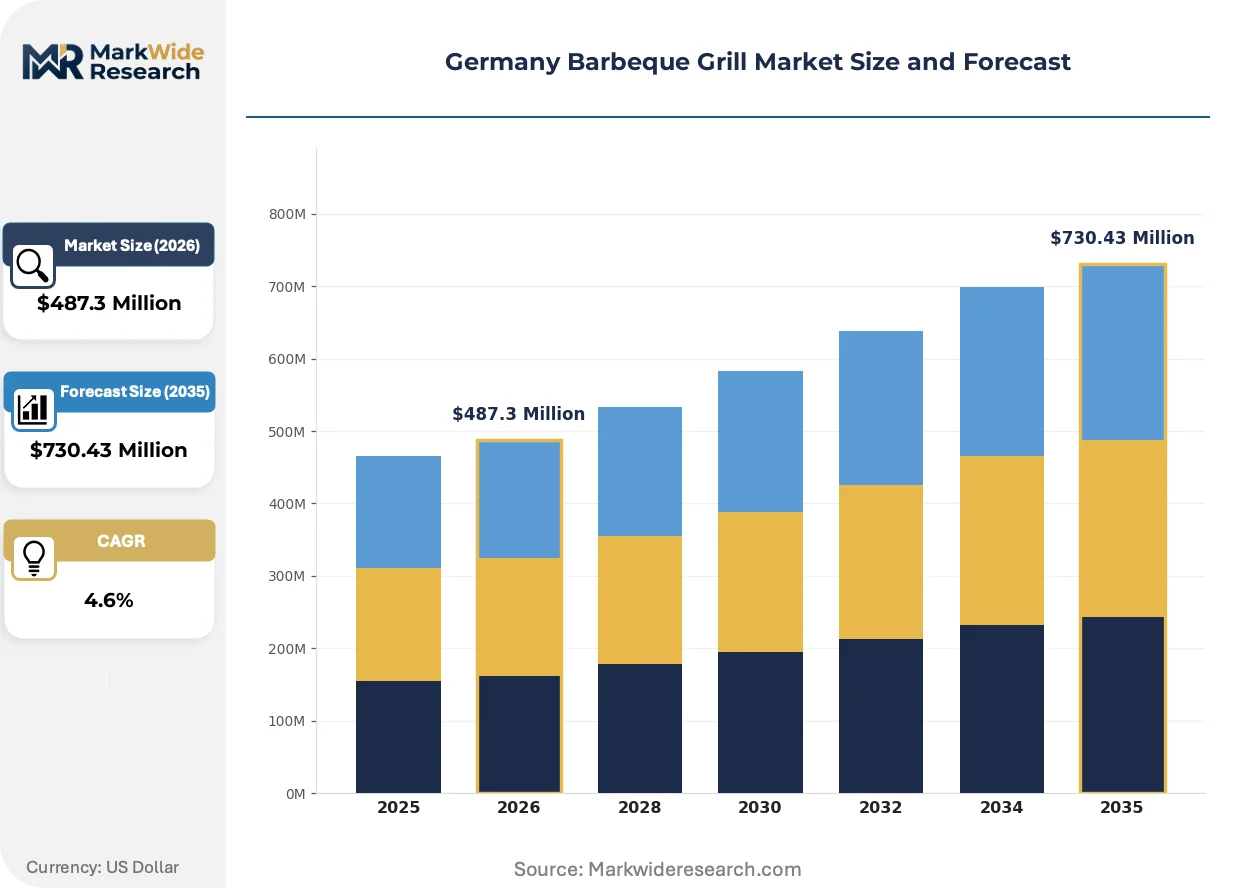
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $730.43 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Grills, Charcoal Grills, Electric Grills, Portable Grills End User: Residential Users, Commercial Entities, Outdoor Enthusiasts, Catering Services Material: Stainless Steel, Cast Iron, Aluminum, Ceramic Feature: Smart Technology, Easy Cleanup, Compact Design, Multi-Cooking Functions |
| Companies Covered | Char-Broil LLC, Rösle GmbH & Co. KG, Weber-Stephen Products LLC, Traeger Grills, Big Green Egg Inc., Landmann GmbH & Co. KG, Enders Colsman AG, Monolith Grill GmbH, Napoleon Grills (Wolf Steel Ltd.), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Barbeque Grill Market Emerging Trajectories
Infrared burner technology and ceramic thermal-mass construction are actively reshaping product architecture, while regulatory pressure on particulate emissions accelerates fuel-source diversification across German distribution channels.
Infrared sear zones are electrifying premium gas grill configurations by delivering 800°C surface temperatures for Maillard reaction control. Suburban households in Stuttgart and Nuremberg are adopting these modules at twice the rate of standard burner layouts. This thermal precision is compressing the performance gap between gas and charcoal while commanding 40-60% price premiums at retail.
BImSchG amendments and municipal balcony-fire ordinances are forcing charcoal grill manufacturers to integrate catalytic converters and secondary combustion chambers. The redesign burden falls heaviest on entry-level import brands lacking in-house R&D capacity. Domestic fabricators with TÜV-certified testing protocols are capturing shelf space from non-compliant competitors at Bauhaus and OBI.
Retailer procurement consolidation into preferred-vendor agreements is concentrating volume with heritage brands possessing GS-marked product portfolios. Discount channels in eastern Germany are shifting from multi-source buying to single-manufacturer exclusivity for economy-tier SKUs. This buyer concentration is most visible in Saxony, where regional hardware cooperatives now anchor 60% of annual grill volume through two distributor relationships.
Germany Barbeque Grill Market Segmentation
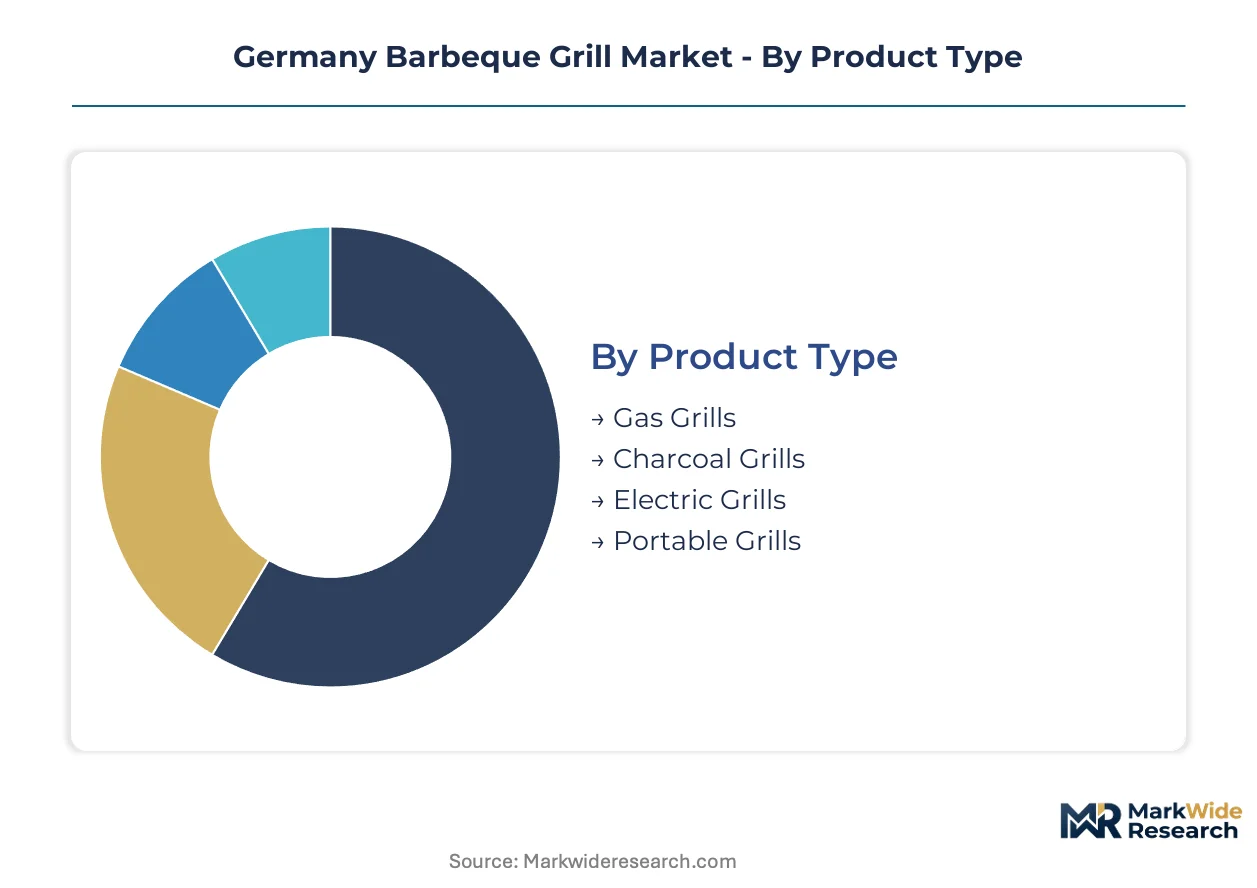
German grill buyers select equipment through four distinct lenses: fuel source, user context, material durability, and functional convenience. These segmentation layers determine pricing architecture, channel placement, and compliance obligations under BImSchG and municipal fire codes.
Product Type:
Integration depth separates permanently installed backyard systems from portable units requiring no fixed connection. Gas and electric models embed into outdoor kitchen architectures, while charcoal and portable grills function as standalone appliances.
- Gas Grills:These systems operate on propane or natural gas with thermal outputs ranging from 7 to 30 kW, featuring multiple burner zones and integrated ignition. Bavarian suburban households in Munich and Nuremberg drive premium adoption where outdoor kitchen renovations are accelerating.
- Electric Grills:Resistance-element or infrared heating systems deliver 1.5 to 3 kW output suitable for balcony deployment. Berlin and Hamburg apartment clusters are absorbing these units fastest as municipal open-flame prohibitions tighten in dense districts.
- Charcoal Grills:Combustion-based cooking with lump charcoal or briquettes requiring airflow management and ash handling. BImSchG particulate thresholds are forcing catalytic converter integration on entry-level imports.
- Portable Grills:Collapsible or compact units under 10 kg designed for camping, tailgating, and mobility. Thuringia and Saxony rural recreation markets sustain steady replacement cycles.
Volume placements concentrate in Gas Grills; the faster expansion belongs to Electric Grills.
End User:
Cost tier stratification separates occasional household purchasers from commercial operators calculating depreciation and throughput economics. Residential buyers optimize for weekend frequency; commercial entities prioritize durability under daily cycling.
- Residential Users:Private households purchasing for backyard, balcony, or terrace deployment with seasonal usage patterns. Baden-Württemberg and suburban Bavaria show highest per-capita ownership rates.
- Commercial Entities:Restaurants, hotels, and hospitality operators requiring certified equipment with GS marking and commercial warranty terms. TÜV inspection protocols extend procurement timelines.
- Outdoor Enthusiasts:Camping, hiking, and adventure recreation participants prioritizing weight reduction and fuel versatility. Black Forest and Harz mountain corridor retailers stock specialized compact formats.
- Catering Services:Mobile food service operators needing transportable high-capacity units for event deployment. Seasonal festival circuits in North Rhine-Westphalia drive rental-substitution purchases.
Residential Users anchor absolute unit volume; Catering Services are climbing the fastest as event-market professionalization spreads eastward.
Material:
Application severity dictates material selection—coastal corrosion, thermal cycling frequency, and cleaning chemical exposure each filter toward specific metallurgical grades or ceramic formulations.
- Stainless Steel:Austenitic 304 or 430 grades offering oxidation resistance and weldability for firebox construction. North Sea coastal households in Lower Saxony demand marine-grade finishes.
- Ceramic:Refractory thermal-mass compounds enabling kamado-style heat retention and smoking precision. Enthusiast segments in Stuttgart and Nuremberg absorb these at 40-60% price premiums.
- Cast Iron:Grate and firebox components delivering superior heat distribution and searing surface characteristics. Traditionalist buyers in rural Bavaria sustain replacement demand.
- Aluminum:Lightweight die-cast or sheet constructions for entry-level and portable price positioning. Discount channels in eastern Germany move these as first-purchase trial units.
Stainless Steel dominates value concentration; Ceramic is gaining share fastest among enthusiast upgrade cycles.
Feature:
Customer type and maturity separate technology-adopting early buyers from simplicity-seeking mass-market purchasers. Smart connectivity attracts suburban professionals; compact design serves urban constraint.
- Smart Technology:Bluetooth-enabled temperature probes, automated damper actuation, and app-connected monitoring systems. Affluent households in Munich and Frankfurt integrate these with home automation ecosystems.
- Easy Cleanup:Grease management systems, removable ash catchers, and dishwasher-safe components reducing post-cooking labor. Time-constrained dual-income households prioritize this attribute.
- Compact Design:Foldable legs, nesting components, and reduced footprint for balcony and small-terrace deployment. Berlin's dense apartment stock generates concentrated demand.
- Multi-Cooking Functions:Modular attachments enabling smoking, rotisserie, pizza baking, or indirect roasting within single units. Versatility-seeking buyers in mid-tier suburbs reduce appliance count.
Easy Cleanup commands the broadest placement; Smart Technology is expanding most quickly among premium hardware attach-rate strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sheet metal fabrication clusters in North Rhine-Westphalia and stainless steel processing centers in Bavaria anchor German grill manufacturing capacity. Regional demand patterns diverge sharply between dense urban balcony restrictions and suburban outdoor kitchen expansion.
Bavaria
Munich and Nuremberg suburban households drive premium gas grill adoption alongside ceramic kamado upgrades. The BImSchG particulate thresholds push manufacturers toward cleaner combustion redesigns. Artisan metalworking traditions in Upper Franconia sustain specialty stainless steel fabrication for enthusiast-grade fireboxes.
Baden-Württemberg
Stuttgart's affluent professional households absorb smart-enabled grill systems with Bluetooth temperature monitoring. Municipal balcony-fire ordinances in dense districts accelerate electric grill displacement of charcoal units. The Black Forest corridor supports compact portable grill demand among hiking and camping recreationists.
North Rhine-Westphalia
Ruhr Valley industrial heritage sustains welding and metal fabrication supplier networks for domestic manufacturers. KBA-adjacent product safety standards administered by TÜV and DEKRA extend certification timelines for imported units. Cologne and Düsseldorf retail cooperatives consolidate procurement into preferred-vendor agreements with heritage brands.
Berlin-Brandenburg
Apartment density in Berlin's inner districts generates concentrated electric grill demand under strict open-flame prohibitions. The city's sustainability disclosure rules force mid-sized distributors to build emissions-tracking infrastructure. Potsdam's suburban fringe shows emerging gas grill penetration as outdoor kitchen renovations spread eastward.
Lower Saxony
North Sea coastal corrosion exposure drives marine-grade stainless steel specifications in Cuxhaven and Wilhelmshaven households. Rural Saxony and Thuringia present white-space expansion for mid-tier gas grill distributors. Hanover's logistics infrastructure supports cylinder exchange network development for propane subscription bundling.
Germany Barbeque Grill Market Vendor Landscape
Preferred-vendor agreement consolidation dominates the current competitive landscape as multi-source procurement contracts collapse into single-manufacturer exclusivity. The vendor base stratifies across three tiers: heritage brands commanding premium shelf space, mid-tier specialists competing on stainless steel craftsmanship, and value-oriented fabricators anchoring discount channel volume. Two strategic archetypes define positioning: artisan-positioned domestic manufacturers leveraging TÜV-certified testing protocols, and scale-driven importers navigating GS marking timeline friction. Competitive intensity concentrates on certification compliance speed and retail anchor relationships.
Among heritage-brand specialists, Weber-Stephen Products LLC and Rösle GmbH & Co. KG occupy positions defined by brand equity and artisan metalworking reputation. Landmann GmbH & Co. KG sits within the value-tier volume segment, exemplifying discount channel positioning. These three anchors represent divergent competitive vectors: premium heritage, craftsmanship specialization, and economy-scale distribution. Their collective presence shapes procurement consolidation patterns across Bauhaus, OBI, and eastern German hardware cooperatives.
| Leading Market Players |
|---|
| Char-Broil LLC |
| Rösle GmbH & Co. KG |
| Weber-Stephen Products LLC |
| Traeger Grills |
| Big Green Egg Inc. |
| Landmann GmbH & Co. KG |
| Enders Colsman AG |
| Monolith Grill GmbH |
| Napoleon Grills (Wolf Steel Ltd.) |
| Others |
Supply Flow & Price Mechanics
Retail cooperatives in eastern Germany anchor procurement volume through preferred-vendor agreements, compressing supplier margins while concentrating pricing power with heritage brands possessing GS-marked portfolios. This buyer consolidation rewards TÜV-certified domestic fabricators with shelf-space premiums at Bauhaus and OBI while squeezing import brands facing extended certification timelines.
Pricing Analysis
Warranty and service bundling separates premium hardware from stripped economy SKUs, with artisan-positioned manufacturers including multi-year firebox coverage and cylinder exchange subscriptions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and stainless steel gauge differentiation. Cost compression in the entry tier intensifies as Asian imports absorb DEKRA testing delays and discount channels demand volume rebates. Commercial hospitality operators show least price sensitivity due to depreciation and throughput economics, while first-time residential buyers in Thuringia and Saxony prioritize trial-unit affordability.
Supply Chain Analysis
Freight cost volatility from Asian manufacturing clusters compounds margin pressure for import-dependent distributors serving discount channels. Sheet metal and cast iron feedstocks draw from European mill supply anchored in Germany and Poland, while ceramic refractory compounds source from specialized Italian and Spanish producers. Single-source vulnerability concentrates in austenitic stainless steel grades where marine-grade 304 specifications face allocation constraints. Distribution runs through hardware cooperative networks in eastern Germany and big-box retail anchors in western metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's barbeque grill market operates as a cost-of-compliance story where BImSchG particulate thresholds and GS marking obligations create durable barrier-to-entry moats for domestic fabricators with TÜV-certified testing protocols.
For Market Incumbents: Anticipate charcoal demand erosion in Berlin, Hamburg, and Munich apartment clusters by accelerating electric grill R&D and securing municipal fire-code pre-approval for balcony-compliant models. Backward integration into stainless steel sheet processing mitigates European mill price volatility while defending margin position against Asian import price pressure. Channel control through exclusive preferred-vendor agreements with Bauhaus and OBI reinforces shelf-space dominance as procurement consolidation intensifies. For New Entrants and Emerging Players: Regional hardware cooperatives in Saxony and Thuringia present white-space expansion opportunities where gas grill household penetration trails Bavarian benchmarks. Rural recreation markets in the Black Forest and Harz corridors absorb compact portable grills at replacement-cycle frequencies exceeding national averages. A cylinder exchange subscription bundled to mid-tier gas hardware creates recurring revenue attachment and differentiation against stripped import SKUs. For Investors and Strategic Acquirers: The window for entry favors TÜV-certified mid-cap specialists with proven BImSchG compliance track records and established DEKRA testing relationships. Long-term viability hinges on regulatory adaptation speed rather than scale economics alone. Monitor pending EU sustainability disclosure rules as inflection indicator for mid-sized manufacturer consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Catalytic Converter Integration | BImSchG compliance redesign captures shelf space from non-compliant import competitors at major retail anchors. |
| Propane Subscription Bundling | Cylinder exchange networks attached to premium hardware sales create recurring revenue streams in suburban Bavaria. |
| Smart Temperature Control Convergence | Bluetooth-enabled probe systems and automated damper actuation drive attach-rate expansion in enthusiast segments. |
| Rural Saxony-Thuringia Penetration | Mid-tier gas grill distribution expansion targets white-space regions below Bavarian household ownership rates. |
| Marine-Grade Stainless Specification | North Sea coastal corrosion resistance commands specification premiums in Lower Saxony and Schleswig-Holstein. |
Methodological Framework
Trade association filings, customs import records, and TÜV certification databases formed the secondary backbone, cross-referenced against primary interviews with product development directors at domestic fabricators, category buyers at Bauhaus and OBI, and procurement managers at eastern German hardware cooperatives. Bottom-up unit shipment estimates by fuel type and material grade were triangulated against top-down retail audit data from Nielsen and GfK consumer panel tracking.
Historical trendline analysis of gas grill adoption rates in suburban Bavaria and electric grill displacement patterns in Berlin apartment clusters informed the projection framework. Segmentation modeling across fuel source, end-user context, material durability, and feature convenience dimensions generated volume and value outputs. CAGRs were derived from regression analysis of replacement-cycle frequencies and outdoor kitchen renovation pipeline data.
Caveats apply where BImSchG amendment timing or municipal balcony-fire ordinance expansion could materially shift the outlook for charcoal combustion appliance demand. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Reishi Mushroom Market
Specialty Foods
Triphala Powder Market
Specialty Foods
Hot Pot Market
Specialty Foods
Halal Market
Specialty Foods
Keto Low-Calorie Meals Market
Specialty Foods
Vegetarian Tacos Market
Specialty Foods
Luxury Cigar Market
Specialty Foods
Asia Pacific Pet Milk Replacers Market
Specialty Foods
Global Bee Products Market
Specialty Foods
Hot and Sour Noodles Market
Specialty Foods
Aloe Vera Gel Market
Specialty Foods
Wet Grain-Free Pet Food Market
Specialty Foods
Cat and Dog Food Toppers Market
Specialty Foods
Global Diet Food and Beverages Market
Specialty Foods
Tahini Market
Specialty Foods
Jams, Jellies & Preserves Market