
 Fermented Black Beans Market | 2026-2036
Fermented Black Beans Market Size, Share, and Industry Trends Forecast 2026-2036
Fermented Black Beans Market Foresight
The gap between artisanal heritage batches and mass-produced commodity lines is shifting how buyers evaluate fermented black beans. Lee Kum Kee leverages century-old fermentation protocols to command shelf space in premium Asian grocery channels. Haitian Flavoring anchors its position through backward integration into soybean sourcing across southern China. Kikkoman competes by applying Japanese koji expertise to black bean fermentation, creating hybrid products for fusion cuisine markets.
Fermented black beans are salted, dried soybeans inoculated with Aspergillus oryzae or similar molds, then aged in brine for weeks to develop umami depth and dark color; manufacturers control moisture content between 15-25% to stabilize shelf life without refrigeration. The ingredient serves primarily as a savory base in Chinese cooking, anchoring sauces for steamed fish, stir-fried clams, and mapo tofu preparations. Dried and paste formats dominate volume through restaurant procurement and industrial sauce production, while powdered variants capture emerging demand from snack seasoning and ready-meal manufacturers seeking clean-label umami alternatives. Canned presentations retain strength in Western retail where convenience and extended shelf life reduce purchase hesitation among unfamiliar consumers.
China's SAMR enforces GB standards for fermented soybean products that dictate permissible mold strains, salt content thresholds, and heavy metal limits, directly shaping which facilities qualify for export certification. The USDA and FDA in the United States impose additional phytosanitary and labeling requirements that filter out smaller producers lacking documentation infrastructure. Stakeholders must monitor evolving allergen disclosure rules and clean-label certification programs, as these criteria increasingly determine retail access in premium channels across multiple jurisdictions.
Market Dynamics
Heritage fermentation protocols from Guangdong province are colliding with industrial scale demands as Asian grocery retail expands beyond traditional enclaves into suburban North American and European markets. This tension between artisanal batch integrity and mass-production efficiency is forcing suppliers to bifurcate their facility investments.
Growth Catalysts
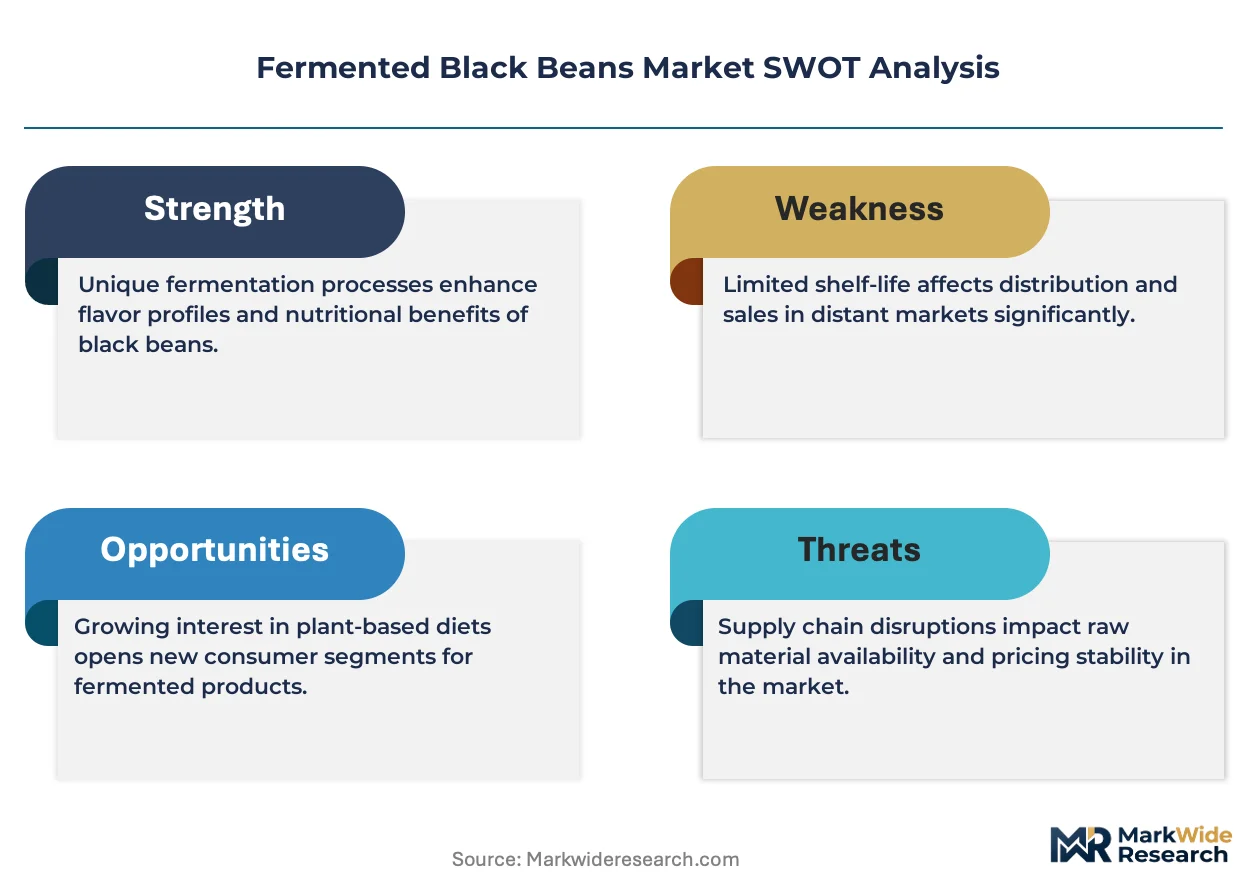
- GB Standards Export Alignment:China's SAMR certification requirements for fermented soybean products create a de facto quality floor that qualified facilities leverage to access premium retail channels in multiple jurisdictions.
- Fusion Cuisine Adoption:Japanese koji expertise applied to black bean fermentation generates hybrid umami profiles that capture demand from experimental restaurant concepts seeking differentiated sauce bases.
- Clean-Label Snack Seasoning:Powdered fermented black bean variants displace synthetic MSG in ready-meal and snack manufacturing as manufacturers pursue natural umami positioning without E-number additives.
Market Restraints
- Soybean Input Volatility:Southern China's concentrated soybean sourcing regions expose processors to climate-driven crop variability and regional procurement cost swings.
- Heritage Production Bottleneck:Guangdong's legacy fermentation clusters lack capacity expansion flexibility due to urban encroachment and traditional facility footprints.
- Refrigeration-Independent Substitution:Dried mushroom powders and yeast extracts compete for shelf-stable umami positioning in Western retail where consumer familiarity advantages substitutes.
Strategic Opportunities
- Suburban Asian Retail Penetration:North American markets outside traditional Chinatowns present underdeveloped distribution for premium paste and dried formats in mainstream grocery.
- USDA Organic Certification Pathway:Emerging clean-label certification programs create positioning differentiation for processors willing to document fermentation inputs and salt sourcing.
- Industrial Sauce Partnerships:Ready-meal manufacturers seeking fermented depth without in-house fermentation capability offer contract processing volume for certified facilities.
Industry Challenges
- Multi-Jurisdiction Allergen Labeling:FDA disclosure requirements for soy and mold-derived proteins demand packaging redesign and translation infrastructure that smaller exporters lack.
- Batch-to-Batch Standardization:Heritage fermentation methods resist moisture-content standardization between 15-25%, complicating shelf-life guarantees for mass retail contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fermented Black Beans Market |
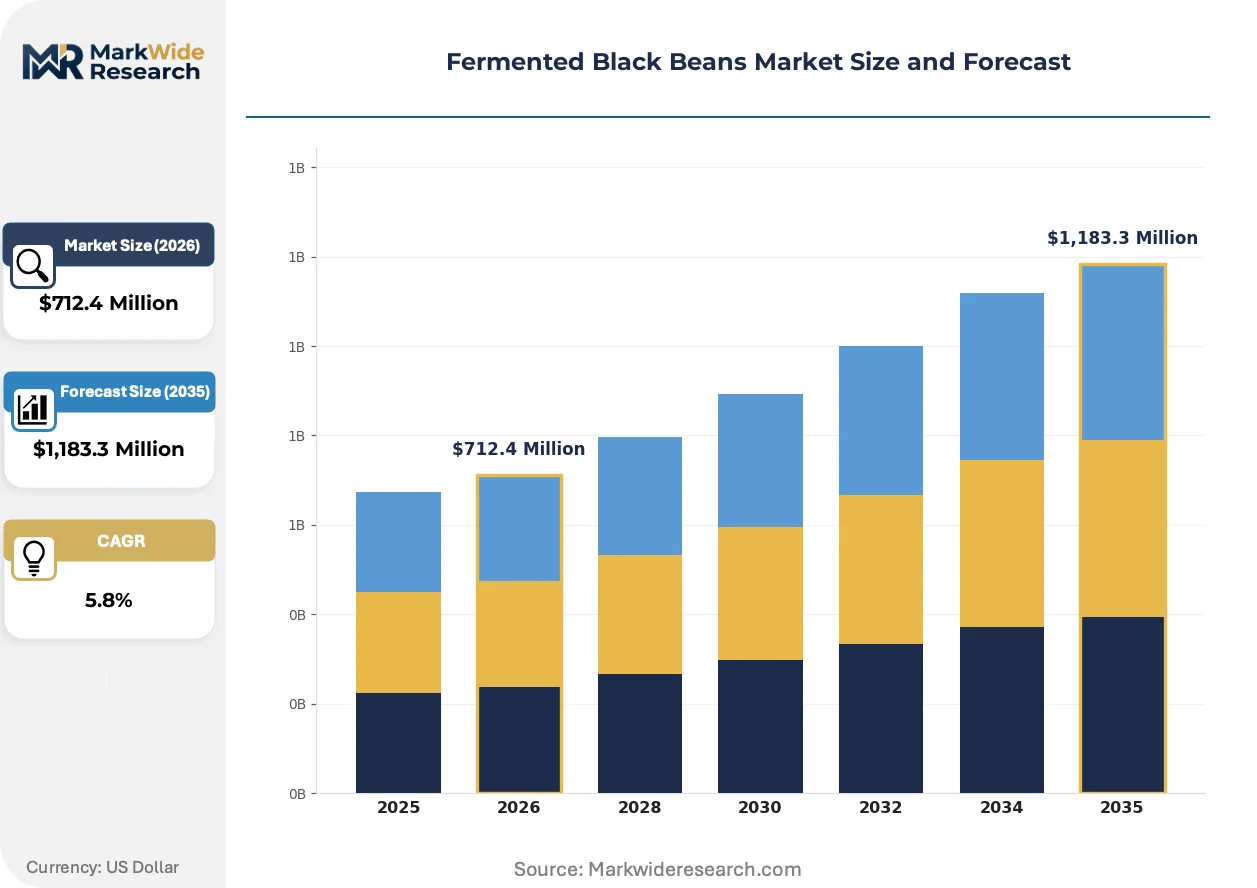
| Market Size in 2026 | $712.4 Million |
| Market Size in 2035 | $1,183.3 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned, Dried, Paste, Powdered End User: Household, Restaurants, Food Manufacturers, Catering Services Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale Application: Asian Cuisine, Sauces, Snacks, Seasoning |
| Companies Covered | Lee Kum Kee, Haitian Flavoring, Kikkoman, Pearl River Bridge, Amoy Food, Wangzhihe, Lao Gan Ma, CJ CheilJedang, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fermented Black Beans Market Shifts & Advancements
Controlled-environment fermentation technology is eroding the geographic monopoly of heritage production clusters. These advances permit quality replication outside traditional terroirs while compressing aging timelines.
Continuous-flow fermentation systems with precision humidity and temperature modulation are overtaking earthenware vessel aging in new facility construction. Industrial sauce manufacturers in Thailand and Vietnam are adopting these systems to bypass import dependence on Guangdong-sourced beans. The technology is overtaking artisanal methods in mid-tier procurement channels where consistency and volume scale outweigh provenance claims.
REACH-compliant packaging material standards are reshaping export logistics for European-bound shipments. The regulation mandates migration testing for salt-brine contact surfaces, forcing processors to replace traditional ceramic and certain polymer containers. Dried-format suppliers face accelerated compliance timelines as German and Dutch retail chains enforce certification pre-qualification for shelf placement.
Direct-procurement relationships between restaurant groups and heritage processors are compressing traditional distributor layers. Multi-unit Asian cuisine operators in Canada and Australia are establishing annual volume contracts with named Guangdong facilities, bypassing import-export intermediaries. This pattern concentrates most visibly in seafood-centric chains where fermented black bean sauce differentiation anchors menu identity.
Fermented Black Beans Market Segmentation
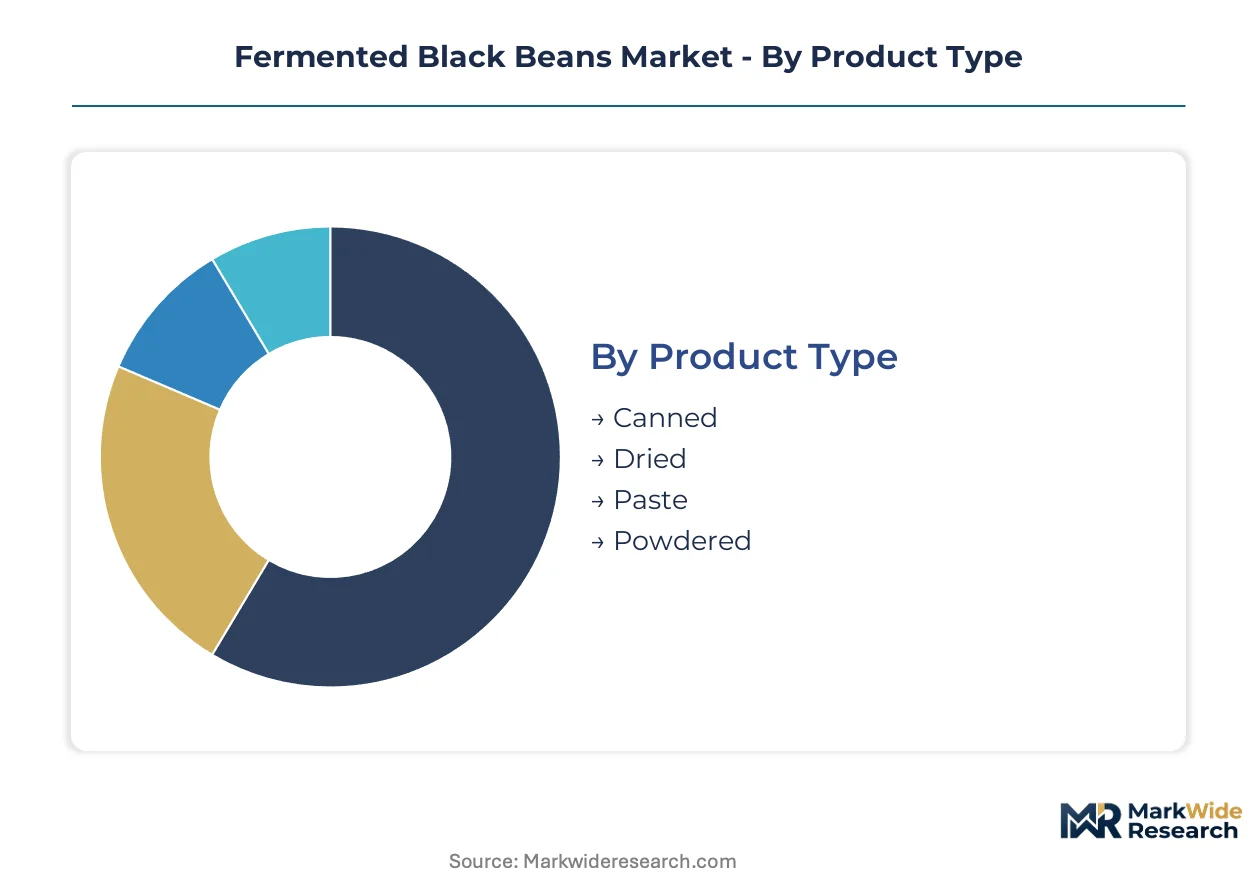
Segmentation in fermented black beans reveals how procurement patterns diverge between heritage-driven restaurant supply and mass-market retail formats. Understanding these splits exposes where margin concentrates and which channels reward quality certification versus price competition.
Product Type:
Buyers choose formats based on shelf-life requirements and kitchen workflow integration, with moisture content and packaging driving the decision calculus.
- Dried:Whole fermented beans with 15-25% controlled moisture content deliver the longest ambient stability without refrigeration. Restaurant kitchens across Guangdong province and North American Chinatowns favor this format for sauce-building flexibility and authentic texture in steamed fish preparations.
- Paste:Ground and salted preparations reduce prep time for high-volume operators. Food manufacturers in Thailand and Vietnam source paste for industrial sauce production where consistency and rapid incorporation matter more than artisanal provenance.
- Canned:Brine-packed beans in metal containers target Western retail channels where convenience and extended shelf life reduce purchase hesitation among unfamiliar consumers. REACH-compliant packaging migration testing now filters European-bound shipments.
- Powdered:Dehydrated fine-ground variants displace synthetic MSG in snack seasoning and ready-meal manufacturing. Clean-label positioning drives procurement from manufacturers seeking natural umami without E-number additives.
Volume sits with Dried; growth tilts toward Powdered.
End User:
Procurement scale and quality tolerance separate institutional buyers from household purchasers, with certification requirements widening the gap.
- Restaurants:Asian cuisine operators from Vancouver to Sydney establish direct annual contracts with named Guangdong heritage facilities. Menu differentiation in seafood-centric chains depends on specific fermentation protocols that mass production cannot replicate.
- Food Manufacturers:Industrial sauce producers and ready-meal assemblers seek contract processing volume from SAMR-certified facilities. These buyers prioritize batch standardization and documentation infrastructure over terroir claims.
- Household:Individual consumers purchase smaller formats through Asian grocery retail expanding into suburban North American and European markets. Familiarity gaps in these new locations favor canned presentations with explicit usage instructions.
- Catering Services:Large-volume event and institutional feeders balance cost control with consistent supply. These operators typically source through wholesale layers rather than direct heritage relationships.
Procurement concentration favors Restaurants; Catering Services expand most quickly as Asian cuisine penetrates corporate and institutional channels.
Distribution Channel:
Channel selection determines which quality tiers reach which buyer segments, with certification acting as the gatekeeper.
- Specialty Stores:Asian grocery chains and independent importers curate heritage-labeled products for authenticity-seeking consumers. These channels reward GB standards compliance and named provenance with premium positioning.
- Wholesale:Restaurant supply and foodservice distributors move volume formats to institutional kitchens. SAMR export certification and USDA phytosanitary documentation determine supplier eligibility at this tier.
- Supermarkets:Mainstream Western retail requires FDA-compliant allergen labeling and consumer-friendly packaging that smaller Guangdong exporters struggle to produce. Canned formats dominate this channel.
- Online Retail:Direct-to-consumer platforms connect heritage processors with diaspora communities and experimental home cooks. Logistics complexity limits this channel to dried and powdered formats with stable shipping profiles.
Wholesale commands current volume; Online Retail gains share fastest as direct-procurement relationships compress traditional distributor layers.
Application:
End-use function dictates fermentation intensity specifications and format requirements, with fusion experimentation opening new demand pockets.
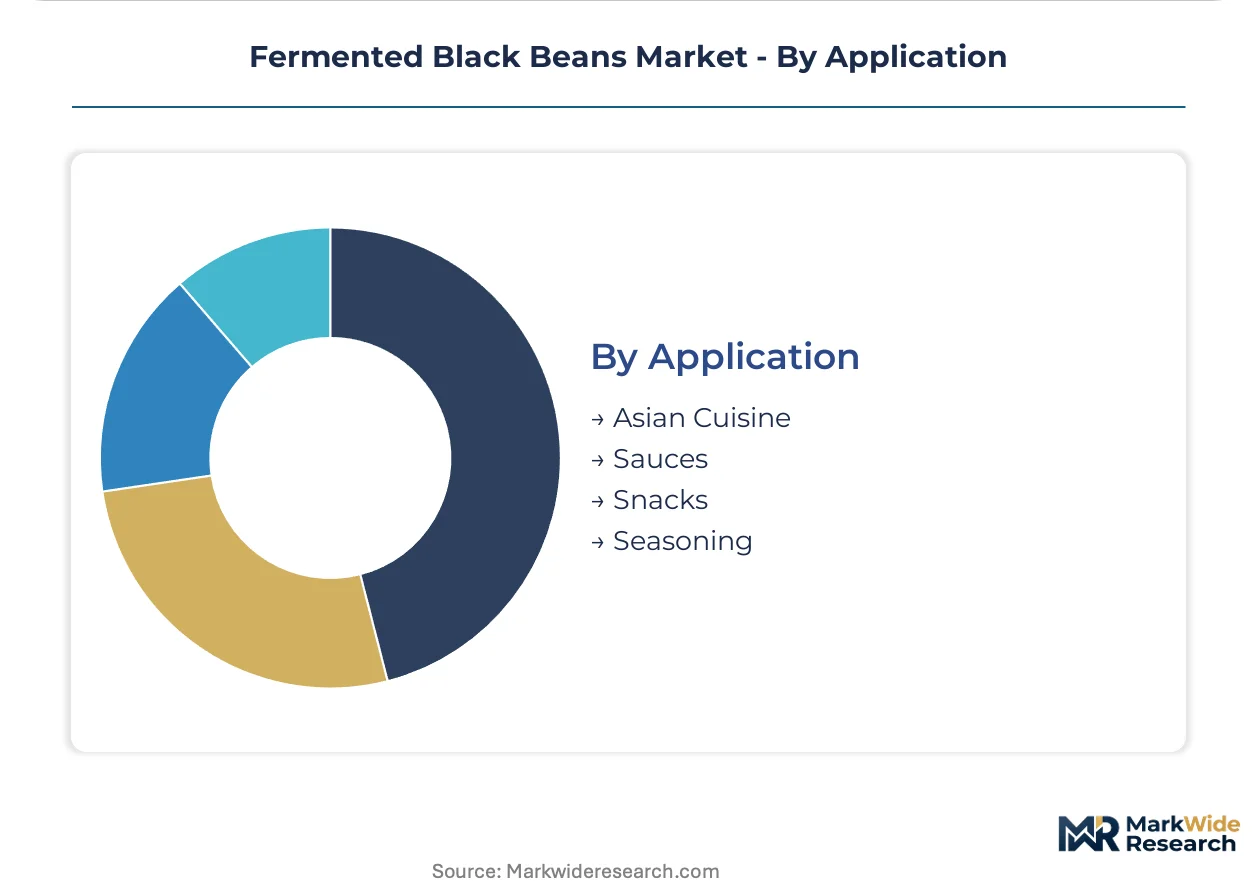
- Asian Cuisine:Traditional Chinese preparations—steamed fish, stir-fried clams, mapo tofu—anchor demand for heritage-processed dried beans. Guangdong production clusters supply this segment through both domestic premium brands and international distributors.
- Sauces:Industrial and artisanal sauce production consumes paste and dried formats in roughly equal measure. Kikkoman applies Japanese koji expertise to black bean fermentation for hybrid umami profiles targeting fusion cuisine markets.
- Seasoning:Powdered variants serve as clean-label umami bases in compound seasonings and marinade blends. Snack manufacturers substitute these for synthetic additives to meet retailer clean-label certification programs.
- Snacks:Emerging application in flavored nuts, chips, and extruded products leverages powdered fermented black bean for savory depth without MSG. Product development cycles in this segment move faster than traditional sauce applications.
Asian Cuisine retains volume dominance; Snacks demonstrate the steepest expansion trajectory as flavor innovation crosses category boundaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangzhou anchors fermented black bean production through heritage fermentation clusters in Guangdong province, where centuries-old protocols supply both domestic premium brands and international distributors seeking authentic umami depth.
China
Guangdong province concentrates heritage production capacity for fermented black beans, with SAMR enforcing GB standards that dictate permissible mold strains and salt content thresholds for export certification. Pearl River Delta facilities supply dried and paste formats to Asian grocery chains across North America and Europe. Urban encroachment in Foshan and Shunde limits traditional facility expansion, forcing bifurcated investments between artisanal preservation and industrial-scale construction.
United States
Asian cuisine restaurants in California and New York drive procurement of dried and paste formats as operators expand beyond traditional Chinatowns into suburban markets. FDA allergen disclosure requirements for soy and mold-derived proteins filter out smaller Guangdong exporters lacking documentation infrastructure. Los Angeles and San Francisco Bay Area distribution hubs concentrate direct-procurement relationships between multi-unit chains and heritage processors.
Canada
Vancouver and Toronto metropolitan areas anchor demand from seafood-centric restaurant chains where fermented black bean sauce differentiation anchors menu identity. Health Canada phytosanitary requirements parallel USDA standards, creating dual compliance burdens for Chinese exporters. Direct annual volume contracts between named Guangdong facilities and Canadian restaurant groups compress traditional import-export intermediary layers.
Germany
REACH-compliant packaging material standards reshape export logistics for European-bound shipments, mandating migration testing for salt-brine contact surfaces. German retail chains in Berlin and Hamburg enforce certification pre-qualification for shelf placement ahead of regulatory deadlines. Dried-format suppliers face accelerated compliance timelines to maintain access to premium European grocery channels.
Australia
Sydney and Melbourne restaurant groups establish direct procurement with Guangdong heritage processors, bypassing distributors for annual volume contracts. TGA alignment with international food safety standards facilitates import clearance for SAMR-certified facilities. Powdered format demand emerges from snack manufacturers seeking clean-label umami alternatives to synthetic additives.
Fermented Black Beans Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tiers, with SAMR export qualification and heritage provenance claims separating price bands. The vendor base clusters around three strategic archetypes: century-old fermentation houses leveraging traditional protocols, industrial flavor conglomerates with backward integration into soybean sourcing, and cross-border specialists applying alternative koji expertise to hybrid product development. Capacity expansion and direct-procurement relationship building constitute the dominant competitive moves as suburban retail penetration accelerates.
Within the heritage-protocol tier, Lee Kum Kee and Haitian Flavoring occupy positions defined by geographic origin and organizational structure. Lee Kum Kee exemplifies the Hong Kong-based sauce specialist archetype, while Haitian Flavoring represents the Chinese limited company format with southern China operational roots. Kikkoman anchors the cross-border specialist category as a Japanese corporation applying domestic fermentation expertise to black bean variants. These three entities collectively illustrate how provenance claims, regulatory compliance infrastructure, and format diversification determine competitive positioning across restaurant supply and retail channels.
| Leading Market Players |
|---|
| Lee Kum Kee |
| Haitian Flavoring |
| Kikkoman |
| Pearl River Bridge |
| Amoy Food |
| Wangzhihe |
| Lao Gan Ma |
| CJ CheilJedang |
| Archer Daniels Midland Company |
| Others |
Supply & Pricing Matrix
Soybean futures volatility on the Dalian Commodity Exchange cascades through Guangdong fermentation facilities into three distinct pricing tiers that separate heritage-batch premiums from industrial-scale contract rates.
Pricing Analysis
Fermentation-protocol certification anchors value-based pricing tiers that separate SAMR-export-qualified heritage batches from commodity-grade paste outputs. Three-tier pricing structure across premium, standard, and economy levels reflects GB standards compliance, backward integration into Pearl River Delta soybean sourcing, and direct-procurement contract scale. Cost compression in mid-tier paste formats intensifies because Thai and Vietnamese industrial sauce manufacturers adopt continuous-flow fermentation systems that bypass Guangdong import dependence. Food manufacturers seeking batch standardization exhibit highest price sensitivity; seafood-centric restaurant chains with menu-identity stakes show lowest.
Supply Chain Analysis
Direct-to-restaurant channels handle volume demand from North American multi-unit chains establishing annual contracts with named Guangdong heritage facilities. Supply concentrates in China, Thailand, and Vietnam as controlled-environment fermentation technology erodes geographic production monopolies. Raw material flows draw from southern China soybean regions, Japanese koji strain imports, and REACH-compliant packaging materials for European-bound shipments. Single-source vulnerability runs through Guangdong's legacy fermentation clusters where urban encroachment limits capacity expansion flexibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Controlled-environment fermentation technology is displacing earthenware vessel aging as the dominant production architecture, compressing aging timelines while replicating quality outside traditional terroirs.
For Market Incumbents: Cement heritage-protocol differentiation through exclusive annual volume contracts with seafood-centric restaurant chains in Vancouver and Sydney where menu identity depends on specific fermentation depth. Expand SAMR-certified capacity in Pearl River Delta greenfield facilities before urban encroachment eliminates expansion sites in Foshan and Shunde. Synthetic umami substitutes and yeast extract displacements in Western retail channels threaten mid-tier paste margins. For New Entrants and Emerging Players: Enter via USDA Organic certification pathways for powdered formats targeting snack manufacturers seeking clean-label umami alternatives without E-number additives. Suburban North American grocery retail outside traditional Chinatowns presents underdeveloped distribution for premium dried and paste formats with explicit usage instructions. Position through industrial sauce partnerships with ready-meal manufacturers lacking in-house fermentation capability. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier paste processors in Thailand and Vietnam with installed continuous-flow fermentation capacity and SAMR-export documentation infrastructure. Five-to-ten year viability hinges on suburban Asian retail penetration rates in North America and Europe. Monitor REACH packaging compliance acceleration in German and Dutch retail chains as inflection indicator for European market access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Soybean Sourcing | Haitian Flavoring's Pearl River Delta procurement control insulates margin from Dalian futures volatility. |
| Continuous-Fermentation Capacity Buildout | Thai and Vietnamese facilities bypass Guangdong import dependence with precision humidity modulation systems. |
| USDA Organic Certification Investment | Clean-label positioning unlocks snack manufacturer procurement previously captured by synthetic MSG suppliers. |
| Direct-Restaurant Procurement Relationships | Annual volume contracts with Canadian seafood chains compress distributor layers and anchor menu-identity pricing. |
| REACH-Compliant Packaging Transition | German retail pre-qualification requirements filter out ceramic-container traditionalists from European shelf placement. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs that combined with primary interviews across fermentation facility operators, Asian grocery chain category buyers, restaurant group procurement directors, and industrial sauce manufacturing executives. SAMR GB standard documentation, FDA allergen disclosure requirements, USDA phytosanitary records, and REACH migration testing protocols provided regulatory validation layers. Bottom-up facility capacity assessments triangulated against top-down import volume flows through North American and European customs databases.
Granularity-level modeling operated at product-type, end-user, and distribution-channel dimensions across the analysis window, with separate treatment of heritage-batch versus continuous-flow production cost structures. CAGRs derived from volume trajectory reconciliation between Guangdong export certification records and destination-market retail scan data. Forecast inputs incorporated urban encroachment constraints on legacy facility expansion, suburban Asian grocery retail penetration rates, and clean-label certification program adoption curves in snack manufacturing.
Forecast precision tightens around the base case; tail outcomes carry wider variance under climate-driven soybean crop variability in southern China and accelerated REACH compliance deadlines in German retail channels. Projections reflect assumptions regarding fermentation technology adoption rates and diaspora demographic concentration patterns. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Organic Skin Care Market
Specialty Foods
CBD-Infused Ice Cream Market
Specialty Foods
Cannabis-Infused Burger Market
Specialty Foods
Global Diet Food and Beverages Market
Specialty Foods
Aloe Butter Market
Specialty Foods
Europe Gluten-Free Breakfast Cereals Market
Specialty Foods
Dill Juice Market
Specialty Foods
Honey Spread Market
Specialty Foods
Asia-Pacific Alcohol-Infused Ice Cream Market
Specialty Foods
Manuka Honey Market
Specialty Foods
Sweet Spreads Market
Specialty Foods
Cat and Dog Food Toppers Market
Specialty Foods
Carbonic Maceration Market
Specialty Foods
Heat-Stable Fruit Fillings Market
Specialty Foods
US Jam Jelly and Preserves Market
Specialty Foods
Middle East and Africa Yerba Mate Market