
 Human Grade Pet Food Market | 2026-2036
Human Grade Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Human Grade Pet Food Market Insights
Veterinary nutritionist shortages across North America is unwinding production scalability for fresh-formula brands. The Farmer's Dog leverages direct-to-consumer logistics to control cold-chain delivery quality. Nestle SA anchors conventional retail shelf presence while building human-grade adjacent lines. Mars Group Holdings competes through manufacturing scale in wet and dry formats.
Human grade pet food denotes formulations manufactured in USDA-inspected facilities using ingredients meeting edible-grade standards, with processing temperatures, moisture content, and microbial limits matching human food codes rather than traditional feed-grade allowances. Dry Food occupies the largest volume share due to logistics efficiency and shelf stability, though Freeze-Dried segments command premium margins through nutrient retention claims. Online Retailers represent the fastest-growing distribution vector as subscription algorithms reduce customer acquisition costs for fresh-format entrants.
FDA Center for Veterinary Medicine oversees ingredient safety notifications while AAFCO model bills shape state-level labeling enforceability across the United States. USDA FSIS facility inspection requirements create capital barriers that favor established processors over artisan entrants. Stakeholders must monitor evolving state-by-state enforcement divergence on "human grade" claim substantiation to anticipate compliance cost trajectories.
Market Dynamics
USDA FSIS facility certification requirements are fragmenting production capacity between capital-rich processors and artisan entrants unable to absorb compliance overhead, concentrating volume among multi-site operators while squeezing regional co-packers.
Growth Catalysts
- AAFCO model bill harmonization:State-level labeling standardization reduces interstate compliance friction for direct-to-consumer brands expanding beyond origin markets.
- Subscription algorithm optimization:Predictive replenishment models lower customer acquisition costs for fresh-format entrants competing against conventional retail.
- Urban coastal disposable income concentration:Metropolitan clusters in California, New York, and Washington sustain premium price tolerance for refrigerated meal plans.
Market Restraints
- Cold-chain logistics cost structure:Refrigerated last-mile delivery absorbs 18-25% of product cost, compressing margins versus ambient shelf-stable alternatives.
- Veterinary nutritionist supply scarcity:North American academic programs produce insufficient formulation specialists to support brand proliferation.
- USDA facility inspection backlog:Certification queue delays extend go-to-market timelines for new production sites by 8-14 months.
Strategic Opportunities
- Veterinary channel underpenetration:Clinic dispensing programs remain nascent relative to retail and direct-to-consumer vectors.
- Freeze-dried format whitespace:Nutrient retention claims command premium positioning with lower logistics burden than fresh refrigerated.
- IRA-adjacent sustainability incentives:Renewable energy credits for cold-chain infrastructure reduce operating cost exposure for refrigerated operators.
Industry Challenges
- Microbiological testing protocol standardization:Absence of unified pathogen detection thresholds creates batch-release uncertainty across co-manufacturing relationships.
- Legacy ERP integration with subscription platforms:Inventory synchronization failures between production scheduling and consumer-facing portals generate fulfillment errors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Human Grade Pet Food Market |
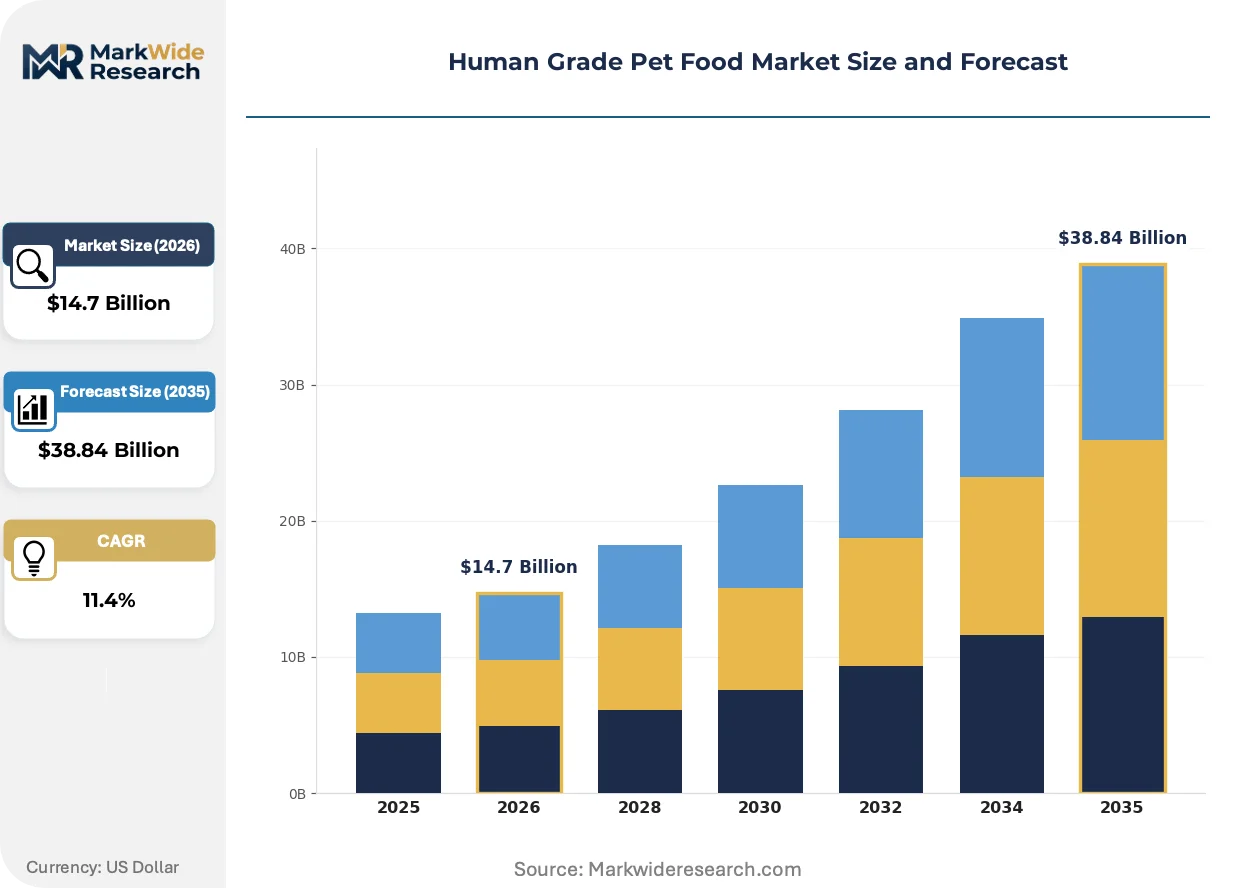
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $38.84 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Freeze-Dried Ingredient Source: Organic, Non-GMO, Locally Sourced, Human-Grade Distribution Channel: Online Retailers, Pet Specialty Stores, Supermarkets, Direct Sales Pet Type: Dogs, Cats, Small Animals, Others |
| Companies Covered | The Farmer's Dog, Spot & Tango, Nestle SA, The Honest Kitchen, PetPlate, Mars Group Holdings, Ollie, Darwin's Natural Pet Products, JustFoodForDogs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Human Grade Pet Food Market Trends and Innovations
Formulation science and distribution infrastructure are diverging sharply between mass-market convenience positioning and veterinary-directed therapeutic nutrition, with technology investment concentrating in divergent directions.
High-pressure processing technology is bifurcating safety assurance approaches in raw and lightly cooked segments. Premium subscription brands deploy HPP to extend refrigerated shelf life without synthetic preservatives. This capability is compressing the competitive window for conventional retort packaging while enabling fresh-format brands to reduce spoilage allowance.
USDA FSIS facility inspection requirements are tightening enforcement consistency across state boundaries. Multi-site processors face synchronized audit schedules that compress maintenance windows. Refrigerated meal plan operators with captive production assets absorb compliance costs more readily than brands reliant on third-party co-manufacturing.
Millennial pet owner purchasing behavior is rotating toward algorithm-driven replenishment models that displace discretionary retail browsing. Veterinary nutritionist consultation is displacing self-directed ingredient label evaluation in urban coastal markets. California and New York metropolitan clusters exhibit the highest concentration of subscription conversion and lowest tolerance for feed-grade ingredient disclosure.
Human Grade Pet Food Market Segmentation
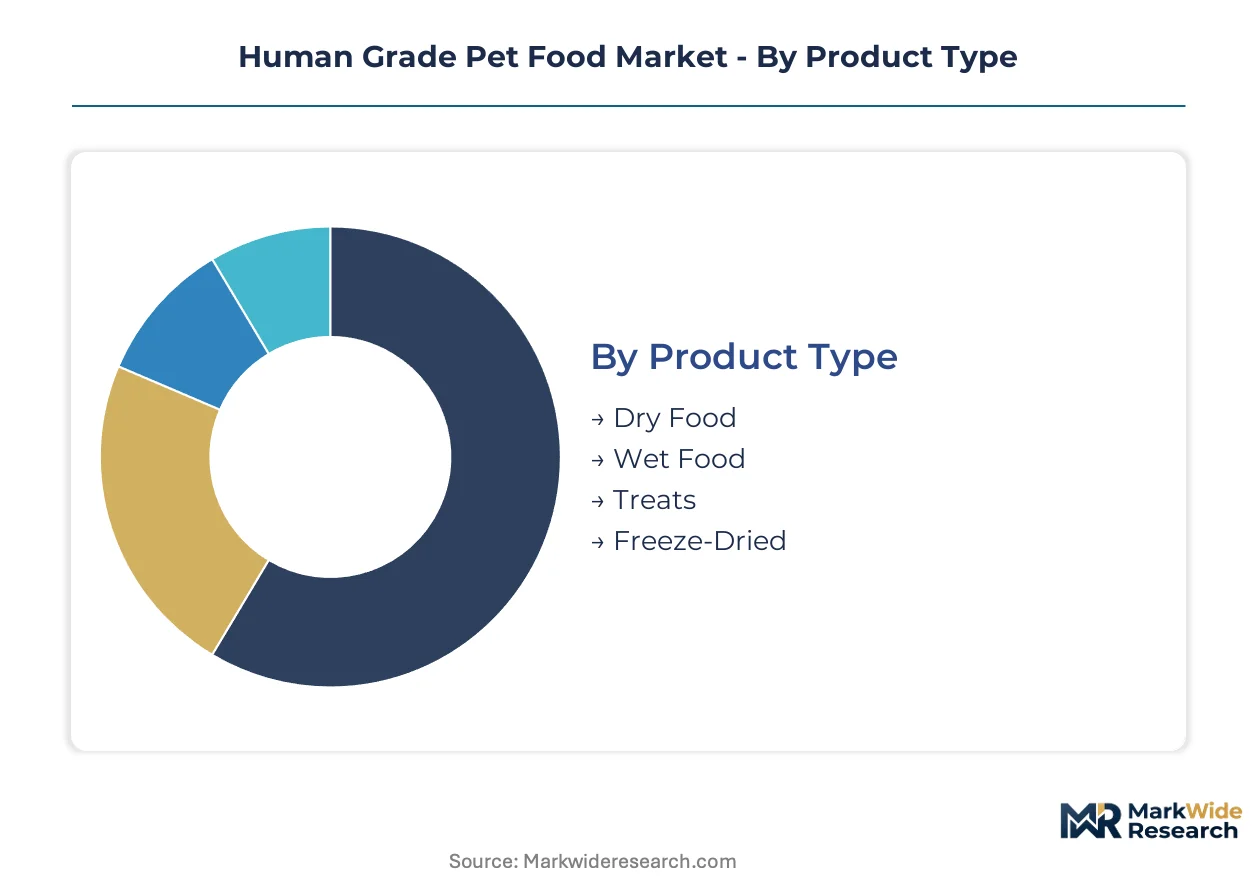
Segmentation in human grade pet food reveals how USDA facility certification, cold-chain economics, and subscription logistics reshape competitive boundaries across formats and channels. Each dimension carries distinct capital requirements and margin profiles that determine which entrants can scale.
Product Type:
Dry Food moves through conventional retail and mass e-commerce with minimal logistics overhead, while fresh and freeze-dried formats concentrate in direct-to-consumer channels with refrigerated or controlled-atmosphere requirements.
- Dry Food:Extruded and baked formulations manufactured at ambient temperatures with moisture content below 10 percent. Shelf-stable kibble dominates mass-market volume in California, Texas, and Florida metropolitan clusters where conventional retail penetration remains highest. USDA FSIS facility requirements apply only to human-grade claim substantiation, not base production.
- Freeze-Dried:Sublimation dehydration preserves raw nutrient profiles without synthetic preservatives. Premium positioning in Seattle, Portland, and Denver sustains price tolerance for lightweight logistics that avoid refrigerated last-mile costs. HPP-treated variants extend shelf life for subscription replenishment models.
- Wet Food:Retort-pouched or tray-sealed meals with 75-85 percent moisture content requiring thermal processing.
- Treats:Supplementary nutrition or training rewards spanning jerky, dental chews, and functional biscuits.
By volume, Dry Food leads. By growth pace, Freeze-Dried is climbing the fastest.
Ingredient Source:
Certification tiers stratify procurement costs and label claim defensibility, with human-grade designation requiring full USDA FSIS facility compliance that organic and non-GMO specifications do not mandate.
- Human-Grade:Ingredients meeting FDA edible standards processed in USDA-inspected facilities with microbial limits matching human food codes. Formulation costs concentrate in urban coastal markets—New York, Los Angeles, San Francisco—where millennial pet owners reject feed-grade disclosure. AAFCO model bill harmonization reduces interstate label friction for multi-state subscription operators.
- Organic:USDA NOP-certified ingredients excluding synthetic pesticides, fertilizers, and genetically modified organisms. Pacific Northwest and Northeast corridors sustain premium positioning through co-op retail and natural specialty channels.
- Non-GMO:Third-party verified absence of genetically engineered ingredients without full organic certification.
- Locally Sourced:Regional supply chain radius claims—typically 100-250 miles—emphasizing freshness and carbon footprint reduction.
Human-Grade commands the steepest price premiums. Organic shows the strongest correlation with veterinary channel placement.
Distribution Channel:
Channel selection determines customer acquisition economics and cold-chain infrastructure requirements, with refrigerated formats excluding conventional retail and mass e-commerce fulfillment.
- Online Retailers:Algorithm-driven subscription platforms with predictive replenishment reducing churn. Chewy and Amazon Fresh anchor mass-market penetration; dedicated fresh-meal sites control logistics quality. Customer lifetime value optimization dominates California and New York metropolitan statistical areas.
- Direct Sales:Brand-captive websites with subscription portals and cold-chain delivery networks. The Farmer's Dog model of in-house logistics insulates quality control from third-party co-manufacturing variability.
- Pet Specialty Stores:Independent and chain retailers—Petco, PetSmart premium aisles—offering tactile evaluation and staff consultation.
- Supermarkets:Mass-market grocery placement for shelf-stable formats with human-grade adjacent positioning in premium aisles.
Online Retailers absorb the highest marketing spend per acquisition. Direct Sales achieves the strongest subscription retention rates.
Pet Type:
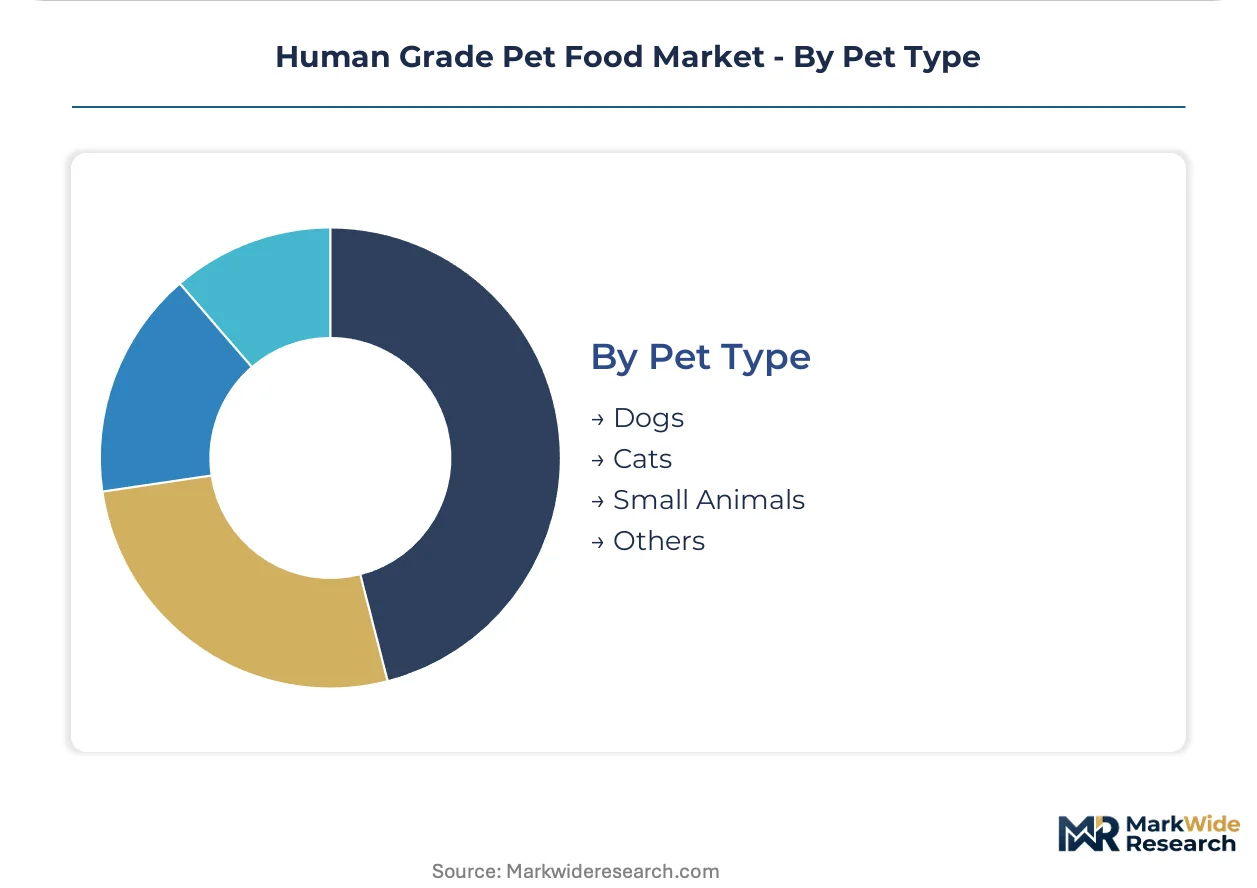
Species-specific formulation requirements and portion economics concentrate human-grade investment in canine segments with higher per-pet spending and subscription plan viability.
- Dogs:Larger portion sizes and established fresh-meal subscription infrastructure sustain unit economics for refrigerated delivery. Formulation complexity—protein rotation, breed-specific caloric density—drives veterinary nutritionist demand. Urban coastal markets in California, Washington, and Massachusetts show highest conversion from kibble to fresh plans.
- Cats:Obligate carnivore protein requirements and lower moisture tolerance in dry formats create formulation constraints. Smaller portion sizes challenge refrigerated subscription unit economics outside premium urban clusters.
- Small Animals:Rabbits, guinea pigs, and exotic mammals with specialized forage and pellet requirements.
- Others:Avian, reptile, and equine formulations with limited human-grade penetration.
Dogs generate the absolute revenue concentration. Cats represent the steepest expansion trajectory for freeze-dried formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban coastal markets in the United States command price premiums that inland metropolitan clusters in Germany cannot replicate, creating a transatlantic pricing-power asymmetry that shapes capital deployment strategies for refrigerated meal plan operators.
United States
Millennial pet owner density in California and New York metropolitan areas sustains subscription conversion rates above national baselines, while FDA Center for Veterinary Medicine ingredient safety notifications tighten claim substantiation requirements for human-grade labeling. The Los Angeles-San Francisco corridor concentrates fresh-format production capacity as USDA FSIS facility certification queues extend wait times for new market entrants.
Canada
Veterinary channel penetration remains underdeveloped relative to direct-to-consumer vectors, with Toronto and Vancouver metropolitan clusters showing highest tolerance for premium refrigerated pricing. Health Canada and the Canadian Food Inspection Agency coordinate oversight of imported human-grade formulations, while British Columbia's cold-chain infrastructure supports cross-border fulfillment into Pacific Northwest US markets.
Germany
Organic certification preference among pet owners in Bavaria and North Rhine-Westphalia exceeds human-grade claim recognition, creating a distinct regulatory environment where EFSA feed-grade standards intersect with national organic labeling. The Munich-Stuttgart corridor hosts specialized co-manufacturing capacity serving private-label entrants across continental Europe.
United Kingdom
Subscription algorithm adoption in Greater London lags US coastal benchmarks by approximately three years, though veterinary nutritionist consultation rates exceed European averages as the Royal College of Veterinary Surgeons strengthens continuing education requirements. The M4 corridor from London to Bristol concentrates direct-to-consumer fulfillment infrastructure for fresh-format brands.
Australia
Freeze-dried format penetration in Sydney and Melbourne metropolitan areas advances faster than refrigerated meal plans due to last-mile logistics constraints across dispersed suburban geographies. The Therapeutic Goods Administration and Australian Pesticides and Veterinary Medicines Authority coordinate on imported ingredient standards, while domestic production clusters in Victoria and Queensland serve Asia-Pacific export demand.
Human Grade Pet Food Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with direct-to-consumer subscription platforms controlling algorithm-driven customer acquisition while multinational packaged goods manufacturers dominate conventional retail shelf presence. The vendor base stratifies into three tiers: venture-backed fresh-format specialists with captive logistics, diversified food conglomerates building human-grade adjacent portfolios, and regional co-manufacturers serving private-label demand. Consolidation pressure concentrates among mid-scale operators unable to absorb USDA facility certification overhead or achieve subscription scale economics.
Within the fresh-format specialist tier, The Farmer's Dog and Spot & Tango exemplify the direct-to-consumer logistics archetype, while Nestle SA occupies a position representing diversified conglomerate expansion into premium adjacent categories. Mars Group Holdings anchors the conventional manufacturing scale tier with wet and dry format production assets. These three patterns—captive delivery infrastructure, portfolio diversification, and manufacturing scale—define the competitive boundary conditions shaping capital allocation across the analysis window.
| Leading Market Players |
|---|
| The Farmer's Dog |
| Spot & Tango |
| Nestle SA |
| The Honest Kitchen |
| PetPlate |
| Mars Group Holdings |
| Ollie |
| Darwin's Natural Pet Products |
| JustFoodForDogs |
| Others |
Pricing and Supply Chain Analysis
Eight-to-fourteen-month USDA FSIS facility certification queues compress inventory turnover for fresh-format entrants while amplifying pricing power for multi-site operators with cleared production assets. This lead-time asymmetry stratifies the market between capital-rich processors commanding subscription premiums and artisan brands forced into co-manufacturing dependency.
Pricing Analysis
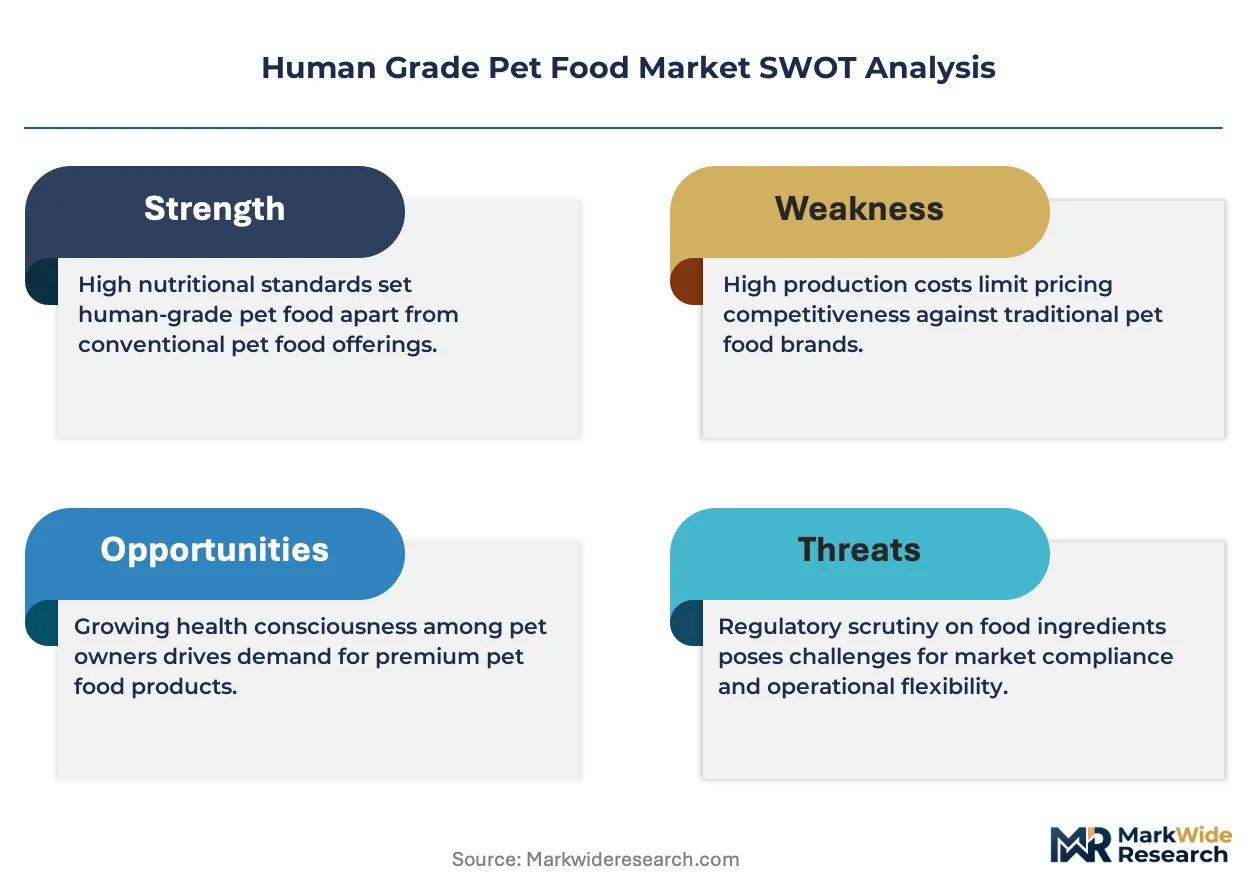
Customization-premium spreads in refrigerated meal plans separate configured-to-order subscription pricing from standard freeze-dried SKUs by a substantial margin gap. Three-tier pricing structure across premium, standard, and economy levels dominates, with human-grade certification and cold-chain delivery cost as primary price differentiation drivers. Pricing pressure stems from veterinary nutritionist supply scarcity elevating formulation overhead. Mass-market conventional retail buyers exhibit highest price sensitivity, while urban coastal millennial subscribers show lowest tolerance elasticity.
Supply Chain Analysis
USDA-inspected facility availability in the United States, Canada, and Germany constitutes the primary chokepoint constraining human-grade production expansion. Raw material dependencies center on USDA-certified protein suppliers, organic produce distributors, and HPP technology providers. Single-source vulnerability permeates the cold-chain logistics tier where specialized refrigerated carriers dominate last-mile fulfillment. Distribution runs through direct-to-consumer subscription portals for fresh formats, while freeze-dried variants leverage conventional e-commerce and pet specialty retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity pervades this market as millennial pet owner demand rotates sharply toward algorithm-driven replenishment models, creating niche entry points between mass-market incumbents and artisan local producers.
For Market Incumbents: Fortify subscription retention through captive cold-chain infrastructure investments that insulate quality control from third-party variability. Nestle SA and Mars Group Holdings should accelerate human-grade adjacent line development before fresh-format specialists achieve scale economics. USDA FSIS facility certification backlog poses the central threat to expansion timelines.
For New Entrants and Emerging Players: Lead with veterinary channel underpenetration in Canada and the United Kingdom where clinic dispensing programs remain nascent relative to direct-to-consumer saturation. Freeze-dried cat food represents the most penetrable whitespace segment given smaller portion sizes and lower refrigerated logistics burden. A sampling-to-subscription conversion model through veterinary partnerships offers the clearest go-to-market angle.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates seeking to divest non-core pet nutrition assets amid portfolio rationalization pressures. Long-term viability favors operators with captive production and algorithmic customer acquisition infrastructure over pure-brand plays dependent on co-manufacturing. The signal to watch is AAFCO model bill harmonization progress across state legislatures as inflection indicator for interstate scaling feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Investment | Captive refrigerated logistics insulates The Farmer's Dog from third-party spoilage liability. |
| Veterinary Channel Partnership Program | Clinic dispensing access unlocks underpenetrated prescriptive nutrition segment in Toronto and Vancouver. |
| USDA FSIS Facility Certification Acceleration | Multi-site clearance compresses go-to-market timelines versus artisan competitors facing 8-14 month queues. |
| Freeze-Dried Format Line Extension | Nutrient retention claims command premium positioning with lighter logistics burden than refrigerated alternatives. |
| Subscription Algorithm Optimization | Predictive replenishment models reduce customer acquisition costs for fresh-format brands competing against retail. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with veterinary nutritionists, direct-to-consumer brand operators, pet specialty retail buyers, and USDA facility compliance officers; and secondary validation through FDA Center for Veterinary Medicine ingredient safety notifications, AAFCO model bill tracking, SEC 10-K filings from diversified food conglomerates, and refrigerated logistics trade association data. Bottom-up segment sizing triangulated against top-down macro pet expenditure trends.
Across the projection horizon, the analytical framework modeled volume and value trajectories by product format, ingredient certification tier, distribution channel, and pet species. CAGRs derived from historical growth pattern analysis adjusted for regulatory enforcement intensity and cold-chain infrastructure buildout rates. Veterinary nutritionist supply constraints and subscription platform penetration curves served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in FDA and AAFCO oversight regimes; material policy shifts around human-grade claim substantiation would require re-modeling. Practitioners should keep alternative scenarios live as state-by-state enforcement divergence and veterinary channel development trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Gluten-Free Desserts and Ice Creams Market
Specialty Foods
Chamomile Market
Specialty Foods
Low Fat Hummus Market
Specialty Foods
Foie Gras Market
Specialty Foods
Low Calorie Diet Meal Plan Market
Specialty Foods
Moringa Products Market
Specialty Foods
Keto Low-Calorie Meals Market
Specialty Foods
Cat Food Flavors Market
Specialty Foods
Cat and Dog Food Toppers Market
Specialty Foods
Global Truffle Market
Specialty Foods
Edible Cutlery Market
Specialty Foods
Heat-Stable Fruit Fillings Market
Specialty Foods
Cultures Market
Specialty Foods
Sofrito Market
Specialty Foods
Silver Food Market
Specialty Foods
Asia-Pacific Hummus Market