
 Super Foods Market | 2026-2036
Super Foods Market Size, Share, and Industry Trends Forecast 2026-2036
Super Foods Market Analysis
Quinoa is rebalancing protein economics in plant-based formulations as manufacturers seek alternatives to soy and wheat isolates. Archer Daniels Midland Company leverages its global grain handling infrastructure to secure South American quinoa supply chains. Navitas Organics differentiates through certified organic sourcing and direct farmer partnerships in Peru and Bolivia. Terrasoul Superfoods specializes in raw, minimally processed formats that command shelf-space premiums in natural retail channels.
Super foods denote nutrient-dense whole foods, extracts, and concentrates containing elevated levels of vitamins, minerals, antioxidants, or omega fatty acids, typically processed through freeze-drying, cold-pressing, or low-temperature milling to preserve bioactive compounds. Their primary commercial purpose centers on delivering functional nutrition claims in packaged foods, beverages, and dietary supplements. Fruits and vegetables occupy the largest product type position, driven by berry powders and leafy green concentrates with established consumer recognition. The organic source segment captures disproportionate margin pools as certification requirements create supply scarcity and price premiums over conventional alternatives. Powder form leads volume throughput due to logistical efficiency and formulation flexibility across beverage and bakery applications.
EFSA novel food regulations govern ingredient approval and safety assessment for non-traditional EU botanicals entering European formulations. The EU Green Deal carbon border adjustments are pressuring importers to document sustainable cultivation practices across Latin American and African supply bases. In the United States, FDA enforcement of New Dietary Ingredient notifications shapes market access for emerging superfood extracts. Stakeholders must monitor evolving novel food classification decisions and carbon accounting requirements to anticipate which supply origins and ingredient formats will retain competitive access across major demand jurisdictions.
Market Dynamics
Carbon border adjustments under the EU Green Deal are forcing superfood importers to reconstruct Latin American and African supply chains with verified emissions documentation, while EFSA novel food classifications determine which botanical extracts gain formulation access across European markets.
Growth Catalysts
- Functional beverage expansion:Manufacturers are accelerating procurement of chia, quinoa, and açaí for fortified product lines targeting protein diversification beyond soy isolates.
- EU Green Deal traceability mandates:Carbon accounting requirements create competitive moats for suppliers with documented sustainable cultivation practices across Peruvian and Bolivian origins.
- German retail premiumization:Health-conscious consumers in Germany drive organic superfood adoption across both retail and foodservice channels, concentrating demand in this high-margin market.
Market Restraints
- EFSA novel food approval bottlenecks:Non-traditional botanicals face extended safety assessment timelines that delay European market entry for emerging superfood extracts.
- South American supply concentration:Quinoa and açaí sourcing depends heavily on Peruvian and Bolivian harvests, exposing buyers to climate volatility and political risk in the Andean region.
- Organic certification scarcity:Limited certified acreage creates supply bottlenecks that inflate input costs for premium product lines relative to conventional alternatives.
Strategic Opportunities
- Raw format differentiation:Minimally processed superfoods command shelf-space premiums in natural retail channels as consumers reject heat-degraded nutrient profiles.
- Powder form logistics optimization:Formulation flexibility across beverage and bakery applications enables manufacturers to consolidate SKUs while serving multiple end-use verticals.
- Direct farmer partnerships:Bypassing commodity traders through origin-level relationships secures volume commitments and quality consistency for organic supply chains.
Industry Challenges
- Novel food classification uncertainty:Evolving EFSA decisions on ingredient status force reformulation investments and regulatory contingency planning.
- Cold-chain infrastructure gaps:Freeze-drying and low-temperature milling requirements demand specialized processing equipment that limits geographic expansion of processing capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Super Foods Market |
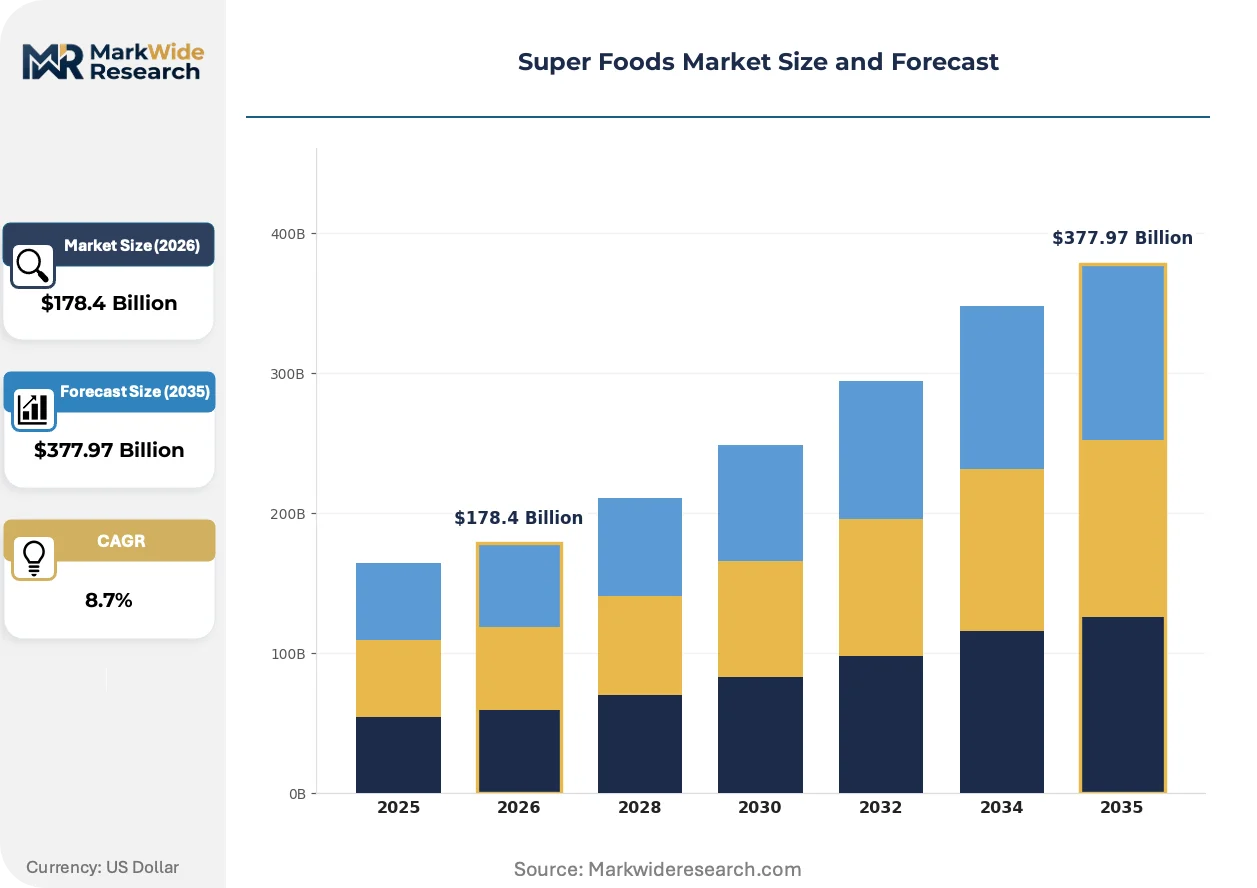
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $377.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Grains, Supplements Source: Organic, Non-GMO, Conventional, Wildcrafted Form: Raw, Powder, Liquid, Bar Distribution Channel: Online, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | Archer Daniels Midland Company, Suncore Foods, Del Monte Foods, Terrasoul Superfoods, Navitas Organics, Sunfood Superfoods, OMG Superfoods, The Green Labs LLC, Creative Nature, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Super Foods Market Emerging Trajectories
Superfood processing is converging with precision fermentation and cellular agriculture techniques, while regulatory traceability requirements and shifting procurement models reshape competitive positioning across the value chain.
Freeze-drying technology is unifying nutrient preservation with extended shelf stability in berry powders and leafy concentrates. Functional beverage manufacturers adopt these formats at accelerating rates to maintain bioactive compound integrity through distribution. This unification is compressing the traditional trade-off between processing efficiency and nutritional claims, enabling clean-label positioning in premium segments.
EFSA novel food regulations are tightening safety assessment protocols for non-traditional botanicals entering European formulations. The framework now requires comprehensive toxicological data that extends approval timelines and raises entry barriers for emerging suppliers. Berry extracts and African-origin botanicals face the steepest compliance burdens, prompting applicants to front-load clinical investment before market submission.
Health-conscious buyers are consolidating procurement around certified organic sourcing with verified carbon footprints. Natural retail channels and foodservice operators in Germany now require documentation of sustainable cultivation practices as a condition of shelf placement. This behavioral shift is most visible in Berlin and Munich, where premium organic superfoods displace conventional alternatives in both grocery and café segments.
Super Foods Market Segmentation
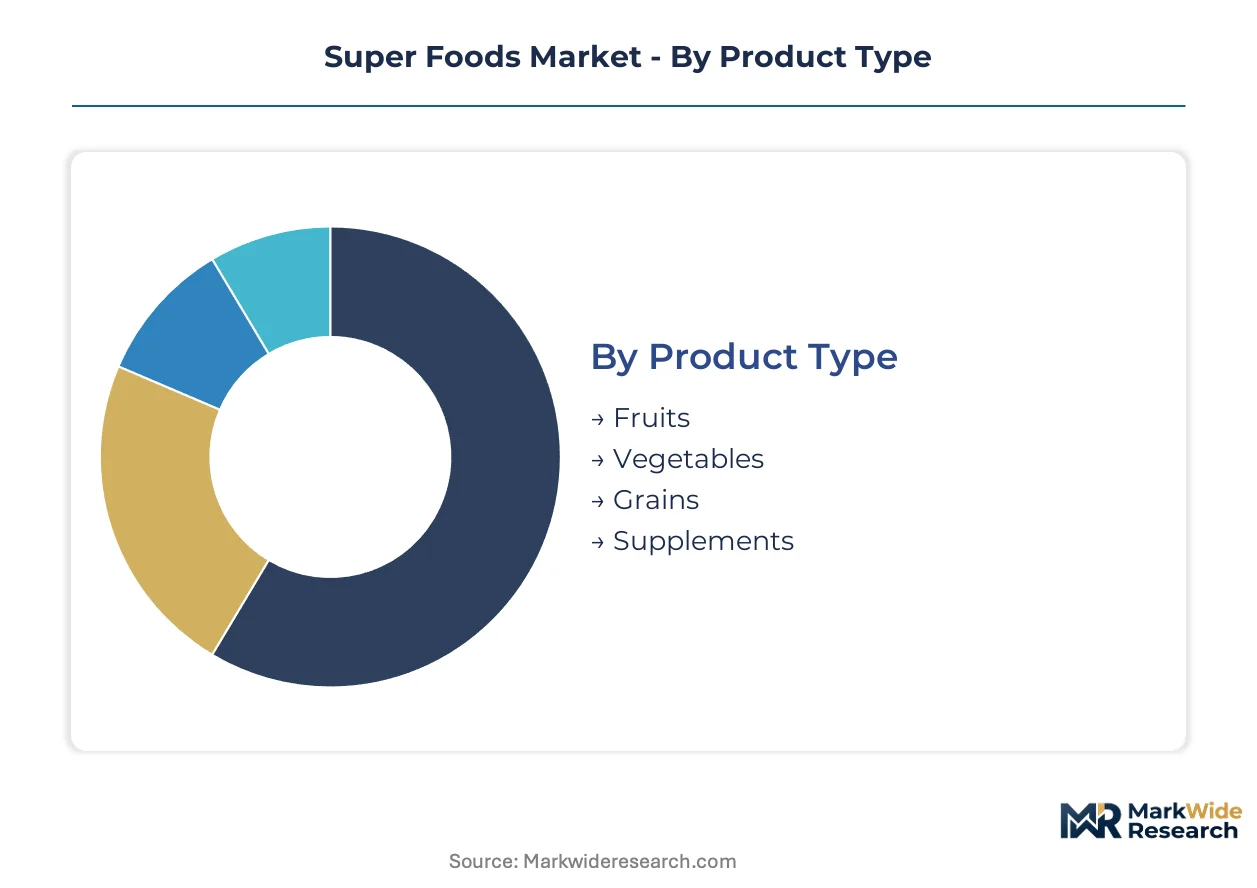
Superfood segmentation determines regulatory pathways, margin capture, and supply chain configuration. Certification requirements vary sharply across organic versus conventional sourcing, while form factor choices dictate processing infrastructure investments and distribution economics.
Product Type:
EFSA novel food classifications apply differentially across product categories, with berry concentrates and leafy extracts facing distinct safety assessment protocols compared to whole grain submissions.
- Fruits:Berry powders and tropical concentrates deliver anthocyanin and polyphenol payloads for functional beverage formulations. German health food retailers prioritize freeze-dried acai and maqui powders with verified ORAC scores, driving premium positioning in Berlin and Munich natural channels.
- Vegetables:Leafy green concentrates from spirulina, chlorella, and wheatgrass supply chlorophyll and micronutrient density. Demand clusters in California wellness markets and Scandinavian clean-label applications where heat-sensitive processing claims command shelf-space premiums.
- Grains:Quinoa and amaranth flours provide complete protein matrices for gluten-free bakery and pasta segments.
- Supplements:Standardized extracts in capsule and tablet formats target measurable bioactive dosing for clinical positioning.
Fruits sits at the top of the volume ranking, with Vegetables climbing the fastest.
Source:
Cost tier stratification separates certified organic supply from conventional alternatives, with wildcrafted materials occupying a niche premium position above both.
- Organic:Third-party certification under USDA National Organic Program or EU 2018/848 creates supply scarcity and price premiums. Peruvian and Bolivian quinoa cooperatives command multi-year contracts from Archer Daniels Midland and Navitas Organics seeking volume security.
- Non-GMO:Identity-preserved supply chains document genetic integrity through PCR testing and chain-of-custody protocols. North American soybean and corn alternatives to superfood proteins rely on Non-GMO Project verification for natural retail placement.
- Conventional:Uncertified cultivation supplies mass-market formulations where price elasticity dominates purchasing decisions.
- Wildcrafted:Hand-harvested botanicals from unmanaged ecosystems carry sustainability risks and harvest variability.
Organic captures the steepest margin expansion, with Non-GMO gaining share fastest in North American conventional retail.
Form:
Application flexibility varies across form factors, with powders enabling multi-vertical deployment while bars and liquids target single-use consumption occasions.
- Raw:Minimally processed whole foods and sprouted seeds retain enzyme activity and heat-sensitive vitamins. Terrasoul Superfoods and comparable specialists command 40-60% price premiums over heat-processed alternatives in natural retail channels.
- Powder:Freeze-dried and low-temperature milled formats optimize logistics density and formulation versatility. Beverage manufacturers in Germany and California consolidate procurement around berry and green concentrates that reconstitute across smoothie, shot, and functional water applications.
- Liquid:Cold-pressed juices and concentrated extracts require refrigerated distribution.
- Bar:Extruded and cold-pressed formats combine superfood inclusions with binding ingredients for portable nutrition.
Powder leads volume throughput, with Raw expanding most quickly in premium natural channels.
Distribution Channel:
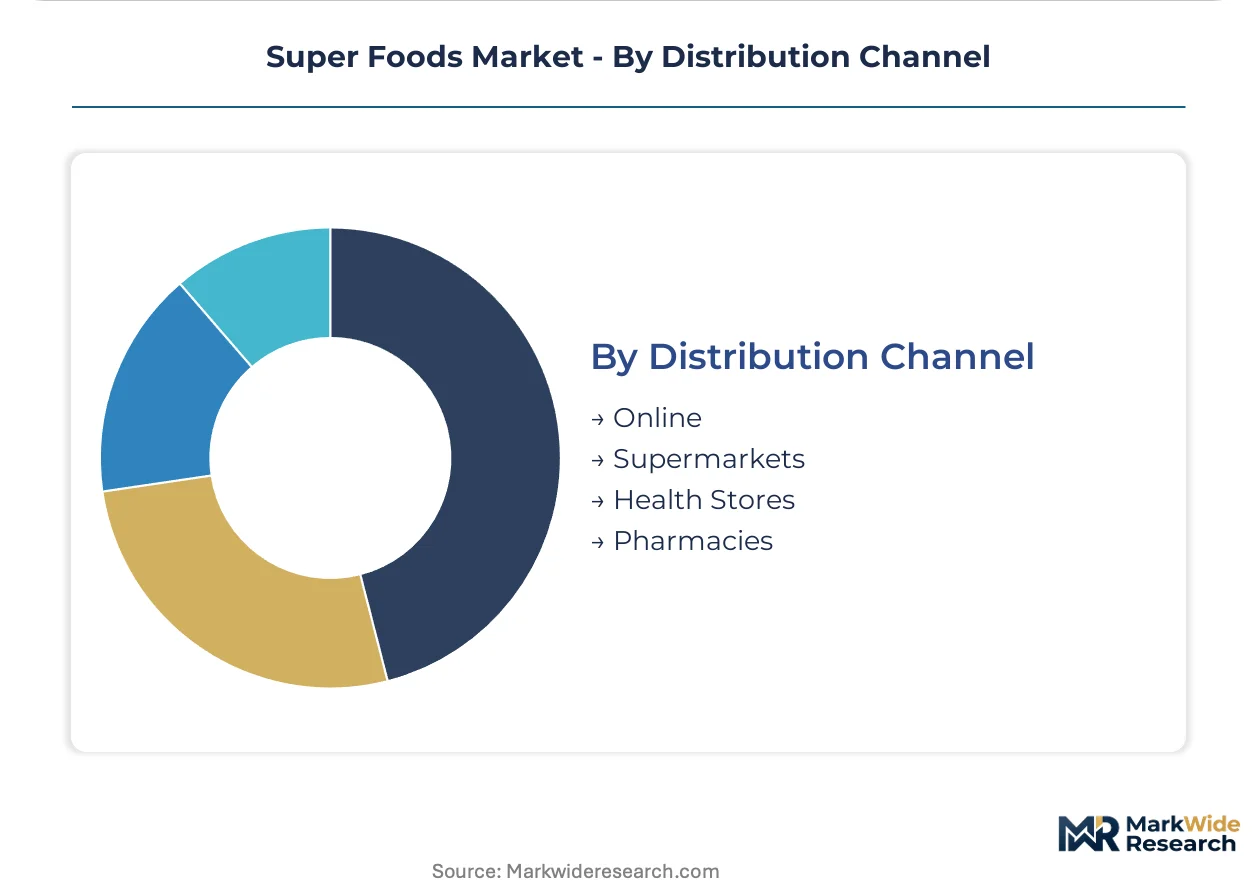
Customer type and purchase behavior diverge sharply across channel formats, with online and health stores rewarding education-intensive positioning while supermarkets prioritize velocity and packaging clarity.
- Online:Direct-to-consumer and marketplace platforms enable subscription models and detailed nutritional storytelling. Amazon and specialized wellness e-tailers in Germany capture recurring purchases of organic chia and hemp products with auto-replenishment incentives.
- Supermarkets:Mass retail placement demands case-rate velocity and front-of-pack certification callouts. Kroger and Albertsons in the United States dedicate end-cap displays to organic berry powders during January wellness campaigns.
- Health Stores:Staff-curated assortments support premium pricing and emerging ingredient introduction.
- Pharmacies:Clinical positioning and healthcare practitioner recommendations drive supplement-format sales.
Supermarkets dominate absolute volume, with Online gaining share fastest in recurring purchase categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Berlin-Munich corridor anchors continental demand for organic superfoods, with carbon accounting mandates and novel food classifications creating divergent competitive access across major consumption clusters.
Germany
Health-conscious consumers in Berlin and Munich drive premium organic adoption across retail and foodservice channels. EFSA novel food regulations govern ingredient approval for non-traditional botanicals entering German formulations. Bavaria's natural products cluster concentrates procurement decisions for chia, quinoa, and açaí destined for functional beverage lines.
United States
California wellness markets and New York Metro health food retail command shelf-space premiums for raw, minimally processed formats. FDA enforcement of New Dietary Ingredient notifications shapes market access for emerging superfood extracts. Los Angeles and San Diego anchor West Coast demand for berry powders and green concentrates with verified ORAC positioning.
Peru
Andean quinoa and açaí harvests supply protein diversification demand from North American and European manufacturers. EU Green Deal carbon border adjustments pressure Peruvian cooperatives to document sustainable cultivation practices. Cusco-Puno agricultural belt concentrates organic certification efforts for export-bound superfood supply chains.
Bolivia
High-altitude quinoa production serves gluten-free bakery and pasta segments seeking alternatives to soy and wheat isolates. EFSA traceability requirements drive investment in chain-of-custody documentation from Altiplano growing regions. La Paz-Oruro corridor hosts processing infrastructure for low-temperature milling and freeze-dried format exports.
United Kingdom
London health food retailers and Manchester-based natural product distributors prioritize certified organic sourcing with verified carbon footprints. EFSA novel food classifications apply differentially to berry concentrates and leafy extracts entering UK formulations. Southeast England logistics hubs consolidate import volumes for redistribution across domestic and Irish markets.
Super Foods Market Vendor Landscape
Direct farmer partnerships dominate the current landscape as procurement models shift away from commodity traders. The vendor base stratifies across multinational grain handlers, certified organic specialists, and raw format purists. Three archetypes anchor competitive positioning: global infrastructure players leveraging South American supply chains, organic certification specialists with origin-level relationships, and minimally processed format experts commanding natural retail premiums. M&A activity and geographic expansion represent the dominant competitive vectors as participants secure volume commitments and quality consistency.
Within the global infrastructure tier, Archer Daniels Midland Company anchors multinational grain handling capabilities across Peruvian and Bolivian origins. Navitas Organics exemplifies the certified organic specialist archetype through direct farmer partnerships in Andean growing regions. Terrasoul Superfoods occupies the raw format premium position, representing minimally processed specialists that command shelf-space premiums in natural retail channels.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Suncore Foods |
| Del Monte Foods |
| Terrasoul Superfoods |
| Navitas Organics |
| Sunfood Superfoods |
| OMG Superfoods |
| The Green Labs LLC |
| Creative Nature |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap cooperatives across the Peruvian Altiplano and Bolivian highlands anchor upstream supply, translating organic certification scarcity into sustained pricing power for certified quinoa and açaí. Their collective bargaining leverage intensifies as EU Green Deal carbon accounting mandates force European buyers to document chain-of-custody from these specific origins, compressing procurement alternatives and reinforcing premium capture.
Pricing Analysis
Input-cost pass-through from Andean harvest volatility flows directly into contract renegotiations, with freeze-dried berry powders and low-temperature milled grains absorbing climate-driven yield fluctuations. Three-tier pricing structure across premium organic, standard conventional, and economy uncertified levels separates certified Peruvian quinoa from Bolivian conventional alternatives and mass-market commodity grades. Cost compression in the conventional tier is intensifying because Brazilian and Argentine suppliers are expanding acreage, while German health food retailers remain least price-sensitive due to mandatory sustainability documentation requirements.
Supply Chain Analysis
Regional distribution centers in Hamburg and Rotterdam consolidate Andean shipments before hub-and-spoke redistribution across European natural retail channels. Supply concentrates in Peru, Bolivia, and Ecuador for quinoa and açaí, with secondary sourcing emerging from Colombia and Brazil for chia and camu camu. Raw material dependencies rest on high-altitude Andean cultivation, freeze-drying equipment capacity, and cold-chain logistics infrastructure. Single-source vulnerability runs through the Cusco-Puno agricultural belt, where political instability and drought frequency threaten harvest reliability. Distribution runs through certified organic importers with direct farmer partnerships, bypassing commodity traders to secure volume commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
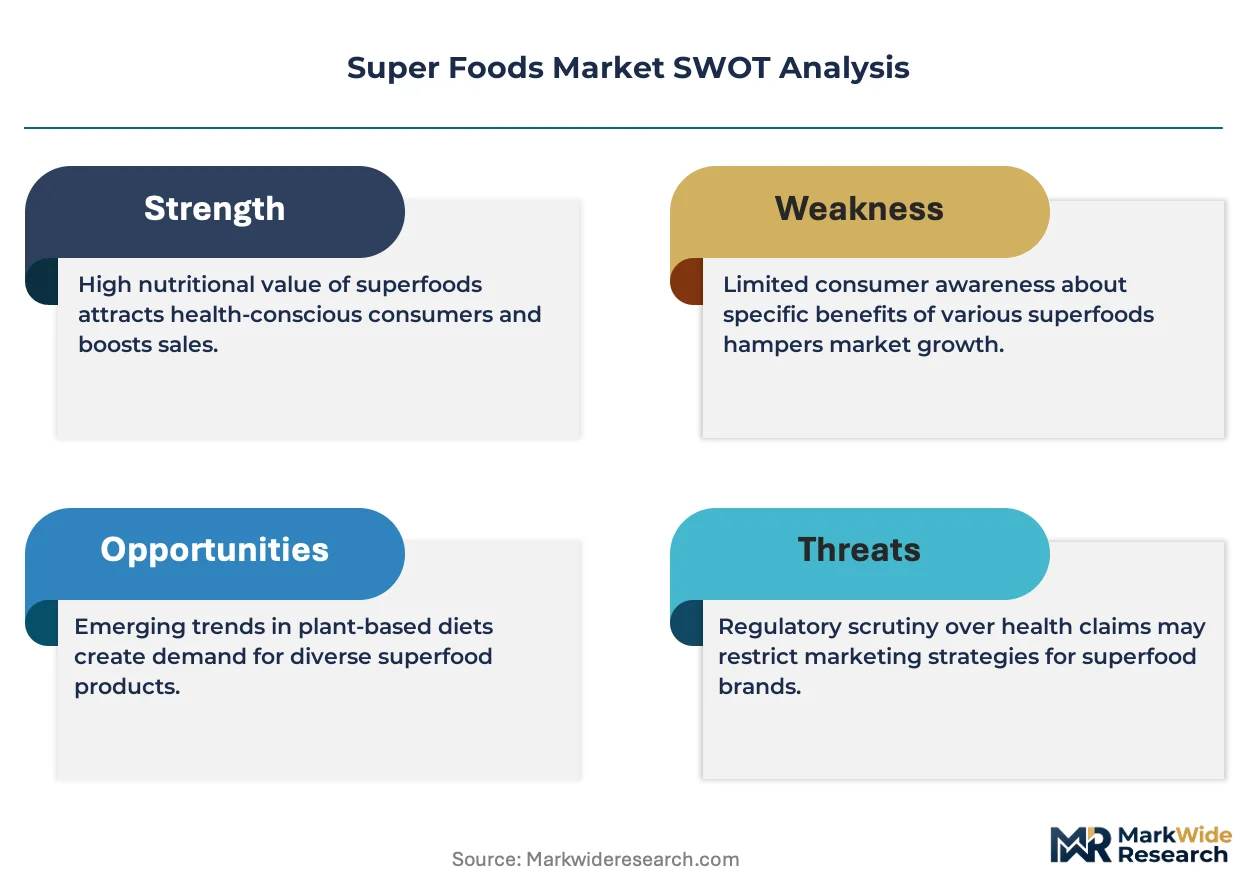
The Super Foods Market functions as a regulatory compounder, with EFSA novel food classifications and EU Green Deal carbon border adjustments continuously tightening compliance requirements that favor incumbent scale and documented supply chains.
For Market Incumbents: Acquire freeze-drying and low-temperature milling capacity in the La Paz-Oruro corridor to capture processing premiums currently flowing to third-party facilities. Consolidate direct farmer partnerships into multi-year offtake agreements with volume guarantees, defending against emerging South African and Australian entrants seeking to diversify protein sourcing beyond Andean origins. Certification investment in EU 2018/848 organic compliance and carbon footprint documentation represents the critical lever for retaining German retail shelf placement. For New Entrants and Emerging Players: Raw format specialists serving California wellness markets and Berlin-Munich natural channels represent an underserved buyer archetype with willingness to pay 40-60% premiums for minimally processed superfoods. Foodservice operators in Scandinavian clean-label applications and Los Angeles functional beverage startups offer the most penetrable entry points, with verified ORAC positioning and enzyme activity claims providing the essential go-to-market angle against established heat-processed competitors. For Investors and Strategic Acquirers: Valuations sit cheapest among conventional-tier traders lacking organic certification infrastructure and direct farmer relationships, presenting consolidation targets for private equity roll-ups. Long-term viability over the five-to-ten year window favors participants with captive Andean supply bases and in-house processing capacity, as regulatory traceability requirements deepen competitive moats. The signal to watch is EFSA novel food approval velocity for African-origin botanicals, which would diversify supply geography and compress Andean pricing power if accelerated.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Farmer Partnership Consolidation | Multi-year offtake agreements with Peruvian cooperatives secure volume commitments ahead of EU Green Deal enforcement. |
| Freeze-Drying Capacity Expansion | In-house low-temperature processing in Bolivia captures margin currently paid to third-party facilities in La Paz. |
| Organic Certification Investment | EU 2018/848 compliance documentation enables continued access to German premium retail and foodservice channels. |
| Carbon Footprint Verification | Verified emissions data satisfies EU Green Deal border adjustments and differentiates supply for Berlin-Munich buyers. |
| Raw Format Product Line Extension | Minimally processed superfoods command shelf-space premiums in California wellness markets and natural retail channels. |
Methodological Framework
Bottom-up functional beverage and dietary supplement modeling reconciled against top-down Andean harvest tracking and import customs documentation forms the analytical core of this study. Primary interviews with organic certification specialists, procurement directors at multinational grain handlers, natural retail category buyers in Germany and California, and cooperative managers in Peru and Bolivia combined with secondary validation from EFSA novel food registers, EU Green Deal implementation guidance, USDA National Organic Program standards, and German Federal Office for Agriculture and Food import statistics. Triangulation across these sources calibrated volume and value estimates.
Historical trendline analysis of certified organic acreage expansion, freeze-drying capacity utilization, and functional beverage formulation adoption established baseline growth patterns across the projection horizon. The analytical framework segmented demand by product type, certification tier, processing format, and distribution channel, with additional modeling of regional regulatory cluster effects on market access. CAGRs derived from curve-fitting across these segmented trendlines, incorporating climate volatility indices for Andean growing regions and EFSA approval pipeline status for emerging botanicals.
Underlying measurement precision varies by segment; certified organic supply chains with documented chain-of-custody carry tighter precision than wildcrafted or conventional alternatives with fragmented sourcing. Forecasts reflect assumptions regarding EFSA novel food classification timelines, EU carbon border adjustment implementation scope, and Andean climate stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Low Calorie Popsicles Market
Specialty Foods
Asia-Pacific Free from Food Market
Specialty Foods
Zhacai Market
Specialty Foods
Chamomile Market
Specialty Foods
CBD Snacks Market
Specialty Foods
Poke Food Market
Specialty Foods
Luxury Cigar Market
Specialty Foods
Cat and Dog Food Toppers Market
Specialty Foods
Low Calorie Diet Meal Plan Market
Specialty Foods
Europe Halal Food and Beverage Market
Specialty Foods
Coconut Butter Market
Specialty Foods
Low Calorie Oatmeal Market
Specialty Foods
Guacamole Market
Specialty Foods
Wet Grain-Free Pet Food Market
Specialty Foods
Dog Food Toppers Market
Specialty Foods
Goldenseal Market