
 Global Hispanic Foods Market | 2026-2036
Global Hispanic Foods Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hispanic Foods Market Analysis
Food service operators is rotating toward authentic Hispanic menu components as fast-casual chains and independent restaurants compete for flavor differentiation. Gruma SAB de CV anchors North American tortilla production through vertically integrated corn milling and masa processing infrastructure. Goya Foods dominates shelf-stable Latin ingredient distribution across independent bodegas and mainstream retail channels. Grupo Bimbo SAB de CV extends its baked goods manufacturing scale into Hispanic-specific bread and snack categories across multiple geographies.
Hispanic foods encompass prepared and semi-prepared products derived from Latin American culinary traditions, typically featuring corn, chile peppers, beans, and tomatillo-based formulations processed through nixtamalization, fermentation, or thermal treatment for shelf stability or immediate consumption. The category serves both household meal preparation and commercial food service applications requiring consistent flavor profiles and scalable portion formats. Tortillas and salsas sustain the largest volume positions within product type segmentation, though sauce varieties command stronger margin pools through premium positioning. The food service channel leads distribution value capture as restaurants and food trucks drive bulk procurement of prepared salsas and masa-based substrates.
The FDA enforces ingredient safety and labeling standards for imported chiles, spices, and processed vegetable products entering US commerce, while Mexico's COFEPRIS regulates domestic food additive thresholds and nutritional claims on packaged Hispanic staples. These frameworks elevate compliance costs for cross-border suppliers but simultaneously reinforce quality-based market access for certified producers. Stakeholders must monitor evolving allergen disclosure requirements and organic certification pathways as consumer scrutiny intensifies around ingredient provenance and clean-label formulations.
Market Dynamics
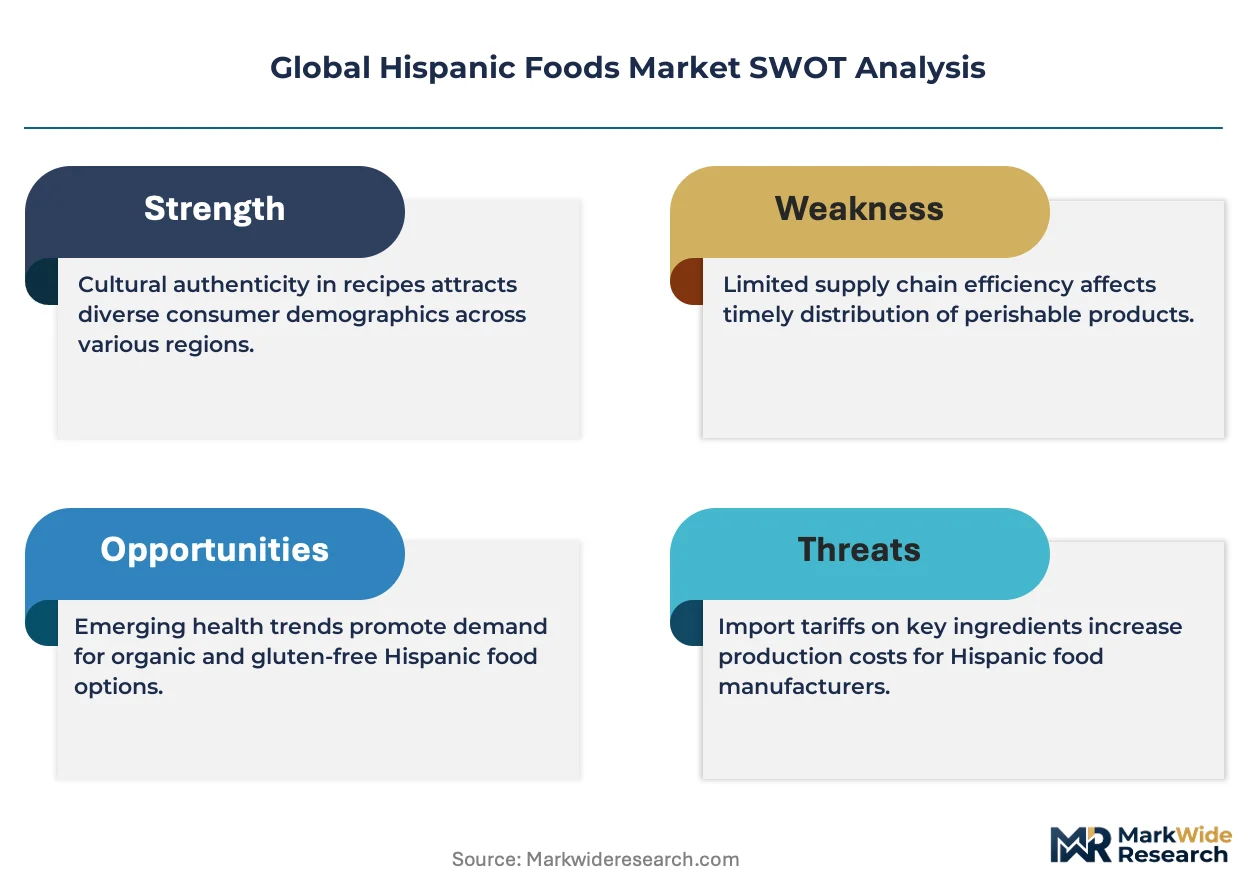
Authenticity-driven menu differentiation across US fast-casual chains is pulling masa-based substrates and heritage chile varieties into mainstream food service procurement at unprecedented scale. This demand rotation is restructuring supplier qualification protocols and cross-border logistics investments.
Growth Catalysts
- FDA's Food Safety Modernization Act:Updated traceability requirements for imported produce and spices are accelerating supplier consolidation toward certified producers with validated cold-chain documentation.
- Nixtamalization process modernization:Automated lime-cooking and stone-grinding systems are reducing labor intensity while preserving flavor profiles essential to heritage product positioning.
- Food truck and ghost kitchen proliferation:Mobile and virtual food service operators are creating bulk demand for pre-portioned salsas and ready-to-press masa with consistent viscosity specifications.
Market Restraints
- Heirloom corn input volatility:Climate-sensitive cultivation cycles in Oaxaca and Puebla create supply interruptions for non-GMO white and blue corn varieties essential to premium positioning.
- Single-origin supply concentration:Jalapeño and habanero chile processing clusters in Chihuahua and Yucatán expose buyers to weather-related crop failures and logistics bottlenecks.
- COFEPRIS additive threshold mismatches:Divergent maximum residue limits for colorants and preservatives between Mexican domestic and US export formulations force dual-formulation production runs.
Strategic Opportunities
- Colombia and Peru underpenetration:Andean heritage grain and aji pepper varieties remain absent from North American retail and food service channels despite established export infrastructure.
- Clean-label organic certification:USDA Organic and EU Organic equivalency agreements are opening premium shelf placement for additive-free masa harina and fermented hot sauce lines.
- Direct-to-restaurant e-procurement platforms:B2B marketplaces specializing in Latin ingredients are disintermediating traditional distributor markups for independent taquerias and bodegas.
Industry Challenges
- Nixtamalization specialist scarcity:Master millers with generational knowledge of lime ratios and grind calibration are retiring faster than vocational programs can replace them.
- Dual-label packaging complexity:Simultaneous FDA nutrition facts panels and COFEPRIS Spanish-language disclosures require specialized graphic design and inventory segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hispanic Foods Market |
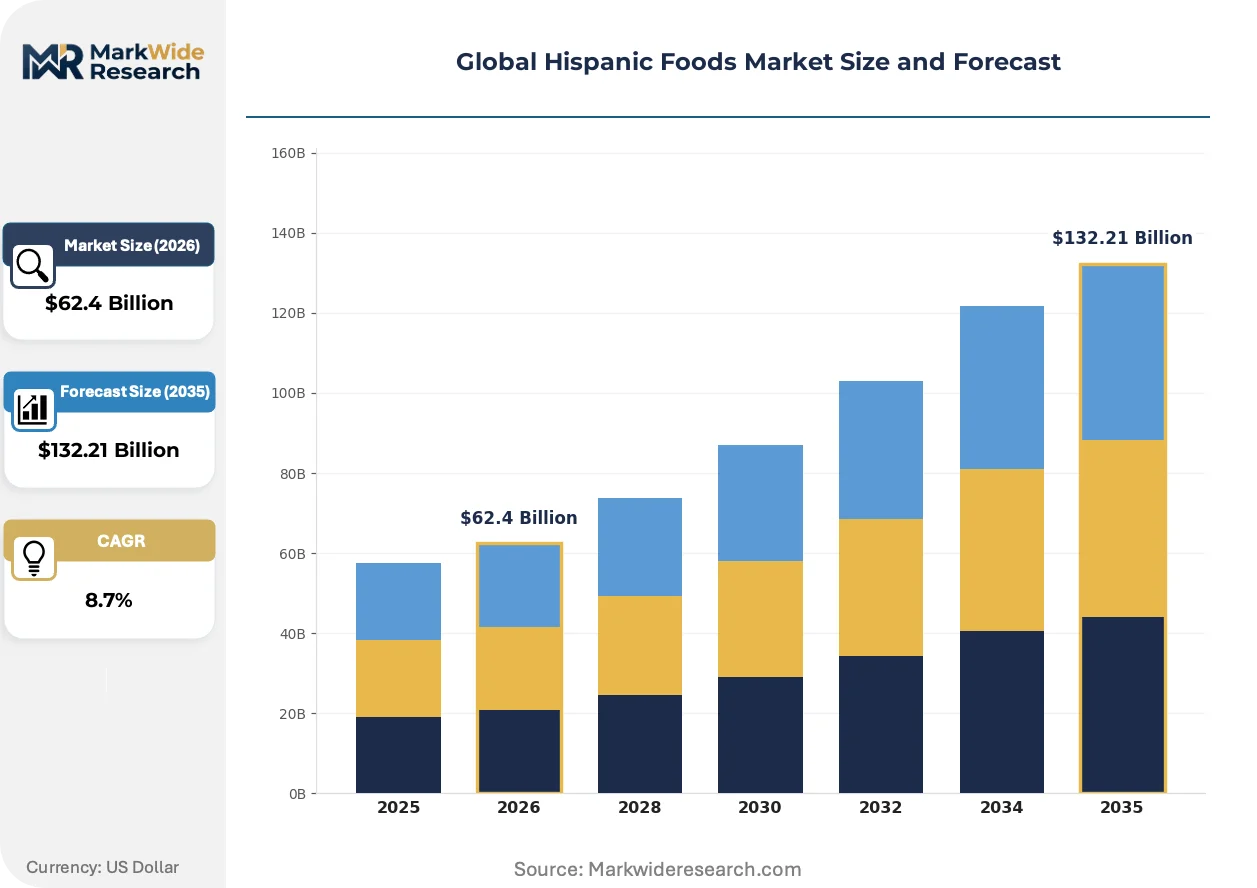
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $132.21 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tortillas, Salsas, Sauces, Snacks Flavor Profile: Spicy, Savory, Sweet, Tangy Distribution Channel: Online, Supermarkets, Specialty Stores, Food Service End User: Households, Restaurants, Cafes, Food Trucks |
| Companies Covered | Grupo Bimbo SAB de CV, Gruma SAB de CV, Goya Foods, B and G Foods Inc., Campbell Soup Co., General Mills, Conagra Brands, Hormel Foods Corp., The Kraft Heinz Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hispanic Foods Market Emerging Trajectories
Processing technology and procurement digitization are converging to compress production timelines while expanding the geographic sourcing radius for heritage ingredients. These shifts are redrawing competitive boundaries between artisanal and scaled producers.
High-pressure processing for refrigerated salsas and guacamole is displacing traditional thermal pasteurization in premium food service channels. National fast-casual chains are adopting HPP systems to extend refrigerated shelf life without flavor degradation from heat exposure. This technology is displacing conventional hot-fill operations and enabling regional distribution networks previously uneconomical for fresh products.
REACH compliance requirements for imported spice oleoresins and extractives are tightening contaminant screening protocols for EU-bound Hispanic sauces and seasoning blends. European importers now demand comprehensive pesticide residue testing and supply chain documentation exceeding baseline CODEX standards. Small and mid-size Mexican processors are responding by consolidating laboratory partnerships and abandoning spot-market raw material purchasing.
Chef-driven procurement is rotating toward single-origin chile varietals with documented terroir and harvest dates. Fine-dining establishments and upscale taquerias are bypassing commodity-grade ancho and guajillo powders for direct relationships with specific cooperatives in Zacatecas and San Luis Potosí. This pattern is most visible in Los Angeles, Houston, and Chicago metropolitan clusters where menu differentiation commands measurable price premiums.
Global Hispanic Foods Market Segmentation
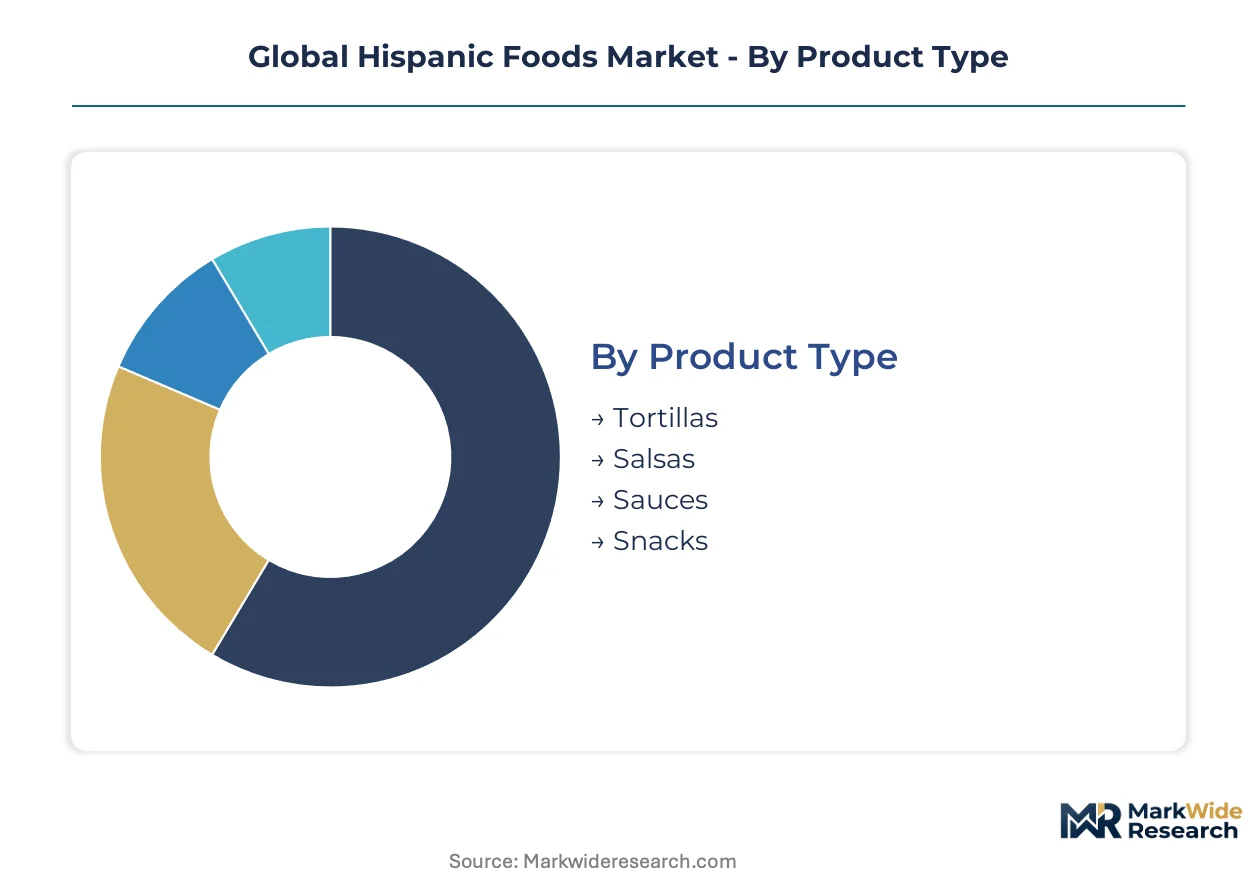
Channel configuration determines profitability thresholds across Hispanic food categories. Tortilla and salsa producers face divergent margin pressures depending on whether volume flows through retail grocers or food service distributors.
Product Type:
Channel mix splits sharply: tortillas and salsas move predominantly through food service bulk procurement, while sauces and snacks concentrate in retail shelf placement.
- Tortillas:Corn and flour variants processed through nixtamalization or industrial mixing. Food service operators in Texas and California drive bulk demand for 6-inch and 10-inch formats with specified moisture retention. Automated press lines now achieve 30,000 units per hour.
- Salsas:Fresh refrigerated, shelf-stable jarred, and high-pressure processed formats. Fast-casual chains specify Scoville consistency and viscosity for portion-controlled dispensing. HPP adoption is climbing fastest in premium food service channels.
- Sauces:Mole, enchilada, and cooking bases with extended shelf stability through thermal processing. Retail placement dominates.
- Snacks:Fried and baked formats including chicharrones, plantain chips, and seasoned corn products. Convenience store distribution is expanding.
Tortillas dominate installed base. Salsas are where expansion concentrates.
Flavor Profile:
Cost tier stratification separates commodity blends from single-origin varietals commanding price premiums.
- Spicy:Chile-forward formulations ranging from jalapeño to habanero and ghost pepper heat levels. Food trucks in Houston and Los Angeles specify Scoville-targeted batches for menu differentiation.
- Savory:Umami-rich profiles built on tomato, garlic, and cumin foundations. Household penetration is highest for this accessible profile.
- Sweet:Dulce de leche, cajeta, and fruit-based dessert applications. Specialty store placement is expanding most quickly.
- Tangy:Tomatillo and citrus-fermented profiles. Chef-driven procurement in Chicago and Miami is elevating this segment.
Savory holds the largest volume position. Spicy is climbing the fastest.
Distribution Channel:
Customer type determines pack size, labeling burden, and cold-chain requirements.
- Online:Direct-to-consumer and B2B marketplace platforms. Independent taquerias in secondary US metros are adopting e-procurement for heritage ingredients.
- Supermarkets:Mass retail placement requiring bilingual packaging and COFEPRIS-compliant Spanish labeling. Volume scale is concentrated here.
- Specialty Stores:Independent bodegas and Latin-focused grocers. Authenticity signaling through origin labeling commands premium positioning.
- Food Service:Restaurant, cafeteria, and institutional supply. Bulk viscosity specifications and consistent Scoville targeting are mandatory.
Food service captures the highest value per unit. Online is gaining share fastest.
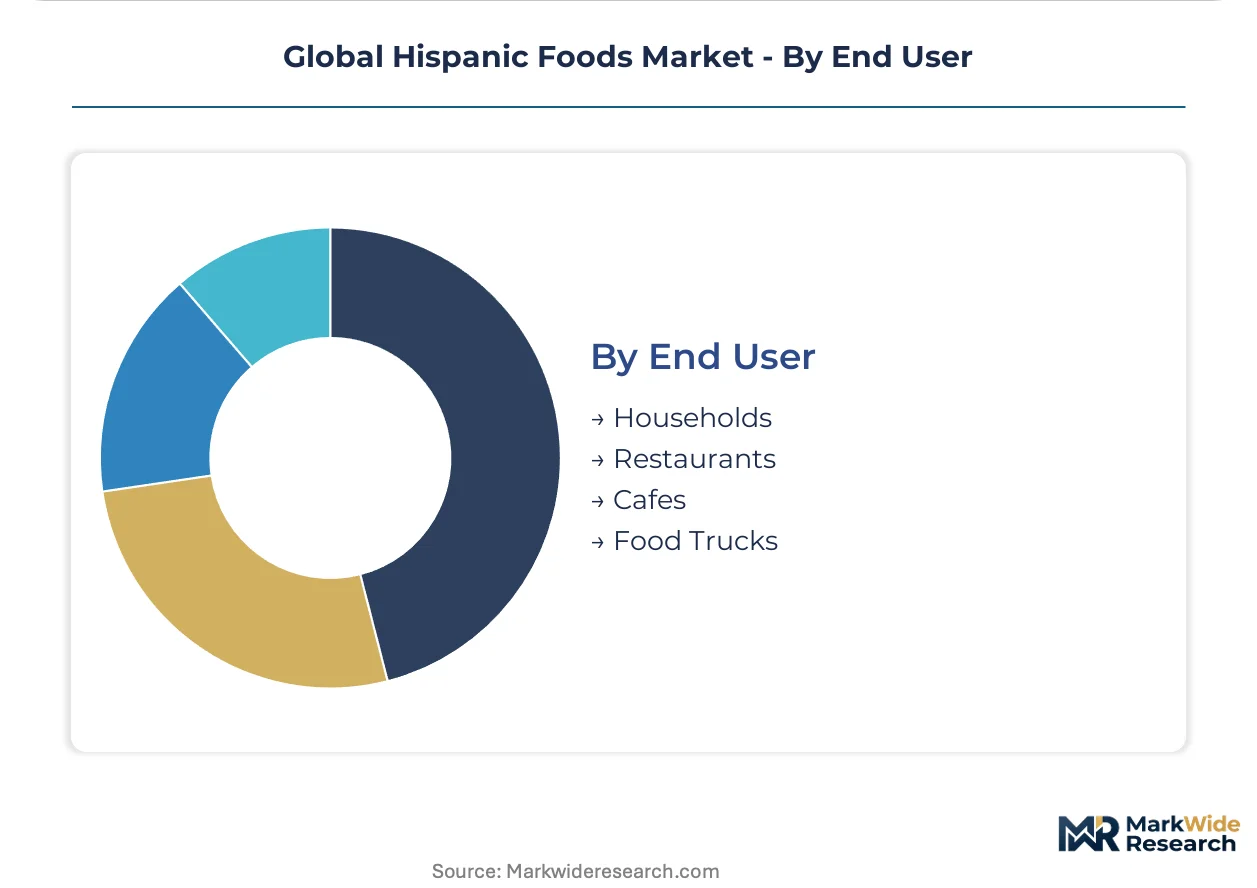
End User:
Application requirements diverge between meal preparation and commercial menu execution.
- Households:Retail-packaged formats with extended shelf life and bilingual instruction panels. Weekly purchase frequency supports volume.
- Restaurants:Full-service establishments requiring consistent batch characteristics for menu standardization. Fine-dining operators in Mexico City specify single-origin chile documentation.
- Cafes:Breakfast and coffee-focused operators integrating breakfast taco and mollete applications. Morning daypart demand is expanding.
- Food Trucks:Mobile operators with space-constrained storage requiring shelf-stable or frozen formats with rapid preparation protocols. Ghost kitchen affiliates are multiplying this channel.
Restaurants anchor procurement volume. Food trucks are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Veracruz's container terminal expansion underwrites Mexico's central role in heritage corn and masa supply chains serving North American food service networks. Cross-border rail corridors from this hub connect directly to Texas distribution centers.
United States
Fast-casual chains in Houston, Los Angeles, and Chicago drive bulk procurement of single-origin chile varietals and HPP-processed salsas. The FDA's updated FSMA traceability rules are disqualifying uncertified Mexican suppliers from import eligibility. Texas border cities concentrate tortilla manufacturing capacity to minimize freight exposure to input volatility.
Mexico
Oaxaca and Puebla anchor heirloom corn cultivation for premium nixtamalization, though climate stress is compressing harvest windows. COFEPRIS regulates domestic additive thresholds that diverge from US export requirements, forcing dual-formulation production. Mexico City Metro hosts the largest concentration of master millers with generational lime-cooking expertise.
Spain
Barcelona and Madrid food service operators are importing Andean aji pepper varieties for menu differentiation in competitive tapas segments. EFSA pesticide residue standards exceed CODEX baselines for imported spice oleoresins. Valencia's port infrastructure is expanding cold-chain capacity for refrigerated Latin American sauces entering EU commerce.
Colombia
Bogotá-based distributors are building export pipelines for heritage grain varieties and fermented hot sauce lines previously absent from North American channels. The national agricultural regulator enforces phytosanitary certification for aji pepper shipments. Antioquia Department concentrates small-batch processing facilities serving chef-driven procurement in Miami and New York.
Peru
Lima's coastal processing clusters are scaling production of shelf-stable rocoto and amarillo pepper pastes for US specialty retail placement. SENASA administers export health certificates that align with USDA organic equivalency protocols. Arequipa's dairy infrastructure supports cajeta and dulce de leche output targeting dessert applications in California and Texas markets.
Global Hispanic Foods Market Vendor Landscape
Listed leaders compete with private specialists across capital access and heritage authenticity positioning. The vendor base splits between scale-driven multinationals with integrated milling infrastructure and family-owned specialists commanding premium placement through origin documentation. Three archetypes dominate: vertically integrated corn processors, shelf-stable ingredient distributors with bodega channel control, and chef-facing specialists in single-origin chile sourcing. Capacity expansion and backward integration into heirloom corn procurement represent the dominant competitive moves.
Within the scale-driven tier, Gruma SAB de CV and Grupo Bimbo SAB de CV occupy positions defined by captive supply chain control. Goya Foods exemplifies the distribution-architype model. These three anchors illustrate how geographic concentration in Mexico City and Monterrey intersects with divergent channel strategies—bulk food service supply versus retail shelf placement versus independent bodega penetration.
| Leading Market Players |
|---|
| Grupo Bimbo SAB de CV |
| Gruma SAB de CV |
| Goya Foods |
| B and G Foods Inc. |
| Campbell Soup Co. |
| General Mills |
| Conagra Brands |
| Hormel Foods Corp. |
| The Kraft Heinz Co. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Texas tortilla manufacturers and Oaxaca heirloom corn cooperatives lock in both supply access and price visibility for premium nixtamalization inputs. These arrangements insulate buyers from spot-market volatility in blue and white corn varieties while securing COFEPRIS-compliant harvest documentation for FDA import eligibility.
Pricing Analysis
Volume-discount tiering structures separate food service bulk procurement from retail shelf placement across masa harina and salsa categories. Three-tier pricing stratification across heritage-certified, commercial-grade, and economy formulations reflects organic certification status and single-origin documentation. Cost compression in economy tiers intensifies as automated nixtamalization displaces artisanal production. Quick-service restaurants exhibit highest price sensitivity, while fine-dining operators in Los Angeles and Houston absorb premiums for documented terroir.
Supply Chain Analysis
The Port of Veracruz container terminal expansion constitutes a chokepoint underwriting North American distribution of heritage corn and chile pepper shipments. Mexico, the United States, and Peru anchor supply concentration for nixtamalized substrates and aji pepper varieties. Raw material flows draw from Oaxaca heirloom corn cultivation, Chihuahua jalapeño processing clusters, and Antioquia small-batch facilities. Single-source vulnerability in generational master miller expertise threatens continuity. Distribution runs through cross-border rail corridors into Texas distribution centers serving fast-casual chain networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chef-driven procurement fragmentation creates white-space opportunities for specialists commanding authenticity premiums through documented origin. Fast-casual menu differentiation multiplies niche demand for single-varietal chiles and heritage grain substrates.
For Market Incumbents: Compound channel control through backward integration into Oaxaca and Puebla heirloom corn procurement. Master miller apprenticeship programs counter generational knowledge attrition threatening nixtamalization consistency. COFEPRIS-FDA dual-label packaging automation reduces inventory segmentation costs. HPP equipment deployment captures premium food service salsa demand from thermal-pasteurization competitors. For New Entrants and Emerging Players: Direct-to-restaurant e-procurement platforms address incumbent under-service of independent taquerias and ghost kitchen operators in secondary US metros. Colombia and Peru heritage grain varieties offer the most penetrable geography for North American market entry. USDA Organic certification investment unlocks premium shelf placement in specialty retail channels previously closed to unverified suppliers. For Investors and Strategic Acquirers: Family-owned cooperatives with documented single-origin chile relationships and COFEPRIS export certification represent priority acquisition targets. Long-term viability hinges on climate-resilient cultivation partnerships and cold-chain infrastructure ownership. FDA FSMA enforcement intensity serves as the critical signal to watch for supplier consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Heirloom Corn Procurement Partnerships | Backward integration into Oaxaca and Puebla cultivation secures non-GMO supply for premium positioning. |
| High-Pressure Processing Deployment | HPP system adoption extends refrigerated salsa shelf life without FDA-mandated thermal degradation. |
| Master Miller Apprenticeship Programs | Vocational training addresses generational knowledge scarcity threatening nixtamalization quality consistency. |
| Dual-Label Packaging Automation | COFEPRIS Spanish and FDA English panel integration reduces inventory segmentation complexity. |
| Direct-to-Restaurant E-Procurement Launch | B2B marketplace platforms disintermediate distributor markups for independent taqueria networks. |
Methodological Framework
Desk research of FDA import compliance databases, COFEPRIS additive threshold filings, and customs trade records preceded structured interviews with tortilla plant managers, fast-casual chain procurement directors, specialty store category buyers, and nixtamalization equipment engineers. Primary fieldwork captured operational constraints in Veracruz port logistics and Oaxaca heirloom corn cultivation cycles. Secondary validation drew from SEC filings of listed food manufacturers, Nielsen retail audit data, and USDA organic certification registries. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Variance decomposition across product type, flavor profile, distribution channel, and end-user application dimensions shaped analytical framework construction throughout the projection horizon. CAGRs derived from installed base growth rates and per-unit value capture trajectories in food service versus retail channels. Forecast inputs incorporated nixtamalization automation adoption curves and HPP equipment penetration in premium salsa processing.
Forecasts assume regulatory continuity in FDA FSMA traceability requirements and COFEPRIS domestic additive thresholds; material policy shifts would require re-modeling of cross-border supplier qualification protocols. Climate stress in Oaxaca and Puebla cultivation zones, master miller retirement velocity, and REACH compliance evolution for EU-bound spice oleoresins represent specific risk factors that could revise projections. Practitioners should keep alternative scenarios live as heirloom corn harvest window compression and ghost kitchen proliferation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Brahmi Market
Specialty Foods
Asia-Pacific Alcohol-Infused Ice Cream Market
Specialty Foods
Yeast-Based Spreads Market
Specialty Foods
Low Fat Hummus Market
Specialty Foods
Manuka Honey Market
Specialty Foods
Konjac Noodles Market
Specialty Foods
Vegetarian Tacos Market
Specialty Foods
Cat Food Toppings Market
Specialty Foods
Europe Gluten-Free Breakfast Cereals Market
Specialty Foods
Edible Cutlery Market
Specialty Foods
Cat and Dog Food Toppers Market
Specialty Foods
Reishi Mushroom Market
Specialty Foods
Gluten-Free Desserts and Ice Creams Market
Specialty Foods
Global Nata De Coco Market
Specialty Foods
Miso Market
Specialty Foods
Low Fat and Low Carb Foods Market