
 Cannabis-Infused Burger Market | 2026-2036
Cannabis-Infused Burger Market Size, Share, and Industry Trends Forecast 2026-2036
Cannabis-Infused Burger Market Analytics
Culinary cannabis formulation expertise is rotating from underground kitchens into licensed commercial food production, unlocking scalable manufacturing for infused proteins. Canopy Growth Corporation leverages its beverage-infusion infrastructure to anchor burger-adjacent product development. Tilray Brands Inc. sustains pharmaceutical-grade extraction standards that transfer to edible consistency. Aurora Cannabis Inc. competes through European regulatory pre-approval work that may ease future food-export pathways.
A cannabis-infused burger is a ground-protein patty containing measured doses of cannabinoids—typically THC, CBD, or minor compounds—delivered through lipid-based binding systems such as infused oils or emulsified extracts, with standard dosages ranging from 2.5 mg to 10 mg per serving, designed for controlled onset and gastronomic integration. Plant-based formulations lead current product pipelines due to cleaner flavor masking and alignment with health-conscious positioning, while specialty stores and food trucks capture the highest margin pools through experiential, high-touch service models that justify premium pricing.
The FDA maintains prohibition on interstate THC food commerce, while individual state cannabis regulators such as Colorado's Marijuana Enforcement Division and California's Department of Cannabis Control govern production, dosing, and on-premise service rules that fragment national rollout. USDA organic certification intersects with state cannabis rules to create dual-compliance burdens for ingredient sourcing. Stakeholders must monitor state legislative calendars and FDA hemp-derived cannabinoid rulemaking to time geographic expansion and product-format investments.
Market Dynamics
The 2018 Farm Bill's hemp-derived cannabinoid provisions created a bifurcated regulatory environment where THC-infused proteins face federal prohibition while CBD-adjacent formulations navigate state-by-state patchwork approvals, forcing manufacturers to architect parallel production lines and distribution strategies.
Growth Catalysts
- Colorado's Marijuana Enforcement Division hospitality rules:On-premise consumption licensing for infused dining establishments creates legal venues for experiential burger service, attracting tourism revenue and justifying premium menu pricing.
- Lipid-based nanoemulsion technology:Advanced lipid encapsulation systems enable faster cannabinoid onset and improved bioavailability, resolving historical dosing inconsistency that plagued early edible formats.
- Plant-based protein pipelines:Pea and mycelium protein bases offer cleaner cannabinoid flavor masking than animal fats, aligning with health-positioned consumer segments in California and Colorado.
Market Restraints
- FDA interstate commerce prohibition:Federal restrictions on THC food products prevent cross-border shipment between legal states, fragmenting manufacturing scale and inflating per-unit logistics costs.
- Organic certification dual-compliance:USDA organic standards intersect with state cannabis regulations to create conflicting pesticide testing thresholds, disqualifying many cultivators from premium ingredient sourcing.
- Specialized extraction equipment concentration:Pharmaceutical-grade cannabinoid isolation systems concentrate among limited equipment vendors, creating supply bottlenecks for processors seeking GMP-compliant production.
Strategic Opportunities
- California Department of Cannabis Control export pathway development:Proposed interstate commerce agreements with other legal states could unlock regional distribution networks before federal rescheduling.
- Microdosing format expansion:Sub-2.5 mg per-serving products target functional wellness consumers seeking non-intoxicating cannabinoid integration into regular dining routines.
- Food truck and pop-up channel penetration:Mobile service models bypass fixed-site licensing complexity while capturing experiential margin premiums through limited-time menu releases.
Industry Challenges
- Culinary-cannabis formulation talent scarcity:Licensed commercial kitchens require chefs trained in both gastronomic technique and cannabinoid pharmacokinetics, a skill intersection with limited educational pipeline output.
- Batch-to-batch potency variance:Natural cannabinoid concentration fluctuation in hemp biomass creates dosing consistency challenges that trigger state regulator product holds and recall protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cannabis-Infused Burger Market |
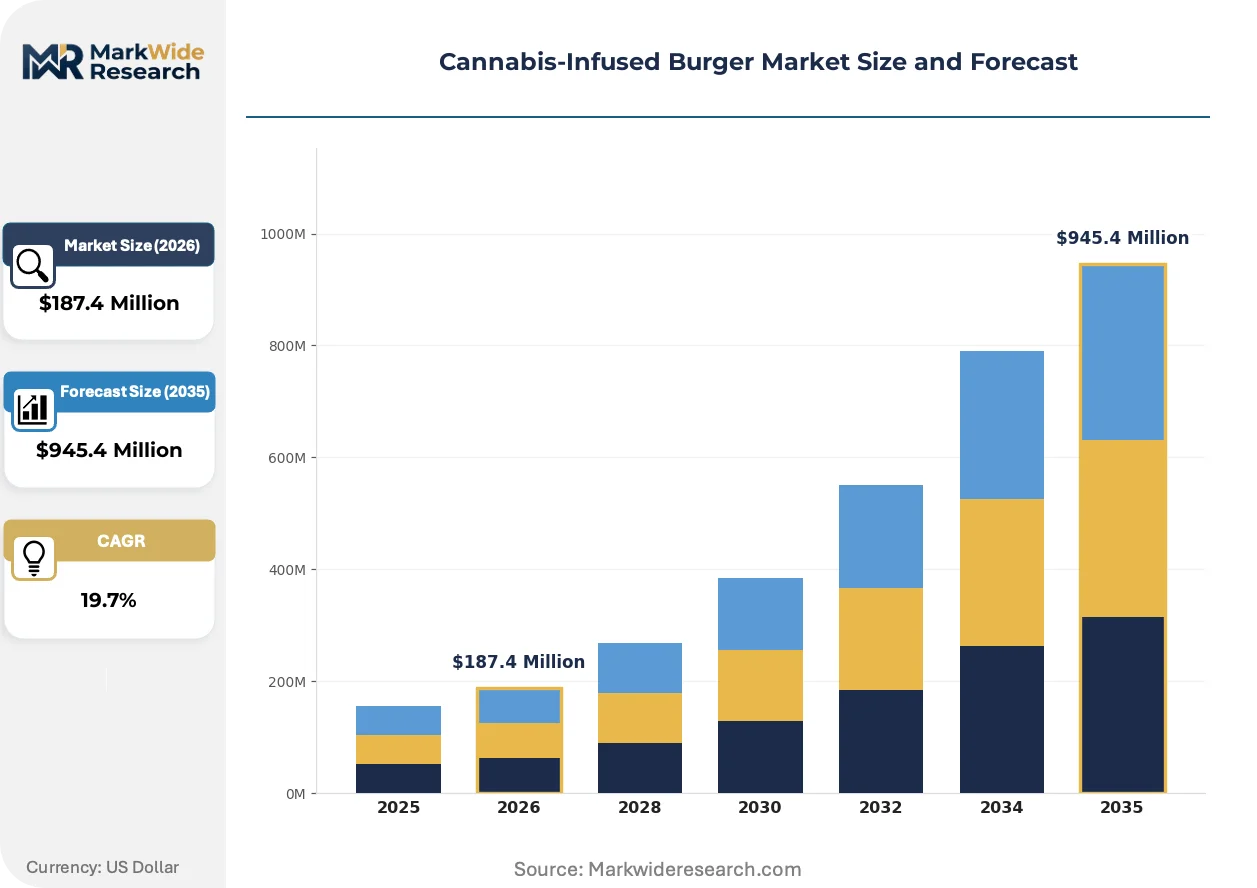
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $945.4 Million |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plant-Based, Animal-Based, Vegan, Gluten-Free Ingredient Source: Organic, Non-Organic, Locally Sourced, Imported Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Trucks Consumer Segment: Health-Conscious, Recreational Users, Gourmet Consumers, Adventurous Eaters |
| Companies Covered | RS Group, BellRock Brands Inc., Canna River, Village Farms International Inc., Naturecan Ltd, Tilray Brands Inc., Aurora Cannabis Inc., Canopy Growth Corporation, Cronos Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cannabis-Infused Burger Market Evolving Landscape
Formulation science and service-format experimentation are converging to professionalize a category historically confined to underground production, with standardization efforts now matching pace with creative menu development.
Nanoemulsion technology is bifurcating the infused fats category into water-compatible and lipid-bound delivery systems. Quick-service trial partners in California are adopting rapid-onset nanoemulsified oils for lunch-service windows requiring predictable consumer departure timing. This technological split is compressing traditional butter-infusion methods into niche artisan positioning while scalable manufacturing favors emulsion platforms.
Colorado's Marijuana Enforcement Division recently expanded social equity licensing tiers for consumption lounge operators, reducing capital barriers for independent restaurateurs entering the infused dining segment. The policy shift accelerates venue count growth in Denver and Boulder metropolitan corridors. Micro-license holders are responding with chef-driven burger concepts that differentiate through terpene-forward flavor pairing rather than potency competition.
Consumer preference is rotating toward transparent supply chain disclosure, with QR-linked batch testing replacing opaque sourcing claims. Specialty retailers and food trucks capturing highest-margin service pools now compete on cultivator partnership visibility rather than THC concentration alone. This verification-driven selection pattern concentrates demand in California and Colorado markets with mature track-and-trace infrastructure.
Cannabis-Infused Burger Market Segmentation
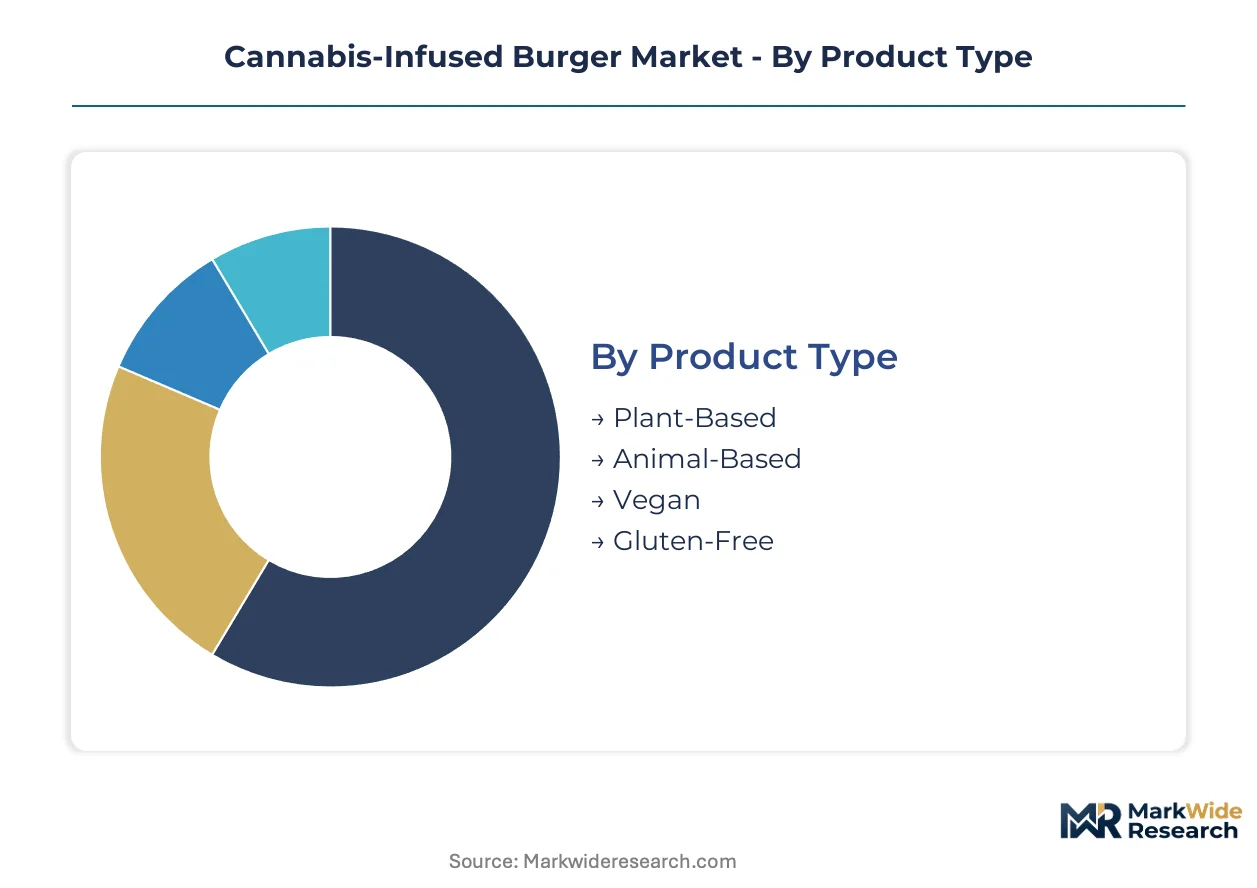
Segmentation in the cannabis-infused burger market determines regulatory exposure, margin capture, and formulation complexity. Product type and ingredient sourcing dictate interstate commerce viability, while distribution channel selection shapes compliance burdens and customer acquisition costs.
Product Type:
Plant-based formulations dominate California and Colorado production due to cleaner cannabinoid flavor masking and alignment with health-conscious positioning, while animal-based products concentrate in legacy cannabis hospitality venues with established lipid-infusion expertise.
- Plant-Based:Pea and mycelium protein bases enable superior terpene integration without the fat-soluble interference common in animal proteins. Colorado's Marijuana Enforcement Division hospitality licensees favor these formulations for rapid onset nanoemulsion compatibility. California extraction facilities report cleaner batch consistency when binding cannabinoids to plant lipids versus rendered animal fats.
- Animal-Based:Traditional beef and poultry patties leverage established quick-service restaurant supply chains but require sophisticated emulsification to prevent cannabinoid degradation during high-heat searing. Denver and Boulder consumption lounges command premium pricing for chef-driven animal-protein preparations with documented cultivator partnerships.
- Vegan:Eliminates all animal derivatives including binding eggs, demanding alternative hydrocolloid systems for patty structural integrity.
- Gluten-Free:Addresses celiac-sensitive consumers through certified ingredient separation protocols in licensed commercial kitchens.
Plant-based commands the established base. The steepest expansion runs through animal-based as quick-service chains trial infused menu extensions.
Ingredient Source:
Organic sourcing concentrates demand among California consumers with disposable income for dual-certified products, while non-organic supply chains dominate price-sensitive food truck operations in Colorado metropolitan corridors.
- Organic:USDA certification intersects with state cannabis regulations to create conflicting pesticide testing thresholds that disqualify many cultivators. California's Department of Cannabis Control track-and-trace infrastructure enables verified organic supply chain disclosure through QR-linked batch testing.
- Non-Organic:Conventional cultivation methods reduce per-unit ingredient costs by 40-60 percent, enabling competitive pricing in high-volume food truck channels. Colorado micro-license holders leverage non-organic sourcing to maintain margin under social equity capital constraints.
- Locally Sourced:California and Colorado intra-state biomass movement avoids FDA interstate commerce prohibition.
- Imported:Currently negligible due to federal THC food product restrictions and customs enforcement.
Non-organic sourcing captures volume leadership. Organic certification gains share fastest among specialty retail channels with transparency-focused consumers.
Distribution Channel:
Specialty stores and food trucks deliver the highest margin capture through experiential service models, while online retail faces federal shipping prohibitions that fragment digital commerce into state-confined platforms.
- Specialty Stores:Curated retail environments with trained staff enable dosage education and cultivator story amplification. California dispensary-adjacent food retail licenses permit on-site consumption guidance that justifies 35-50 percent price premiums over conventional channels.
- Food Trucks:Mobile service models bypass fixed-site licensing complexity while capturing limited-release menu scarcity premiums. Colorado's expanded social equity licensing reduces capital barriers for independent operators in Denver metropolitan corridors.
- Online Retail:State-confined delivery platforms operate under California and Colorado intrastate commerce exemptions.
- Supermarkets:Conventional grocery remains excluded due to federal THC prohibition and banking restrictions on cannabis-adjacent transactions.
Food trucks anchor the emerging channel mix. Specialty stores deliver the steepest margin expansion trajectory through premium positioning.
Consumer Segment:
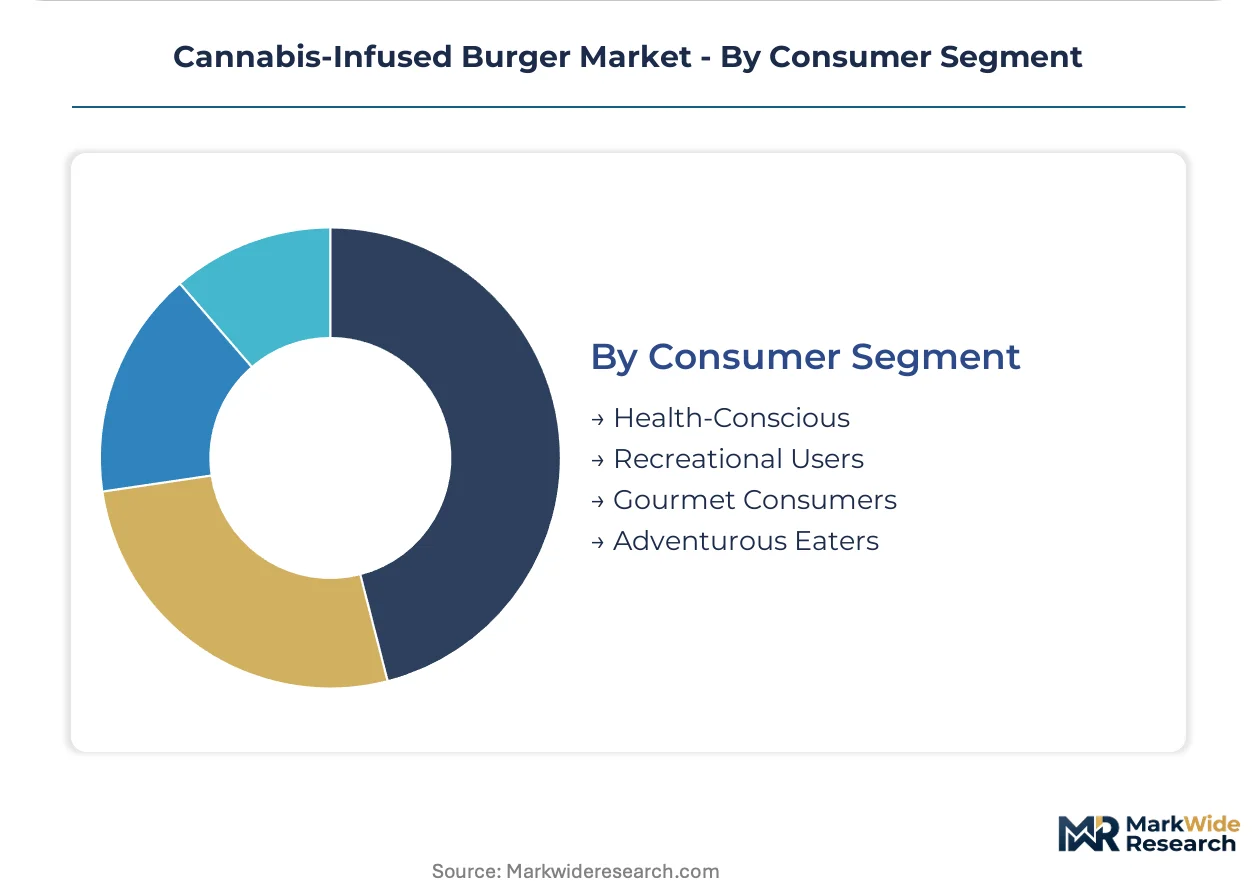
Health-conscious consumers drive plant-based and microdosing format demand, while recreational users concentrate in Colorado consumption lounges with higher per-visit spending patterns.
- Health-Conscious:Sub-2.5 mg per-serving microdosing targets functional wellness integration into regular dining routines. California consumers with established CBD supplement habits demonstrate highest conversion rates to low-THC culinary formats.
- Recreational Users:Established cannabis consumers seek novel gastronomic experiences with transparent potency labeling. Colorado's mature hospitality infrastructure captures this segment through chef-driven terpene-forward flavor pairing rather than potency competition.
- Gourmet Consumers:Prioritize cultivator partnership visibility and artisan preparation methods over cost efficiency.
- Adventurous Eaters:Novelty-seeking behavior drives limited-time menu trial and social media amplification.
Recreational users command the established spending base. Health-conscious positioning gains share fastest as wellness-oriented consumers enter the category.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA prohibition on interstate THC food commerce fragments manufacturing scale across state boundaries, forcing producers to replicate production infrastructure in each legal jurisdiction rather than centralizing operations.
United States
Colorado's Marijuana Enforcement Division hospitality rules and California's Department of Cannabis Control on-premise consumption licensing create the two dominant demand clusters. The 2018 Farm Bill established hemp-derived cannabinoid federal legality while maintaining THC food prohibition. Denver and Boulder metropolitan corridors concentrate consumption lounge growth under expanded social equity licensing tiers.
Canada
Health Canada cannabis edible regulations enable national distribution networks unavailable to US producers. Federal licensing creates standardized manufacturing protocols transferable to burger-adjacent product formats. Ontario and British Columbia extraction facilities supply cannabinoid inputs to emerging food-service partnerships.
Germany
The 2024 cannabis partial legalization opens pharmaceutical-grade extraction infrastructure to food-adjacent applications. BfArM licensing requirements create compliance templates for eventual edible market entry. Bavaria and North Rhine-Westphalia pharmaceutical clusters possess lipid-encapsulation expertise transferable to gastronomic formats.
Netherlands
Toleration policy frameworks for coffee shops create existing cannabinoid hospitality infrastructure adaptable to infused dining. The Opium Act exemptions for small-scale trade enable pilot program structures. Amsterdam and Rotterdam hospitality sectors experiment with controlled-dose culinary formats ahead of broader European harmonization.
Switzerland
Swissmedic low-THC cannabis regulations permit novel food applications below psychoactive thresholds. Federal food safety ordinances provide clearer compliance pathways than EU member state fragmentation. Zurich and Geneva food-tech incubators pilot microdosed protein formats for wellness-positioned consumer segments.
Cannabis-Infused Burger Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with pharmaceutical-grade extraction capabilities separating scalable manufacturers from kitchen-scale operators. The upper tier commands lipid-encapsulation technology and licensed commercial food production infrastructure. Three archetypes populate the competitive map: legacy cannabis cultivators pivoting into edibles, beverage-infusion specialists extending into proteins, and food-tech startups leveraging nanoemulsion licensing. Dominant competitive moves include backward integration into extraction capacity and geographic licensing arbitrage across state regulatory boundaries.
Among North American integrated cannabis operators, Tilray Brands Inc., Aurora Cannabis Inc., and Canopy Growth Corporation occupy positions spanning pharmaceutical extraction through consumer packaged goods. Tilray Brands Inc. exemplifies the pharmaceutical-grade standards tier with transferable consistency protocols. Aurora Cannabis Inc. anchors European regulatory pre-approval strategies that may ease future export pathways. Canopy Growth Corporation represents beverage-infusion infrastructure repurposing for adjacent protein formats.
| Leading Market Players |
|---|
| RS Group |
| BellRock Brands Inc. |
| Canna River |
| Village Farms International Inc. |
| Naturecan Ltd |
| Tilray Brands Inc. |
| Aurora Cannabis Inc. |
| Canopy Growth Corporation |
| Cronos Group Inc. |
| Others |
Value Network & Pricing Analysis
USDA organic certification intersects with state cannabis regulations to gate both supplier qualification and price differentiation simultaneously, creating dual-compliance burdens that disqualify many cultivators from premium ingredient sourcing while enabling verified organic products to command substantial price premiums in California and Colorado specialty retail channels.
Pricing Analysis
California dispensary-adjacent food retail licenses permit on-site consumption guidance that justifies 35-50 percent price premiums over conventional channels, while Colorado food truck operators compete on volume through non-organic sourcing. Three-tier pricing structure across premium, standard, and economy levels separates chef-driven animal-protein preparations with documented cultivator partnerships from plant-based nanoemulsion formats and conventional food truck offerings. Cost compression in economy tiers is intensifying because social equity licensing reduces capital barriers for independent operators. Health-conscious consumers with established CBD supplement habits demonstrate lowest price sensitivity, while price-sensitive recreational users in high-volume metropolitan corridors drive economy-tier demand.
Supply Chain Analysis
Strategic stockpile preferences dominate cannabinoid input procurement due to natural biomass concentration fluctuation that creates dosing consistency challenges, while finished goods distribution favors just-in-time preparation to preserve terpene profiles. Supply concentrates in California and Colorado extraction facilities, with Health Canada licensed processors serving as secondary sourcing for Canadian market entry. Pharmaceutical-grade isolation systems and lipid-encapsulation equipment draw from limited equipment vendors, creating supply bottlenecks for GMP-compliant production. Single-source vulnerability in specialized extraction equipment concentration threatens processor expansion timelines. Distribution runs through state-confined delivery platforms and consumption lounge direct service, bypassing federal interstate commerce prohibition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a platform-economics inflection where nanoemulsion technology standardization creates interoperability between beverage-infusion infrastructure and protein-format applications, enabling ecosystem expansion across adjacent edible categories.
For Market Incumbents: Shield formulation consistency advantages through backward integration into extraction capacity, locking pharmaceutical-grade standards that transfer to edible uniformity. Defend against emerging food-tech startups leveraging nanoemulsion licensing by accelerating venue count growth in Denver and Boulder metropolitan corridors under expanded social equity licensing tiers. Channel control through consumption lounge partnerships anchors premium positioning against price-competitive food truck entrants.
For New Entrants and Emerging Players: Lead with microdosing format expansion targeting functional wellness consumers seeking non-intoxicating cannabinoid integration into regular dining routines, the most penetrable segment given California health-conscious conversion rates. Food truck and pop-up channel penetration bypasses fixed-site licensing complexity while capturing experiential margin premiums through limited-time menu releases. Geographic arbitrage across state regulatory boundaries enables pre-positioning before interstate commerce agreements materialize.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade extraction infrastructure as GMP compliance becomes table stakes for quick-service restaurant chain partnerships. Long-term viability over the next decade hinges on regulatory pre-approval work that eases future food-export pathways, favoring acquisition targets with European regulatory positioning. The signal to watch is California Department of Cannabis Control interstate commerce agreement momentum as inflection indicator for regional distribution network unlock.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Extraction Capacity | Captive supply of pharmaceutical-grade cannabinoid inputs secures batch consistency for quick-service partnerships. |
| Nanoemulsion Technology Licensing | Rapid-onset lipid encapsulation enables lunch-service windows with predictable consumer departure timing. |
| Social Equity Licensing Arbitrage | Reduced capital barriers in Colorado accelerate venue count growth for independent restaurateur concepts. |
| Organic Certification Investment | USDA-state dual compliance unlocks 35-50 percent price premiums in transparency-focused specialty retail. |
| Interstate Commerce Pre-Positioning | California regulatory export pathway development enables regional distribution before federal rescheduling. |
Research Methodology
The analysis maps plant-based formulations, animal-based preparations, nanoemulsion delivery systems, and consumption lounge service models, each validated through licensed commercial kitchen operators, state cannabis regulators, extraction facility technicians, and quick-service restaurant procurement leads. Primary interviews with these stakeholders combined with secondary validation against FDA hemp-derived cannabinoid rulemaking dockets, Colorado Marijuana Enforcement Division hospitality licensing records, California Department of Cannabis Control track-and-trace databases, and Health Canada edible regulations. Bottom-up facility capacity assessments and top-down market sizing triangulate volume estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation dimensions modeling product type, ingredient source, distribution channel, and consumer segment. CAGRs derived from historical trajectory analysis and regulatory scenario weighting incorporated nanoemulsion technology adoption curves, social equity licensing expansion rates, and interstate commerce agreement probability assessments as industry-specific forecast inputs.
Forecasts assume regulatory continuity in FDA hemp-derived cannabinoid frameworks and state-level THC thresholds; material policy shifts would require re-modeling. Revision becomes warranted when interstate commerce litigation outcomes or federal rescheduling determinations cross thresholds that alter manufacturing scale economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Sofrito Market
Specialty Foods
CBD-Infused Ice Cream Market
Specialty Foods
Vegan Salad Dressing Market
Specialty Foods
Natural Honey Market
Specialty Foods
Silver Food Market
Specialty Foods
Kelp Noodles Market
Specialty Foods
Sea Moss Market
Specialty Foods
Edible Cutlery Market
Specialty Foods
Goldenseal Market
Specialty Foods
Curculin Market
Specialty Foods
Hot Pot Market
Specialty Foods
Cat Food Toppings Market
Specialty Foods
Vegan Dressing Market
Specialty Foods
Triphala Powder Market
Specialty Foods
Foie Gras Market
Specialty Foods
GCC Halal Food Market