
 Low Salt Low Fat Meals Market | 2026-2036
Low Salt Low Fat Meals Market Size, Share, and Industry Trends Forecast 2026-2036
Low Salt Low Fat Meals Market Analytics
Premium nutritional certification tiers is reorganizing competitive dynamics in prepared meals. Nestle sustains extensive frozen distribution networks across North American retail channels. General Mills differentiates through heritage brand portfolios reformulated for reduced sodium profiles. Tyson Foods leverages vertically integrated poultry supply chains to control fat content at the protein sourcing stage.
Low salt low fat meals are prepared food products formulated with sodium content below established dietary guidelines and reduced lipid fractions, typically employing steam cooking, vacuum sealing, and controlled-temperature processing to preserve organoleptic properties while meeting clinical dietary requirements. Ready-to-eat meals command substantial shelf-space allocations in health-focused retail as consumers prioritize convenience without nutritional compromise. Frozen meals retain dominant volume share due to extended preservation timelines and established cold-chain logistics, though meal kits attract premium positioning through customizable ingredient sourcing and portion control.
FDA sodium reduction guidelines and USDA school nutrition standards directly constrain permissible salt levels in commercially distributed prepared foods, while EPA packaging regulations influence sustainable material transitions across meal formats. Health Canada and EFSA parallel frameworks create compliance complexity for multinational suppliers operating across North American and European jurisdictions. Stakeholders must monitor evolving front-of-package labeling mandates and their downstream effects on consumer purchase behavior and retail placement algorithms.
Market Dynamics
FDA sodium reduction mandates are compressing allowable salt thresholds across prepared food categories, forcing reformulation investments and supplier qualification changes throughout the value chain.
Growth Catalysts
- Medicare Advantage Coverage:US health plans now reimburse medically tailored meals for chronic disease management, expanding institutional procurement channels beyond traditional retail.
- Steam-Vacuum Processing:Controlled-temperature cooking technologies preserve organoleptic properties while achieving clinical-grade sodium and fat reduction targets.
- Front-of-Package Labeling:FDA and Health Canada mandates are accelerating consumer preference shifts toward certified low-sodium products in supermarket aisles.
Market Restraints
- Poultry Fat Specification Volatility:Vertically integrated protein suppliers face margin compression when feed costs spike, destabilizing controlled-fat meal economics.
- Cross-Border Compliance Friction:EFSA and FDA divergent sodium thresholds force dual formulation tracks, raising R&D overhead for multinational suppliers.
- Flavor Masking Limitations:Current potassium chloride substitutes generate metallic aftertastes that limit consumer acceptance in ready-to-eat formats.
Strategic Opportunities
- US School Nutrition Contracts:USDA updated meal pattern requirements create institutional procurement windows for compliant frozen meal suppliers.
- Meal Kit Customization:Direct-to-consumer subscription models enable precise portion control and ingredient traceability for cardiac rehabilitation patients.
- IRA Food Is Medicine Pilots:Federal demonstration programs are funding medically tailored meal integration into Medicaid managed care plans.
Industry Challenges
- Sensory Science Talent Scarcity:Formulation chemists skilled in salt-fat replacement without taste degradation command premium compensation and limited availability.
- Cold-Chain Capex Requirements:Frozen meal distribution demands continuous refrigeration infrastructure investment that strains regional distributor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Salt Low Fat Meals Market |
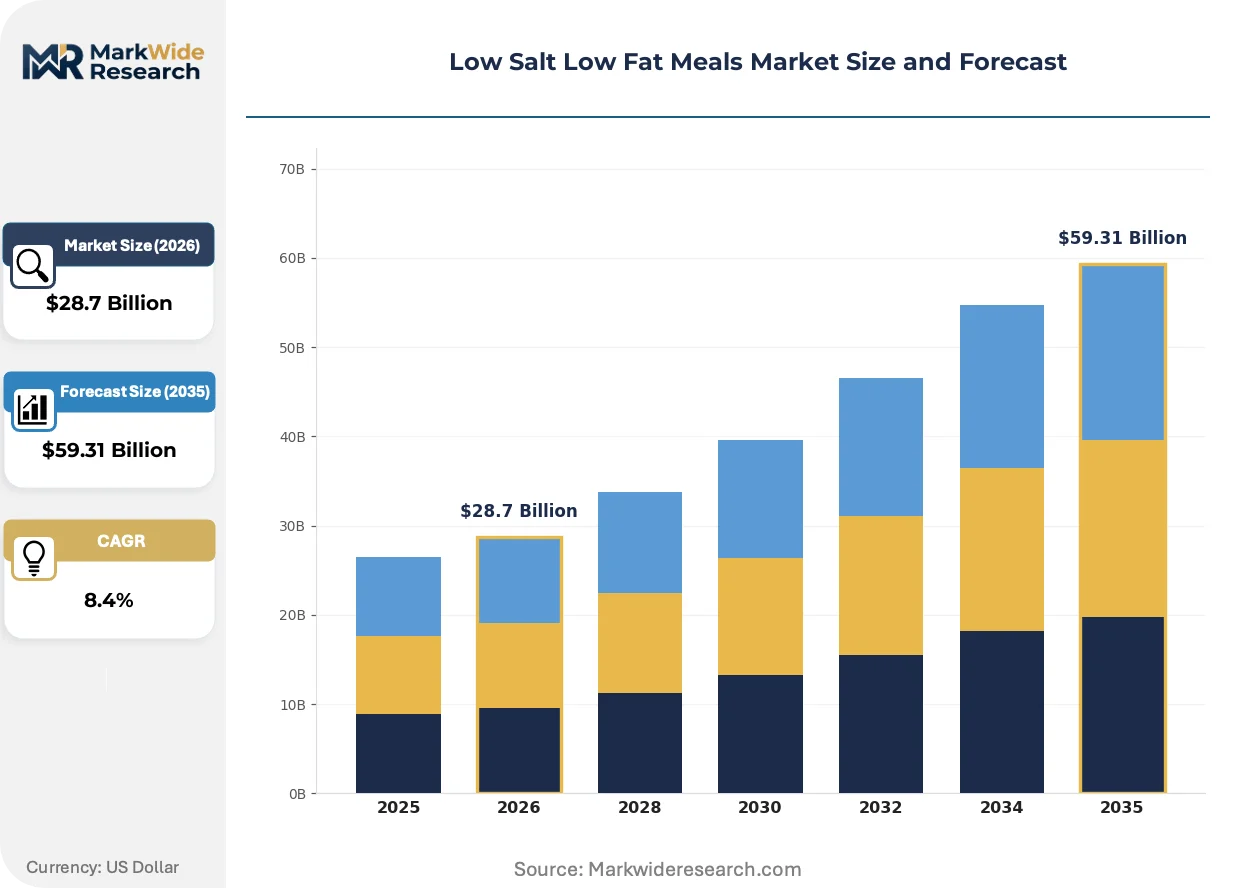
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $59.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Meals, Canned Meals, Ready-to-Eat Meals, Meal Kits Consumer Type: Health-Conscious Consumers, Diabetics, Weight Watchers, Seniors Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Specialty Stores Ingredient Source: Organic Ingredients, Local Produce, Natural Preservatives, Others |
| Companies Covered | General Mills, Nestle, PepsiCo, The Kraft Heinz Company, Hormel Foods Corporation, Maple Leaf Foods, Tyson Foods, Conagra Brands, Kellogg Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Salt Low Fat Meals Market Evolving Landscape
Processing technology convergence and regulatory labeling mandates are restructuring how low-sodium, low-fat meals achieve sensory parity with conventional alternatives while meeting clinical dietary specifications.
High-pressure processing is displacing traditional thermal sterilization in premium ready-to-eat segments. Hospital foodservice directors are adopting HPP-treated meals to extend refrigerated shelf life without sodium-dependent preservation. This technology is displacing frozen formats in short-loop institutional procurement by enabling fresher texture profiles at comparable food safety standards.
EU F-Gas Regulation phase-down schedules are accelerating refrigeration equipment replacement cycles across European cold-chain networks. Meal manufacturers operating in Germany and France face accelerated capital expenditure timelines for compliant cooling systems. Frozen meal exporters to European markets are consolidating distribution partnerships around upgraded logistics providers.
Cardiac rehabilitation centers are consolidating meal procurement through group purchasing organizations rather than individual hospital contracts. This concentration is compressing supplier margins while demanding batch-level nutritional certification documentation. The procurement shift is most visible in US Medicare Advantage network expansions across Florida and Arizona retirement corridors.
Low Salt Low Fat Meals Market Segmentation
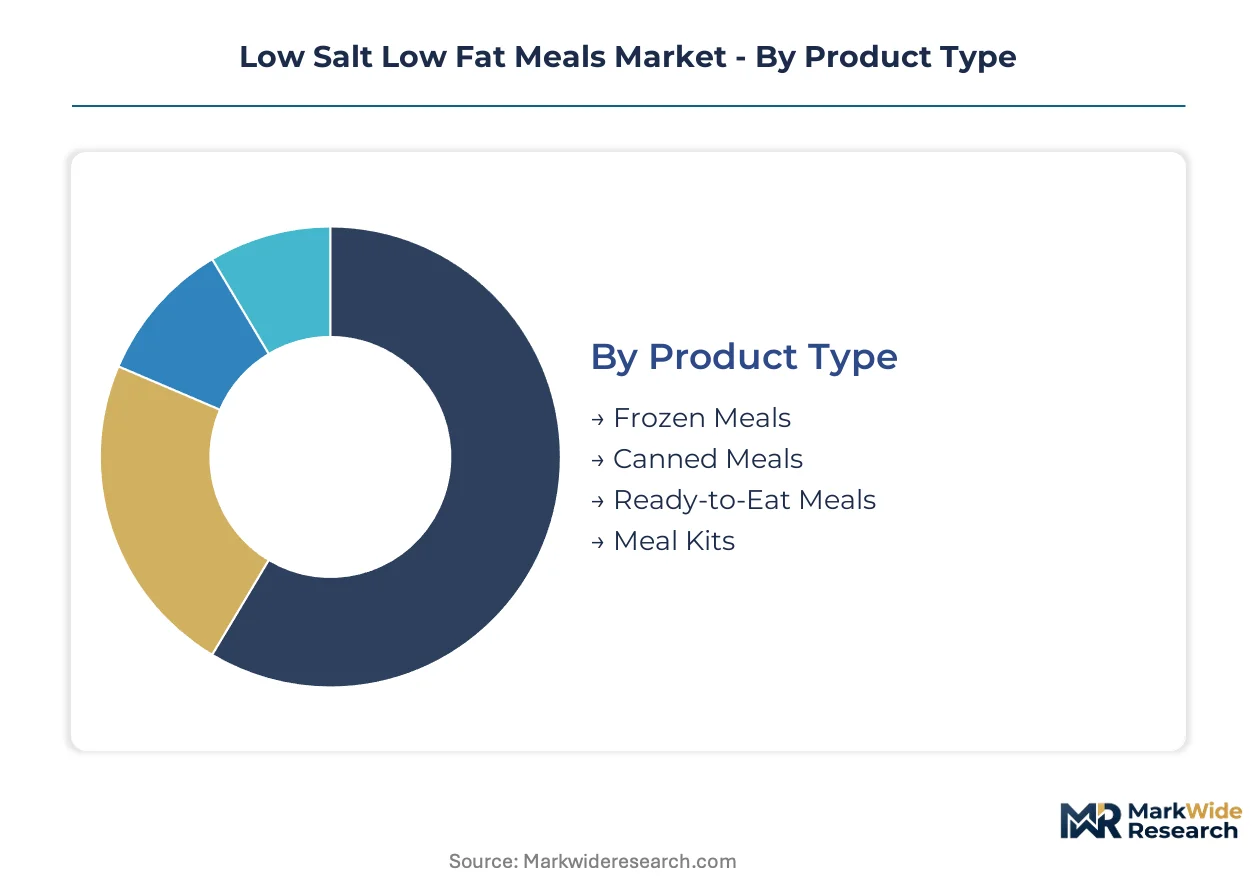
Segmentation in low salt low fat meals reflects divergent preservation technologies and distinct procurement channels serving clinical versus wellness-oriented demand. Each category reveals where formulation investments concentrate and which consumer cohorts command premium pricing power.
Product Type:
Frozen meals capture the deepest margin pools through extended shelf stability and established cold-chain economics that justify premium positioning.
- Frozen Meals:Vacuum-sealed entrees processed through controlled-temperature cooking retain organoleptic properties across 12-18 month shelf timelines. Hospital foodservice directors in Medicare Advantage networks prioritize these formats for cardiac rehabilitation patient discharge planning.
- Ready-to-Eat Meals:Refrigerated products employing high-pressure processing achieve 45-60 day shelf life without sodium-dependent preservation. Demand concentrates in short-loop institutional procurement where Florida and Arizona retirement corridor facilities favor fresher texture profiles.
- Canned Meals:Retort-pouched proteins and vegetables formulated with reduced sodium broths serve emergency preparedness and rural distribution.
- Meal Kits:Component-based subscriptions enable precise portion control for weight management protocols through customizable ingredient sourcing.
Frozen meals hold installed capacity. Ready-to-eat formats are rotating up the share rankings.
Consumer Type:
Volume concentration aligns with reimbursed care pathways rather than discretionary wellness spending.
- Seniors:Medicare Advantage coverage expansion for medically tailored meals creates institutional procurement concentration. Arizona and Florida retirement corridor facilities now mandate batch-level nutritional certification for sodium and saturated fat thresholds.
- Diabetics:Glycemic-controlled formulations with sub-600mg sodium per serving address comorbid hypertension management. Health plan reimbursement pilots through IRA Food Is Medicine demonstrations are accelerating adoption.
- Health-Conscious Consumers:Front-of-package labeling preference shifts drive supermarket aisle placement decisions without clinical reimbursement support.
- Weight Watchers:Portion-calibrated meals with controlled lipid fractions serve commercial diet program partnerships.
Seniors command reimbursement infrastructure. Diabetics are gaining share fastest through comorbid condition targeting.
Distribution Channel:
Channel economics diverge between high-velocity retail and specialized health-focused procurement.
- Supermarkets:Frozen meal shelf-space allocations concentrate in perimeter cases near produce sections. FDA front-of-package labeling mandates are accelerating certified low-sodium product placement algorithms.
- Online Retailers:Direct-to-consumer subscription models enable precise dietary customization for cardiac rehabilitation patients. Cold-chain last-mile capabilities determine regional service viability.
- Health Food Stores:Premium positioning for organic-certified and locally sourced formulations targets discretionary wellness spending.
- Specialty Stores:Medical nutrition retailers serving diabetes and renal disease patient populations with prescription-integrated meal planning.
Supermarkets hold installed capacity. Online retailers are climbing the fastest through subscription model expansion.
Ingredient Source:
Certification tiers create pricing stratification that separates premium positioning from commodity competition.
- Organic Ingredients:USDA-certified produce and proteins command 25-40% price premiums in health food and specialty retail channels. Supply contracting with certified organic poultry operations controls fat content at the sourcing stage.
- Natural Preservatives:Rosemary extract and cultured celery powder replace sodium-based preservation in clean-label formulations. FDA sodium reduction guidelines are accelerating reformulation investment.
- Local Produce:Regional sourcing contracts reduce transportation emissions for sustainability-positioned meal kit providers.
- Others:Conventional ingredient sourcing serves price-sensitive retail tiers without certification premiums.
Organic ingredients hold installed capacity. Natural preservatives are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of low-sodium prepared meals concentrate in North American and European corridors where cold-chain infrastructure supports extended distribution. Import demand is accelerating in Asian markets where clinical nutrition protocols are adopting Western meal formats.
United States
Medicare Advantage reimbursement expansion and IRA Food Is Medicine pilots are institutionalizing medically tailored meal procurement. FDA sodium reduction targets and front-of-package labeling mandates are compressing allowable salt thresholds in prepared foods. Florida and Arizona retirement corridor facilities now mandate batch-level nutritional certification for cardiac rehabilitation patient discharge planning.
Germany
EU F-Gas Regulation phase-down schedules are accelerating refrigeration equipment replacement across cold-chain networks. EFSA sodium thresholds diverge from FDA standards, forcing dual formulation tracks for exporters. Bavaria-based meal manufacturers are consolidating distribution partnerships around upgraded logistics providers serving hospital foodservice directors.
Japan
Aging demographics and hypertension prevalence are expanding institutional procurement of clinically appropriate meal formats. METI guidelines on processed food sodium content are tightening faster than regional peers. Kanto region facilities around Tokyo are adopting high-pressure processing to achieve fresher texture profiles at comparable food safety standards.
United Kingdom
NHS long-term plan commitments to cardiovascular disease prevention are embedding low-sodium meal protocols in hospital discharge planning. Health Canada parallel frameworks create compliance complexity for suppliers operating across North American and European jurisdictions. London and Southeast England procurement clusters are consolidating through group purchasing organizations rather than individual hospital contracts.
Canada
Health Canada front-of-package labeling mandates are accelerating consumer preference shifts toward certified low-sodium products in supermarket aisles. Cross-border compliance friction with FDA divergent sodium thresholds raises R&D overhead for multinational suppliers. Ontario and Quebec health authorities are piloting medically tailored meal integration into provincial chronic disease management programs.
Low Salt Low Fat Meals Market Competitive Landscape
Concentration sits with diversified food conglomerates possessing frozen distribution infrastructure and vertically integrated protein supply chains. Three to four multinational holding companies control shelf-space allocations in health-focused retail channels. Strategic archetypes include heritage brand reformulators, private-label contract manufacturers, and direct-to-consumer meal kit specialists. Competitive moves center on M&A to acquire clean-label formulation capabilities and capacity expansion in high-pressure processing equipment.
Among North American diversified food manufacturers, General Mills, Nestle, and Tyson Foods occupy distinct positioning within the competitive structure. General Mills exemplifies the heritage brand reformulator archetype through portfolio assets adapted for reduced sodium profiles. Nestle anchors the multinational nutrition conglomerate tier with extensive frozen distribution networks. Tyson Foods represents protein-integrated meal manufacturing through captive poultry supply chains that control fat content at the sourcing stage.
| Leading Market Players |
|---|
| General Mills |
| Nestle |
| PepsiCo |
| The Kraft Heinz Company |
| Hormel Foods Corporation |
| Maple Leaf Foods |
| Tyson Foods |
| Conagra Brands |
| Kellogg Company |
| Others |
Value Network & Pricing Analysis
FDA sodium reduction targets and front-of-package labeling mandates gate both supplier qualification and price differentiation simultaneously. Certification tiers separate Medicare Advantage-compliant meal producers from conventional frozen food suppliers, with batch-level nutritional documentation commanding substantial premiums in institutional procurement channels.
Pricing Analysis
Hospital foodservice directors anchor pricing structures through multi-year procurement contracts tied to cardiac rehabilitation discharge protocols. Three-tier pricing structure across premium certified-organic, standard clinically-compliant, and economy conventional tiers reflects USDA organic certification and FDA sodium threshold compliance as primary differentiation drivers. Pricing pressure stems from Medicare Advantage reimbursement rate compression in Florida and Arizona retirement corridors. Health-conscious retail consumers exhibit highest price sensitivity, while institutional buyers prioritize certification documentation over unit cost.
Supply Chain Analysis
Container availability constraints on trans-Pacific trade lanes strain inbound logistics for organic produce sourcing. Protein supply concentrates in vertically integrated US poultry operations and Canadian beef processing facilities, with sodium-reduced broth formulations drawing from Midwest grain suppliers. Single-source vulnerability sits with high-pressure processing equipment manufacturers in Germany and Japan. Distribution runs through regional cold-chain consolidators serving Medicare Advantage network facilities before reaching supermarket perimeter cases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemists skilled in salt-fat replacement without taste degradation represent the critical capability gap constraining competitive expansion. Procurement concentration among group purchasing organizations amplifies supplier qualification barriers beyond capital requirements alone.
For Market Incumbents: Secure exclusive contracts with certified organic poultry operations to control fat content at the sourcing stage against emerging private-label contract manufacturers. Invest in high-pressure processing capacity additions in Arizona and Florida to capture Medicare Advantage network expansions before reimbursement rates compress further. Lock in sensory science talent through compensation premiums that match clinical nutrition consultancy rates. For New Entrants and Emerging Players: Direct-to-consumer subscription customization represents the service-layer gap where incumbents under-serve cardiac rehabilitation patients requiring precise portion calibration. Meal kit personalization for diabetic comorbid management offers the most penetrable white-space target, with IRA Food Is Medicine demonstration pilots providing reimbursement infrastructure. Pursue white-label partnerships with regional health plans rather than competing for supermarket shelf-space against entrenched frozen distribution networks. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across high-pressure processing equipment and EU F-Gas Regulation-compliant refrigeration infrastructure. Long-term viability over the coming decade rests on acquiring clean-label formulation capabilities rather than commodity frozen capacity. Target acquisition archetype: mid-cap meal kit specialists possessing direct-to-consumer subscription infrastructure and USDA organic certification relationships. Watch FDA front-of-package labeling mandate implementation timelines as the primary inflection indicator for consumer preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Capacity Expansion | HPP equipment deployment extends refrigerated shelf life for Medicare Advantage discharge planning without sodium-dependent preservation. |
| USDA Organic Certification Investment | Organic poultry supply contracts control fat content at sourcing while commanding 25-40% price premiums in health-focused retail. |
| Direct-to-Consumer Subscription Launch | Meal kit customization captures cardiac rehabilitation patients requiring precise sodium and lipid fraction control outside institutional channels. |
| Group Purchasing Organization Partnership | GPO consolidation in Florida and Arizona retirement corridors compresses margins but locks in volume commitments for compliant suppliers. |
| Sensory Science Talent Acquisition | Reformulation chemists skilled in potassium chloride substitution without metallic aftertaste enable FDA sodium target compliance. |
Research Methodology
Operator-level perspectives from hospital foodservice directors, Medicare Advantage plan procurement officers, cardiac rehabilitation clinicians, and frozen distribution logistics managers anchored the qualitative base. Primary interview data combined with secondary validation from FDA sodium reduction guidance documents, USDA school nutrition standards, Health Canada front-of-package labeling mandates, and CMS Medicare Advantage reimbursement data. Bottom-up volume modeling across product type, consumer segment, and distribution channel dimensions triangulated against top-down market sizing from cold-chain logistics capacity assessments.
Sensitivity analysis tested forecast outputs against variable Medicare Advantage coverage expansion rates and EU F-Gas Regulation compliance cost trajectories. Segmentation dimensions modeled include preservation technology, clinical versus wellness-oriented demand archetype, procurement channel concentration, and regional regulatory framework clustering. CAGRs derived from installed capacity growth in high-pressure processing equipment and Medicare Advantage network penetration patterns across retirement corridor geographies. Industry-specific inputs incorporated batch-level nutritional certification adoption timelines and potassium chloride substitute formulation success rates.
Underlying assumptions cover sustained Medicare Advantage reimbursement for medically tailored meals, stable cold-chain infrastructure investment, and gradual FDA sodium threshold enforcement, with deviation risk concentrated in IRA Food Is Medicine pilot program funding continuity and feed cost volatility for vertically integrated poultry suppliers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Asia-Pacific Alcohol-Infused Ice Cream Market
Specialty Foods
Aloe Vera Gel Market
Specialty Foods
Aloe Butter Market
Specialty Foods
Jams, Jellies & Preserves Market
Specialty Foods
Liquid Mushroom Market
Specialty Foods
Halal Foods Market
Specialty Foods
Human Grade Pet Food Market
Specialty Foods
Europe Halal Food and Beverage Market
Specialty Foods
Cultures Market
Specialty Foods
Low Calorie Vegetable Dip Market
Specialty Foods
Tahini Market
Specialty Foods
Healthy Low-Fat Desserts Market
Specialty Foods
Yeast-Based Spreads Market
Specialty Foods
Cannabis-Infused Burger Market
Specialty Foods
Asia Pacific Pet Milk Replacers Market
Specialty Foods
United States Tofu Market