
 Soft Tofu Market | 2026-2036
Soft Tofu Market Size, Share, and Industry Trends Forecast 2026-2036
Soft Tofu Market Insights
The gap between premium artisan soft tofu and mass-market commodity blocks is shifting from texture claims to provenance transparency and coagulant chemistry. House Foods Group leverages its integrated soy supply chain to sustain consistent quality across North American retail channels. Pulmuone anchors its position through Korean domestic dominance in fresh-packaged formats, while Hodo Foods differentiates via organic certification and chef-centric distribution in the United States.
Soft tofu denotes a high-moisture, minimally pressed soybean curd with protein content typically ranging from 5% to 8% and a silken-to-firm texture gradient depending on coagulant type; it serves as a versatile protein substrate across hot-pot preparations, blended applications, and plant-based meat analogs. Silken tofu occupies the fastest-growing margin pool as dessert and beverage formulations expand, while regular soft tofu dominates volume through household penetration in East Asian markets. Vacuum-sealed packs are displacing bulk bags in foodservice channels where shelf-life extension reduces spoilage costs.
The FDA oversees soy protein labeling and GRAS status determinations that govern product claims, while USDA organic certification shapes premium pricing tiers; South Korea's Ministry of Food and Drug Safety enforces stringent fresh tofu microbial standards that filter smaller producers from modern retail. Stakeholders must monitor coagulant innovation—magnesium chloride versus glucono-delta-lactone—as clean-label preferences reshape formulation decisions across export markets.
Market Dynamics
The FDA's updated plant-based protein labeling guidance is forcing manufacturers to restructure claims and shelf positioning, while South Korea's MFDS microbial standards filter smaller producers from modern retail channels. Coagulant chemistry transparency now separates premium positioning from commodity blocks.
Growth Catalysts
- Clean-label coagulant innovation:Magnesium chloride and glucono-delta-lactone formulations respond to consumer demand for ingredient simplicity. Manufacturers reformulate to highlight natural coagulant chemistry on packaging.
- South Korean retail modernization:Sundubu-jjigae chain expansion and fresh-packaged formats in Seoul and Busan drive premium soft tofu consumption. Modern retail penetration filters toward higher-margin products.
- USDA organic certification tiering:Certified organic soft tofu commands shelf placement advantages in US natural grocery channels. Premium pricing tiers solidify around third-party verification.
Market Restraints
- Soybean input cost volatility:Weather-driven commodity price swings compress margins for non-integrated processors. Smaller manufacturers lack captive supply buffers.
- Fresh tofu spoilage economics:Seven-day refrigerated shelf life limits distribution radius from production facilities. Vacuum-sealed packaging adoption requires capital retooling.
- MFDS microbial compliance barriers:Stringent coliform and aerobic plate count standards exclude artisan producers from South Korean modern retail. Regulatory friction concentrates supply among integrated players.
Strategic Opportunities
- Silken tofu dessert applications:Beverage and confectionery formulations in Japan and Taiwan expand addressable market beyond savory uses. Texture versatility opens new end-use verticals.
- Chef-centric foodservice distribution:Direct supply relationships with restaurant groups bypass conventional retail slotting fees. Hodo Foods' organic positioning demonstrates model viability in the United States.
- Integrated soy supply chain control:Backward integration into soybean sourcing and coagulant production insulates margin pressure. House Foods Group's captive supply model offers template for quality consistency.
Industry Challenges
- Coagulant chemistry expertise scarcity:Formulation specialists who balance texture, yield, and clean-label positioning command premium compensation. Technical talent gaps constrain R&D velocity.
- Multi-jurisdiction label compliance:Divergent FDA, USDA, and MFDS claim requirements force SKU proliferation. Packaging redesign cycles compress operational bandwidth.
- Cold-chain infrastructure capex:Vacuum-sealed line installation and refrigerated logistics expansion demand capital deployment. Smaller producers face financing constraints for equipment upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soft Tofu Market |
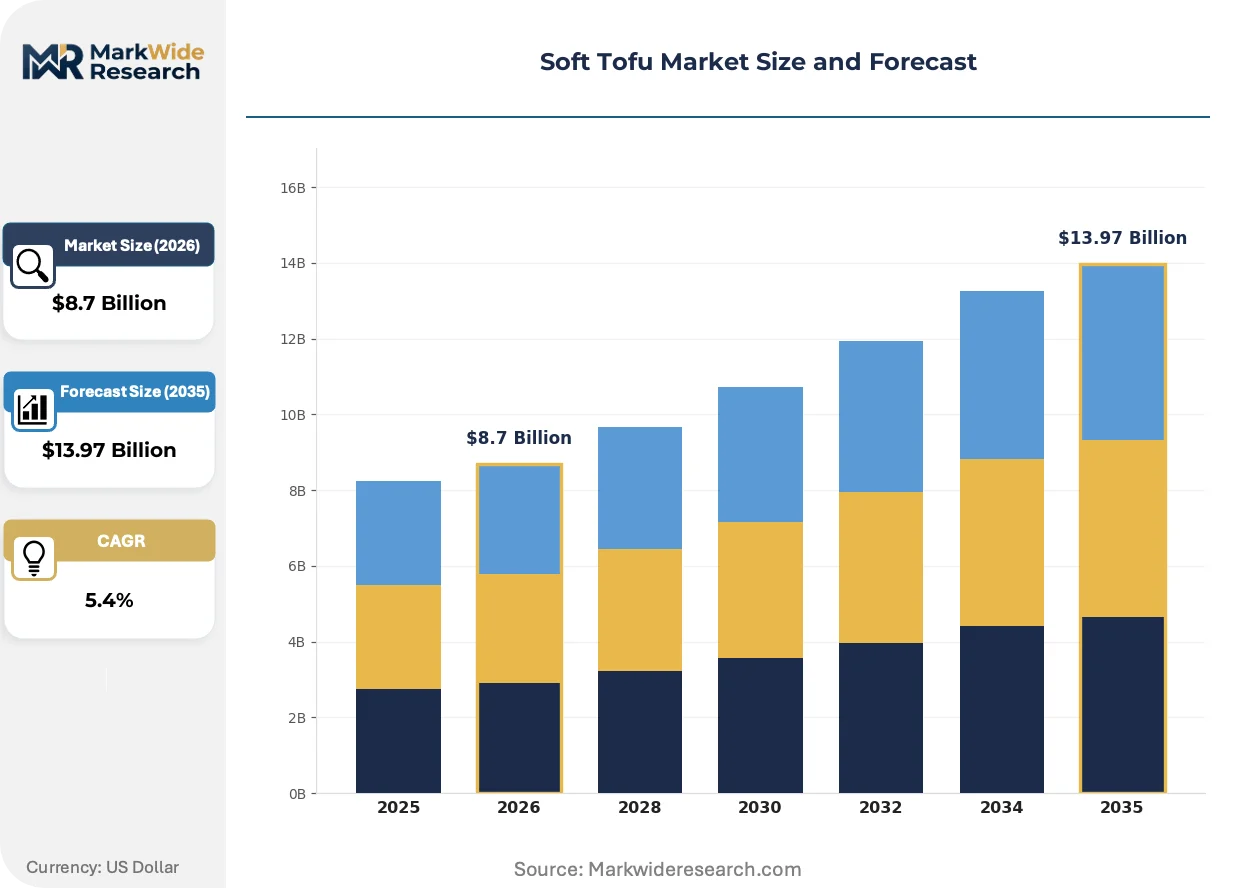
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Soft Tofu, Silken Tofu, Regular Soft Tofu, Flavored Soft Tofu Packaging Type: Plastic Containers, Vacuum-Sealed Packs, Bulk Bags, Cartons Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Wholesale Distributors End User: Households, Restaurants, Food Manufacturers, Meal Kit Providers |
| Companies Covered | House Foods Group, Pulmuone, Hodo Foods, Kikkoman Corporation, VITASOY, MoriNu, White Wave Foods, CJ CheilJedang, Nasoya, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soft Tofu Market Trends and Innovations
Texture-engineering breakthroughs and regulatory claim restructuring are compressing product development cycles. Manufacturers now compete on provenance transparency and coagulant specificity rather than moisture content alone.
High-pressure processing technology is unifying shelf-life extension with clean-label positioning. Premium soft tofu producers in South Korea and Japan adopt HPP to eliminate preservatives while maintaining silken texture. This convergence is compressing the freshness-versus-shelf-life tradeoff that previously segmented retail and foodservice formats.
REACH-compliant packaging material standards in the European Union are forcing migration from conventional plastics to bio-based films. Soft tofu exporters to Germany and France must validate barrier properties for oxygen and moisture transmission. The transition most affects vacuum-sealed formats where film integrity determines spoilage rates.
Plant-forward menu development at North American restaurant groups is rotating procurement toward chef-specific block sizes and texture specifications. Direct supplier relationships are replacing broadline distributor purchasing for premium SKUs. This pattern concentrates in California and New York metro areas where Korean and Japanese cuisine penetration is deepest.
Soft Tofu Market Segmentation
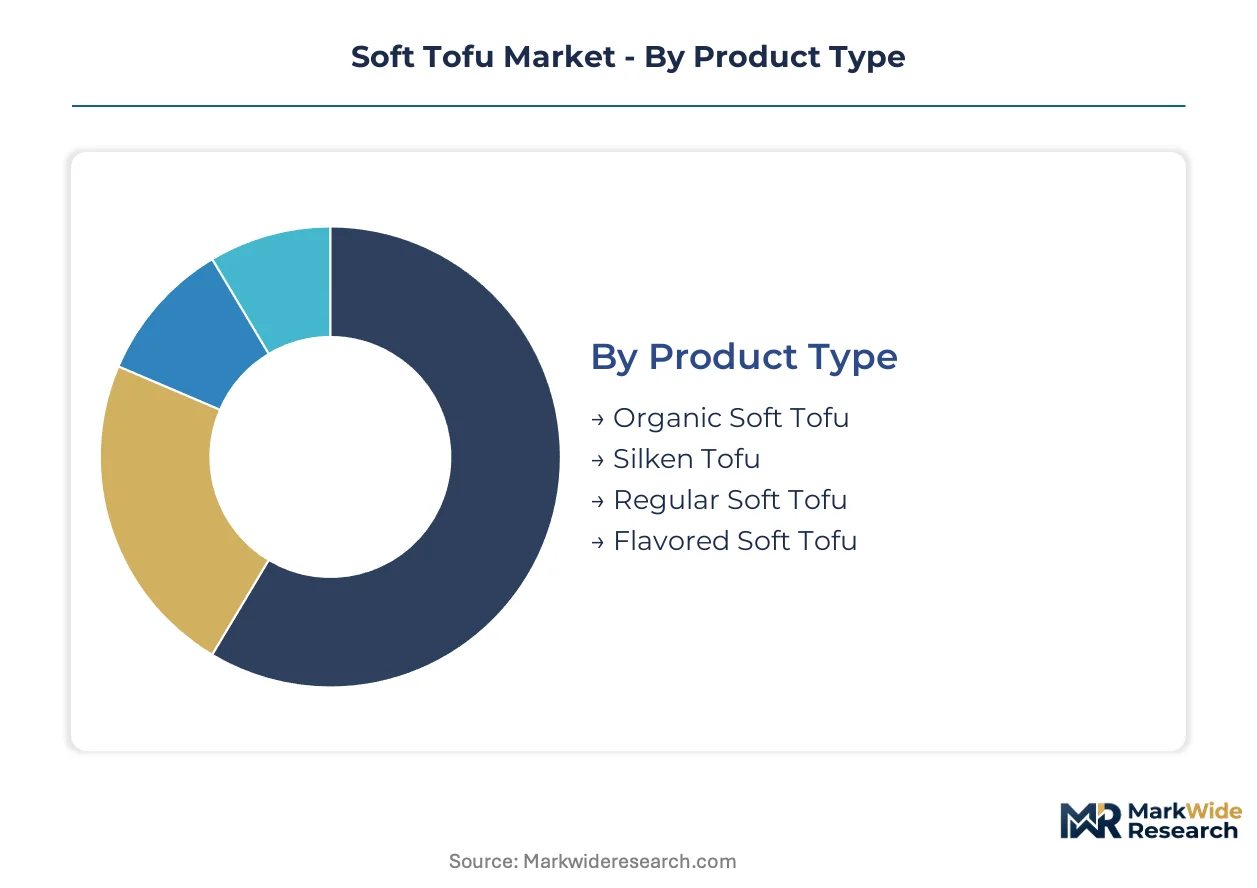
Soft tofu segmentation reveals how certification requirements, shelf-life engineering, and channel economics partition the market into distinct competitive arenas. Each dimension carries specific regulatory burdens that shape margin structures and defendability.
Product Type:
Organic Soft Tofu demands USDA organic certification and third-party verification for premium shelf placement in US natural grocery channels. Silken Tofu and Regular Soft Tofu operate under FDA GRAS determinations with varying protein content claims. Flavored Soft Tofu faces additional state-level labeling scrutiny for added ingredients.
- Organic Soft Tofu:Soybeans sourced from certified organic farms with full traceability documentation. Demand concentrates in California and New York metro areas where Korean and Japanese cuisine penetration drives chef-specific procurement at 15-20% price premiums over conventional.
- Silken Tofu:Highest moisture content (85-90%) with delicate curd structure requiring specialized coagulant chemistry. Dessert and beverage formulations in Japan and Taiwan expand addressable market beyond traditional savory applications, with HPP-treated variants gaining traction for clean-label positioning.
- Regular Soft Tofu:Household staple across East Asian markets with 5-8% protein content and firmer texture than silken variants.
- Flavored Soft Tofu:Pre-seasoned blocks incorporating herbs, spices, or vegetable purees for convenience-oriented consumers.
Regular Soft Tofu sits at the top of the volume ranking, with Silken Tofu climbing the fastest.
Packaging Type:
Packaging economics pivot on shelf-life extension versus capital intensity, with vacuum-sealed formats requiring the steepest equipment investment but delivering the widest distribution radius.
- Vacuum-Sealed Packs:Oxygen barrier films extend refrigerated shelf life to 21-30 days, enabling cross-state distribution from single production facilities. South Korean manufacturers lead HPP integration to eliminate preservatives while maintaining texture integrity.
- Plastic Containers:Standard retail format with 7-14 day shelf life, dominating household penetration in urban Japanese and Korean markets where purchase frequency remains high.
- Bulk Bags:Foodservice format for high-volume restaurant and manufacturer accounts with same-day or next-day delivery requirements.
- Cartons:Aseptic packaging for ambient distribution in emerging markets with limited cold-chain infrastructure.
Plastic Containers capture the largest installed base, though Vacuum-Sealed Packs are gaining share fastest as foodservice operators prioritize spoilage reduction.
Distribution Channel:
Channel selection determines slotting fee exposure, margin retention, and the granularity of consumer data available to manufacturers.
- Supermarkets:Dominant volume channel in South Korea and Japan with fresh-packaged formats positioned adjacent to meat and produce departments. Modern retail penetration filters toward higher-margin SKUs as chains consolidate supplier bases.
- Online Retailers:Fastest-expanding channel in US coastal markets, enabling direct-to-consumer subscription models for organic and specialty variants with temperature-controlled logistics.
- Specialty Stores:Korean and Japanese grocers in Los Angeles, New York, and Toronto with curated selection and turnover velocity advantages for artisan producers.
- Wholesale Distributors:Broadline and specialty foodservice networks serving restaurant groups and institutional accounts with chef-specific block sizes.
Supermarkets maintain volume leadership, with Online Retailers expanding most quickly in North American premium segments.
End User:
End-use segmentation maps directly to formulation specificity, with food manufacturers demanding the tightest texture and protein consistency specifications.
- Restaurants:Korean sundubu-jjigae chains in Seoul and Busan drive premium fresh tofu consumption with daily delivery requirements and custom coagulant preferences.
- Food Manufacturers:Plant-based meat analog producers require consistent protein content and water-holding capacity for binding applications.
- Households:Retail purchasers across East Asian markets with established preparation traditions and brand loyalty patterns.
- Meal Kit Providers:Emerging demand source in US and Canadian markets seeking pre-portioned, extended-shelf-life formats.
Households anchor current volume, while Food Manufacturers present the steepest expansion trajectory as plant-based protein demand accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized coagulant chemists and food safety auditors cluster in South Korea and Japan, anchoring premium soft tofu production expertise. These talent concentrations shape regional competitive advantages and regulatory compliance capabilities.
United States
Plant-forward restaurant menus in California and New York metro areas expand soft tofu procurement for Korean and Japanese cuisine applications. The FDA's updated plant-based protein labeling guidance forces manufacturers to restructure claims and shelf positioning. Chef-centric distribution networks in Los Angeles and New York bypass conventional retail slotting fees for premium organic variants.
South Korea
Sundubu-jjigae chain expansion in Seoul and Busan drives premium fresh-packaged soft tofu consumption with daily delivery requirements. The MFDS enforces stringent coliform and aerobic plate count standards that filter smaller producers from modern retail channels. High-pressure processing adoption in Seoul production facilities eliminates preservatives while maintaining silken texture integrity.
Japan
Dessert and beverage formulations in Tokyo and Osaka expand silken tofu applications beyond traditional savory uses. METI standards govern food manufacturing equipment specifications and hygiene protocols. Artisan producers in Kyoto maintain heritage coagulant methods while industrial clusters in Nagoya scale vacuum-sealed formats for export markets.
China
Household penetration in Shanghai and Beijing sustains volume demand for regular soft tofu with established preparation traditions. SAMR oversees food safety national standards and production licensing requirements. Yangtze River Delta manufacturing bases supply both domestic retail and foodservice channels with integrated soy processing capabilities.
Soft Tofu Market Competitive Landscape
Top-tier vendors anchor integrated supply chain control, while mid-tier specialists compete on organic certification and chef-centric distribution. The market exhibits moderate concentration with clear tiering between captive soy processors and third-party dependent manufacturers. Three archetypes dominate: backward-integrated conglomerates with captive soybean sourcing, organic-certified specialists targeting natural grocery channels, and regional fresh-format leaders with localized distribution networks. Capacity expansion and coagulant chemistry transparency represent the dominant competitive moves reshaping positioning.
Within the integrated supply tier, House Foods Group and Pulmuone exemplify archetypes of upstream control and regional dominance respectively. Hodo Foods occupies a position representing the organic-certified specialist model in United States distribution. These three entities anchor the competitive spectrum from mass-market scale to premium niche positioning without overlapping strategic territories.
| Leading Market Players |
|---|
| House Foods Group |
| Pulmuone |
| Hodo Foods |
| Kikkoman Corporation |
| VITASOY |
| MoriNu |
| White Wave Foods |
| CJ CheilJedang |
| Nasoya |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between USDA organic and conventional soft tofu generates divergent margin architectures across North American retail channels while simultaneously filtering supplier eligibility through traceability documentation requirements. This tier divergence manifests in procurement economics: premium organic SKUs command shelf placement advantages in natural grocery channels, whereas commodity blocks compete on input cost efficiency and refrigerated logistics proximity.
Pricing Analysis
Packaging-service bundling separates vacuum-sealed extended-shelf-life formats from basic plastic container offerings. Price differentiation hinges on organic certification tier and coagulant chemistry transparency, with magnesium chloride-labeled products sustaining premiums over glucono-delta-lactone alternatives. Pricing pressure intensifies in conventional segments as soybean commodity volatility compresses processor margins. Food manufacturers exhibit highest price sensitivity due to volume procurement scale, while Korean sundubu-jjigae chains absorb premiums for custom coagulant specifications.
Supply Chain Analysis
Single-source vulnerability sits with South Korean domestic production for premium fresh-packaged formats serving Seoul and Busan restaurant chains. Soybean sourcing concentrates in the United States, Brazil, and Argentina, while coagulant production rests on Chinese magnesium chloride and Japanese glucono-delta-lactone supply. Tariff exposure on imported coagulants threatens margin stability for non-integrated processors. Distribution runs through refrigerated direct-store-delivery networks in East Asian markets and broadline foodservice distributors in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The soft tofu market represents a late-cycle quality story where provenance transparency and coagulant specificity now outweigh moisture content as purchase determinants. Demand is concentrating toward premium specifications as South Korean retail modernization and North American plant-forward menu development elevate chef-grade procurement standards.
For Market Incumbents: Hedge against commodity margin compression through backward integration into organic soybean sourcing and captive coagulant production. Secure HPP equipment capacity ahead of clean-label shelf-life extension demand. Defend against artisan competitor encroachment by locking exclusive supply agreements with sundubu-jjigae chain expansion networks. For New Entrants and Emerging Players: Launch via chef-centric foodservice distribution bypassing conventional retail slotting fees in California and New York metro areas. Target silken tofu dessert applications in Japanese and Taiwanese beverage formulations as the most penetrable white-space vertical. Pursue organic certification as the primary go-to-market credential for natural grocery channel access. For Investors and Strategic Acquirers: Consolidation pressure builds where MFDS microbial compliance barriers exclude smaller producers from South Korean modern retail, concentrating supply among integrated players with quality laboratory infrastructure. Long-term viability favors processors with captive soy supply chains and multi-jurisdiction label compliance capabilities. Monitor coagulant chemistry specialist compensation inflation as the inflection signal for R&D velocity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Adoption | HPP integration eliminates preservatives while maintaining silken texture integrity for clean-label positioning. |
| Organic Certification Investment | USDA organic tiering commands 15-20% price premiums in California and New York natural grocery channels. |
| Chef-Centric Distribution Partnership | Direct supply relationships with Korean restaurant groups bypass broadline distributor slotting fees. |
| Coagulant Chemistry Transparency | Magnesium chloride labeling responds to consumer demand for ingredient simplicity in premium segments. |
| Vacuum-Sealed Packaging Retooling | Oxygen barrier films extend distribution radius from production facilities, reducing spoilage economics constraints. |
Research Methodology
Multiple input streams — executive interviews with tofu processing plant managers, procurement leads at North American restaurant groups, and South Korean retail category buyers — were reconciled against trade data, MFDS compliance filings, and USDA organic certification records. Primary fieldwork captured coagulant formulation practices and shelf-life engineering decisions. Secondary validation drew from customs records, FDA GRAS determinations, and refrigerated logistics operator disclosures. Bottom-up facility capacity estimates and top-down consumption trend analysis were triangulated for convergence.
Historical volume trajectories were cross-referenced against panel input from supply chain executives across the projection horizon. The analytical framework modeled segmentation across product type, packaging format, distribution channel, and end-use application. CAGRs were derived from trend extrapolation moderated by regulatory compliance cost assumptions. Forecast inputs included soybean commodity price volatility scenarios and HPP equipment adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MFDS regulatory tightening or sustained drought conditions in major soybean producing regions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Konjac Noodles Market
Specialty Foods
Morocco Couscous Market
Specialty Foods
Human Grade Pet Food Market
Specialty Foods
Foie Gras Market
Specialty Foods
Wet Grain-Free Pet Food Market
Specialty Foods
Germany Barbeque Grill Market
Specialty Foods
Dog Food Toppers Market
Specialty Foods
Grain Free Dog Food Market
Specialty Foods
Global Pine Pollen Market
Specialty Foods
Thai Cuisine Market
Specialty Foods
Edible Cutlery Market
Specialty Foods
Organic Skin Care Market
Specialty Foods
Global Sauerkrauts Market
Specialty Foods
Low Calorie Veggie Dip Market
Specialty Foods
Coconut Butter Market
Specialty Foods
Fermented Black Beans Market