
 Saw Palmetto Market | 2026-2036
Saw Palmetto Market Size, Share, and Industry Trends Forecast 2026-2036
Saw Palmetto Market Analytics
Standardized extract specifications above eighty-five percent fatty acid content is reorganizing procurement priorities across the saw palmetto supply chain. Euromed leverages its vertical integration from Florida berry harvesting to European extraction facilities, sustaining consistent phytochemical profiles for pharmaceutical-grade buyers. Sabinsa competes through its patented bioavailability enhancement technologies, while Valensa International anchors its position with USP-verified potency certifications that command premium positioning in practitioner channels.
Saw palmetto comprises lipophilic extracts derived from Serenoa repens berries, standardized to eighty-five to ninety-five percent total fatty acids including lauric, oleic, and linoleic acids via supercritical CO2 or ethanol extraction for therapeutic applications in benign prostatic hyperplasia management and androgenic alopecia intervention. Liquid extract formats dominate institutional procurement for compounding pharmacies due to dosing flexibility, whereas softgel capsules capture the fastest growth in direct-to-consumer channels where convenience drives repeat purchase behavior. Nutritional supplements as an application category concentrates the deepest margin pools, with hair loss treatment emerging as the highest-velocity subsegment among health enthusiasts seeking natural alternatives to synthetic 5-alpha-reductase inhibitors.
FDA dietary supplement cGMP enforcement and EFSA novel food assessments jointly elevate barriers for unstandardized raw material entrants, while USP monograph compliance increasingly functions as a de facto market access requirement for North American distribution. The EU Nutrition and Health Claims Regulation constrains permissible prostate health messaging, redirecting formulation investment toward substantiated structural claims. Stakeholders must monitor evolving pharmacovigilance expectations for botanicals as regulators scrutinize drug-herb interaction profiles more intensively.
Market Dynamics
FDA cGMP enforcement and EFSA novel food assessments are compressing raw material qualification timelines, forcing extractors to consolidate upstream berry sourcing or exit North American distribution entirely.
Growth Catalysts
- USP Monograph Compliance:North American practitioner channels now require verified potency documentation, filtering out unstandardized suppliers and concentrating volume among certified processors.
- Supercritical CO2 Extraction:This solvent-free technology preserves heat-sensitive fatty acid profiles, enabling pharmaceutical-grade applications that ethanol methods cannot satisfy.
- Germany:EMA herbal monograph recognition for Serenoa repens drives reimbursement eligibility across statutory health insurance, expanding institutional procurement volumes.
Market Restraints
- Wild Berry Supply Concentration:Florida and Georgia harvests dominate raw material availability, exposing processors to climate-induced yield volatility and land development pressure.
- EFSA Health Claims Regulation:Prohibition of disease-risk reduction language for prostate conditions forces reformulation toward unsubstantiated structural claims with weaker consumer pull-through.
- Synthetic 5-Alpha-Reductase Inhibitors:Finasteride and dutasteride maintain physician preference for diagnosed BPH cases, capping saw palmetto penetration in reimbursed therapeutic settings.
Strategic Opportunities
- Japan:PMDA guidance on mixed herbal preparations creates a pathway for saw palmetto inclusion in Kampo-style formulations targeting middle-aged male wellness.
- Direct-to-Consumer Subscription Models:Softgel auto-delivery programs bypass retail margin stacking while capturing recurring revenue and consumption data for personalization.
- Androgenic Alopecia Positioning:Hair loss treatment applications face lighter regulatory scrutiny than prostate claims, permitting bolder marketing in influencer-driven channels.
Industry Challenges
- Phytochemical Standardization Expertise:Analytical chemists capable of validating fatty acid ratios via GC-MS command premium compensation, constraining mid-tier extractor expansion.
- Multi-Jurisdiction Label Harmonization:Divergent FDA, EFSA, and TGA disclosure requirements force SKU proliferation and inventory fragmentation for international suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saw Palmetto Market |
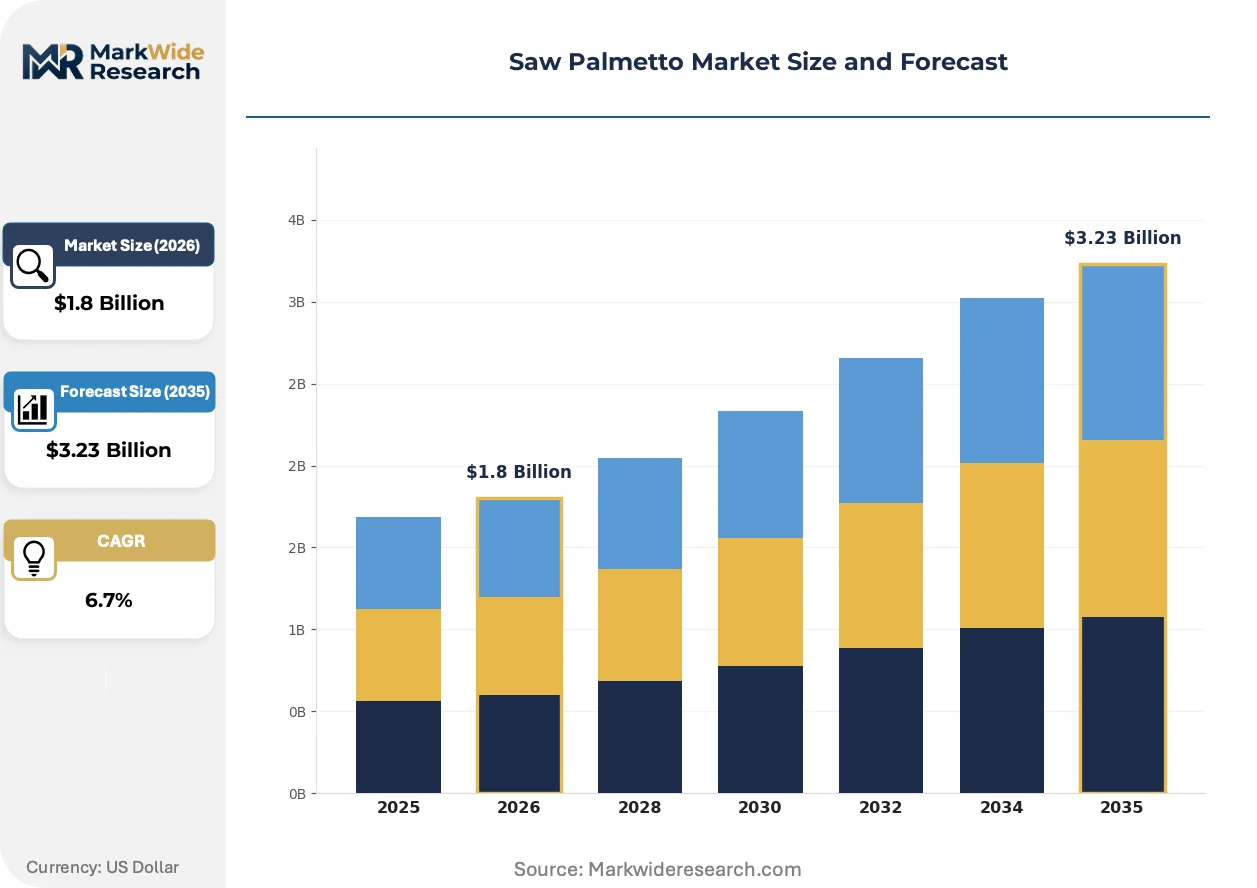
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Extract, Capsule, Powder, Softgel End User: Retail Consumers, Health Enthusiasts, Healthcare Professionals, Wellness Centers Application: Hair Loss Treatment, Prostate Health, Nutritional Supplements, Dietary Support Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Supermarkets |
| Companies Covered | Euromed, Bio-Botanica, Valensa International, Sabinsa, Maypro, Martin Bauer, Naturex, Nature's Bounty Co., Indena, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saw Palmetto Market Evolving Landscape
Extract technology and distribution architecture are diverging sharply between pharmaceutical-grade and wellness-grade supply chains, creating distinct capability requirements that few suppliers can bridge simultaneously.
Supercritical CO2 extraction is bifurcating the supply base into pharmaceutical-compliant and commodity wellness tiers. Compounding pharmacies and clinical trial sponsors specify CO2-derived extracts for batch-to-batch consistency. Ethanol processors retain cost-sensitive softgel contracts but face margin compression as USP verification becomes table stakes for practitioner channel access.
EFSA novel food assessments for concentrated berry extracts are extending qualification timelines beyond eighteen months. This regulatory friction favors incumbent extractors with established safety dossiers. New entrants pivot toward whole-berry powder positioning to bypass novel food classification, accepting lower potency margins for faster market access.
Practitioner channel consolidation is compressing distributor intermediation. Integrated health systems and functional medicine networks negotiate direct supply agreements with USP-verified extractors, disintermediating traditional supplement wholesalers. This pattern concentrates most visibly in United States metropolitan clusters where cash-pay wellness practices aggregate sufficient volume to justify dedicated procurement infrastructure.
Saw Palmetto Market Segmentation
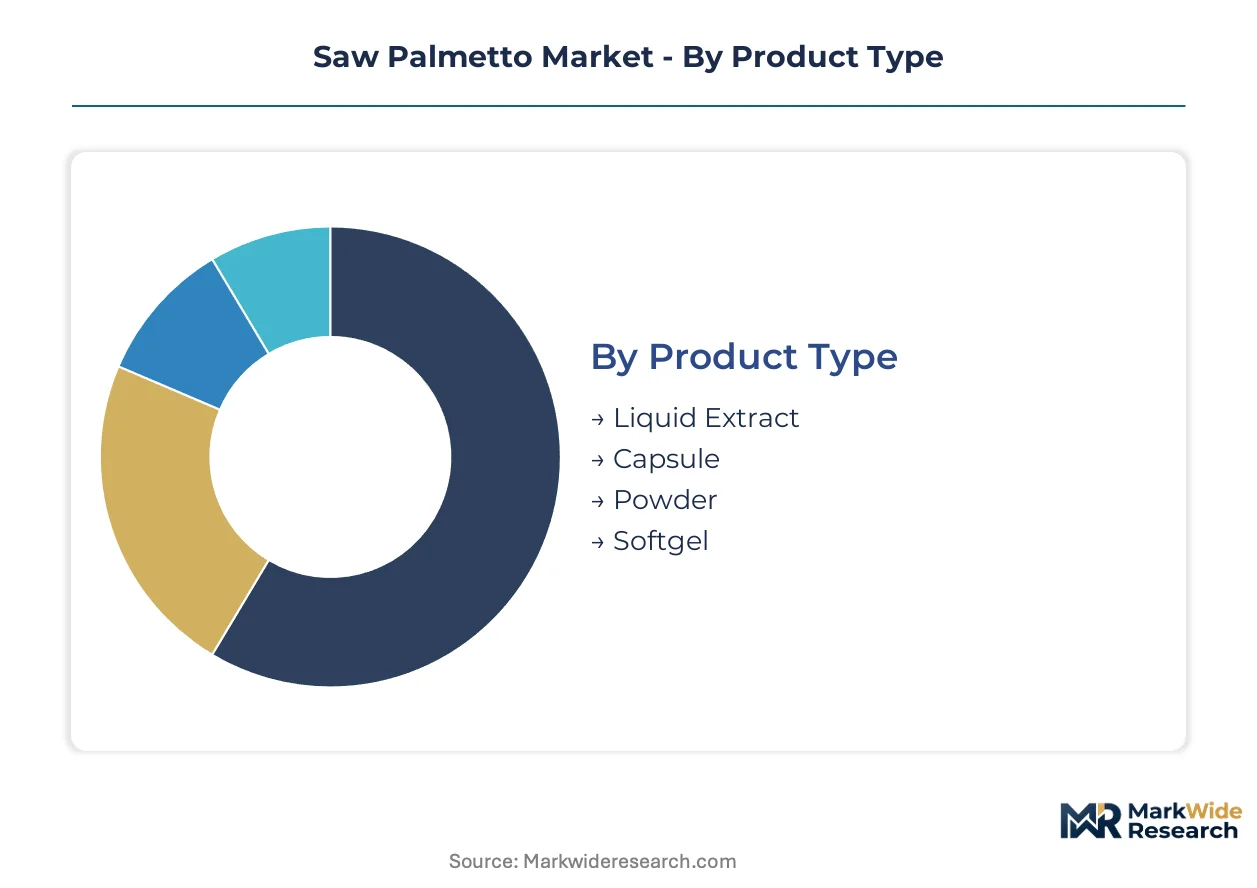
Saw palmetto procurement splits sharply between pharmaceutical-grade specifications and wellness-grade tolerances. Each segment carries distinct regulatory burdens, extraction requirements, and margin structures that reshape supplier qualification priorities.
Product Type:
FDA cGMP and EFSA novel food assessments enforce divergent purity thresholds across delivery formats, concentrating volume among certified processors.
- Liquid Extract:Compounding pharmacies favor this format for dosing flexibility in personalized protocols. Institutional procurement in Germany and the United States concentrates here due to EMA herbal monograph alignment and USP verification requirements.
- Softgel:Direct-to-consumer channels drive fastest expansion through convenience positioning. Auto-delivery subscription models in United States metropolitan clusters capture recurring revenue with minimal retail margin stacking.
- Capsule:Standard two-piece hard shells dominate cost-sensitive wellness retail with simpler manufacturing overhead.
- Powder:Bulk ingredient sales to formulators and Kampo-style preparation houses in Japan.
Liquid extract handles the majority of throughput; softgel is the fastest mover on share.
End User:
Procurement authority concentrates with stakeholders who control reimbursement pathways or repeat purchase mechanisms.
- Healthcare Professionals:Functional medicine networks and integrated health systems negotiate direct supply agreements with USP-verified extractors. Cash-pay wellness practices in United States urban clusters aggregate sufficient volume to justify dedicated procurement infrastructure.
- Health Enthusiasts:Influencer-driven channels favor androgenic alopecia positioning over prostate claims due to lighter regulatory scrutiny on hair loss marketing.
- Retail Consumers:Mass-market softgel purchases through mainstream supplement retail with lower potency expectations.
- Wellness Centers:On-site compounding and personalized protocol delivery for premium service tiers.
Healthcare professionals command the deepest margin pools; health enthusiasts are expanding most quickly through digital-native channels.
Application:
Claim substantiation requirements determine permissible marketing language and formulation investment returns.
- Nutritional Supplements:Broadest positioning flexibility with structural claims on general male wellness. This segment anchors revenue concentration as consumer preference shifts toward plant-based alternatives.
- Hair Loss Treatment:Natural 5-alpha-reductase inhibition positioning faces lighter FDA scrutiny than disease-state claims. Social media amplification drives velocity among younger demographics seeking alternatives to finasteride.
- Prostate Health:EFSA prohibition on disease-risk reduction language forces reformulation toward weaker structural claims with diminished consumer pull-through.
- Dietary Support:General wellness positioning with minimal therapeutic claim exposure.
Nutritional supplements capture the largest revenue base; hair loss treatment shows the steepest expansion trajectory.
Distribution Channel:
Channel selection determines margin retention, customer data access, and regulatory exposure breadth.
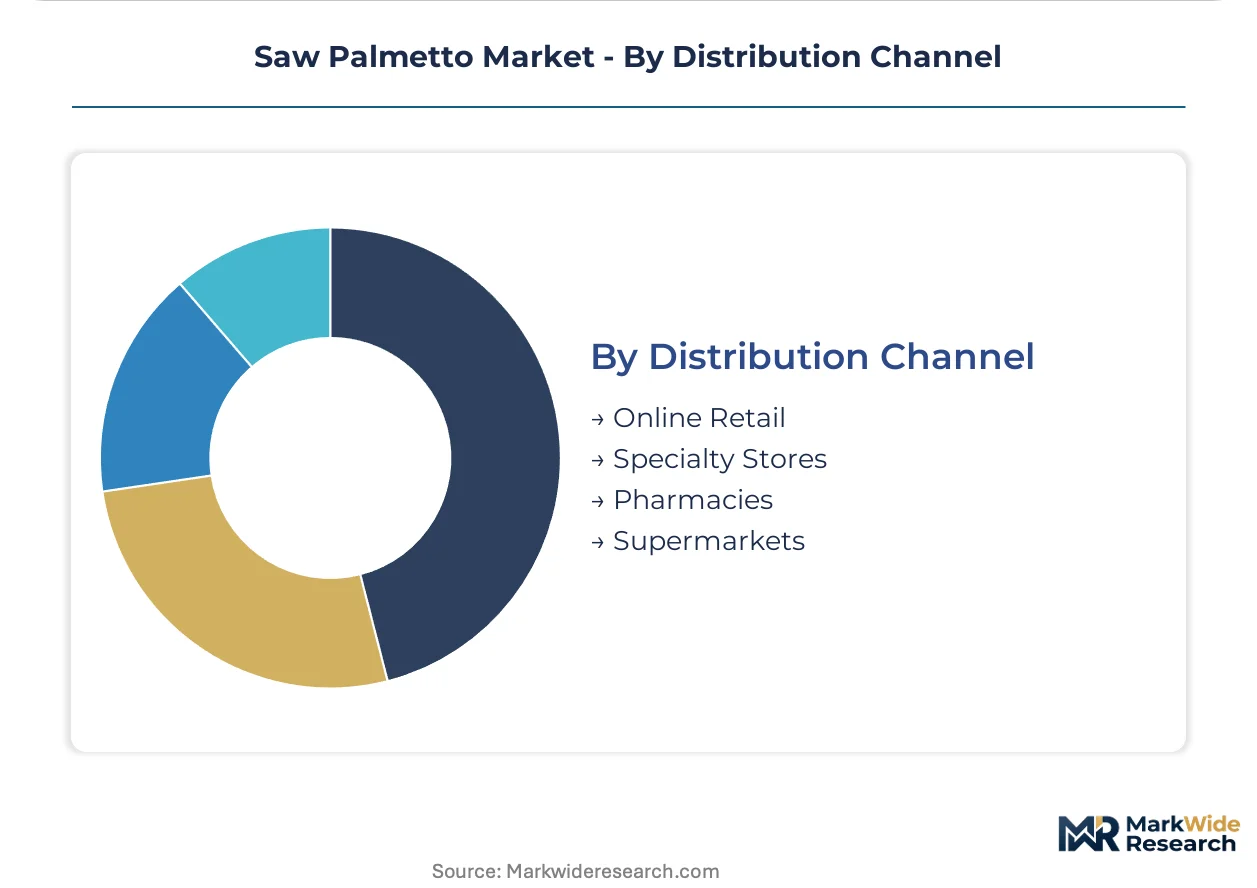
- Online Retail:Direct-to-consumer platforms bypass wholesale intermediation while capturing consumption data for personalization. Subscription auto-delivery models concentrate in United States and German-speaking markets.
- Specialty Stores:Practitioner-exclusive channels require USP verification as table stakes for shelf placement.
- Pharmacies:Reimbursement eligibility in Germany drives institutional procurement through this channel.
- Supermarkets:Mass-market softgel placement with economy-grade specifications and compressed margins.
Online retail commands the fastest share gain; specialty stores handle premium-grade throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate low price elasticity for USP-verified extracts, while mass-market consumers in Brazil and India prioritize cost over certification. This demand bifurcation shapes regional procurement patterns.
United States
Aging demographics and established supplement retail infrastructure sustain category expansion. FDA dietary supplement cGMP enforcement elevates barriers for unstandardized raw material entrants. Florida and Georgia harvests dominate raw material availability, with integrated health systems in metropolitan clusters negotiating direct supply agreements.
Germany
EMA herbal monograph recognition for Serenoa repens drives reimbursement eligibility across statutory health insurance. EFSA novel food assessments extend qualification timelines beyond eighteen months. Institutional procurement concentrates in compounding pharmacies aligned with EMA specifications.
Japan
PMDA guidance on mixed herbal preparations creates pathways for saw palmetto inclusion in Kampo-style formulations. Middle-aged male wellness demand concentrates in Tokyo and Osaka metropolitan areas. Formulation houses source bulk powder for traditional medicine integration.
China
SAMR botanical ingredient regulations tighten extract purity standards for imported supplements. Domestic processors face qualification pressure from NMPA pharmaceutical-grade requirements. Yangtze River Delta formulators import USP-verified extracts for premium positioning.
Brazil
ANVISA supplement registration requirements filter out unstandardized suppliers from mass-market distribution. Cost-sensitive consumers drive demand for ethanol-extracted softgels over CO2-derived alternatives. São Paulo and Rio de Janeiro retail channels concentrate volume.
Saw Palmetto Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the saw palmetto supply base. Supercritical CO2 extraction capabilities concentrate among pharmaceutical-grade suppliers, while ethanol processors retain cost-sensitive wellness contracts. Three archetypes dominate: vertically integrated harvester-extractors, bioavailability technology specialists, and USP-certified premium processors. Consolidation pressures favor M&A among mid-tier ethanol extractors and capacity expansion by CO2-equipped facilities.
Among European-integrated suppliers, Euromed exemplifies harvest-to-extraction vertical control, while Indena represents Italian phytochemical extraction expertise. Sabinsa anchors the bioavailability enhancement specialist tier. These three occupy distinct competitive positions without overlapping capability claims.
| Leading Market Players |
|---|
| Euromed |
| Bio-Botanica |
| Valensa International |
| Sabinsa |
| Maypro |
| Martin Bauer |
| Naturex |
| Nature's Bounty Co. |
| Indena |
| Others |
Value Network & Pricing Analysis
Eighteen-month EFSA novel food qualification timelines compress inventory turns for European-bound extracts, concentrating pricing power with incumbents holding validated safety dossiers while forcing new entrants toward lower-margin whole-berry positioning. This lead-time rigidity in regulatory clearance directly shapes procurement premiums and supplier selection criteria across the saw palmetto value chain.
Pricing Analysis
Subscription auto-delivery programs anchor lifetime value in direct-to-consumer channels, with recurring revenue models commanding premium positioning over transactional retail. Three-tier pricing structure across pharmaceutical-grade, practitioner-channel, and mass-market wellness levels separates USP-verified CO2 extracts from ethanol-derived softgels and unstandardized powders. Cost compression in commodity ethanol tiers is intensifying because USP verification becomes table stakes for practitioner access. Mass-market retail consumers in Brazil and India exhibit highest price sensitivity, while German healthcare professionals and Japanese Kampo formulators demonstrate lowest elasticity for certified extracts.
Supply Chain Analysis
Container availability constraints on Savannah-to-Rotterdam lanes elevate inbound logistics costs for Florida-harvested berries bound for European extraction facilities. Raw material supply concentrates in Florida and Georgia wild harvests, with secondary sourcing from cultivated operations in Texas and Mexico. Supercritical CO2 equipment, USP reference standards, and GC-MS analytical capacity constitute critical input dependencies. Single-source vulnerability in wild berry harvesting exposes processors to climate-induced yield volatility. Distribution runs through direct supply agreements between integrated health systems and certified extractors, disintermediating traditional supplement wholesalers in United States metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Analytical chemists capable of validating fatty acid ratios via GC-MS command compensation premiums that constrain mid-tier extractor expansion, creating durable scarcity for phytochemical standardization expertise. This capability gap shapes competitive dynamics and investment priorities across the supply base.
For Market Incumbents: Compound USP verification advantages through captive CO2 capacity additions in Florida harvesting zones, locking in pharmaceutical-grade throughput before ethanol processors can upgrade. Deepen practitioner channel control via direct supply agreements with functional medicine networks, defending against disintermediation by integrated health systems. Prioritize backward integration into berry sourcing to secure raw material availability against land development pressure and climate volatility. For New Entrants and Emerging Players: Differentiate on Kampo-style formulation partnerships in Japan, where PMDA guidance on mixed herbal preparations creates lower barriers than USP-dominated North American channels. Target androgenic alopecia positioning in influencer-driven digital channels, exploiting lighter regulatory scrutiny on hair loss claims versus prostate health messaging. Pursue white-label softgel supply to subscription wellness brands seeking auto-delivery infrastructure without captive extraction assets. For Investors and Strategic Acquirers: Long-term, this sits as a certification-arbitrage play because regulatory divergence between FDA cGMP, EFSA novel food, and USP monograph requirements creates persistent margin premiums for compliant processors. Acquisition focus should center on mid-tier ethanol extractors with upgradeable CO2 infrastructure and established berry sourcing relationships. Monitor PMDA guidance evolution on mixed herbal preparations as signal for Japanese market inflection.| Strategic Initiative | Industry Significance |
|---|---|
| USP Monograph Compliance Investment | FDA cGMP enforcement elevates verification to table stakes for practitioner channel access. |
| Supercritical CO2 Capacity Expansion | Pharmaceutical-grade batch consistency enables clinical trial sponsorship and compounding pharmacy supply. |
| Direct-to-Consumer Subscription Launch | Auto-delivery models bypass retail margin stacking while capturing consumption data for personalization. |
| Backward Integration into Berry Sourcing | Captive Florida harvest supply insulates processors from climate-induced yield volatility and development pressure. |
| Kampo Formulation Partnership | PMDA guidance on mixed herbal preparations opens Japanese institutional procurement pathways. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA warning letters, EFSA novel food safety opinions, USP monograph documentation, and botanical trade association harvest reports. Primary interviews engaged extraction facility technical directors, functional medicine practitioner network procurement leads, supplement brand formulators, and compounding pharmacy purchasing managers. Secondary validation drew from SAMR botanical ingredient regulations, ANVISA supplement registration databases, and EMA herbal monograph assessments. Bottom-up volume modeling from berry harvest estimates and extraction yield rates triangulates against top-down category spending analysis.
Segmentation dimensions modeled include product format, end-user procurement authority, therapeutic application claim type, and distribution channel structure across the projection horizon. Value projections incorporate fatty acid standardization tier, certification level, and geographic regulatory cluster. CAGRs derive from historical category expansion patterns adjusted for demographic aging trajectories and supplement retail infrastructure development. Forecast inputs include EMA reimbursement eligibility expansion, PMDA Kampo guidance evolution, and influencer channel penetration rates for androgenic alopecia positioning.
Material uncertainties — regulatory enforcement intensity shifts, climate-induced harvest volatility, and synthetic 5-alpha-reductase inhibitor pricing pressure — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained FDA cGMP inspection cadence and stable EFSA novel food assessment timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
GCC Halal Food Market
Specialty Foods
Global Cocoa Nibs Market
Specialty Foods
Middle East and Africa Yerba Mate Market
Specialty Foods
Super Foods Market
Specialty Foods
Areca Bowl Market
Specialty Foods
Halal Products Market
Specialty Foods
Europe Halal Food and Beverage Market
Specialty Foods
Space Food Market
Specialty Foods
Guacamole Market
Specialty Foods
Superfood Bars Market
Specialty Foods
Sweet Spreads Market
Specialty Foods
Vegetarian Taquitos Market
Specialty Foods
Marine Thermal Water Ferments Market
Specialty Foods
Maple Syrup Market
Specialty Foods
Global Hispanic Foods Market
Specialty Foods
Military Forces Ready to Eat Meals Market