
 Dried Tomato Lycopene-Rich Flake Ingredients Market | 2026-2036
Dried Tomato Lycopene-Rich Flake Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Dried Tomato Lycopene-Rich Flake Ingredients Market Insights
Functional beverage developers is bifurcating demand away from legacy bakery buyers for dried tomato lycopene-rich flake ingredients. Lycored leverages its Israel-based extraction infrastructure to supply carotenoid-dense flakes for premium supplement lines. DSM Nutritional Products anchors European distribution through its Basel headquarters and broad food-grade certification portfolio. Kagome competes on raw material proximity, drawing from its integrated tomato processing chain in Japan.
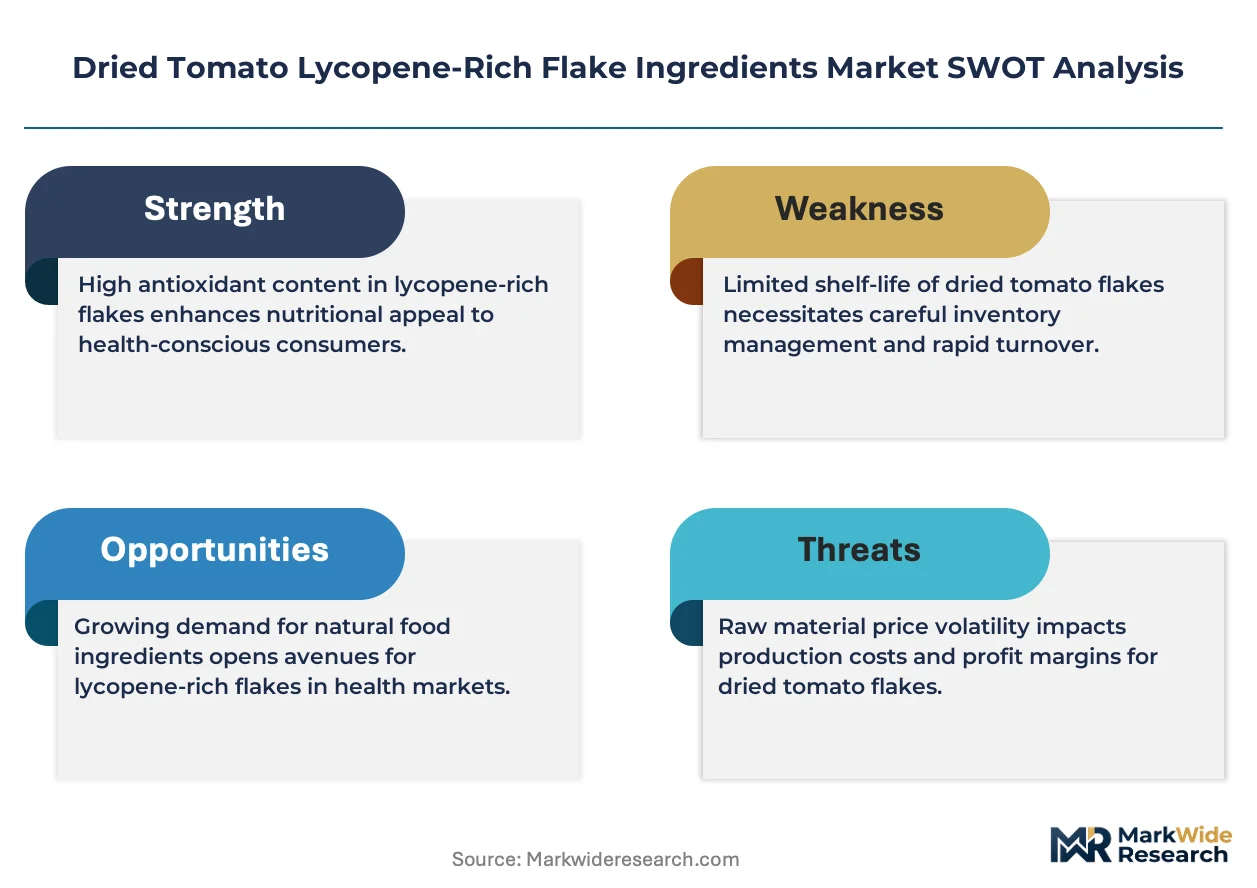
Dried tomato lycopene-rich flake ingredients consist of dehydrated Solanum lycopersicum fruit tissue standardized to elevated carotenoid content, typically achieving lycopene concentrations between 0.5% and 5.0% by weight through controlled thermal processing and solvent-free mechanical concentration. These flakes serve primarily as natural colorants and antioxidant fortificants in clean-label food and supplement matrices. Powder and flake product forms currently occupy the largest volume positions, though extract and concentrate formats command superior unit economics in high-potency nutraceutical applications. Dietary supplement makers represent the fastest-expanding end-user channel, while food manufacturers still generate the deepest margin pools through long-term supply agreements.
The European Food Safety Authority maintains strict purity thresholds for novel food additives, while the FDA governs GRAS self-affirmation pathways for lycopene in U.S. interstate commerce. Japan's Ministry of Health, Labour and Welfare classifies lycopene as a food ingredient with specified manufacturing standards under existing food sanitation law. Stakeholders must monitor evolving maximum residue limits for pesticide carryover in tomato-derived inputs and pre-validate extraction solvent profiles against destination-market positive lists.
Market Dynamics
Clean-label mandates across Germany, the United States, and Japan are compressing formulation timelines for synthetic additive replacements, forcing ingredient buyers to validate natural colorant supply chains before legacy inventory expires.
Growth Catalysts
- EFSA Novel Food Thresholds:Tightened purity standards for plant-derived additives in European nutraceuticals are accelerating flake standardization investments by contract manufacturers serving Central European supplement brands.
- Solvent-Free Mechanical Concentration:Cold-pressing and vacuum dehydration systems are expanding lycopene retention rates without residual solvent contamination, satisfying FDA GRAS self-affirmation pathways for interstate commerce.
- Functional Beverage Formulators:Antioxidant-fortified drink developers in North America are diverting procurement volumes from legacy bakery applications toward high-viscosity liquid matrices requiring dispersible flake formats.
Market Restraints
- Tomato Crop Volatility:Concentrated cultivation in Mediterranean and Californian growing belts exposes processors to climate-driven yield swings that compress raw material margins without forward-contract hedging.
- Extraction Equipment Capex:Supercritical CO2 and membrane filtration systems require seven-figure capital commitments that fragment production scale among mid-tier processors.
- Synthetic Lycopene Substitution:Fermentation-derived carotenoids from microbial hosts are penetrating cost-sensitive food coloring applications where natural provenance carries minimal premium.
Strategic Opportunities
- South Korean Supplement Channels:MFDS registration pathways for functional health foods remain underpenetrated by Western flake suppliers despite accelerating local demand for antioxidant fortification.
- Personalized Nutrition Kits:Direct-to-consumer micronutrient subscription services are creating specification demand for pre-dosed lycopene sachets with batch-level traceability.
- EU Green Deal Procurement Incentives:Carbon footprint disclosure requirements for public foodservice contracts are favoring mechanically processed, low-energy-input flake suppliers over solvent-extracted alternatives.
Industry Challenges
- Cross-Contamination Protocols:Facilities handling both conventional and organic tomato streams face audit complexity from USDA-NOP and EU organic certifiers demanding segregated processing lines.
- Carotenoid Stability Expertise:Shortage of food chemists specializing in oxidative degradation kinetics is delaying shelf-life extension projects for ambient-stable flake formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dried Tomato Lycopene-Rich Flake Ingredients Market |
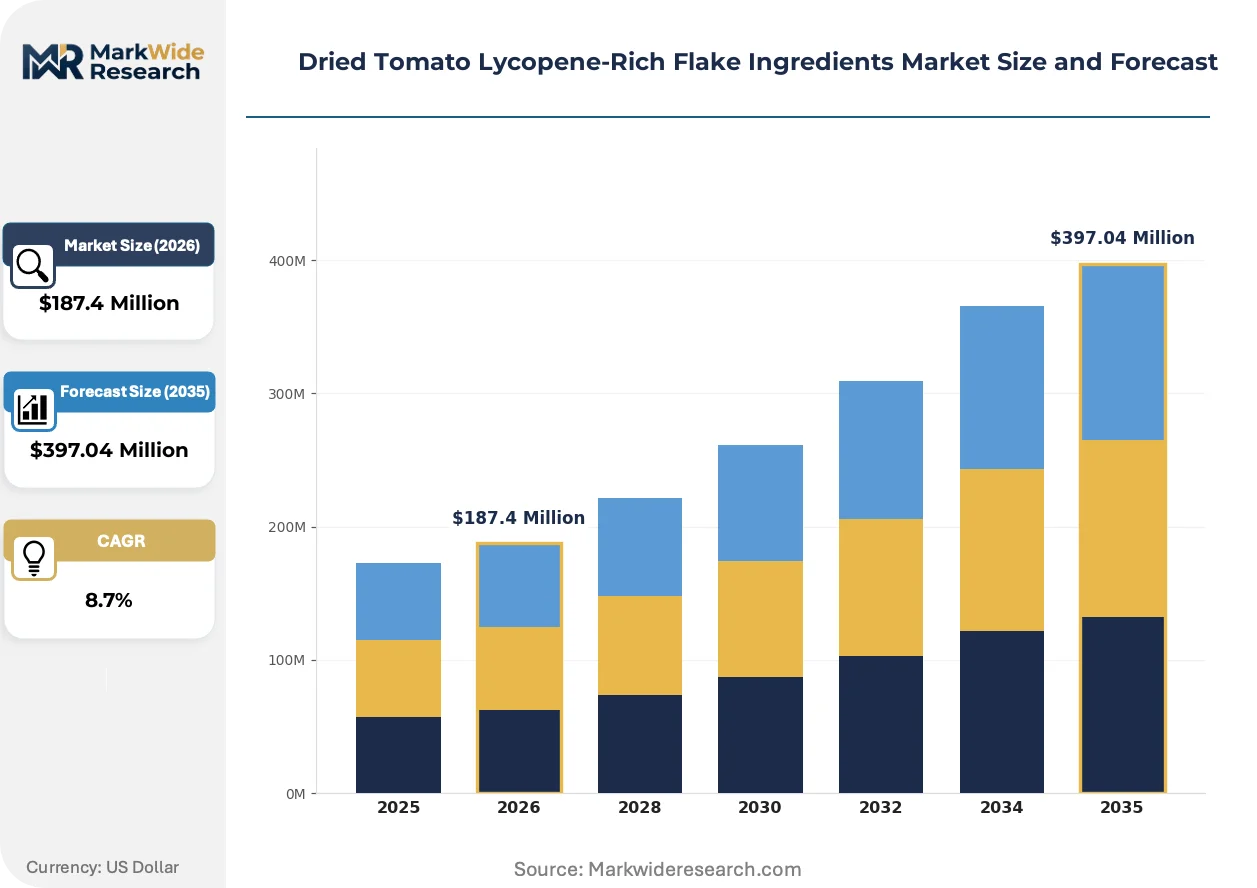
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Form: Powder, Flake, Granule, Extract, Concentrate Application: Beverages, Nutraceuticals, Bakery, Confectionery, Animal Feed End User: Food Manufacturers, Dietary Supplement Makers, Cosmetic Producers, Veterinary, Pet Food Packaging Type: Plastic Pouches, Paper Bags, Aluminum Foil, Jars, Bulk Containers |
| Companies Covered | Lycored, DSM Nutritional Products, Kagome, Chr. Hansen, Kemin Industries, Allied Biotech Corporation, Nutrex Hawaii, Farbest Brands, Givaudan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dried Tomato Lycopene-Rich Flake Ingredients Market Trends and Innovations
Processing technology and procurement logic are diverging from legacy tomato ingredient conventions, with mechanical concentration methods and clean-label verification systems commanding disproportionate R&D allocation.
Spray-dried microencapsulation is supplanting conventional hot-air dehydration for high-potency nutraceutical applications. Supplement formulators in Germany and Switzerland are adopting the format at accelerated validation cycles. The shift is compressing acceptable lycopene loss thresholds from 15% to sub-5% across thermal processing windows.
REACH-compliant solvent disclosure requirements are forcing European processors to document extraction aid residues at parts-per-billion precision. The regulation is redirecting capital toward mechanical concentration infrastructure and away from ethanol-assisted extraction. German ingredient traders are now demanding batch-level solvent affidavits before contract execution.
Long-term offtake agreements with fixed price bands are displacing spot-market purchasing among North American dietary supplement manufacturers. The contractual shift is concentrating procurement authority with three to five national distributors who warehouse certified inventory. California-based formulators are leading the transition to secure supply ahead of harvest volatility.
Dried Tomato Lycopene-Rich Flake Ingredients Market Segmentation
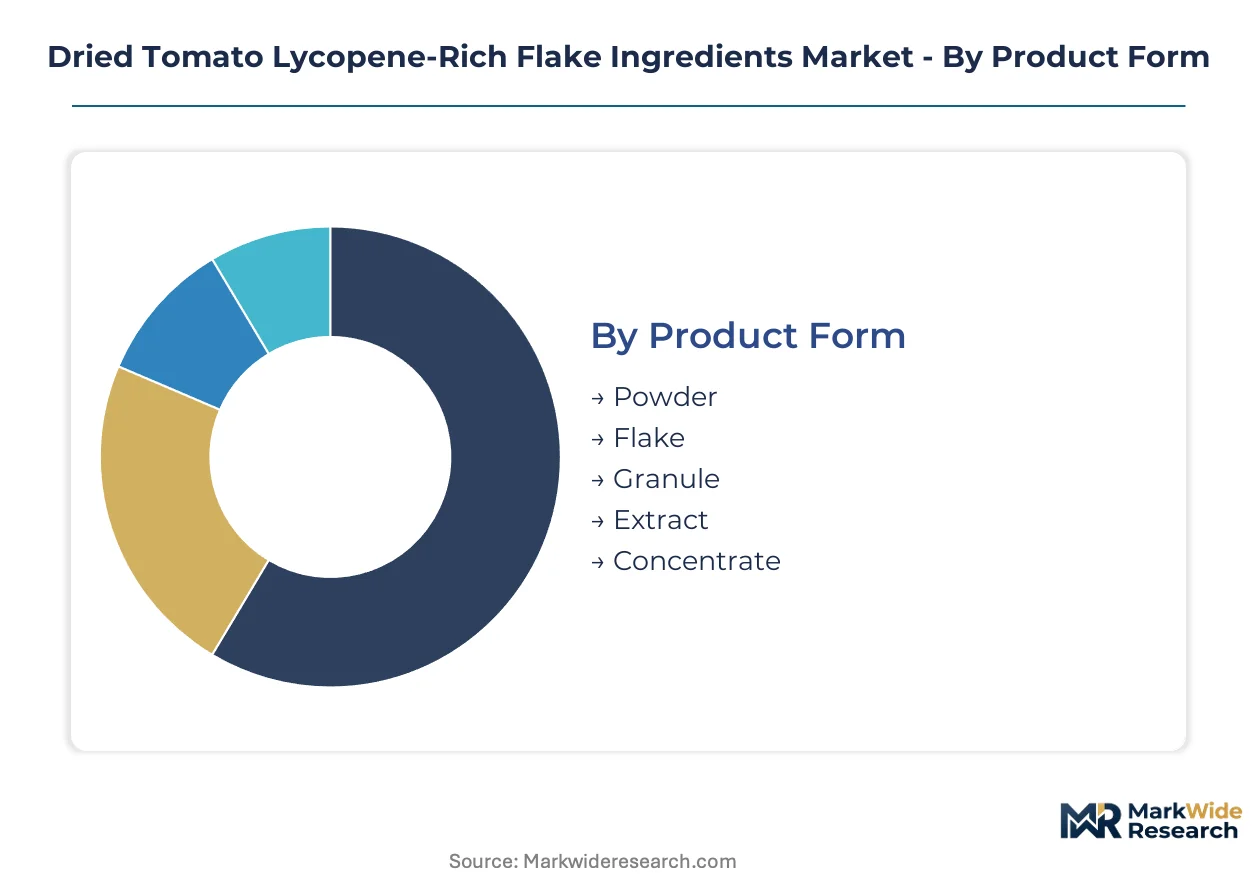
Ingredient buyers segment procurement by technical specification and regulatory pathway. Formulators align product form and packaging with destination-market purity thresholds and shelf-life requirements.
Product Form:
EFSA novel food standards and FDA GRAS pathways impose divergent concentration limits that reshape processor equipment choices.
- Flake:Dehydrated tomato tissue with lycopene concentrations between 0.5% and 5.0% by weight. German nutraceutical contract manufacturers specify flake formats for antioxidant supplement matrices where mechanical concentration satisfies REACH solvent disclosure rules.
- Powder:Finely milled particles produced through spray-dried microencapsulation. North American functional beverage developers in California and New York are diverting procurement volumes toward powder formats for high-viscosity liquid applications requiring rapid dispersibility.
- Extract:Solvent-derived concentrates commanding premium unit economics in high-potency applications.
- Concentrate:Reduced-moisture preparations for industrial-scale fortification.
- Granule:Agglomerated particles optimized for flow properties in automated packaging lines.
Flake handles the majority of throughput; Powder is expanding most quickly on share.
Application:
Procurement volumes concentrate where clean-label mandates compress synthetic additive replacement timelines.
- Nutraceuticals:Antioxidant capsules, tablets, and sachets requiring batch-level traceability. Swiss and German supplement brands validate flake supply chains ahead of legacy inventory expiration under tightened EFSA purity thresholds.
- Beverages:Fortified drinks and functional juices. California formulators secure long-term offtake agreements to hedge against Mediterranean and Californian harvest volatility affecting raw material flows.
- Bakery:Natural colorant replacement for synthetic dyes in bread and pastry applications.
- Confectionery:Plant-derived coloring for gummies and pressed tablets.
- Animal Feed:Poultry and aquaculture formulations leveraging carotenoid deposition for product differentiation.
Nutraceuticals generate the deepest margin pools; Beverages are climbing the fastest on procurement volume.
End User:
Customer type determines specification stringency and certification requirements.
- Dietary Supplement Makers:Pre-dosed sachet and capsule specifications with oxidative stability testing. Direct-to-consumer micronutrient subscription services in North America demand batch-level traceability documentation.
- Food Manufacturers:Industrial-scale procurement through three to five national distributors warehousing certified inventory. Long-term supply agreements with fixed price bands displace spot-market purchasing.
- Cosmetic Producers:Topical antioxidant formulations with dermal safety validation.
- Veterinary:Livestock feed fortification under animal health regulations.
- Pet Food:Premium companion animal nutrition with natural positioning claims.
Food Manufacturers dominate contract volume; Dietary Supplement Makers show the steepest expansion trajectory.
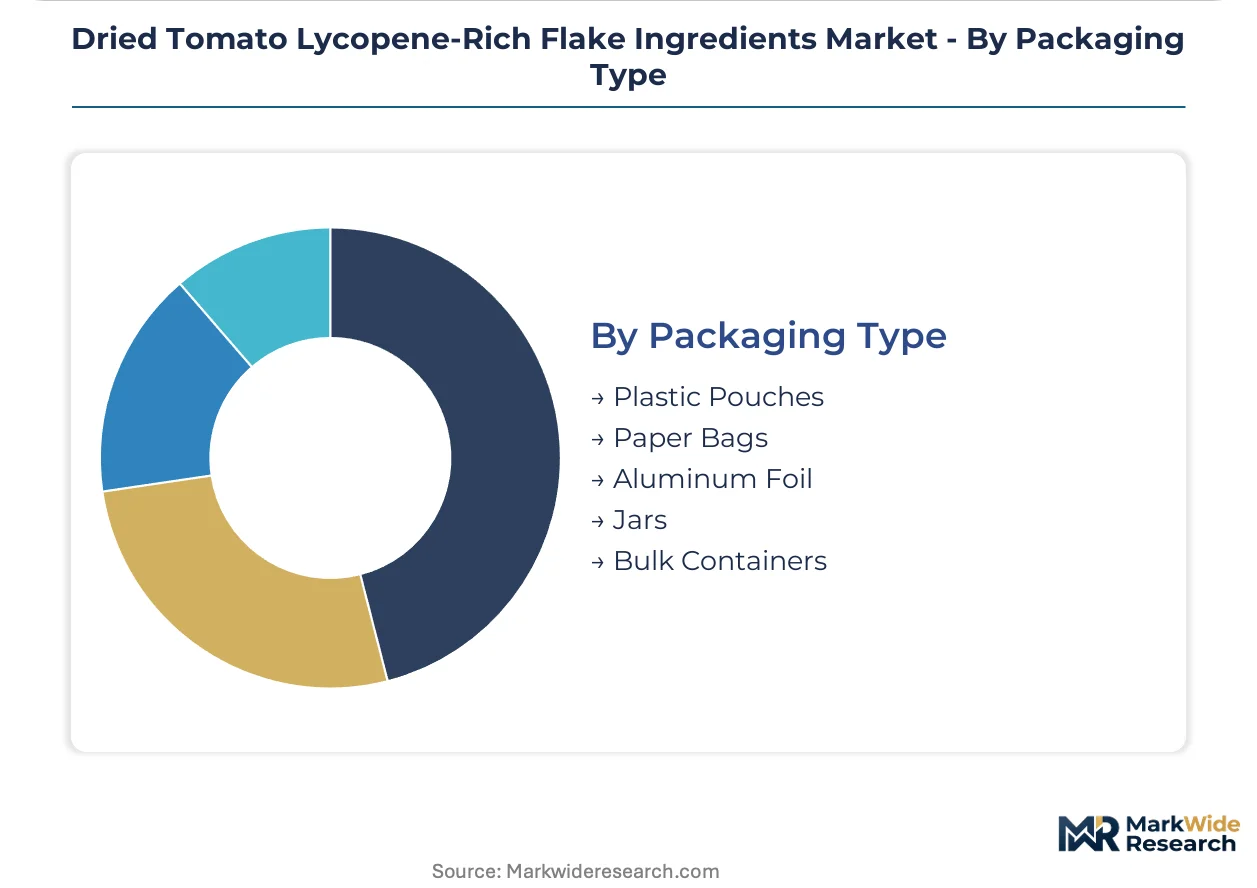
Packaging Type:
Packaging selection hinges on moisture sensitivity and carbon footprint disclosure requirements under EU Green Deal procurement incentives.
- Aluminum Foil:Barrier protection against oxidative degradation for high-potency extracts. German ingredient traders demand this format for mechanically processed, low-energy-input flake suppliers competing for public foodservice contracts.
- Bulk Containers:Industrial totes and drums for high-volume food manufacturing. California-based formulators lead adoption to secure supply ahead of harvest volatility through consolidated warehousing.
- Plastic Pouches:Flexible retail and sample formats.
- Paper Bags:Recyclable options for sustainability-positioned brands.
- Jars:Premium presentation for direct-to-consumer channels.
Bulk Containers move the largest tonnage; Aluminum Foil is gaining share fastest on certification-grade applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ingredient procurement authority concentrates with German nutraceutical contract manufacturers, California functional beverage formulators, and Japanese integrated processors. Clean-label mandates and antioxidant fortification specifications drive regional demand divergence.
Germany
EFSA novel food thresholds compel Central European supplement brands to validate flake supply chains ahead of legacy inventory expiration. REACH-compliant solvent disclosure rules redirect capital toward mechanical concentration infrastructure. Ingredient processors in Hamburg and Frankfurt serve Swiss and German contract manufacturers demanding batch-level purity documentation.
United States
California formulators secure long-term offtake agreements to hedge against Mediterranean and Californian harvest volatility affecting raw material flows. FDA GRAS self-affirmation pathways govern interstate commerce for lycopene-fortified products. Los Angeles and San Diego clusters anchor North American distribution for dispersible powder formats targeting high-viscosity beverage matrices.
Japan
Integrated tomato processing chains in Nagoya and Osaka supply carotenoid-dense inputs for domestic supplement and functional food applications. Ministry of Health, Labour and Welfare classifications under food sanitation law impose specified manufacturing standards. Kanto region processors leverage proximity to raw material cultivation for cost-competitive flake production.
South Korea
MFDS registration pathways for functional health foods remain underpenetrated by Western flake suppliers despite accelerating local demand for antioxidant fortification. Seoul-based supplement distributors are expanding import validation for mechanically processed, low-solvent formats. Domestic brands in Gyeonggi-do seek pre-dosed sachet specifications with oxidative stability testing.
Switzerland
Swissmedic oversight of nutraceutical quality standards elevates specification stringency for premium supplement lines. Basel anchors European distribution networks for food-grade certified inventory. Zurich and Geneva formulators validate flake supply chains against tightened EFSA purity thresholds for antioxidant capsule applications.
Dried Tomato Lycopene-Rich Flake Ingredients Market Competitive Landscape
Player mix skews toward integrated extractors and specialized carotenoid suppliers with captive cultivation or processing infrastructure. Market structure exhibits moderate consolidation around three to five national distributors warehousing certified inventory. Strategic archetypes include Israel-based extraction specialists, Japanese integrated processors, and diversified nutrition ingredient platforms. Dominant competitive moves encompass long-term offtake contracting with fixed price bands and spray-dried microencapsulation technology licensing.
Within the integrated processor tier, Lycored and Kagome exemplify geographic specialization advantages. Lycored leverages Israel-based infrastructure for carotenoid-dense flake production. Kagome draws from integrated tomato processing chains in Japan for raw material proximity. Among diversified nutrition platforms, DSM Nutritional Products anchors European distribution through Basel headquarters and broad food-grade certification portfolios. These three occupy positions spanning extraction specialization, vertical cultivation control, and continental distribution scale.
| Leading Market Players |
|---|
| Lycored |
| DSM Nutritional Products |
| Kagome |
| Chr. Hansen |
| Kemin Industries |
| Allied Biotech Corporation |
| Nutrex Hawaii |
| Farbest Brands |
| Givaudan |
| Others |
Pricing and Supply Chain Analysis
Seven-figure supercritical CO2 extraction systems create steep scale economies that concentrate production among capitalized processors in Germany, California, and Japan, compressing price floors for mechanically concentrated flakes while elevating entry barriers for solvent-dependent competitors. Capacity utilization rates at Israeli and Japanese integrated facilities directly determine spot-market availability and contract pricing bandwidth for North American supplement distributors.
Pricing Analysis
Cost-plus contracts with tomato paste futures indexation dominate procurement between Mediterranean processors and Central European nutraceutical manufacturers. Three-tier pricing structure across mechanical-concentration premium, standard spray-dried, and economy hot-air formats differentiates by lycopene retention rate and REACH solvent disclosure compliance. Pricing pressure stems from fermentation-derived synthetic lycopene penetrating cost-sensitive food coloring applications. Food manufacturers exhibit highest price sensitivity due to volume procurement and synthetic substitution options, while dietary supplement makers accept premium tiers for batch-level traceability.
Supply Chain Analysis
Israel, Japan, and Germany anchor global flake production through Lycored's Beersheba extraction campus, Kagome's Nagoya integrated processing chain, and DSM's Basel distribution hub. Raw material flows draw from California Central Valley and Mediterranean basin tomato cultivation belts, with mechanical concentration equipment and food-grade nitrogen purging systems as critical component dependencies. Single-source vulnerability concentrates in Israeli processing infrastructure subject to regional logistics disruption. Distribution runs through three to five national distributors warehousing certified inventory under long-term offtake agreements with fixed price bands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Dried Tomato Lycopene-Rich Flake Ingredients Market is cycling through recovery as harvest volatility and clean-label mandates tighten supply discipline and elevate natural colorant premiums.
For Market Incumbents: Secure long-term offtake agreements with California and Mediterranean tomato growers to hedge against climate-driven yield compression threatening raw material margins. Deepen backward integration into mechanical concentration infrastructure to defend against synthetic lycopene substitution in cost-sensitive applications. Prioritize REACH-compliant solvent disclosure documentation to maintain premium positioning in German and Swiss nutraceutical channels. For New Entrants and Emerging Players: Lead with MFDS registration pathway expertise to capture underpenetrated South Korean functional health food demand for antioxidant fortification. Target direct-to-consumer micronutrient subscription services seeking pre-dosed sachet specifications with oxidative stability testing. Establish go-to-market partnerships with Seoul-based supplement distributors to bypass incumbent warehousing consolidation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among mechanically processed flake suppliers with captive cultivation or long-term grower contracts securing raw material throughput. Five-to-ten-year viability favors processors with spray-dried microencapsulation licensing capabilities and EU Green Deal carbon disclosure compliance. Watch for inflection in personalized nutrition kit specifications demanding batch-level traceability as signal of premium tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mechanical Concentration | REACH-compliant solvent-free processing secures premium positioning in EFSA-regulated European nutraceutical channels. |
| Long-term Supply Agreement with Tomato Growers | Forward contracting hedges California and Mediterranean harvest volatility compressing raw material margins. |
| Spray-Dried Microencapsulation Licensing | German and Swiss supplement brands adopt sub-5% lycopene loss formats at accelerated validation cycles. |
| MFDS Registration Pathway Investment | Seoul-based distributors expand import validation for mechanically processed flakes amid accelerating local antioxidant demand. |
| EU Green Deal Carbon Disclosure Program | Low-energy-input mechanical processing qualifies for public foodservice procurement incentives favoring sustainable suppliers. |
Research Methodology
A standing panel of ingredient procurement managers at German contract manufacturers, California functional beverage formulators, Japanese integrated processors, and Swiss supplement brand technical directors provided ongoing calibration against secondary validation from EFSA novel food filings, FDA GRAS affirmation databases, MFDS functional health food registrations, and REACH solvent disclosure compliance records. Bottom-up volume estimates from processor capacity utilization and top-down demand triangulation from end-use procurement surveys were cross-referenced for consistency.
External benchmark validation against customs trade flows and food-grade carotenoid import records confirmed segmentation outputs across product form, application, and end-user dimensions. CAGRs were derived from modeled lycopene retention rate improvements, clean-label regulatory adoption curves, and synthetic substitution elasticity parameters. Forecast inputs incorporated mechanical concentration technology deployment rates and personalized nutrition kit specification demand trajectories.
The analysis sits within stated boundaries; outcomes outside sustained EFSA purity threshold tightening, FDA GRAS pathway stability, or Mediterranean climate pattern continuity would require recalibration. Forecasts reflect documented assumptions about harvest volatility, solvent disclosure enforcement intensity, and fermentation-derived carotenoid cost curves. Recalibration cycles align with material shifts in EU Green Deal procurement incentive expansion and MFDS registration pathway completion rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Pork Skin Gelatin Market
Ingredients
Dry Molasses Products Market
Ingredients
Thinned Starch Market
Ingredients
Icing Shortening Market
Ingredients
Barley Malt Extract Market
Ingredients
Africa Food Ingredients Market
Ingredients
Vegan Ingredients Market
Ingredients
Italy Soy Protein Market
Ingredients
Dry Malt Products Market
Ingredients
Passion Fruit Powder Market
Ingredients
Psyllium Husk Powder Market
Ingredients
Salt Market
Ingredients
Soybean Meal Market
Ingredients
Shortening Fats Market
Ingredients
Phytosterols Market
Ingredients
Asia-Pacific Potato Protein Market