
 North American Jam, Jelly, and Preserve Market | 2026-2036
North American Jam, Jelly, and Preserve Market Size, Share, and Industry Trends Forecast 2026-2036
North American Jam, Jelly, and Preserve Market Insights
California fruit processors is repositioning toward higher-margin organic preserves as water scarcity reshapes acreage allocation. The J. M. Smucker Company leverages its vertically integrated fruit sourcing to sustain cost advantages across conventional and organic lines. B&G Foods anchors its portfolio in heritage brands that dominate Northeast retail shelves. The Kraft Heinz Company competes through massive manufacturing scale and deep penetration into foodservice channels.
Jam, jelly, and preserve denotes shelf-stable fruit spreads manufactured through pectin-gelation, sugar concentration, and thermal processing to achieve water activity below 0.85 for ambient stability. These products serve retail consumers, foodservice operators, and industrial bakeries as flavoring ingredients, toppings, and filling components. Fruit jam commands the largest volume pool due to breakfast ritual stickiness and private-label proliferation, while nut butter generates premium margins as plant-protein positioning attracts health-oriented buyers. Glass jars retain dominance in premium positioning despite higher logistics cost, though pouches are gaining traction in single-serve foodservice and on-the-go consumption formats.
The FDA governs standard of identity rules under 21 CFR 150, mandating minimum fruit soluble solids and restricting artificial flavor claims, while Health Canada enforces parallel compositional standards through the Food and Drug Regulations. USDA organic certification and Canada Organic Regime create dual-track compliance burdens for cross-border suppliers. Stakeholders must monitor evolving added-sugar disclosure requirements and state-level packaging waste mandates that threaten to disrupt conventional glass-heavy supply configurations.
Market Dynamics
Water scarcity across California's Central Valley is forcing fruit processors to abandon conventional acreage and relocate higher-margin organic preserve production to the Pacific Northwest, permanently altering regional supply concentration.
Growth Catalysts
- 21 CFR 150 Standard of Identity:FDA-mandated minimum fruit soluble solids create quality floors that block low-grade imports and protect domestic processor margins.
- Foodservice menu expansion:Premium spreads are penetrating fast-casual breakfast chains and boutique hotel operations across the United States and Canada.
- Pacific Northwest berry concentration:Oregon and Washington raspberry and marionberry harvests supply raw material for high-value small-batch preserves.
Market Restraints
- Cane sugar price volatility:Input cost swings compress margins for mid-tier processors lacking forward-contract coverage.
- California water allocation cuts:State-level agricultural water restrictions threaten stone fruit supply reliability for apricot and peach preserves.
- Artificial sweetener substitution:Low-calorie spread alternatives erode volume in conventional sugar-based jelly segments.
Strategic Opportunities
- Canada Organic Regime certification:Dual-track USDA-Canada organic compliance opens cross-border premium shelf space with limited competitor saturation.
- Single-serve pouch formats:On-the-go consumption channels in airport and convenience retail remain underdeveloped relative to glass jar penetration.
- Industrial bakery ingredient supply:Frozen dough manufacturers in the Midwest seek clean-label fruit fillings with extended ambient stability.
Industry Challenges
- Pectin chemistry expertise shortage:Food science programs produce fewer specialists in hydrocolloid gelation systems required for low-sugar formulation.
- State packaging waste mandates:Extended producer responsibility laws in California and Oregon force glass-heavy supply chain reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North American Jam, Jelly, and Preserve Market |
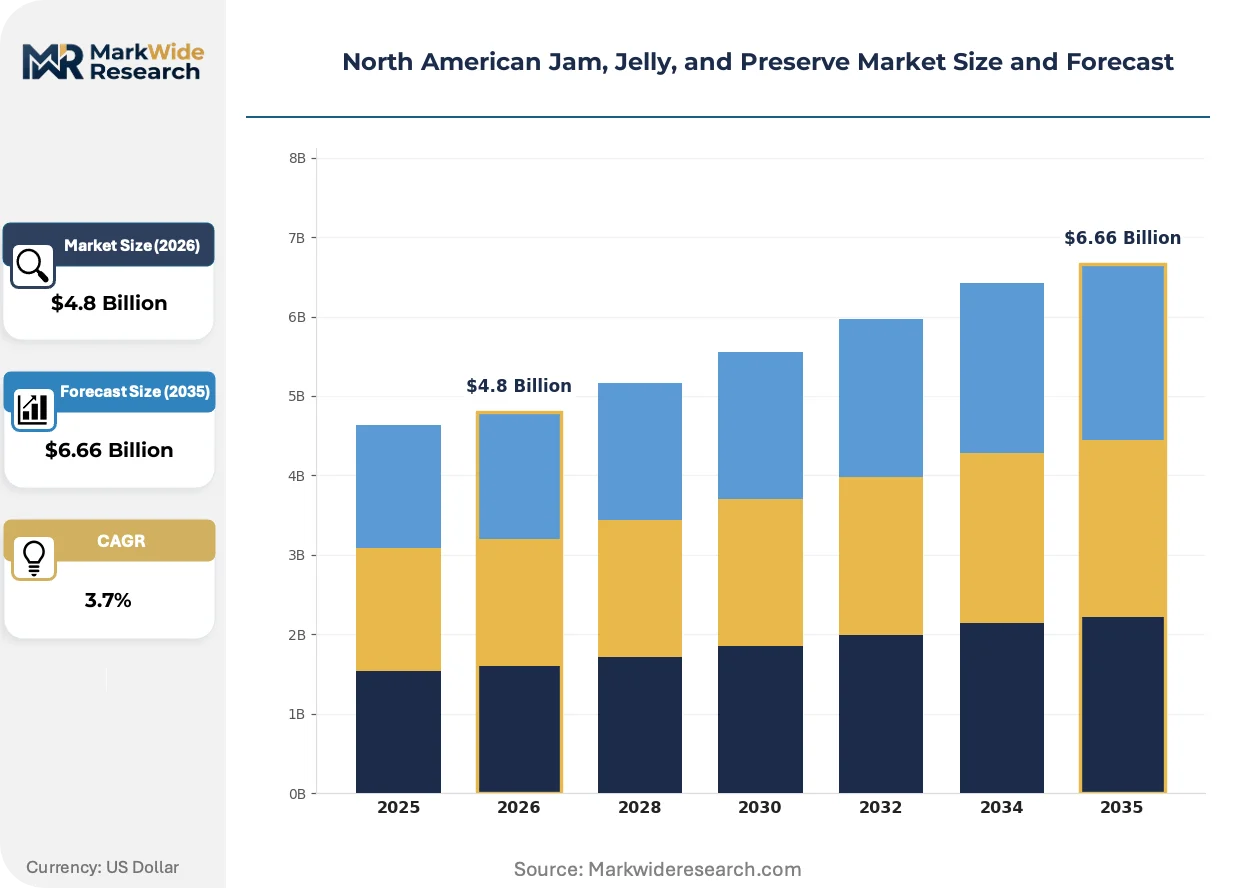
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit Jam, Nut Butter, Spreads, Preserves Ingredient: Organic Fruits, Artificial Flavorings, Pectin, Sweeteners Packaging Type: Glass Jars, Plastic Containers, Tetra Packs, Pouches Distribution Channel: Supermarkets, Online Retailers, Farmer's Markets, Specialty Stores |
| Companies Covered | The J. M. Smucker Company, B&G Foods, The Kraft Heinz Company, Andros Group, Conagra Brands, Unilever Group, Ferrero Group, Hershey Company, The Hain Celestial Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North American Jam, Jelly, and Preserve Market Trends and Innovations
Reformulation pressure and format experimentation are converging to reshape how fruit spreads reach consumers across retail, foodservice, and industrial channels.
Aseptic processing technology is decentralizing preserve manufacturing by enabling smaller-scale production without thermal degradation of volatile flavor compounds. Regional co-packers in Texas and Colorado are adopting these systems to serve local organic brands. This distributed production model is compressing freight costs and shortening farm-to-jar timelines for perishable berry inputs.
Health Canada's updated Food and Drug Regulations on added-sugar disclosure are forcing reformulation across products sold in Ontario and Quebec. Processors must recalculate label declarations or face provincial enforcement actions. The compliance burden falls heaviest on private-label suppliers serving discount retail banners.
Clean-label procurement criteria are reshaping buyer-seller relationships as institutional foodservice operators audit ingredient provenance. Third-party certification programs are displacing self-declared natural claims in contract negotiations. This verification-heavy approach concentrates purchasing power with processors maintaining dual organic and non-GMO supply chains.
North American Jam, Jelly, and Preserve Market Segmentation
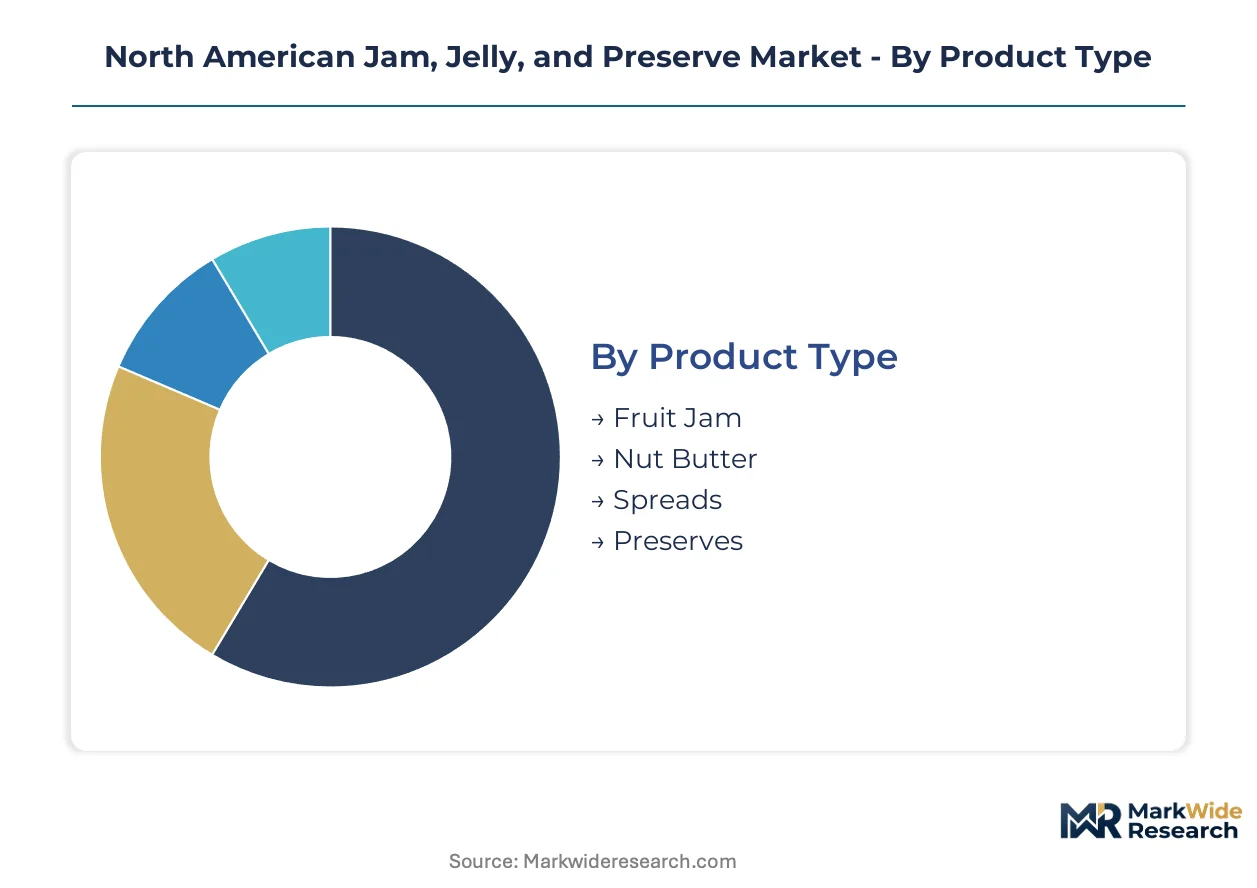
Segmentation in the North American jam, jelly, and preserve market reveals how supply chain configuration and regulatory pressure fragment commercial opportunity across distinct product, ingredient, packaging, and channel dimensions. Each category carries unique compliance burdens and margin profiles that reshape processor investment priorities.
Product Type:
Supply concentration in fruit jam manufacturing dominates processor capacity allocation across California and Pacific Northwest facilities.
- Fruit Jam:Pectin-gelled spreads containing minimum 45% fruit soluble solids per FDA 21 CFR 150 standards. Breakfast ritual consumption in United States households absorbs the majority of volume, though private-label proliferation compresses branded margins in conventional retail.
- Nut Butter:Shelf-stable ground nut pastes positioned as plant-protein alternatives. Premium pricing in Canadian health-food retail and United States coastal metro markets attracts health-oriented buyers seeking clean-label spreads.
- Spreads:Hybrid fruit-nut formulations and specialty alternatives. Mid-tier processors in Texas and Colorado co-packing facilities serve regional organic brands with shorter farm-to-jar timelines.
- Preserves:Whole-fruit or large-cut preparations with higher fruit content than standard jams. Small-batch production in Oregon and Washington raspberry and marionberry harvest zones supplies foodservice and specialty retail.
Fruit jam absorbs the bulk of installed capacity; nut butter is expanding most quickly.
Ingredient:
Cost tier differentiation separates premium-positioned inputs from commodity-grade alternatives that dominate private-label formulations.
- Organic Fruits:Certified produce meeting USDA National Organic Program and Canada Organic Regime standards. Pacific Northwest berry-growing regions and California's remaining organic stone fruit acreage supply raw material for cross-border premium shelf space.
- Artificial Flavorings:Synthetic compounds restricted under FDA 21 CFR 150 identity rules. Discount retail banners in Ontario and Quebec face reformulation pressure as Health Canada tightens added-sugar disclosure requirements.
- Pectin:Hydrocolloid gelling agent extracted from citrus peel or apple pomace. Low-sugar formulation demands specialized pectin chemistry expertise that food science programs now produce in declining numbers.
- Sweeteners:Cane sugar, corn syrup, and alternative carbohydrate inputs. Price volatility in cane sugar markets compresses margins for mid-tier processors lacking forward-contract coverage.
Organic fruits command the steepest price premiums; pectin sourcing is concentrating with specialty hydrocolloid suppliers.
Packaging Type:
Application-driven format selection separates retail shelf-stable positioning from foodservice operational convenience.
- Glass Jars:Premium-positioned containers dominating conventional retail despite higher logistics costs. Extended producer responsibility laws in California and Oregon force supply chain reconfiguration toward lighter alternatives.
- Plastic Containers:Polymer-based jars and tubs reducing freight weight for mass-market distribution. Midwest frozen dough manufacturers favor these for industrial bakery ingredient supply contracts.
- Tetra Packs:Aseptic carton formats enabling ambient-stable distribution without refrigeration. Regional co-packers in Texas adopting aseptic processing technology serve local organic brands with volatile flavor compound preservation.
- Pouches:Flexible single-serve formats gaining traction in airport and convenience retail channels. On-the-go consumption applications remain underdeveloped relative to glass jar penetration.
Glass jars retain dominant share in premium retail; pouches are climbing the fastest in foodservice deployment.
Distribution Channel:
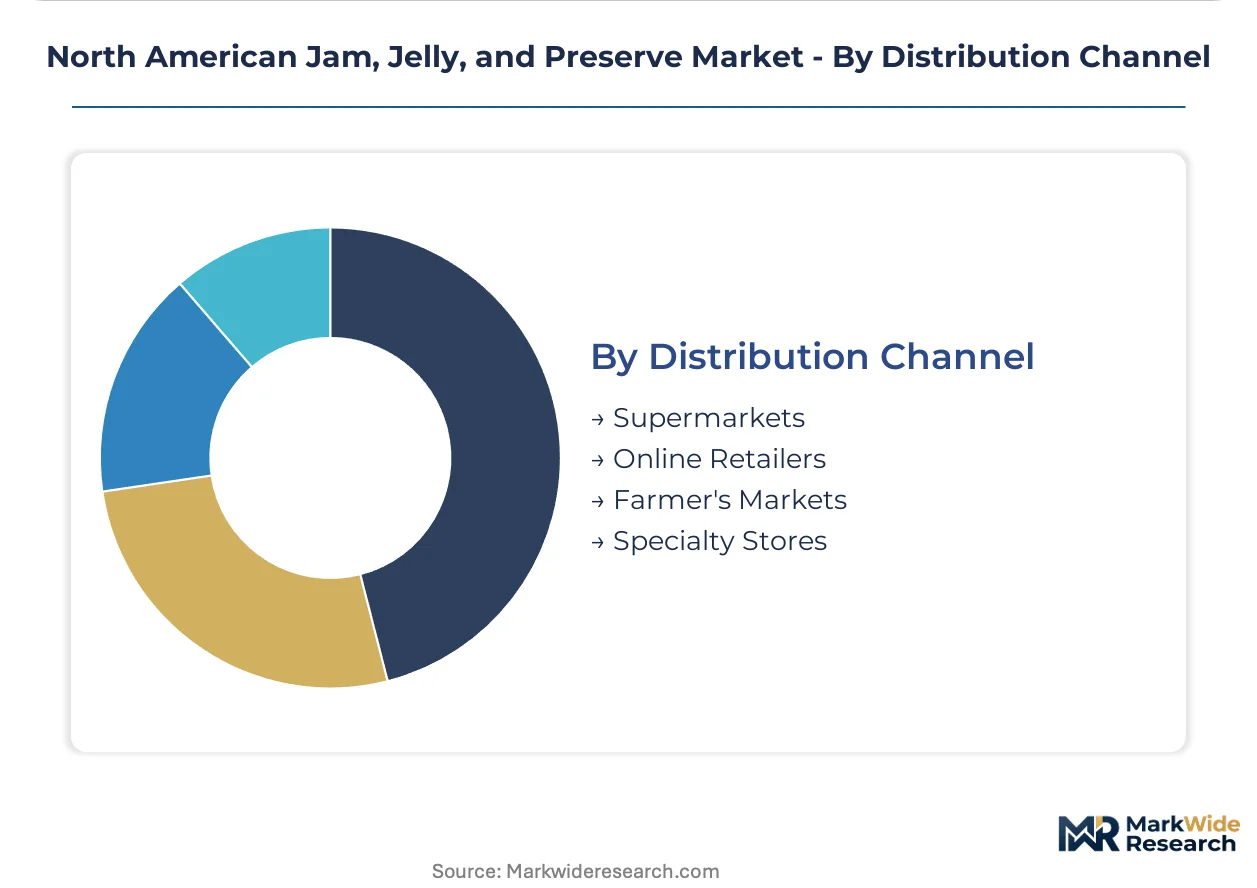
Customer type and procurement scale determine channel access requirements and margin capture potential for processor portfolios.
- Supermarkets:Mass-market retail banners commanding volume concentration in United States and Canada conventional grocery. Clean-label procurement criteria from institutional foodservice operators now influence retail buyer negotiations.
- Online Retailers:E-commerce platforms enabling direct-to-consumer premium positioning. Third-party certification programs displace self-declared natural claims in digital shelf competition.
- Farmer's Markets:Direct producer-to-consumer channels concentrated in California agricultural corridor and Pacific Northwest berry-growing regions. Small-batch preserves from Oregon and Washington harvest zones achieve price premiums here.
- Specialty Stores:Premium food retailers and health-food banners in Canadian urban centers and United States coastal metros. Dual-track USDA-Canada organic compliance opens limited competitor saturation in this channel.
Supermarkets absorb the bulk of volume throughput; online retailers are gaining share fastest in premium segment development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley stone fruit orchards and the Pacific Northwest berry belt anchor North American raw material supply, while water scarcity and regulatory divergence reshape processor location decisions across the continent.
United States
Breakfast ritual consumption drives volume concentration in conventional retail, with private-label proliferation compressing branded margins. FDA enforcement of 21 CFR 150 identity standards blocks low-grade imports and protects domestic processor quality floors. California fruit processors are relocating higher-margin organic preserve production to the Pacific Northwest as agricultural water restrictions intensify.
Canada
Health Canada's updated Food and Drug Regulations on added-sugar disclosure force reformulation across products sold in Ontario and Quebec. Dual-track USDA-Canada Organic Regime compliance creates cross-border premium shelf opportunities with limited competitor saturation. British Columbia's Fraser Valley berry operations supply raw material for small-batch preserves targeting specialty retail banners.
Mexico
Mid-tier processors leverage proximity to United States distribution networks for cost-competitive conventional jam supply. Mexico's national health regulator enforces labeling standards aligned with evolving North American trade requirements. Guadalajara and Monterrey industrial corridors host co-packing facilities serving private-label demand from discount retail chains.
North American Jam, Jelly, and Preserve Market Competitive Landscape
Global majors compete with regional champions across procurement scale, brand heritage, and channel penetration dimensions. The vendor base clusters around three strategic archetypes: vertically integrated fruit processors commanding upstream supply control, heritage-brand portfolio managers dominating retail shelf space, and diversified food conglomerates leveraging manufacturing scale for foodservice access. Dominant competitive moves include backward integration into captive fruit sourcing and portfolio diversification into adjacent spread categories.
Within the heritage-brand tier, The J. M. Smucker Company and B&G Foods exemplify positioning built on decades of retail presence and consumer recognition. The Kraft Heinz Company occupies a scale-driven position leveraging massive manufacturing infrastructure and deep foodservice channel relationships. These three entities represent distinct competitive vectors: upstream supply control, regional retail anchoring, and operational scale deployment.
| Leading Market Players |
|---|
| The J. M. Smucker Company |
| B&G Foods |
| The Kraft Heinz Company |
| Andros Group |
| Conagra Brands |
| Unilever Group |
| Ferrero Group |
| Hershey Company |
| The Hain Celestial Group |
| Others |
Pricing and Supply Chain Analysis
Pectin chemistry specialists concentrated in California's Central Valley and Pacific Northwest command wage premiums that widen spreads between artisanal small-batch preserves and commodity-grade private-label jams. Labor-cost differentials in hydrocolloid formulation expertise directly map to three-tier pricing structure across premium, standard, and economy levels, with FDA 21 CFR 150 compliance certification acting as the threshold between tiers.
Pricing Analysis
Service-bundling separates premium-positioned organic preserves with third-party certification audits from unbundled economy tiers lacking provenance verification. Three-tier pricing structure across premium, standard, and economy levels stratifies by fruit soluble solids content and dual-track USDA-Canada Organic Regime compliance status. Pricing pressure stems from cane sugar price volatility compressing margins for mid-tier processors without forward-contract coverage. Discount retail banners in Ontario and Quebec exhibit highest price sensitivity, while specialty stores in coastal metros absorb premium markups for small-batch marionberry and raspberry preserves.
Supply Chain Analysis
Domestic-content rules in California and Oregon extended producer responsibility laws are forcing glass-heavy supply chain reconfiguration toward lighter packaging alternatives. Raw material supply concentrates in the United States Pacific Northwest berry belt, California's remaining Central Valley stone fruit acreage, and British Columbia's Fraser Valley. Pectin inputs draw from citrus peel processors in Florida and apple pomace suppliers in Washington State. Single-source vulnerability looms in Pacific Northwest berry concentration exposed to climate-driven harvest variability. Distribution runs through mass-market supermarket banners, foodservice broadline distributors, and direct-to-consumer online platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
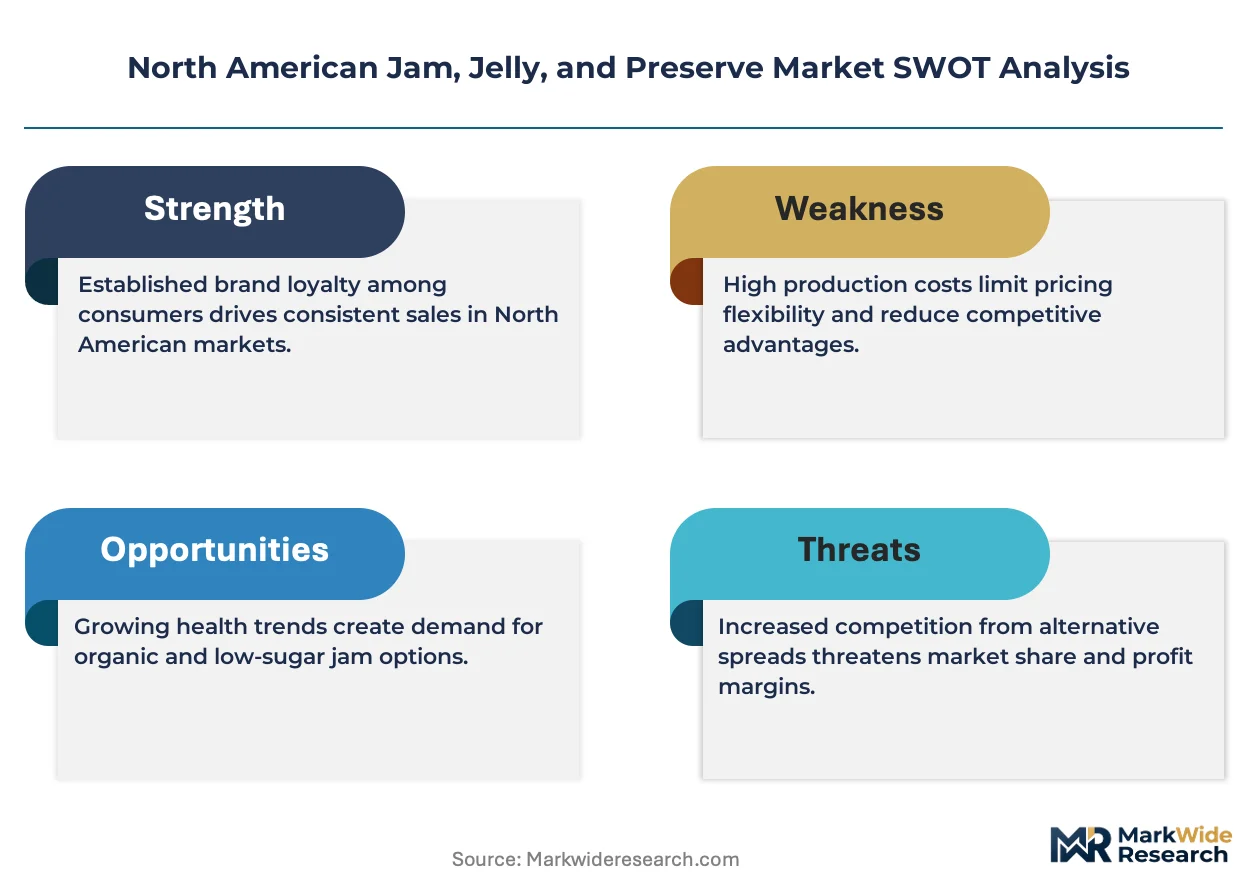
This market reads as a cost-of-compliance story where FDA 21 CFR 150 standard of identity enforcement and Health Canada added-sugar disclosure rules erect barrier-to-entry moats favoring processors with in-house regulatory affairs capabilities.
For Market Incumbents: Hedge against water scarcity-driven supply relocation by securing long-term contracts with Pacific Northwest berry growers before competitor concentration accelerates. Invest in aseptic processing technology at regional co-packing facilities to capture single-serve pouch format growth in airport and convenience retail channels. Defensive consolidation through captive organic fruit sourcing in Oregon and Washington protects margin structure against California acreage abandonment.
For New Entrants and Emerging Players: Aseptic processing technology adoption offers a technology-first wedge into underdeveloped single-serve foodservice channels where glass jar penetration remains minimal. Target industrial bakery ingredient supply contracts with Midwest frozen dough manufacturers seeking clean-label fruit fillings with extended ambient stability. Go-to-market positioning should emphasize Canada Organic Regime certification for cross-border premium shelf access with limited incumbent saturation.
For Investors and Strategic Acquirers: The window for entry favors mid-scale processors with dual USDA-Canada organic certification and established Pacific Northwest fruit sourcing relationships. Long-term viability hinges on water-resilient supply geography and pectin chemistry expertise scarcity. Watch California agricultural water allocation rulings as the inflection signal for accelerated industry consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Fruit Sourcing | Captive supply from Oregon and Washington berry operations secures margin protection against California water cuts. |
| Aseptic Processing Technology Deployment | Regional co-packers in Texas and Colorado compress farm-to-jar timelines for volatile flavor preservation. |
| Dual Certification Investment | USDA-Canada Organic Regime compliance opens premium shelf space with limited cross-border competitor presence. |
| Single-Serve Pouch Format Launch | Flexible packaging penetrates airport and convenience retail channels where glass jar logistics costs dominate. |
| Industrial Bakery Ingredient Supply Expansion | Clean-label fruit filling contracts with Midwest frozen dough manufacturers diversify beyond retail concentration. |
Research Methodology
Multi-period observation of FDA enforcement patterns, Health Canada regulatory amendments, and California water allocation decisions anchored the trend analysis, supplemented by interviews with fruit procurement directors at major processors, co-packing facility operators in Texas and Colorado, category buyers at United States and Canadian supermarket banners, and foodservice distribution executives. Secondary validation drew from FDA 21 CFR 150 regulatory filings, Health Canada Food and Drug Regulations updates, USDA National Agricultural Statistics Service harvest data, Nielsen retail audit measurements, and customs trade records for pectin and sweetener imports. Bottom-up processor capacity assessments and top-down retail channel value estimates were triangulated for convergence.
Segment-weighting across product type, ingredient certification tier, packaging format, and distribution channel dimensions structured the analytical framework across the analysis window. CAGRs were derived from trend extrapolation of historical volume and value trajectories adjusted for regulatory compliance cost imposition and water scarcity-driven supply relocation. Industry-specific forecast inputs included Pacific Northwest berry harvest projections and cane sugar futures price volatility indices.
Several conditions sit outside the modeled scope, including abrupt tariff reconfiguration on Mexican processed fruit imports, catastrophic climate events affecting Pacific Northwest growing seasons, and rapid artificial sweetener technology disruption in low-calorie spread alternatives. Forecasts reflect documented assumptions about regulatory enforcement continuity and water allocation policy stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Vegetarian Tacos Market
Specialty Foods
Huoxiangzhengqi Market
Specialty Foods
Space Food Market
Specialty Foods
Wet Grain-Free Pet Food Market
Specialty Foods
Gluten-Free Oats Market
Specialty Foods
Halal Products Market
Specialty Foods
Carbonic Maceration Market
Specialty Foods
Grain-Free Pet Food Market
Specialty Foods
Low Fat Hummus Market
Specialty Foods
Fruit Dessert Market
Specialty Foods
Yeast-Based Spreads Market
Specialty Foods
Coconut Butter Market
Specialty Foods
Low-Fat Low-Calorie Desserts Market
Specialty Foods
Jams, Jellies & Preserves Market
Specialty Foods
Low Fat and Low Carb Foods Market
Specialty Foods
Military Forces Ready to Eat Meals Market