
 Cat Food Toppings Market | 2026-2036
Cat Food Toppings Market Size, Share, and Industry Trends Forecast 2026-2036
Cat Food Toppings Market Outlook
Multi-source ingredient procurement is recalibrating how manufacturers balance cost volatility against clean-label credibility. Nestlé Purina PetCare leverages its captive supply chain for consistent protein sourcing across North American facilities. Mars Incorporated anchors its portfolio through veterinary-endorsed formulations that command shelf placement in specialty retail. Blue Buffalo Co., Ltd. differentiates via limited-ingredient recipes targeting allergy-sensitive felines.
Cat food toppings comprise concentrated nutritional or flavor additives applied to base kibble or wet food, typically containing 15-40% crude protein with moisture levels varying by form from under 10% in dried formats to over 75% in gravy sauces. Their commercial purpose centers on palatability enhancement, micronutrient supplementation, and meal variety without complete diet replacement. Meat toppers occupy the dominant revenue position due to premium positioning and species-appropriate protein narratives, while gravy sauces represent the fastest-expanding form as convenience-seeking owners favor single-serve pouches over bulk formats. Dried formulations remain the margin pool leader given extended shelf stability and lower logistics costs.
USDA and FDA oversight governs ingredient safety and facility sanitation for products manufactured in the United States, while AAFCO nutritional adequacy guidelines shape formulation standards for products marketed as supplements rather than treats. The EU's Feed Hygiene Regulation and FEDIAF nutritional guidelines establish parallel compliance requirements for European distribution. Stakeholders must monitor evolving state-level packaging waste legislation and upcoming extended producer responsibility frameworks that will reshape pouch and tub material specifications.
Market Dynamics
Pet humanization is restructuring ingredient sourcing priorities as millennial and Gen Z cat owners reject commodity proteins in favor of traceable, functional nutrition inputs that mirror their own dietary standards.
Growth Catalysts
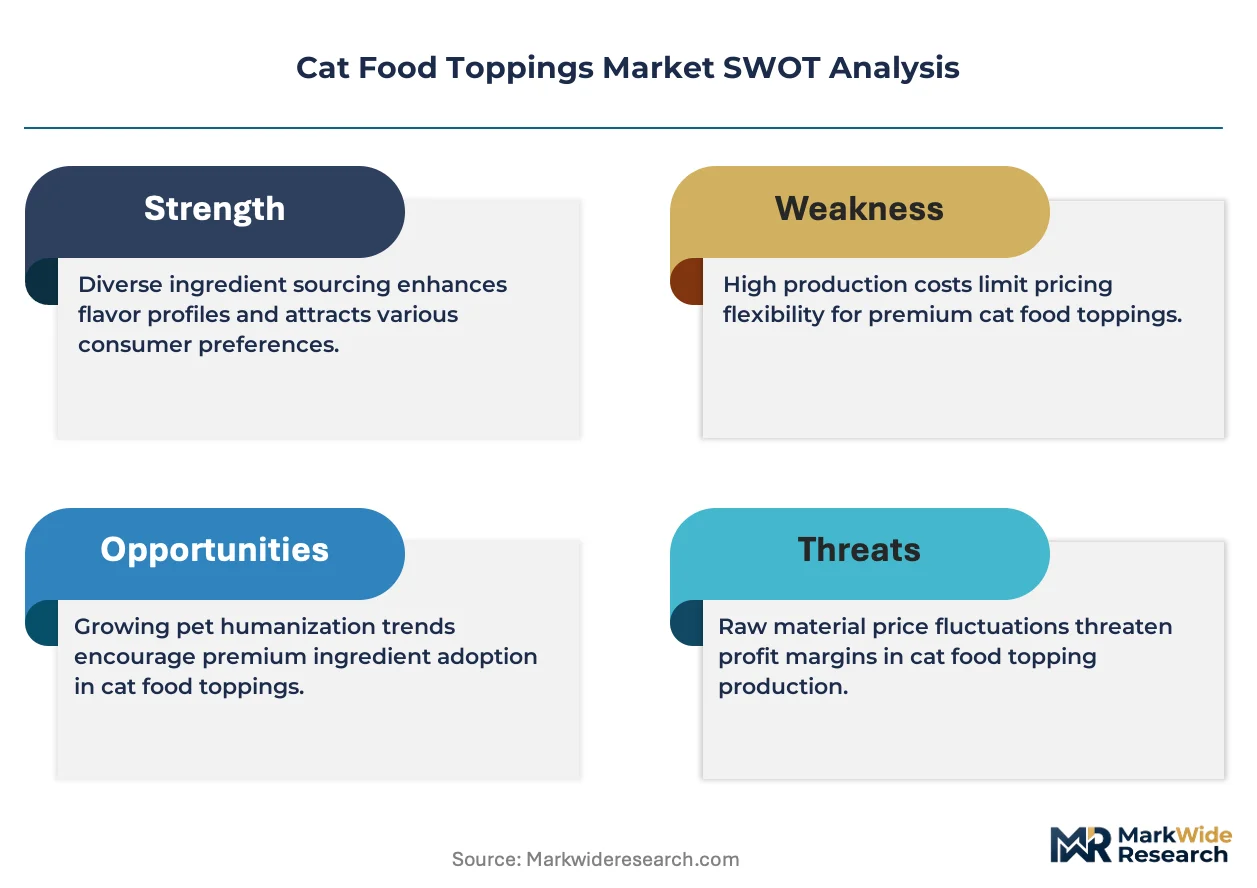
- Clean-label mandates:FEDIAF nutritional guidelines in Europe and AAFCO standards in the United States are pressuring manufacturers to eliminate artificial preservatives and disclose full ingredient provenance.
- Single-serve convenience:Urban apartment dwellers in Tokyo, London, and New York are gravitating toward portion-controlled gravy pouches that eliminate refrigeration waste and meal preparation friction.
- Veterinary endorsement channels:Specialty retail placement through clinic-affiliated stores is elevating therapeutic topper formulations targeting renal support and digestive health.
Market Restraints
- Animal protein cost volatility:Wild-caught fish and free-range poultry inputs face price instability tied to climate-impacted harvest cycles and feed grain inflation.
- Supply concentration risk:Premium collagen and novel protein sources (kangaroo, rabbit) depend on a narrow Australian and New Zealand supplier base vulnerable to export quota restrictions.
- Moisture-format logistics:Gravy and broth toppers above 75% moisture content incur refrigerated transport costs that compress margins versus shelf-stable dried alternatives.
Strategic Opportunities
- Insect protein scale-up:Black soldier fly larvae farming in the Netherlands and Canada offers a regulatory-compliant, low-carbon alternative to conventional livestock inputs.
- Extended producer responsibility tailwinds:EU packaging waste directives are accelerating demand for recyclable mono-material pouches that early movers can certify ahead of compliance deadlines.
- Veterinary telehealth integration:Subscription topper boxes paired with remote feline nutrition consultations are opening direct-to-consumer channels bypassing traditional retail slotting fees.
Industry Challenges
- Formulation talent scarcity:Veterinary nutritionists and food scientists with dual expertise in palatability chemistry and clinical micronutrient dosing command premium compensation that strains mid-tier manufacturer payrolls.
- Legacy equipment retrofitting:Transitioning from bulk dried topping production to aseptic liquid filling lines demands capital outlays that smaller facilities cannot amortize across limited SKU volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cat Food Toppings Market |
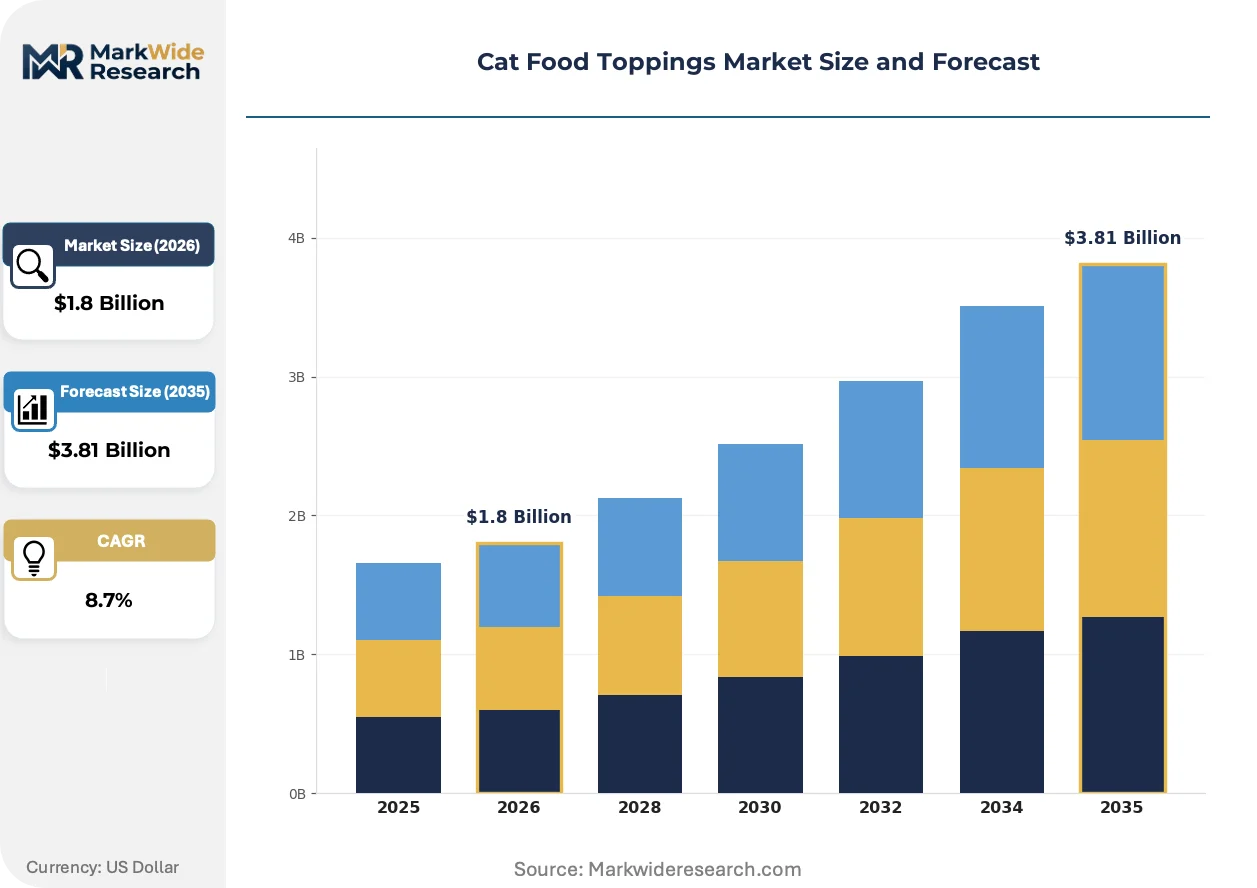
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meat Toppers, Vegetable Mixes, Seafood Enhancers, Gravy Sauces Form: Dried, Frozen, Canned, Powdered Packaging Type: Bags, Tubs, Pouches, Jars Use Case: Meal Enhancement, Nutritional Supplement, Flavor Booster, Treat Addition |
| Companies Covered | Blue Buffalo Co., Ltd., The Honest Kitchen, Nestlé Purina PetCare, Merrick Pet Care, Inc., Nature's Variety, Mars Incorporated, Stella & Chewy's, Castor & Pollux Natural Petworks, The J.M. Smucker Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cat Food Toppings Market Strategic Shifts
Biotechnology and packaging science are converging to redefine how functional ingredients reach feline consumers, with sustainability credentials now inseparable from product design decisions.
Precision fermentation is integrating lab-cultured animal proteins into topper formulations without slaughterhouse supply chains. Premium-positioned brands in Scandinavia and California are piloting these inputs for allergen-sensitive cats. This technology is compressing the traditional livestock-to-processor value chain into single-facility bioreactor operations.
The EU Green Deal's Farm to Fork Strategy is tightening maximum residue limits for pesticides in pet food ingredients. Manufacturers importing plant-based additives from third countries must now certify supply chain compliance through EFSA-recognized laboratories. Wet-format toppers with high botanical content face disproportionate testing burdens versus meat-dominant recipes.
Subscription bundling is displacing single-unit impulse purchases as the dominant acquisition model. Millennial cat owners in metropolitan Germany and the United Kingdom now expect auto-replenishment algorithms that adjust portion sizing based on veterinary weight management protocols. Specialty e-commerce platforms are capturing this demand through personalized nutrition quizzes that gate access to curated topper assortments.
Cat Food Toppings Market Segmentation
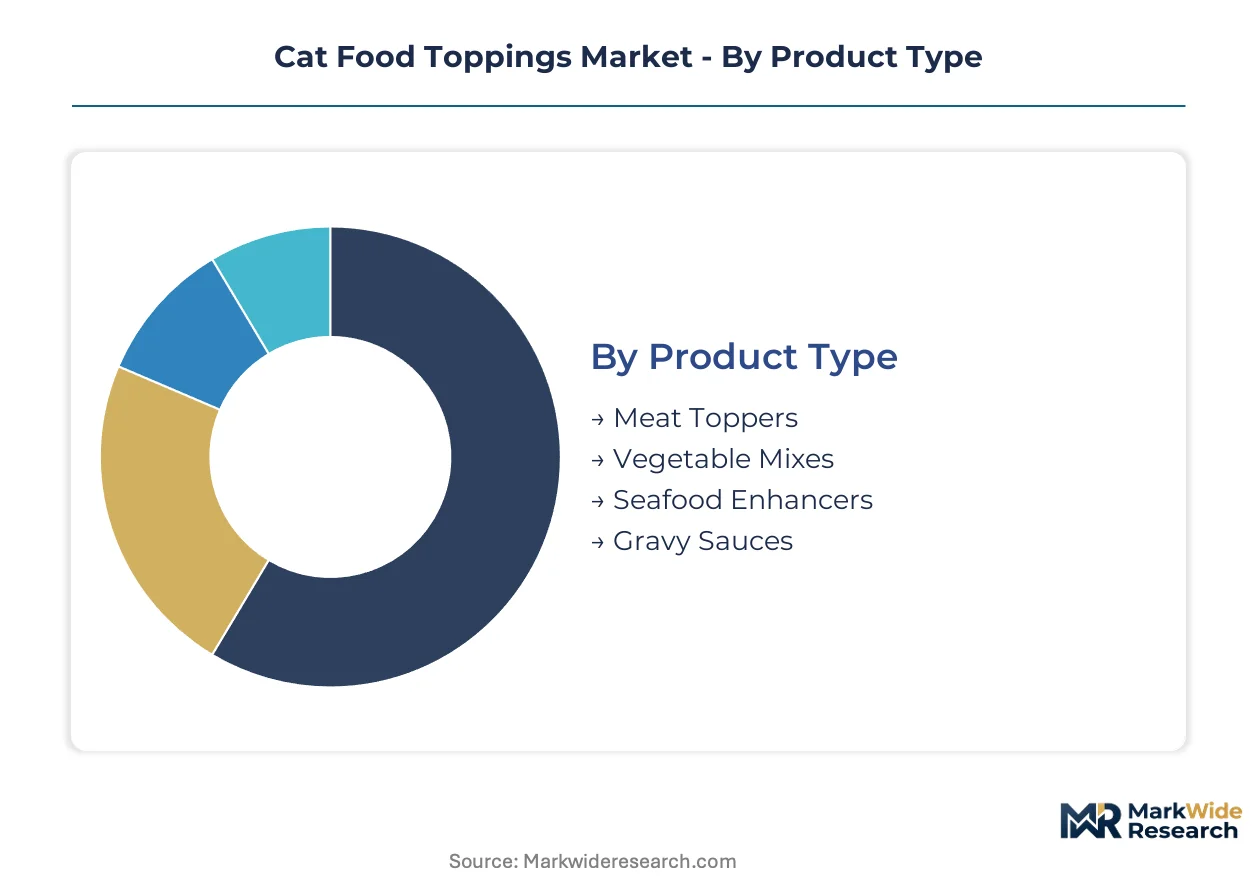
Cat food toppings manufacturers calibrate formulation, shelf stability, and portion formats against distinct owner behaviors. Understanding how urban millennial purchasers differ from multi-cat households or veterinary-directed buyers determines SKU rationalization and channel strategy.
Product Type:
Buyer willingness to pay premium prices varies sharply by protein narrative and perceived species-appropriateness.
- Meat Toppers:Concentrated muscle tissue or organ blends delivering 25-40% crude protein with minimal carbohydrate content. Demand concentrates among single-cat households in Germany and the United Kingdom where owners prioritize ancestral diet alignment over cost.
- Gravy Sauces:High-moisture liquid formats exceeding 75% water content, typically packaged in single-serve pouches for portion control. Urban apartment dwellers in Tokyo and New York favor these for refrigeration-free convenience despite per-ounce premiums over dried alternatives.
- Seafood Enhancers:Wild-caught or farmed fish derivatives rich in omega-3 fatty acids targeting coat health and cognitive function.
- Vegetable Mixes:Botanical blends incorporating pumpkin, sweet potato, or leafy greens for fiber supplementation and digestive regularity.
Meat toppers lead volumes today; gravy sauces are gaining share fastest.
Form:
Logistics infrastructure and retail channel requirements dictate form selection more than owner preference alone.
- Dried:Low-moisture extrusions or freeze-dried pieces with under 10% water content enabling ambient distribution. Mass-market retailers in the United States and France prioritize these for extended shelf life and reduced spoilage risk.
- Frozen:Raw or lightly cooked protein portions requiring cold chain maintenance from production through point-of-sale. Specialty pet boutiques in Canada and Australia stock these for raw-feeding enthusiasts accepting freezer storage trade-offs.
- Canned:Retort-sterilized wet products in metal containers offering 2-3 year ambient stability.
- Powdered:Fine-milled nutritional concentrates for dusting over kibble or reconstitution with water.
Dried formats dominate shelf space; frozen products show the steepest expansion trajectory among premium channels.
Packaging Type:
Extended producer responsibility legislation and e-commerce fulfillment constraints are reshaping material specifications.
- Pouches:Flexible multi-layer laminates enabling single-serve portioning with minimal material weight. E-commerce platforms in the United Kingdom and Netherlands favor these for shipping efficiency, though recyclability compliance with EU packaging waste directives demands mono-material innovation.
- Tubs:Rigid plastic containers with resealable lids for multi-serve wet products. German and French retailers specify these for gravity-fed shelf displays in hypermarket pet aisles.
- Bags:Stand-up or pillow pouches for bulk dried toppings targeting multi-cat households.
- Jars:Glass or PET containers conveying premium positioning for artisanal or limited-ingredient formulations.
Pouches lead new product launches; tubs retain the largest installed base in European mass retail.
Use Case:
Veterinary involvement and subscription commerce penetration vary dramatically by intended functional outcome.
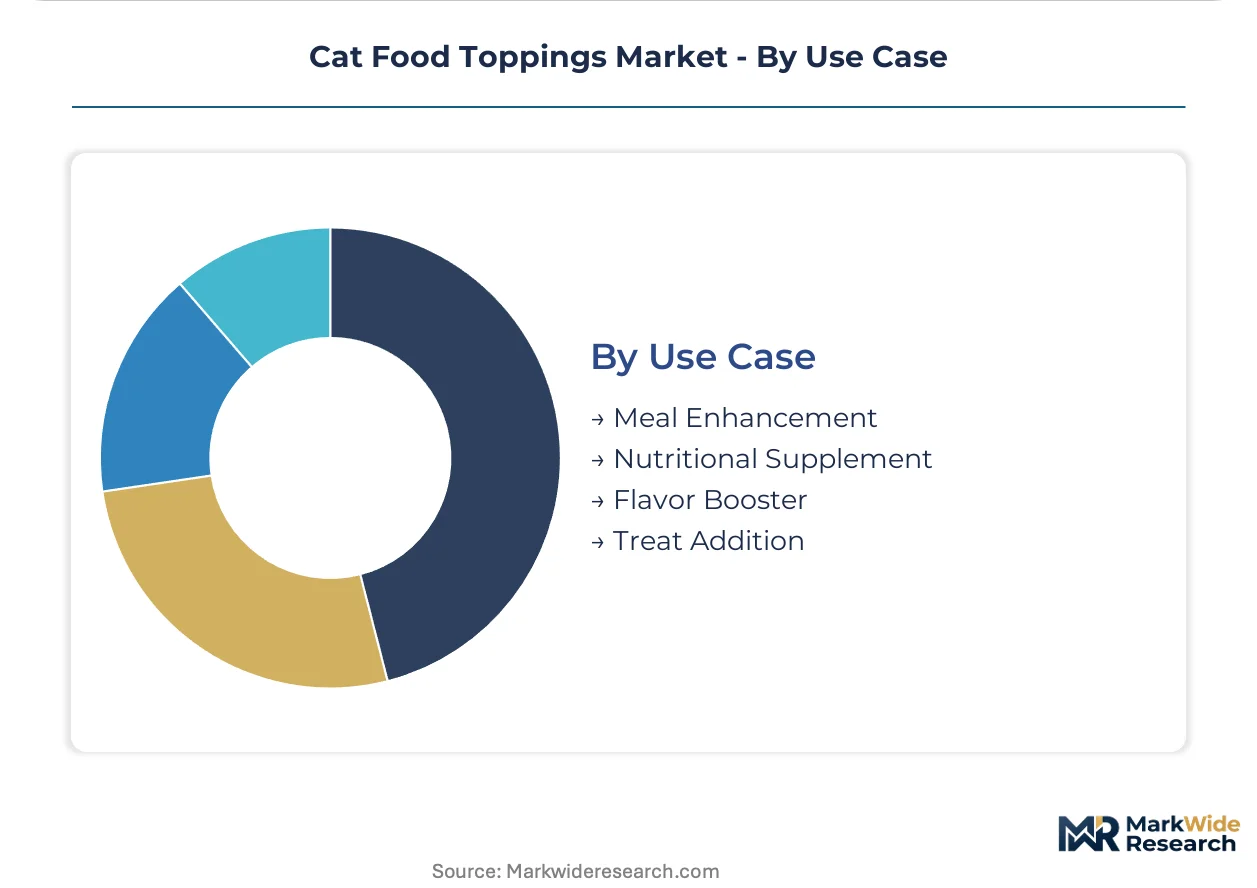
- Nutritional Supplement:Micronutrient-dense formulations addressing specific deficiencies or life-stage requirements. Clinic-affiliated retailers in the United States and Japan stock these for renal support, urinary health, and senior cat protocols with veterinary endorsement requirements.
- Meal Enhancement:Palatability-focused additions for finicky eaters or kibble-to-wet transitions. Subscription services in metropolitan United Kingdom and Germany algorithmically bundle these based on owner-reported acceptance rates.
- Flavor Booster:Aromatic concentrates designed to stimulate appetite in convalescing or stressed felines.
- Treat Addition:Occasional indulgence formats positioned outside daily feeding routines.
Nutritional supplements command the highest price points; meal enhancement applications show the fastest subscriber growth in direct-to-consumer channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity is migrating toward jurisdictions with lower compliance costs for aseptic liquid filling and cold-chain logistics. Manufacturers face divergent regulatory burdens across major demand centers.
United States
Millennial cat owners in Brooklyn and Austin drive subscription demand for functional toppers. FDA facility sanitation requirements and AAFCO nutritional guidelines govern interstate commerce. Kansas and Iowa host concentrated pet food manufacturing corridors where Nestlé Purina operates captive protein processing facilities.
Germany
Urban apartment dwellers in Berlin and Munich favor single-serve gravy pouches with extended producer responsibility-compliant packaging. FEDIAF nutritional guidelines and the EU Feed Hygiene Regulation shape formulation standards. The Bavarian industrial belt clusters specialist aseptic filling equipment suppliers serving premium pet food brands.
Japan
Tokyo's dense metropolitan cat owners prioritize convenience formats with minimal refrigeration requirements. The Ministry of Agriculture, Forestry and Fisheries enforces strict import protocols for animal-derived ingredients. Osaka-Kobe manufacturing zones concentrate retort-sterilization capacity for high-moisture wet products.
United Kingdom
Metropolitan London and Manchester consumers exhibit strong demand for veterinary-endorsed therapeutic formulations. Post-Brexit UK REACH and retained EU feed regulations create dual compliance obligations. The East Midlands logistics corridor serves as the primary distribution hub for direct-to-consumer subscription fulfillment.
Australia
Sydney and Melbourne raw-feeding enthusiasts sustain demand for frozen protein portions despite cold-chain costs. The Department of Agriculture, Water and the Environment administers biosecurity controls on novel protein imports. Victorian manufacturing zones specialize in kangaroo and rabbit protein processing for allergen-sensitive formulations.
Cat Food Toppings Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue precision fermentation and insect protein alternatives. The market exhibits moderate concentration with three to four multinational conglomerates controlling mass retail shelf space alongside numerous regional specialists. Strategic archetypes include captive supply chain operators, veterinary-channel specialists, and limited-ingredient pure-play brands. Dominant competitive moves encompass backward integration into protein processing and portfolio diversification across moisture formats.
Among North American-based operators, Nestlé Purina PetCare and Mars Incorporated exemplify scale-driven archetypes with integrated supply chain control. Blue Buffalo Co., Ltd. occupies a position within the premium limited-ingredient specialist tier, representing the allergy-focused formulation strategy.
| Leading Market Players |
|---|
| Blue Buffalo Co., Ltd. |
| The Honest Kitchen |
| Nestlé Purina PetCare |
| Merrick Pet Care, Inc. |
| Nature's Variety |
| Mars Incorporated |
| Stella & Chewy's |
| Castor & Pollux Natural Petworks |
| The J.M. Smucker Company |
| Others |
Value Chain & Pricing Dynamics
Clean-label certification tiers split the Cat Food Toppings Market into divergent supply chain configurations, with AAFCO-compliant and FEDIAF-registered formulations commanding upstream protein sourcing premiums while commodity-grade alternatives draw from spot-market inputs with thinner traceability documentation. This bifurcation concentrates margin capture among veterinary-endorsed brands with captive supply chains while compressing returns for private-label assemblers dependent on third-party ingredient brokers.
Pricing Analysis
Distributor margins of 18-25% separate mass-market retail from specialty clinic channels, with subscription direct-to-consumer models bypassing this layer entirely. Three-tier pricing structure across premium, standard, and economy levels reflects protein provenance depth and veterinary endorsement status. Cost compression in gravy-format segments intensifies because refrigerated logistics erode per-unit economics versus ambient-stable dried alternatives. Multi-cat households in suburban United States exhibit highest price sensitivity, while single-cat urban owners in Tokyo and Berlin accept per-ounce premiums for convenience packaging.
Supply Chain Analysis
Returns and expired-product flows from e-commerce subscription services are forcing reverse-logistics investments that legacy bulk-format manufacturers never contemplated. Protein sourcing concentrates in United States, Australia, and New Zealand, with novel inputs like kangaroo and rabbit tethered to export quota regimes. Black soldier fly larvae and precision-fermentation alternatives draw from pilot facilities in Netherlands and Canada. Single-source vulnerability in wild-caught fish inputs exposes formulations to climate-impacted harvest volatility. Distribution runs through pet specialty retail, veterinary clinic affiliates, and direct-to-consumer platforms with divergent fulfillment infrastructure requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Cat Food Toppings Market functions as a geographic-arbitrage play where manufacturers locate aseptic liquid filling capacity in Germany's Bavarian industrial belt to access lower compliance costs than United States FDA facility requirements while retaining EU market access.
For Market Incumbents: Cement supply security through backward integration into protein processing or long-term offtake agreements with Australian and New Zealand novel protein suppliers. Capacity expansion in Kansas and Iowa corridors leverages existing Nestlé Purina captive infrastructure. Certification investment in EU Green Deal packaging compliance creates defensive moats against mid-tier competitors lacking amortization scale for mono-material pouch transitions. For New Entrants and Emerging Players: Veterinary telehealth subscription bundling offers the most penetrable route for bypassing traditional retail slotting fees. Target renal support and digestive health therapeutic formulations where incumbent portfolios remain thin. Precision fermentation partnerships with Scandinavian or California bioreactor operators provide differentiated allergen-sensitive positioning without slaughterhouse supply chain capital requirements. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier manufacturers face stranded asset risk from legacy bulk dried equipment incompatible with aseptic liquid filling transitions. Long-term viability favors specialists with dual expertise in palatability chemistry and clinical micronutrient dosing. Signal to watch: state-level extended producer responsibility legislation adoption rates that accelerate packaging compliance cost disparities between integrated and non-integrated players.| Strategic Initiative | Industry Significance |
|---|---|
| Insect Protein Scale-Up | Black soldier fly larvae farming in Netherlands and Canada offers regulatory-compliant, low-carbon alternative inputs. |
| Mono-Material Packaging Transition | EU packaging waste directives accelerate demand for recyclable pouches certifiable ahead of compliance deadlines. |
| Veterinary Telehealth Integration | Subscription topper boxes paired with remote feline nutrition consultations bypass traditional retail slotting fees. |
| Precision Fermentation Partnerships | Lab-cultured animal proteins from Scandinavian and California bioreactors compress livestock-to-processor value chains. |
| Aseptic Liquid Filling Capacity | Germany's Bavarian industrial belt clusters specialist equipment suppliers serving premium pet food brands. |
Study Parameters
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combining executive interviews with pet food formulation scientists, veterinary nutritionists, specialty retail category buyers, and cold-chain logistics operators. Secondary validation draws from FDA facility inspection records, FEDIAF nutritional guideline publications, EU Feed Hygiene Regulation compliance databases, and trade customs data for protein ingredient flows. Bottom-up SKU-level volume estimates and top-down category spend analysis undergo iterative triangulation against manufacturer capacity disclosures.
Rate-of-change decomposition separates volume growth from mix-shift effects and pricing trajectory components across the projection horizon. Segmentation dimensions include protein source type, moisture format, packaging material, distribution channel, and functional use case. CAGRs derive from regression against pet ownership demographics, urbanization indices, and veterinary service utilization rates. Forecast inputs incorporate extended producer responsibility implementation timelines and precision fermentation regulatory approval pathways.
The model assumes a particular technology adoption path; alternative pathways for insect protein and lab-cultured inputs would alter the outlook if regulatory approval accelerates or consumer acceptance lags. Forecasts reflect assumptions about clean-label mandate enforcement consistency and cold-chain infrastructure investment continuity. Practitioners should monitor EU packaging waste directive enforcement intensity and veterinary telehealth reimbursement policy shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Vegetarian Taquitos Market
Specialty Foods
Global Honey Market
Specialty Foods
Curculin Market
Specialty Foods
Low Calorie Diet Meal Plan Market
Specialty Foods
Wet Grain-Free Pet Food Market
Specialty Foods
Almond-Based Spreads Market
Specialty Foods
Halal Foods Market
Specialty Foods
Maple Syrup Market
Specialty Foods
Keto Low-Calorie Meals Market
Specialty Foods
Low Calorie Veggie Dip Market
Specialty Foods
Middle East and Africa Free-From Food Market
Specialty Foods
Middle East and Africa Hummus Market
Specialty Foods
Cultures Market
Specialty Foods
Gluten-Free Desserts and Ice Creams Market
Specialty Foods
North America Alcohol-Infused Ice Cream Market
Specialty Foods
US Jam Jelly and Preserves Market