
 Grain Free Dog Food Market | 2026-2036
Grain Free Dog Food Market Size, Share, and Industry Trends Forecast 2026-2036
Grain Free Dog Food Market Analytics
Asset-light contract manufacturing and third-party co-packing is rewriting competitive economics in grain-free dog food, allowing challenger brands to scale without capital-intensive plant investments. Mars Incorporated leverages its global procurement infrastructure to sustain ingredient cost advantages across multiple protein sources. Diamond Pet Foods anchors North American production capacity through company-owned facilities in Missouri and South Carolina. WellPet LLC specializes in limited-ingredient recipes that differentiate its portfolio within premium independent pet specialty channels.
Grain-free dog food excludes cereal grains such as wheat, corn, rice, and barley, substituting alternative carbohydrate sources like sweet potatoes, peas, lentils, or tapioca to achieve target macronutrient profiles while maintaining extrusion stability during high-pressure thermal processing. The category serves pet owners seeking to address perceived food sensitivities, digestive tolerance issues, or species-appropriate nutritional philosophies in companion animals. Dry food occupies the dominant volume position due to shelf stability and lower per-feeding cost, though freeze-dried formats command the most favorable unit economics and fastest growth trajectory among discerning buyers. Wet food in pouch packaging captures recurring subscription revenue through portion-controlled convenience, while bulk sizing in meat-based formulations concentrates margin pools with multi-dog households.
The FDA's Center for Veterinary Medicine scrutinizes grain-free formulations containing peas, lentils, or potatoes for potential associations with canine dilated cardiomyopathy, compelling reformulation investments and expanded taurine supplementation protocols. AAFCO nutrient profiles and state-level feed control officials enforce minimum labeling and safety standards that shape product claims and market access across the United States. Pet food manufacturers must monitor evolving veterinary research, anticipated FDA guidance refinement, and shifting retailer certification requirements to align R&D priorities with emerging compliance thresholds.
Market Dynamics
The FDA's ongoing investigation into grain-free diets and canine dilated cardiomyopathy is forcing wholesale reformulation across the category, compelling manufacturers to restructure ingredient sourcing and taurine supplementation protocols while defending shelf positioning in specialty retail.
Growth Catalysts
- Millennial Urban Premiumization:Dense metropolitan pet ownership in Austin, Seattle, and Denver concentrates demand for limited-ingredient recipes with transparent supply chains.
- AAFCO Nutrient Profile Enforcement:State-level feed control officials across the United States are tightening labeling standards that favor substantiated functional claims over marketing language.
- Freeze-Dried Format Adoption:Raw-coated kibble and air-dried meat preservation technologies capture margin migration from conventional extrusion toward higher-ASP formats.
Market Restraints
- Pulse Ingredient Scrutiny:Peas, lentils, and potatoes face veterinary research questioning their cardiac safety profile, elevating R&D costs for existing formulations.
- Midwest Production Concentration:Missouri and South Carolina facilities anchor North American extrusion capacity, creating geographic vulnerability to weather and logistics disruptions.
- Veterinary Distrust:Board-certified veterinary nutritionists increasingly counsel clients away from grain-free positioning, constraining professional endorsement channels.
Strategic Opportunities
- Direct-to-Consumer Subscription Models:Chewy and independent platforms capture recurring revenue through auto-ship algorithms that reduce customer acquisition costs.
- Taurine-Fortified Positioning:Proactive supplementation protocols anticipate refined FDA guidance, creating first-mover compliance advantages.
- Novel Protein Expansion:Insect meal and cultivated protein sources address sustainability-motivated buyers in California and New York metro corridors.
Industry Challenges
- Formulation Talent Scarcity:Veterinary nutrition PhDs and extrusion process engineers command premium compensation, constraining mid-tier manufacturer R&D bandwidth.
- Legacy Equipment Retrofit Costs:Existing high-pressure thermal processing lines require capital-intensive modification to handle alternative carbohydrate rheology.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grain Free Dog Food Market |
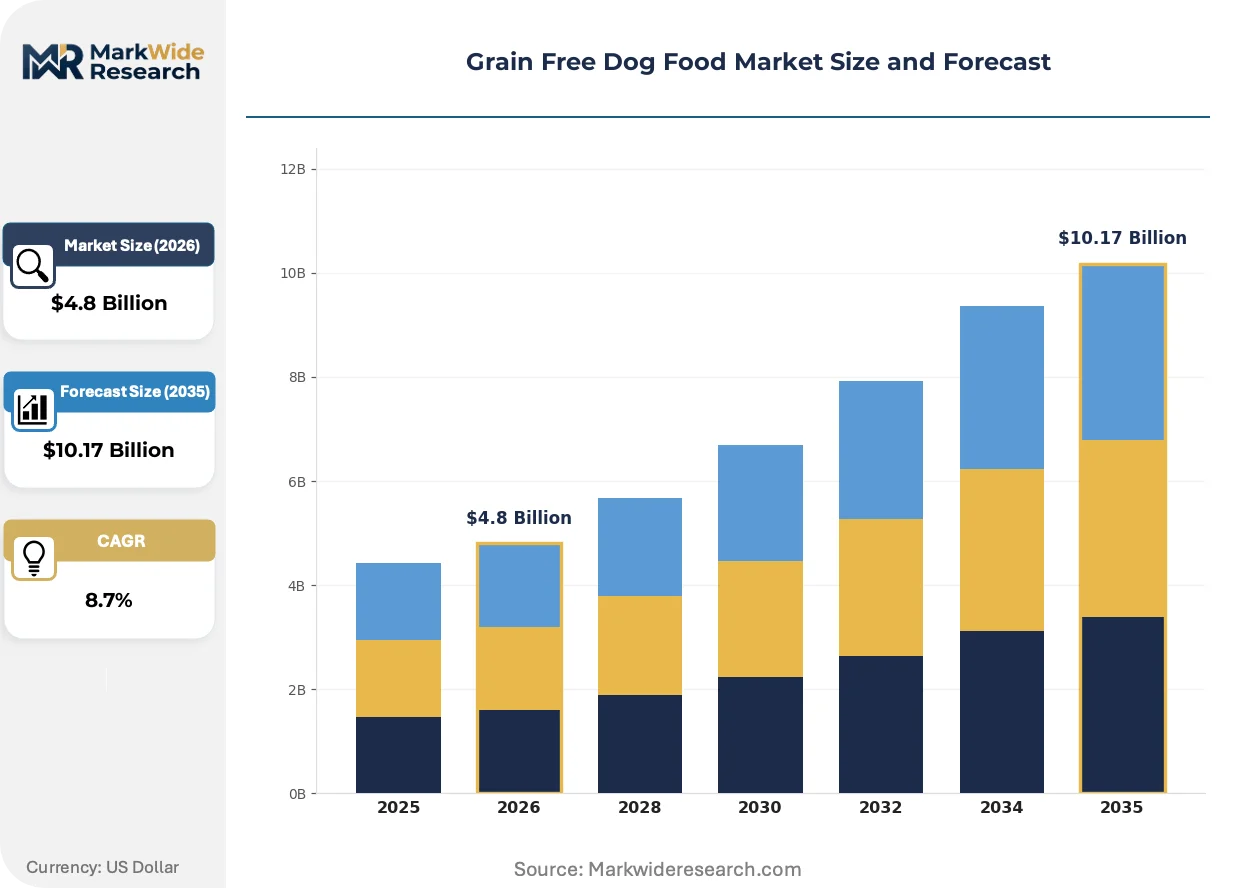
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Food, Dry Food, Freeze-Dried, Treats Main Ingredient: Meat, Fish, Vegetables, Fruits Size: Small Bags, Medium Bags, Large Bags, Bulk Packaging Type: Box, Bag, Can, Pouch |
| Companies Covered | J.M. Smucker Company, Diamond Pet Foods, Mars Incorporated, WellPet LLC, Champion Petfoods, Nestlé Purina PetCare, Blue Buffalo Co. Ltd., Spectrum Brands Holdings Inc., General Mills Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grain Free Dog Food Market Evolving Landscape
Reformulation pressure from veterinary cardiology research is compressing development timelines and collapsing traditional ingredient hierarchies, while digital-native distribution models bypass legacy wholesale structures entirely.
Cold-pressed extrusion technology is collapsing the temperature differential between conventional high-heat processing and raw nutritional preservation. Boutique manufacturers in Colorado and Oregon adopt these systems to serve raw-feeding converts unwilling to handle frozen product. The capital barrier between artisan positioning and industrial scale is collapsing as contract manufacturers deploy modular equipment configurations.
The FDA Center for Veterinary Medicine's July 2018 public notification on diet-associated DCM triggered cascading compliance investments across the industry. Manufacturers must now maintain batch-level taurine assay records and veterinary consultation documentation. Small brands lacking regulatory affairs infrastructure face disproportionate documentation burdens relative to their revenue base.
Subscription auto-ship algorithms now displace periodic retail replenishment among urban millennial households. Chewy's predictive reordering and independent platform loyalty programs capture lifetime value through convenience lock-in. California and Washington metropolitan statistical areas exhibit the highest subscription penetration rates, correlating with dual-income households and premium price acceptance.
Grain Free Dog Food Market Segmentation
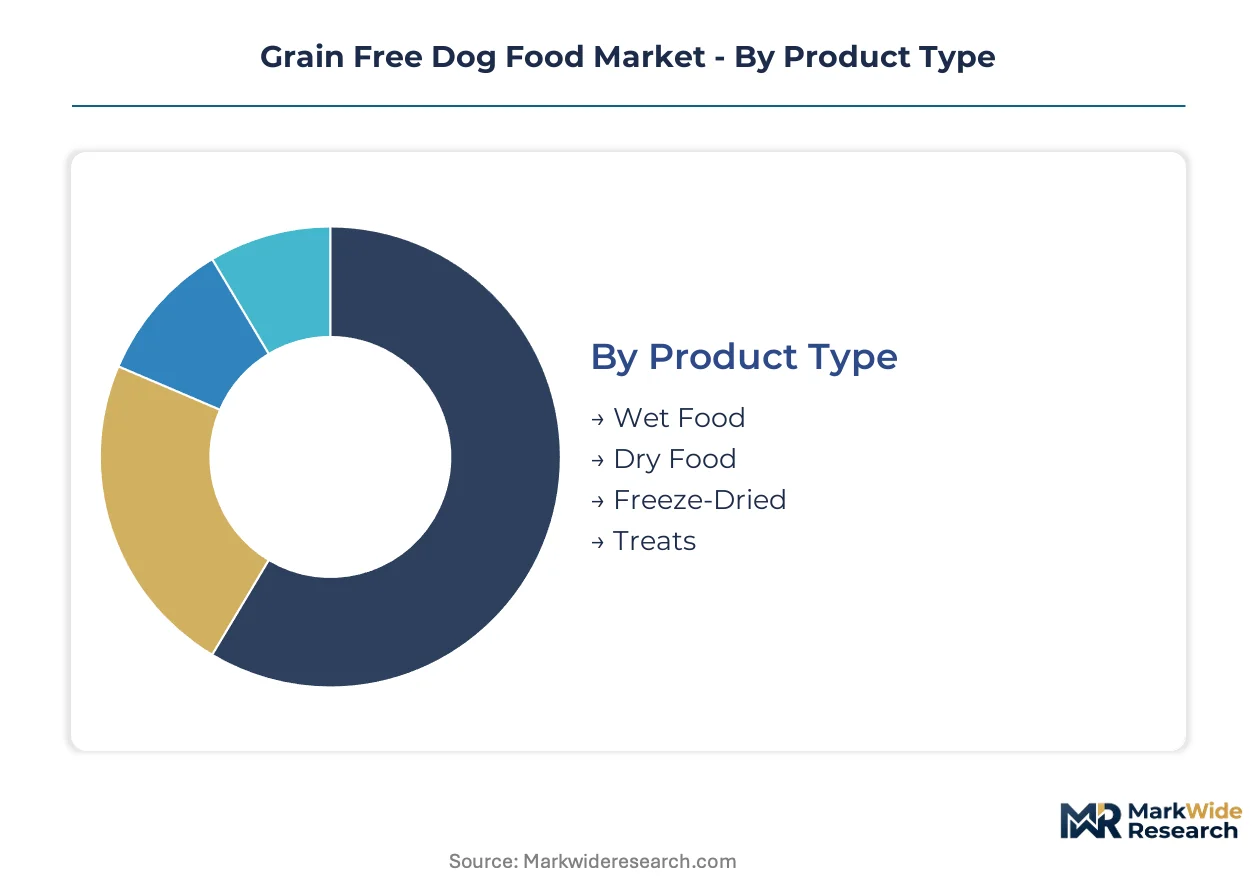
Grain-free dog food manufacturers structure portfolios around feeding occasion, ingredient philosophy, household scale, and retail channel requirements. Each segmentation dimension carries distinct margin profiles, formulation constraints, and customer acquisition economics that shape resource allocation across R&D and marketing functions.
Product Type:
Cost tier stratification separates convenience-driven formats from premium preservation technologies with divergent capital intensity and shelf-life engineering.
- Dry Food:Extruded kibble with alternative carbohydrate binders like sweet potatoes or peas achieves 12-18 month shelf stability through moisture reduction below 10%. Multi-dog households in suburban Texas and Florida metro areas concentrate volume due to per-pound cost efficiency and storage convenience. This segment anchors manufacturer revenue bases despite compressed margins from commodity protein sourcing cycles.
- Freeze-Dried:Sublimation dehydration preserves raw nutritional integrity while eliminating frozen supply chain requirements. Discerning owners in Seattle, Denver, and Austin premium pet boutiques drive adoption, accepting 4-8x per-serving cost premiums for perceived bioavailability advantages. This format is climbing the fastest among urban millennial subscribers seeking raw nutritional benefits without freezer logistics.
- Wet Food:Retort-processed meat formulations in gravy or pâté textures address palatability concerns and hydration support for senior dogs or medical dietary management.
- Treats:Limited-ingredient biscuits, jerky strips, and training rewards extend grain-free positioning into intermittent feeding occasions with impulse-purchase retail dynamics.
Dry food holds installed capacity. Freeze-dried is rotating up the share rankings.
Main Ingredient:
Application focus determines protein sourcing strategy, with species-appropriate nutritional philosophies and allergy management protocols driving ingredient selection.
- Meat:Beef, chicken, turkey, and lamb meals provide complete amino acid profiles with established supply chain infrastructure. Conventional livestock proteins face sustainability scrutiny from California and New York metro buyers, pressuring manufacturers toward certified sourcing disclosures. AAFCO nutritional adequacy protocols favor meat-first formulations for substantiated complete-and-balanced claims.
- Fish:Salmon, whitefish, and novel marine proteins deliver omega-3 fatty acid positioning for coat health and inflammatory modulation. Pacific Northwest coastal markets and Florida retirement communities concentrate demand for fish-forward recipes. Veterinary dermatology recommendations reinforce prescription-tier adoption for atopic skin conditions.
- Vegetables:Sweet potatoes, peas, and lentils substitute cereal grains as carbohydrate sources while contributing fiber and micronutrients to macronutrient profiles.
- Fruits:Blueberries, cranberries, and apples appear in limited quantities for antioxidant marketing claims and palatability enhancement in premium positioning.
Meat-based formulations command formulation talent concentration. Fish is gaining share fastest among coastal veterinary channels.
Size:
Customer type segmentation aligns packaging economics with household penetration, purchase frequency, and storage capacity constraints.
- Large Bags:25-30 pound multi-week supply formats minimize per-pound packaging and shipping costs for established brand loyalty. Households with two or more large-breed dogs in suburban Phoenix, Atlanta, and Dallas-Fort Worth drive replenishment velocity through subscription auto-ship programs. Bulk sizing concentrates margin pools with customer lifetime value optimization.
- Small Bags:4-6 pound trial sizes and toy-breed portions reduce purchase risk for new customer acquisition and breed-specific formulations. Urban apartment dwellers in Boston, Chicago, and San Francisco with single small dogs favor portion-appropriate sizing. This segment expands most quickly through veterinary recommendation samples and breed club direct marketing.
- Medium Bags:12-15 pound configurations balance storage convenience with per-pound value for mid-size single-dog households.
- Bulk:40+ pound commercial or multi-pet professional formats serve breeders, shelters, and working dog kennels with minimal packaging overhead.
Large bags hold installed capacity. Small bags is rotating up the share rankings.
Packaging Type:
Supply concentration in flexible materials versus rigid formats reflects channel requirements, shelf differentiation, and sustainability positioning tradeoffs.
- Bag:Multi-layer flexible films with oxygen barrier properties dominate dry food retail presentation, supporting high-resolution printing for brand storytelling. Specialty pet retail chains and mass-market club stores in the United States standardize on bag formats for pallet efficiency and shelf-ready display. Recyclability and post-consumer content claims increasingly influence material specification decisions.
- Pouch:Stand-up and flat retort pouches capture wet food and fresh-refrigerated segments with portion-controlled convenience. Subscription platforms like Chewy optimize pouch configurations for dimensional shipping weight efficiency. This format is expanding most quickly among urban auto-ship subscribers prioritizing refrigerator space and serving precision.
- Can:Steel and aluminum cylindrical containers preserve wet food through thermal processing, carrying legacy veterinary prescription channel expectations.
- Box:Paperboard cartons contain multi-pouch variety packs or treat assortments, enabling gift positioning and trial bundling strategies.
Bags hold installed capacity. Pouches are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US FDA scrutiny of grain-free formulations and canine dilated cardiomyopathy associations is driving reformulation investments across North American manufacturing bases. European pet food regulations under EFSA guidance are tightening novel protein approval pathways. Asian markets are accelerating premium pet nutrition adoption through urban middle-class expansion.
United States
Millennial pet ownership in Austin, Seattle, and Denver concentrates demand for limited-ingredient recipes with transparent supply chains. FDA Center for Veterinary Medicine maintains active investigation protocols requiring batch-level taurine documentation from manufacturers. Missouri and South Carolina host the dominant extrusion capacity for North American grain-free production.
Canada
Health Canada and the Canadian Food Inspection Agency enforce parallel pet food safety standards that facilitate cross-border formulation consistency with US markets. Toronto and Vancouver metropolitan areas exhibit premium pet food subscription penetration rates matching US coastal cities. Alberta-based ingredient suppliers are expanding pulse protein processing for pet food applications.
Germany
EFSA novel food regulations shape approval timelines for insect protein and cultivated meat ingredients entering European grain-free formulations. Munich and Hamburg anchor specialty pet retail chains demanding certified sustainable sourcing disclosures. German veterinary nutritionists increasingly counsel clients toward evidence-based dietary selection over marketing-driven grain-free positioning.
United Kingdom
London and Southeast England concentrate demand for freeze-dried and air-dried formats among urban professional households. The Food Standards Agency and DEFRA enforce pet food labeling standards that favor substantiated nutritional claims. UK-based direct-to-consumer platforms are capturing recurring revenue through predictive auto-ship algorithms.
Australia
Sydney and Melbourne metropolitan statistical areas drive premium grain-free adoption through high disposable income households and veterinary dermatology recommendations. The Australian Pesticides and Veterinary Medicines Authority regulates ingredient safety standards for imported and domestic pet food manufacturing. Queensland-based meat processors are expanding co-packing capacity for boutique grain-free brands.
Grain Free Dog Food Market Competitive Landscape
On the supply side, the industry is consolidating around diversified consumer packaged goods conglomerates with captive pet food divisions and independent specialists with veterinary channel positioning. The competitive terrain separates multinational nutrition platforms with global procurement infrastructure from mid-tier contract manufacturers serving private-label and challenger brand portfolios. Two dominant strategic archetypes prevail: vertically integrated ingredient-to-shelf operators and asset-light brand marketers leveraging third-party co-packing. Competitive moves concentrate on M&A-driven portfolio diversification into veterinary prescription channels and cold-pressed extrusion technology licensing agreements.
Within the multinational nutrition platform tier, Mars Incorporated and Nestlé Purina PetCare exemplify scale-driven competitive positioning through global supply chain leverage and veterinary research partnerships. Among North American specialists, Diamond Pet Foods and WellPet LLC occupy positions emphasizing company-owned manufacturing control and limited-ingredient formulation expertise respectively. These named entities represent the structural spectrum from diversified conglomerate pet divisions to focused independent operators navigating FDA compliance requirements.
| Leading Market Players |
|---|
| J.M. Smucker Company |
| Diamond Pet Foods |
| Mars Incorporated |
| WellPet LLC |
| Champion Petfoods |
| Nestlé Purina PetCare |
| Blue Buffalo Co. Ltd. |
| Spectrum Brands Holdings Inc. |
| General Mills Inc. |
| Others |
Value Network & Pricing Analysis
FDA Center for Veterinary Medicine scrutiny of pulse ingredient cardiac safety compresses both pricing tier spreads and supply chain configuration, forcing manufacturers to absorb taurine supplementation costs while defending shelf positioning against reformulation-driven margin erosion.
Pricing Analysis
Certification level creates the primary spread across freeze-dried, dry kibble, and wet food tiers, with AAFCO nutritional adequacy protocols commanding premium positioning over state-level minimum compliance. Brand equity from veterinary endorsement channels supports 15-40% price elevation against private-label alternatives. Cost compression in mid-tier extruded kibble intensifies as Missouri and South Carolina production capacity faces weather-related disruption risk. Multi-dog households in suburban Texas and Florida exhibit lowest price sensitivity, while urban apartment dwellers in Boston and Chicago demonstrate highest trial-size purchase elasticity.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now characterize ingredient procurement from Alberta pulse processors and Midwest meat meal suppliers, straining working capital for mid-tier manufacturers. Raw material sourcing draws from Canadian pea protein facilities, domestic rendered protein operations, and Pacific Northwest fish meal processors. Single-source vulnerability concentrates in Missouri extrusion capacity and South Carolina thermal processing infrastructure. Distribution runs through Chewy's fulfillment network, specialty pet retail chains, and veterinary prescription channels with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around FDA taurine documentation requirements creates defensive moats for manufacturers with established quality infrastructure and veterinary affairs capabilities.
For Market Incumbents: Build compliance documentation moats through batch-level taurine assay protocols and veterinary consultation records that smaller competitors cannot replicate without disproportionate overhead. Diamond Pet Foods and Mars Incorporated should anchor capacity control through equipment retrofit investments in Missouri facilities. Champion Petfoods can defend margin position by locking specialty retail shelf space through exclusive distribution arrangements before FDA guidance refinement accelerates.
For New Entrants and Emerging Players: Mid-market freeze-dried formats in Seattle and Denver represent the most penetrable entry point, as capital barriers collapse through contract manufacturing partnerships with Colorado cold-pressed extrusion specialists. Novel protein positioning using insect meal or cultivated sources addresses sustainability-motivated buyers in California metro corridors with premium price acceptance. Direct-to-consumer subscription platforms enable customer acquisition without legacy wholesale margin surrender.
For Investors and Strategic Acquirers: Anticipated FDA guidance refinement on DCM associations reshapes the acquisition landscape toward targets with proactive taurine fortification protocols and established veterinary channel relationships. Five-to-ten year viability favors contract manufacturers with modular equipment configurations serving multiple brand portfolios. The signal to watch is FDA publication of refined pulse ingredient safety thresholds, which would trigger accelerated consolidation among documentation-deficient mid-tier players.
| Strategic Initiative | Industry Significance |
|---|---|
| Taurine-Fortified Reformulation | Proactive supplementation anticipates FDA guidance, creating compliance advantages for early movers. |
| Cold-Pressed Extrusion Licensing | Technology partnerships with Colorado equipment vendors collapse temperature differentials for raw-feeding converts. |
| Direct-to-Consumer Platform Launch | Chewy-competing auto-ship algorithms capture lifetime value through convenience lock-in among urban millennials. |
| Novel Protein Supply Agreement | Insect meal partnerships with Alberta processors address sustainability positioning for California and New York buyers. |
| Veterinary Channel Partnership | Board-certified nutritionist endorsement programs counter professional distrust of grain-free positioning. |
Research Methodology
Cross-validation between primary interviews with pet food formulation scientists, veterinary nutritionists, specialty retail category buyers, and contract manufacturing executives anchors the qualitative findings against secondary validation from FDA Center for Veterinary Medicine filings, AAFCO meeting minutes, state feed control official enforcement records, and Chewy SEC disclosures. Bottom-up demand modeling from household pet ownership demographics and top-down supply analysis from Missouri and South Carolina production capacity triangulate volume estimates across the analysis window.
Calibration against historical pricing data from Nielsen retail audits and customs records for pea protein and fish meal imports refines segment-level projections. The analytical framework models product type, main ingredient philosophy, packaging format, household scale, and regional regulatory cluster across the projection horizon. CAGRs derive from elasticity-adjusted adoption curves for freeze-dried formats and subscription penetration rates in metropolitan statistical areas. Veterinary recommendation intensity and FDA investigation timeline progression serve as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in disposable income growth among millennial households or tariff exposure on Canadian pulse ingredients would shift the trajectory. Forecasts reflect documented assumptions about regulatory timeline progression and veterinary professional sentiment evolution. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Tunisia Couscous Market
Specialty Foods
Mexico Guacamole Market
Specialty Foods
Global Pine Pollen Market
Specialty Foods
Asia-Pacific Alcohol-Infused Ice Cream Market
Specialty Foods
Cat Food Toppings Market
Specialty Foods
High Protein Cat Food Market
Specialty Foods
Global Bee Products Market
Specialty Foods
Cat Food Flavors Market
Specialty Foods
US Jam Jelly and Preserves Market
Specialty Foods
Marine Thermal Water Ferments Market
Specialty Foods
Foie Gras Market
Specialty Foods
North America Alcohol-Infused Ice Cream Market
Specialty Foods
Global Truffle Market
Specialty Foods
Vegetarian Taquitos Market
Specialty Foods
Cannabis Infused Drinks Market
Specialty Foods
Acacia Honey Market