
 Selenium Mining Market | 2026-2036
Selenium Mining Market Size, Share, and Industry Trends Forecast 2026-2036
Selenium Mining Market Insights
Market Context
Tellurium is rebalancing selenium product economics in thin-film photovoltaic applications, pressuring refiners to optimize co-product recovery ratios. JX Nippon Mining & Metals leverages its integrated copper-smelting footprint to sustain captive selenium output across Japanese and overseas facilities. Dowa Holdings anchors its position through advanced hydrometallurgical refining capabilities at its Kosaka complex. Sumitomo Metal Mining competes by controlling access to high-grade anode slime streams from its domestic and international copper operations.
Technical Definition and Segment Structure
Selenium mining encompasses the extraction and recovery of selenium, a chalcogen element with atomic number 34 typically produced as a byproduct of copper, lead, and nickel refining, with commercial grades ranging from 99.5% to 99.999% purity depending on end-use specifications. The element serves primarily as a metallurgical additive, glass decolorizer, and precursor in semiconductor and photovoltaic manufacturing. Open pit mining dominates upstream volume due to its association with large-scale porphyry copper deposits, while underground mining yields higher selenium concentrations in certain polymetallic veins. Metallic selenium and selenium dioxide command the deepest margin pools within product form segmentation, reflecting purification intensity and electronics-grade certification requirements.
Regulatory Environment
EPA hazardous waste rules govern selenium-containing slag and effluent discharge from U.S. refiners, while REACH registration obligations in Europe impose full substance dossiers on selenium dioxide and metallic selenium importers. China's MEE enforces emissions caps on non-ferrous smelters that indirectly constrain selenium byproduct availability. Stakeholders must monitor how evolving battery-grade material specifications and solar panel efficiency standards redirect selenium demand between competing end-use claims.
Market Dynamics
Copper smelter output constraints in China are tightening selenium byproduct availability, forcing refiners worldwide to renegotiate offtake terms and accelerate alternative feedstock development.
Growth Catalysts
- Thin-film photovoltaic expansion:Cadmium-telluride solar manufacturers are absorbing rising selenium volumes for buffer layer deposition, particularly in utility-scale installations across the southwestern United States.
- REACH chemical registration compliance:European importers are consolidating purchases around certified refiners holding full substance dossiers, concentrating demand among pre-qualified supply chains.
- Glass decolorization standards:Container and flat-glass producers in Southeast Asia are mandating higher-purity selenium dioxide to achieve optical clarity specifications for premium packaging and architectural applications.
Market Restraints
- Copper concentrate grade decline:Lower head grades at major porphyry deposits are reducing anode slime generation per ton of refined copper, compressing selenium recovery rates.
- Tellurium co-product competition:Refiners optimizing for tellurium yields in photovoltaic-grade material are diverting metallurgical attention from selenium purification trains.
- Substitution by cerium compounds:Glass manufacturers facing selenium price volatility are qualifying cerium oxide alternatives for decolorizing applications, threatening volume retention.
Strategic Opportunities
- Battery-grade selenium compounds:Emerging sodium-selenium and lithium-selenium chemistries are creating qualification pathways for high-purity metal in next-generation energy storage systems.
- Secondary recovery from electronic waste:Urban mining operations in Germany and Japan are developing hydrometallurgical flowsheets to extract selenium from discarded photocopier drums and rectifiers.
- India's PLI scheme for solar manufacturing:Domestic content requirements for photovoltaic cells are incentivizing local selenium refining capacity to serve integrated module production.
Industry Challenges
- Hydrometallurgical expertise scarcity:Selenium dioxide purification to 99.999% electronics grade requires specialized solvent extraction knowledge concentrated among retiring engineers at legacy refiners.
- Multi-jurisdictional waste classification:Selenium-containing residues trigger divergent hazardous waste protocols across EPA, REACH, and China's MEE frameworks, complicating cross-border logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Selenium Mining Market |
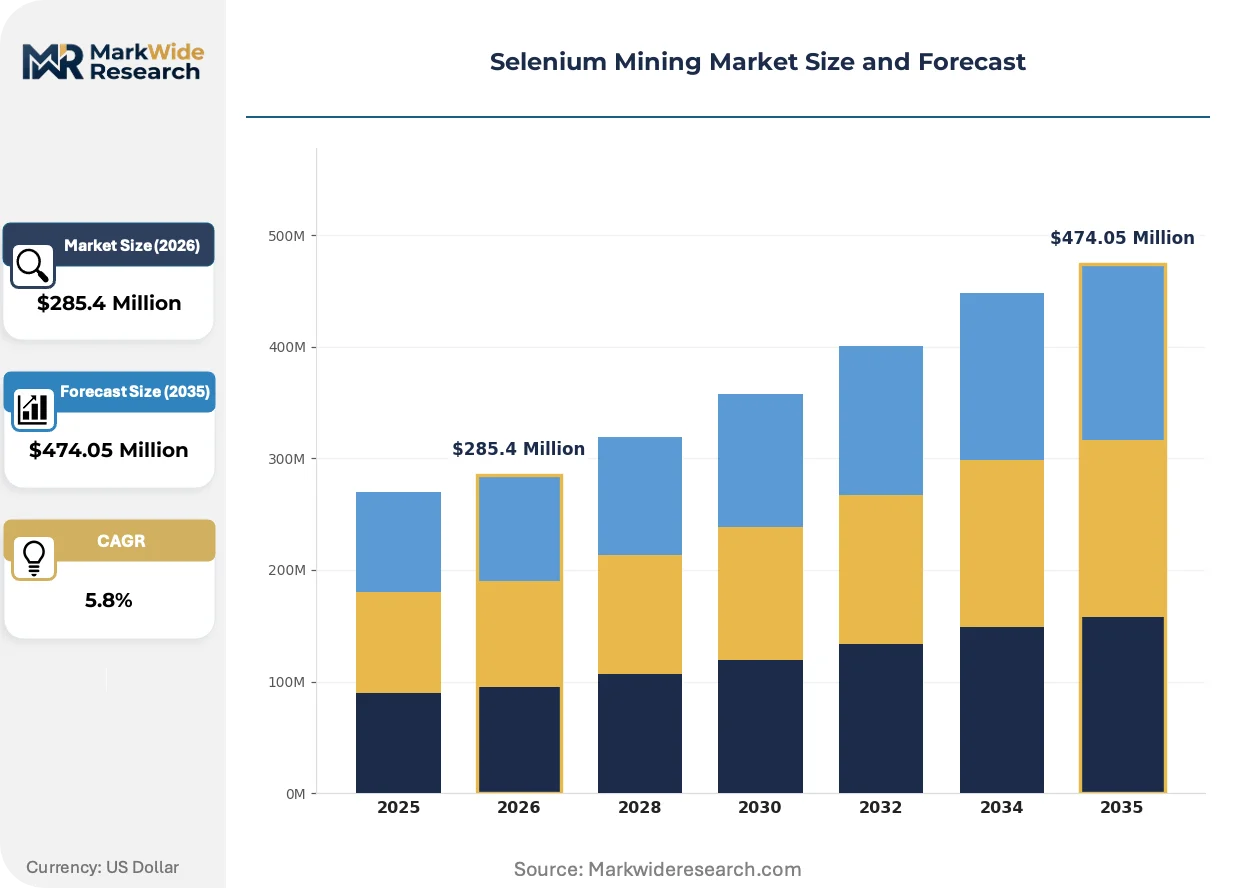
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $474.05 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Mining Method: Open Pit Mining, Underground Mining, Placer Mining, In-situ Leaching End Use Industry: Glass Manufacturing, Electronics & Semiconductors, Agriculture, Photovoltaic Cells Product Form: Metallic Selenium, Selenium Dioxide, Selenium Sulfide, Selenium Powder Extraction Technology: Flotation, Hydrometallurgy, Pyrometallurgy, Chemical Leaching |
| Companies Covered | JX Nippon Mining & Metals, Dowa Holdings Co., Ltd., Sumitomo Metal Mining Co., Ltd., Yunnan Copper, Nippon Rare Metal, Inc., Mitsubishi Materials Corporation, KGHM Polska Miedź, Glencore, Aurubis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Selenium Mining Market Trends and Innovations
Refining technology convergence and end-use specification tightening are compressing the viable supplier base while opening premium segments for purity-certified producers.
Selenium dioxide vapor deposition systems are integrating into semiconductor manufacturing lines for phase-change memory layer fabrication. Memory chip foundries in South Korea and Taiwan are adopting these systems at pilot scale ahead of volume ramp. This integration is compressing qualification timelines for traditional powder suppliers and favoring integrated gas delivery partnerships.
China's MEE emissions caps on non-ferrous smelters are forcing selenium recovery circuit upgrades or temporary production halts at several copper refineries. The policy is redirecting spot market liquidity toward Indonesian and Chilean alternative supply. Electronics-grade buyers are responding by diversifying qualified supplier lists beyond traditional Chinese sources.
Long-term offtake contracting is displacing spot purchasing among major glass and metallurgical consumers. Buyers in Brazil and Turkey are locking in multi-year supply agreements directly with copper smelter affiliates, bypassing merchant traders. This pattern is most visible in container glass hubs where input cost predictability outweighs price optimization.
Selenium Mining Market Segmentation
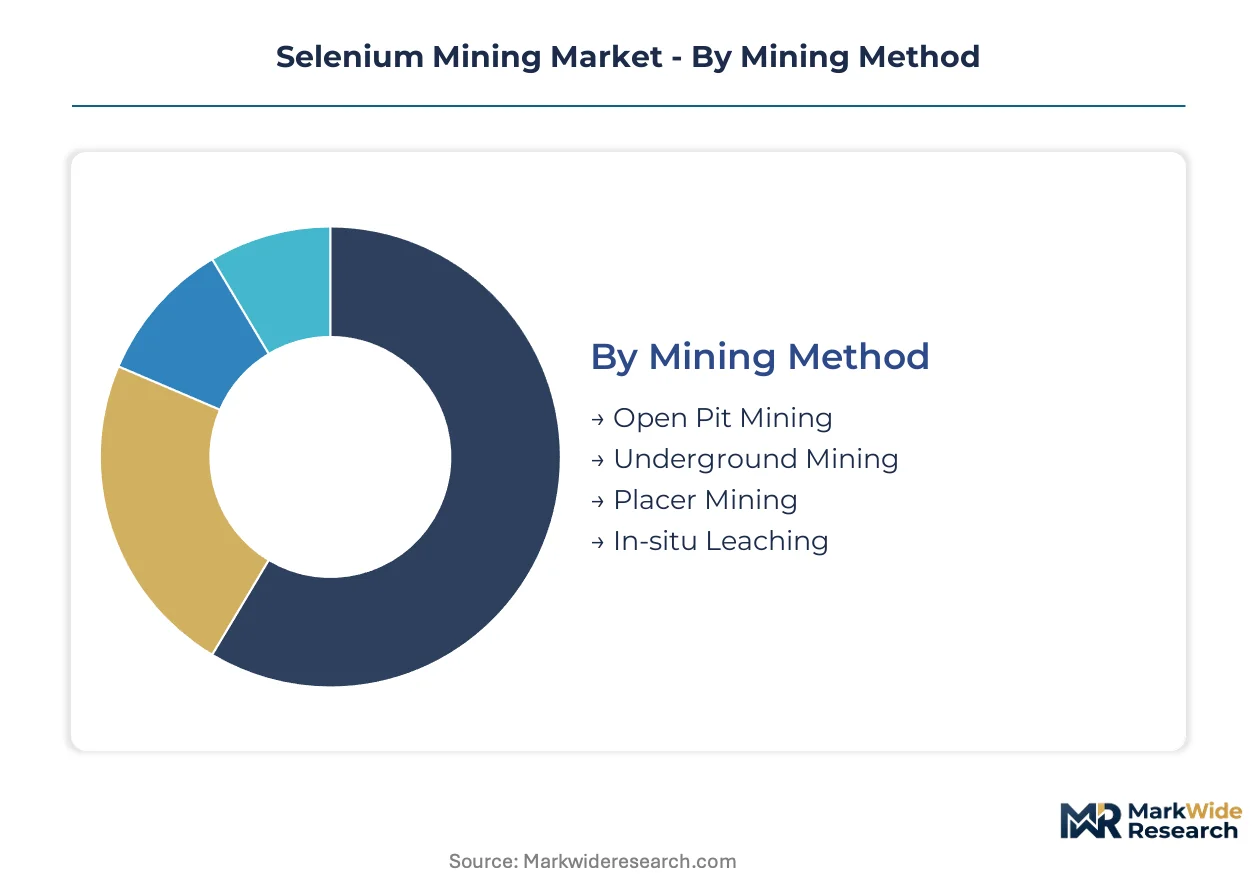
Selenium mining segmentation reveals how extraction economics, purity thresholds, and end-use specifications fragment supply chains. Refiners must align recovery technology with customer certification requirements across distinct commercial tiers.
Mining Method:
Open pit operations dominate raw tonnage while underground methods yield higher selenium concentrations per unit of ore processed.
- Open Pit Mining:Large-scale porphyry copper deposits generate the bulk of selenium-bearing anode slimes as a refining byproduct. Chinese copper smelters in Jiangxi and Anhui provinces rely heavily on this feedstock stream for selenium recovery circuits.
- Underground Mining:Polymetallic vein deposits in the Erzgebirge region and select Canadian shield operations produce concentrated selenium ores requiring less downstream purification intensity.
- Placer Mining:Alluvial deposits in limited jurisdictions yield trace selenium associated with heavy mineral concentrates.
- In-situ Leaching:Solution mining of low-grade deposits applies primarily to uranium-copper co-occurrences with marginal selenium recovery economics.
Mature deployment sits with Open Pit Mining. Newer deployment is concentrated in Underground Mining.
End Use Industry:
Application requirements split the market between commodity-grade volume buyers and electronics-grade premium purchasers.
- Glass Manufacturing:Container and flat-glass producers in Southeast Asia mandate selenium dioxide for optical decolorization. Mundra and Maha Phruettharam glassworks anchor regional offtake for premium packaging applications.
- Electronics & Semiconductors:Phase-change memory foundries in South Korea and Taiwan drive demand for 99.999% purity metal. Vapor deposition systems integration is compressing qualification timelines for traditional powder suppliers.
- Agriculture:Micronutrient formulations for selenium-deficient soils represent steady, price-sensitive demand concentrated in New Zealand and Finland.
- Photovoltaic Cells:Cadmium-telluride solar manufacturers absorb rising volumes for buffer layer deposition in utility-scale southwestern United States installations.
Electronics & Semiconductors commands the steepest expansion trajectory. Agriculture maintains the most stable, mature demand profile.
Product Form:
Purification intensity determines margin capture, with gas-phase and electronics-grade products commanding premium positioning over commodity powders.
- Metallic Selenium:High-purity ingots and pellets serve semiconductor doping and alloy applications. Japanese refiners at the Kosaka complex specialize in 99.99%+ material for phase-change memory layer fabrication.
- Selenium Dioxide:Oxidized form dominates glass decolorization and chemical synthesis feedstock markets. REACH-registered European importers consolidate purchases around certified refiners holding full substance dossiers.
- Selenium Sulfide:Specialty chemical applications in anti-dandruff formulations and veterinary preparations.
- Selenium Powder:Lower-purity material for metallurgical alloying and agricultural supplementation.
Glass Manufacturing anchors Selenium Dioxide offtake. Electronics & Semiconductors is driving Metallic Selenium specification tightening fastest.
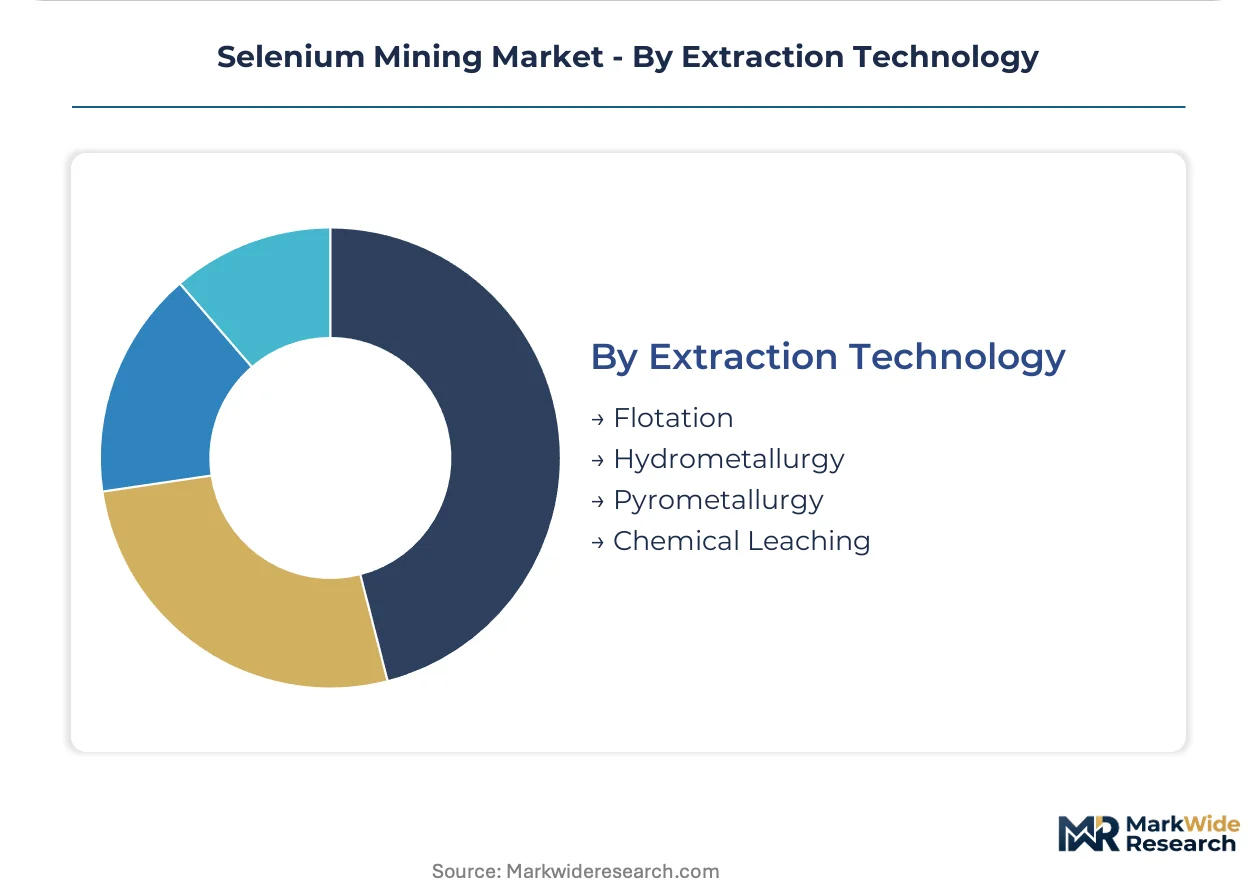
Extraction Technology:
Recovery method selection hinges on feedstock mineralogy, co-product value, and waste management constraints.
- Flotation:Physical separation concentrates selenium-bearing sulfides ahead of smelting. Chilean copper operations employ this front-end processing for porphyry deposit feeds.
- Hydrometallurgy:Solvent extraction and electrowinning circuits enable selective selenium recovery from complex anode slimes. Dowa Holdings anchors its position through advanced hydrometallurgical capabilities at the Kosaka complex.
- Pyrometallurgy:High-temperature smelting and refining remains the dominant pathway for copper-associated selenium recovery.
- Chemical Leaching:Acidic or alkaline leaching of oxidized ores and secondary materials supports urban mining applications in Germany and Japan.
Pyrometallurgy represents the most mature, widely deployed recovery pathway. Hydrometallurgy is expanding most quickly for electronics-grade purification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Jiangxi Copper Industrial Park anchors selenium concentration through integrated copper smelting and anode slime processing. The zone's tax incentives for non-ferrous refining have concentrated recovery capacity in Ganzhou and Yichun corridors.
China
Copper smelters in Jiangxi and Anhui provinces generate the majority of selenium-rich anode slimes as a byproduct stream. MEE emissions caps on non-ferrous smelters are forcing recovery circuit upgrades at several refineries. Ganzhou and Yichun industrial corridors concentrate hydrometallurgical upgrading capacity for electronics-grade output.
Japan
Phase-change memory foundries in Kansai and Chubu regions absorb high-purity metallic selenium for semiconductor layer fabrication. METI's critical minerals security framework prioritizes domestic refining of copper byproduct streams. The Kosaka complex in Akita Prefecture anchors advanced hydrometallurgical purification for 99.999% grade material.
United States
Cadmium-telluride solar manufacturers in the southwestern states absorb rising selenium volumes for buffer layer deposition. EPA hazardous waste rules govern selenium-containing slag discharge from copper refiners in Arizona and Utah. The Colorado Plateau copper belt feeds selenium recovery circuits at smelters near Salt Lake City.
Germany
Urban mining operations in Saxony develop hydrometallurgical flowsheets to extract selenium from discarded photocopier drums and rectifiers. REACH registration obligations impose full substance dossiers on selenium dioxide importers. The Erzgebirge mining region's polymetallic vein deposits yield concentrated selenium ores requiring less downstream purification.
Chile
Large-scale porphyry copper deposits in the Atacama Desert generate bulk selenium-bearing anode slimes through open pit operations. The national mining regulator enforces tailings management protocols affecting byproduct recovery economics. Antofagasta and Calama smelting complexes concentrate pyrometallurgical selenium extraction capacity.
Selenium Mining Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated copper smelters commanding upstream supply and merchant refiners competing on purification technology. The structure concentrates around three archetypes: captive smelter affiliates with guaranteed feedstock access, independent hydrometallurgical specialists, and diversified materials conglomerates with cross-product optimization. M&A activity targets anode slime offtake rights, while capacity expansion focuses on electronics-grade purification trains.
Among Japanese integrated refiners, JX Nippon Mining & Metals and Dowa Holdings exemplify the captive-smelter archetype through copper-smelting footprints sustaining selenium output. Sumitomo Metal Mining occupies a position within this tier by controlling access to high-grade anode slime streams. These three represent how backward integration into copper refining anchors selenium supply security.
| Leading Market Players |
|---|
| JX Nippon Mining & Metals |
| Dowa Holdings Co., Ltd. |
| Sumitomo Metal Mining Co., Ltd. |
| Yunnan Copper |
| Nippon Rare Metal, Inc. |
| Mitsubishi Materials Corporation |
| KGHM Polska Miedź |
| Glencore |
| Aurubis AG |
| Others |
Pricing and Supply Chain Analysis
Electronics-grade hydrometallurgical purification is displacing legacy pyrometallurgical recovery, simultaneously elevating capital intensity for refiners and concentrating margin capture among Japanese and German specialists with certified solvent-extraction capabilities. This technology transition tightens the supplier base while amplifying price premiums for 99.999% purity material destined for phase-change memory foundries.
Pricing Analysis
Volume buyers in glass decolorization and agricultural supplementation operate on thin margins, while electronics-grade metallic selenium commands substantial premiums tied to REACH certification and vapor-deposition compatibility. Price differentiation hinges on purity grade and regulatory dossier completeness, with cerium oxide substitution threats compressing commodity-tier pricing. Buyers in container glass hubs exhibit highest price sensitivity, whereas semiconductor foundries prioritize supply security over unit cost.
Supply Chain Analysis
REACH and EPA certification gating restricts qualified supplier pools, with viable electronics-grade capacity concentrated in Japan, Germany, and select Chinese smelters upgrading hydrometallurgical circuits. The supply chain draws from copper anode slimes, sulfuric acid leaching reagents, and specialized solvent-extraction equipment. Single-source vulnerability intensifies around Kosaka-complex purification expertise. Distribution runs through long-term offtake contracts directly with copper smelter affiliates, displacing spot market liquidity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sodium-selenium battery chemistry is displacing legacy lithium-ion architectures in grid-scale storage applications, creating qualification windows for high-purity selenium producers ahead of volume manufacturing scale-up.
For Market Incumbents: Extend hydrometallurgical purification capabilities to capture battery-grade selenium compound demand, while consolidating anode slime offtake rights from Indonesian and Chilean copper smelters to offset Chinese MEE emissions cap constraints. Certification investment in REACH full substance dossiers represents the critical defensive lever against merchant trader displacement. For New Entrants and Emerging Players: The 40-60% price-point gap between premium electronics-grade and economy metallurgical selenium creates entry space for mid-tier refiners targeting 99.99% purity at moderate scale. India's PLI scheme for solar manufacturing offers the most penetrable geography, with domestic content requirements incentivizing local refining partnerships over import dependency. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified materials conglomerates seeking copper byproduct stream control, with long-term viability contingent on positioning ahead of sodium-selenium battery commercialization. Target acquisition archetype: mid-scale hydrometallurgical specialists with existing REACH registration and vapor-deposition partnerships. The signal to watch is cadmium-telluride solar installation run-rates in southwestern United States utility markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Anode Slime Supply | JX Nippon and Dowa Holdings secure captive feedstock through copper smelter affiliates. |
| Hydrometallurgical Capacity Expansion | Kosaka complex upgrades enable 99.999% purity output for Taiwan memory foundries. |
| REACH Full Substance Dossier Investment | European importers consolidate purchases around certified German and Japanese refiners. |
| Long-term Supply Agreement Lock-in | Brazilian and Turkish glassworks bypass merchant traders with multi-year copper smelter contracts. |
| Battery-Grade Compound Qualification | Sodium-selenium chemistry development opens energy storage offtake beyond photovoltaic applications. |
Research Methodology
Independent corroboration across copper smelter operations managers, hydrometallurgical process engineers, glass manufacturing procurement leads, and semiconductor materials specialists underwrites the qualitative findings. Secondary validation incorporated customs trade data, SEC filings from diversified materials conglomerates, MEE emissions disclosure reports, and REACH registration databases. Bottom-up triangulation across refinery capacity announcements and top-down demand modeling across end-use segments anchored volume estimates.
Comparable-period anchoring to historical copper smelter output and anode slime generation rates established the forecast baseline across the projection horizon. Segmentation dimensions modeled include mining method, purity grade tier, end-use industry application, and regional regulatory framework. CAGRs were derived from regression analysis against copper production forecasts and photovoltaic installation trajectories, with battery-grade material specifications and solar panel efficiency standards treated as scenario-dependent demand shifters.
Inputs from primary stakeholder interviews were available through the study window; gaps in real-time Chinese smelter operating rates and confidential offtake contract terms introduce uncertainty bands around near-term supply projections. Forecasts reflect documented assumptions regarding MEE enforcement consistency and sodium-selenium battery chemistry development timelines. A model refresh is warranted upon material change in copper concentrate grade trends or cadmium-telluride solar technology cost competitiveness.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Titanium Ore Market
Metals & Minerals
Garnet Market
Metals & Minerals
Middle East and Africa Aluminum Extrusion Market
Metals & Minerals
Recycled Lead Market
Metals & Minerals
Hot Briquetted Iron (HBI) Market
Metals & Minerals
Colored Gemstones Market
Metals & Minerals
Global Magnesium Hydroxide Market
Metals & Minerals
Solder Materials Market
Metals & Minerals
Wegscheiderite Market
Metals & Minerals
Californium Market
Metals & Minerals
Mineral Screening Market
Metals & Minerals
Nickel Nano Powder Market
Metals & Minerals
Cobalt Sulphate Market
Metals & Minerals
Recycled Antimony Market
Metals & Minerals
Global Gold Potassium Cyanide Market
Metals & Minerals
Global Fabricated Metal Products Market