
 Middle-East and Africa Lithium Market | 2026-2036
Middle-East and Africa Lithium Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Lithium Market Foresight
REACH compliance is restructuring the cost-of-entry calculus for European-bound lithium exports from Middle-East and Africa processing hubs. Albemarle Corporation leverages its integrated brine-to-cathode expertise to sustain supply relationships across South African port infrastructure. Jiangxi Ganfeng Lithium Co., Ltd. anchors its regional position through offtake agreements with Zimbabwean hard-rock projects. Zimbabwe Lithium Company competes on asset proximity to Africa's only operating petalite concentrator.
Lithium extracted from spodumene, petalite, and lepidolite ores typically grades between 1.0% and 2.5% Li₂O before chemical conversion to battery-grade carbonate or hydroxide exceeding 99.5% purity; this metal serves as the irreplaceable charge carrier in lithium-ion electrochemical cells. Lithium Carbonate dominates current African export volumes due to established conversion infrastructure, while Lithium Hydroxide captures expanding margin pools as high-nickel cathode formulations tighten specification requirements. The Batteries end-use segment absorbs the majority of regional concentrate offtake, though Ceramics and Glass sustain baseline demand from established Middle Eastern industrial consumers.
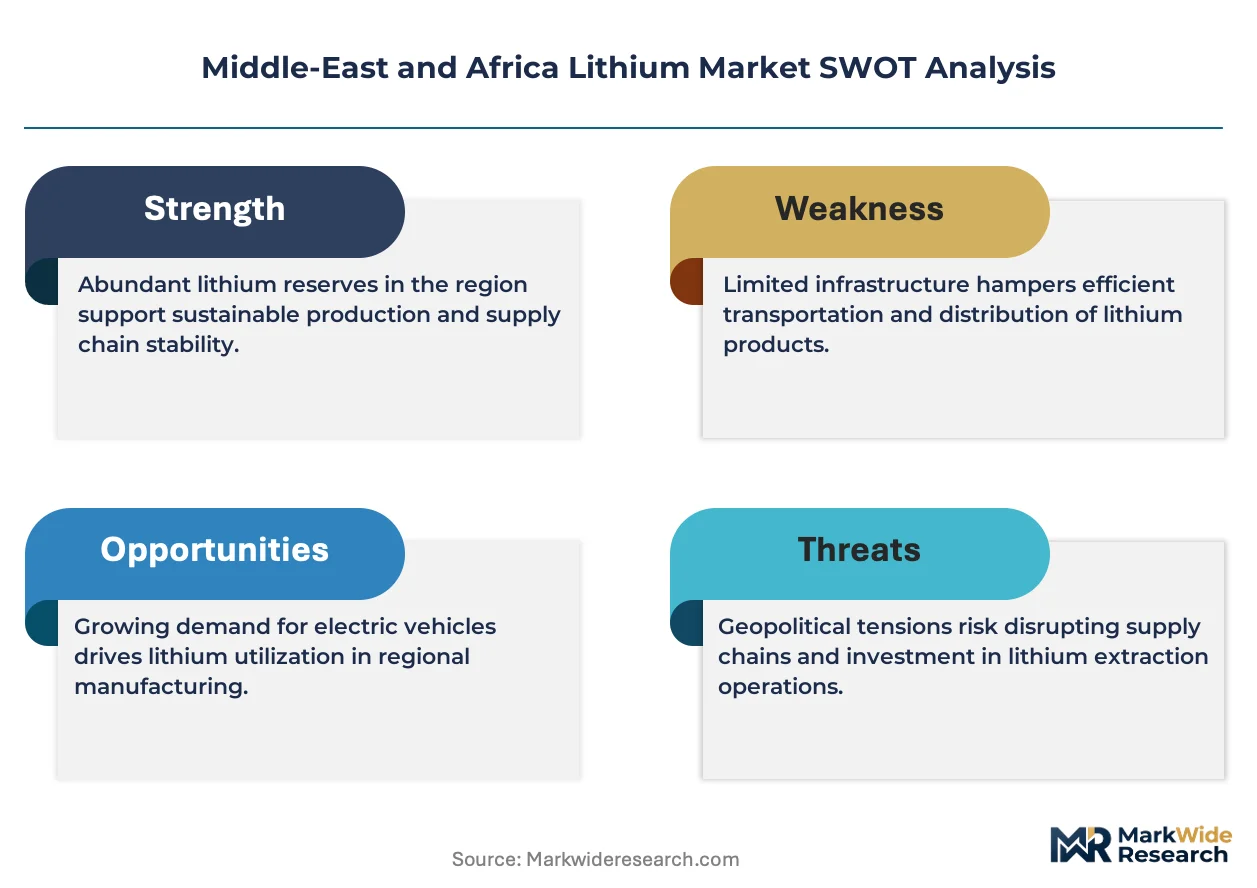
South Africa's Department of Mineral Resources and Energy enforces beneficiation thresholds that shape export licensing conditions, while Zimbabwe's central bank mandates domestic currency retention rules on lithium sales that alter working capital structures for foreign operators. Saudi Arabia's SFDA and industrial investment frameworks are positioning the Kingdom as a downstream chemicals destination through partnerships with Australian and Chinese concentrate suppliers. Stakeholders must monitor how beneficiation enforcement intensity across Southern African jurisdictions reshapes project economics for integrated versus export-only development models.
Market Dynamics
Zimbabwe's beneficiation regulations are forcing foreign operators to build domestic conversion capacity rather than export raw concentrate, fundamentally restructuring capital deployment timelines and joint-venture structures across Southern African lithium provinces.
Growth Catalysts
- Electric vehicle battery demand:Automotive OEMs are securing long-term offtake agreements for battery-grade lithium hydroxide to supply high-nickel cathode formulations, pulling concentrate through Middle Eastern and African processing corridors.
- Saudi downstream investment frameworks:The Kingdom's industrial chemicals partnerships with Australian and Chinese concentrate suppliers are establishing Red Sea processing hubs that reduce logistics costs for European-bound material.
- REACH compliance restructuring:European chemical safety standards are creating premium pricing tiers for certified-sustainable lithium, rewarding operators who invest in traceable supply chains from African hard-rock sources.
Market Restraints
- Hard-rock concentration risk:Zimbabwe's Bikita and Arcadia districts control the majority of proven African spodumene reserves, creating single-jurisdiction exposure for concentrate supply security.
- Energy input cost volatility:Diesel-powered mining fleets and grid-dependent processing plants face fuel price swings that compress operating margins for hard-rock extraction operations.
- Technical beneficiation thresholds:South Africa's Department of Mineral Resources and Energy enforces minimum domestic processing requirements that extend project development timelines and raise capital intensity for export licensing.
Strategic Opportunities
- Underpenetrated Nigerian lithium provinces:Nascent pegmatite discoveries in Kaduna and Nasarawa states offer greenfield development potential ahead of regulatory framework crystallization.
- Direct shipping ore to hydroxide pathways:Emerging acid-roast and pressure-leach technologies enable bypassing carbonate intermediate stages, capturing margin pools previously lost to Asian conversion.
- South African port infrastructure expansion:Richards Bay and Coega port modernization programs are reducing vessel turnaround times for bulk concentrate exports to Asian cathode manufacturers.
Industry Challenges
- Metallurgical skill scarcity:The region lacks sufficient chemical engineers trained in lithium-specific flotation and acid-leach processes, forcing reliance on expatriate technical teams.
- Currency retention compliance complexity:Zimbabwe's central bank mandates on lithium sales revenue create working capital constraints for foreign operators managing dollar-denominated equipment and reagent procurement.
- Integrated project execution timelines:Simultaneous construction of mine, concentrator, and conversion facilities stretches engineering procurement and construction management capacity across multiple concurrent developments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Lithium Market |
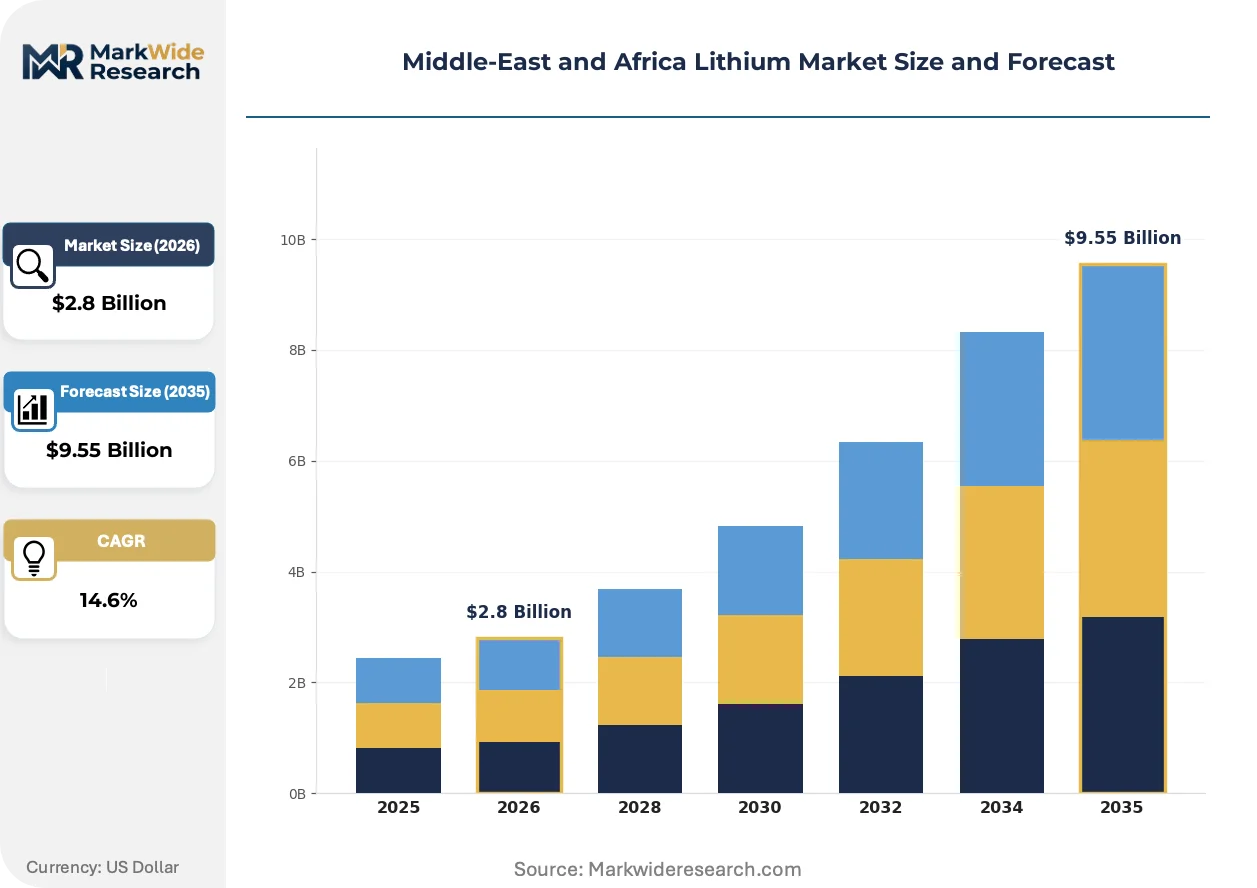
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium Carbonate, Lithium Hydroxide, Lithium Concentrate, Lithium Metal End User: Batteries, Ceramics, Glass, Pharmaceuticals Deployment: Onshore, Offshore, Hybrid, Distributed Market Channel: Direct Sales, Distributors, Online Sales, Others |
| Companies Covered | Albemarle Corporation, SQM S.A., FMC Corporation, Lepidico Ltd, Orocobre Limited Pty Ltd, Pilbara Minerals Limited, Lithium Americas Corp, Jiangxi Ganfeng Lithium Co., Ltd., Zimbabwe Lithium Company, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Lithium Market Shifts & Advancements
Hard-rock lithium processing is absorbing capital and engineering talent as brine dominance wanes, with African operators pioneering novel beneficiation techniques that reduce energy intensity and water consumption in spodumene concentration.
Direct shipping ore is absorbing investment flows from traditional concentrate-to-carbonate pathways, as African projects deploy acid-roast circuits that convert run-of-mine material directly into battery-grade hydroxide. High-nickel cathode manufacturers in South Korea and Japan are qualifying these alternative feedstocks to diversify supply beyond South American brine. The technology is absorbing margin compression in carbonate markets by enabling African producers to bypass intermediate conversion stages and capture hydroxide premiums.
REACH chemical safety regulations are tightening traceability requirements for European-bound lithium, forcing African exporters to implement chain-of-custody systems that document environmental and labor standards across mining and processing stages. The European Chemicals Agency's expanded substance evaluation protocols are extending certification timelines for new concentrate suppliers. Battery manufacturers with European assembly plants are responding by embedding compliance teams within African joint ventures to accelerate audit readiness.
Buyer concentration among integrated battery-cathode producers is compressing offtake negotiation cycles, with tier-one automotive OEMs and their cell suppliers consolidating procurement through direct equity stakes in African projects. Traditional traders and merchant offtakers are losing share to captive supply arrangements that secure volume through project finance participation. This pattern is most visible in Zimbabwe, where Chinese battery manufacturers have acquired majority positions in hard-rock developments to lock in concentrate supply for expanding European electric vehicle assembly capacity.
Middle-East and Africa Lithium Market Segmentation
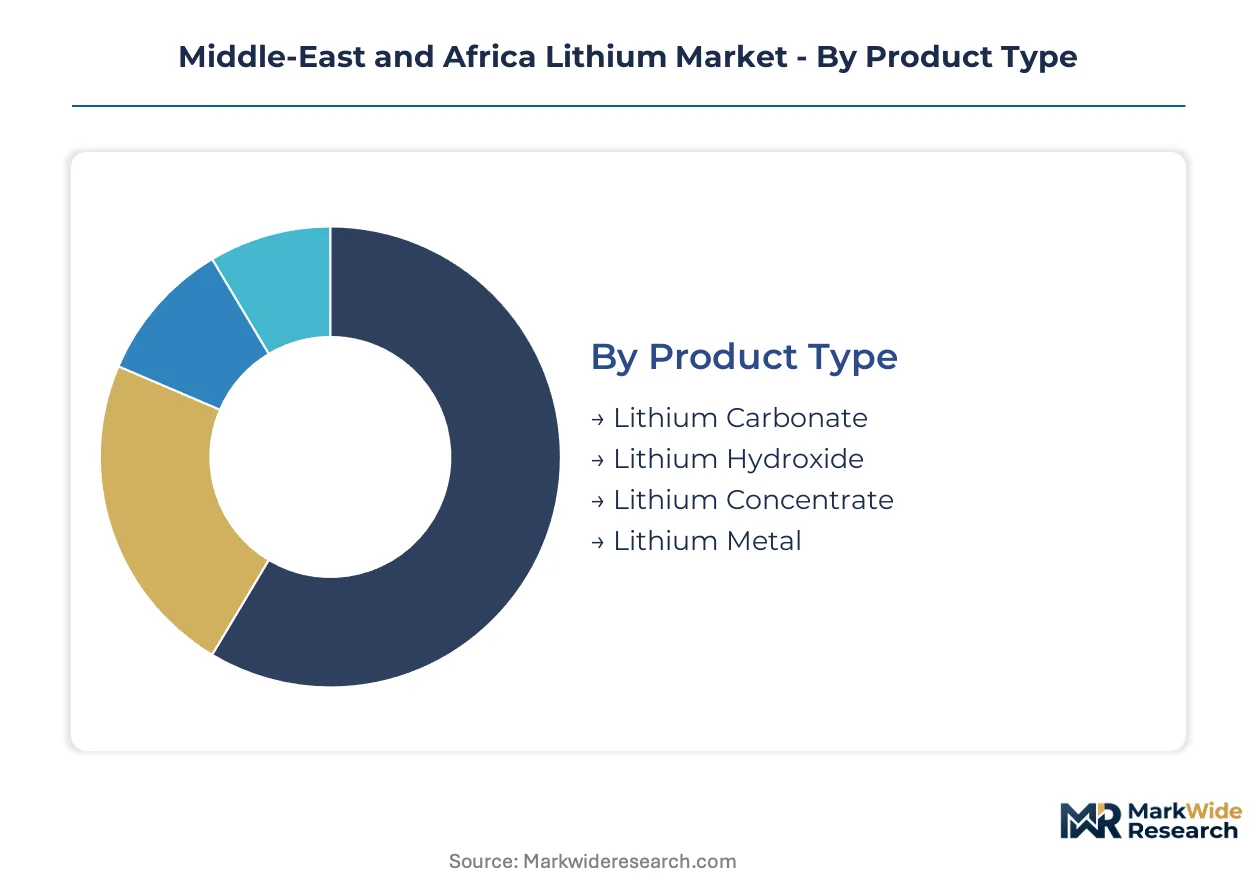
Segmentation in the Middle-East and Africa lithium market reveals how beneficiation regulations and battery supply chain demands are reshaping product flows. Buyers prioritize purity grades and conversion readiness over raw tonnage, forcing suppliers to align output specifications with cathode manufacturer requirements.
Product Type:
Buyers differentiate primarily by conversion stage and purity threshold, with battery-grade specifications commanding premium positioning over technical-grade alternatives.
- Lithium Hydroxide:Battery-grade material exceeding 99.5% purity serves high-nickel cathode formulations. Demand concentrates in Saudi Red Sea processing hubs supplying European automotive OEMs, pulled by REACH-compliant traceability requirements.
- Lithium Carbonate:Dominates current African export volumes through established conversion infrastructure. Zimbabwe's Bikita and Arcadia districts feed carbonate circuits, though margin compression is accelerating interest in direct hydroxide pathways.
- Lithium Concentrate:Spodumene and petalite ores grading 1.0-2.5% Li₂O require downstream chemical conversion. Zimbabwe's beneficiation regulations now restrict raw concentrate exports, forcing domestic processing investment.
- Lithium Metal:Primary demand from specialized industrial applications and next-generation solid-state battery research. Regional production remains minimal due to energy-intensive electrolytic reduction requirements.
Volume sits with Lithium Carbonate; growth tilts toward Lithium Hydroxide.
End User:
Application requirements range from ultra-high purity electrochemical specifications to bulk industrial tolerance, creating divergent procurement patterns across customer categories.
- Batteries:Lithium-ion cell manufacturing absorbs the majority of regional concentrate offtake. Electric vehicle battery supply chains represent the steepest expansion trajectory, with automotive OEMs securing long-term hydroxide agreements.
- Ceramics:Technical-grade lithium lowers thermal expansion in ceramic glazes and bodies. Established Middle Eastern industrial consumers sustain baseline demand through predictable, volume-based contracts.
- Glass:Lithium carbonate improves melting properties and thermal shock resistance in specialty glass production. Saudi and UAE manufacturing clusters maintain steady offtake for optical and container glass applications.
- Pharmaceuticals:High-purity lithium compounds treat bipolar disorder and other psychiatric conditions. Regulatory scrutiny from Saudi SFDA and comparable agencies elevates documentation requirements for medical-grade material.
Procurement scale favors Batteries; margin stability characterizes Ceramics and Glass.
Deployment:
Infrastructure configuration determines capital intensity and grid dependency, with energy access shaping project feasibility across African jurisdictions.
- Onshore:Integrated mine-to-concentrator operations anchor Zimbabwe's Bikita and Arcadia districts. Grid-dependent processing plants face diesel backup requirements during load-shedding events.
- Offshore:Floating or coastal processing concepts remain theoretical for African hard-rock lithium, though Red Sea hub discussions incorporate offshore engineering expertise from Saudi industrial partnerships.
- Hybrid:Solar-diesel generation blends address energy input cost volatility at remote spodumene sites. South African developers pilot hybrid microgrids to reduce fuel price exposure.
- Distributed:Modular concentrator units enable phased capital deployment across multiple pegmatite discoveries. Nigerian greenfield projects in Kaduna and Nasarawa states evaluate distributed architectures ahead of regulatory framework crystallization.
Capital deployment concentrates in Onshore configurations; Hybrid models gain traction fastest among new entrants.
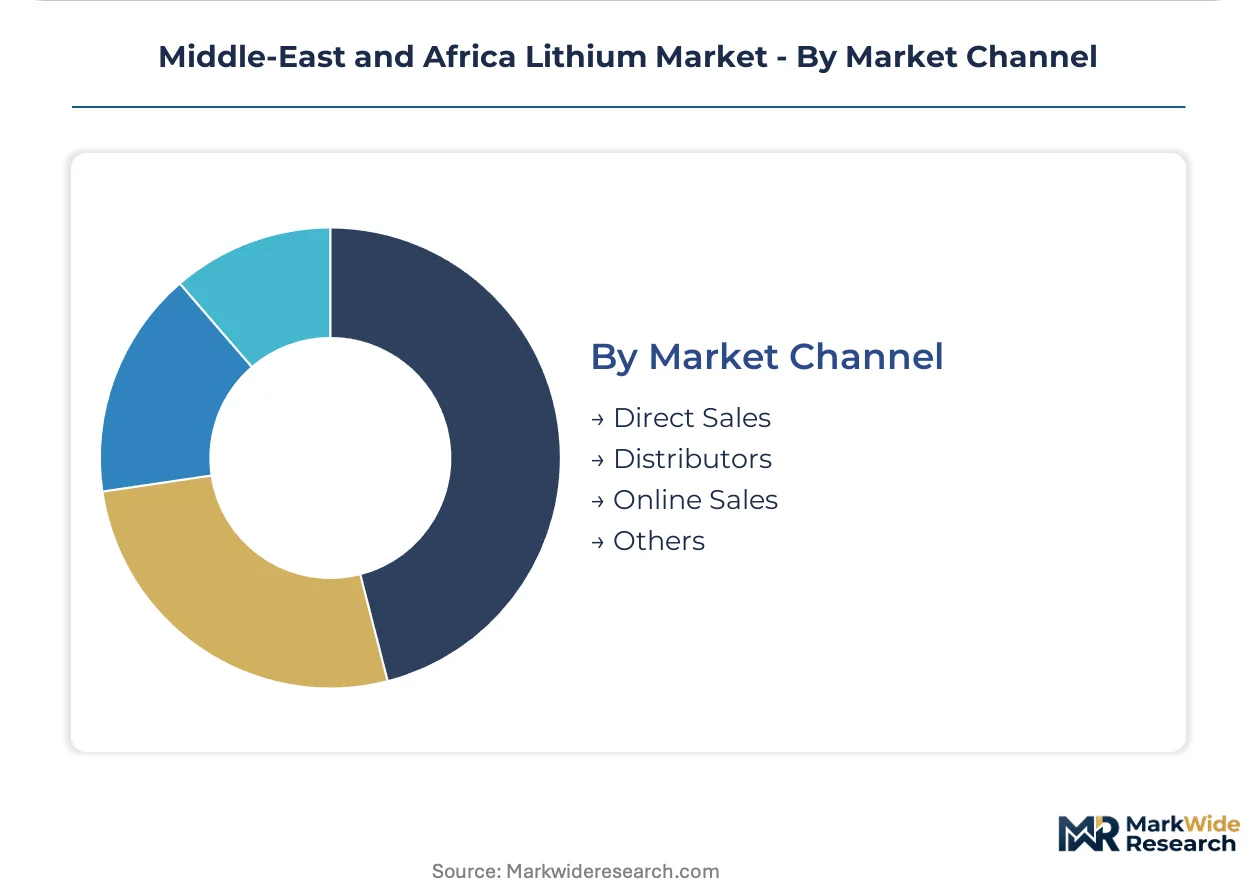
Market Channel:
Channel selection reflects buyer concentration and contract structure preferences, with integrated battery manufacturers displacing traditional merchant offtakers.
- Direct Sales:Tier-one automotive OEMs and cell suppliers secure volume through equity stakes and captive supply arrangements. Chinese battery manufacturers have acquired majority positions in Zimbabwean hard-rock developments.
- Distributors:Merchant traders retain relevance for technical-grade material serving ceramics and glass customers. Working capital constraints from Zimbabwe's currency retention rules complicate distributor financing structures.
- Online Sales:Spot market platforms facilitate small-lot transactions for laboratory and research quantities. Limited penetration in bulk battery-grade material due to certification and traceability requirements.
- Others:Joint-venture offtake structures blend direct equity participation with contracted volume commitments. Albemarle Corporation and Jiangxi Ganfeng Lithium Co., Ltd. leverage integrated relationships across South African port infrastructure.
Contract volume flows through Direct Sales; Distributors retain niche positioning in technical-grade segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zimbabwe's Bikita and Arcadia mining districts operate under special mining zone frameworks that concentrate hard-rock lithium extraction and concentrate processing capacity within designated beneficiation corridors.
Zimbabwe
Electric vehicle battery manufacturers and ceramics producers drive concentrate demand from Bikita and Arcadia districts. The central bank mandates domestic currency retention rules on lithium sales that alter working capital structures for foreign operators. Masvingo Province hosts Africa's only operating petalite concentrator, where Zimbabwe Lithium Company competes on asset proximity advantages.
South Africa
Battery-grade chemical conversion and port logistics services anchor demand from Richards Bay and Coega industrial zones. The Department of Mineral Resources and Energy enforces beneficiation thresholds that shape export licensing conditions for concentrate processors. Northern Cape and Western Cape provinces host emerging processing corridors where grid-dependent plants face diesel backup requirements during load-shedding events.
Saudi Arabia
Red Sea downstream chemicals partnerships with Australian and Chinese concentrate suppliers establish processing hubs for European-bound material. The SFDA and industrial investment frameworks position the Kingdom as a chemicals destination through regulatory alignment with battery supply chain requirements. Jazan and Yanbu industrial cities absorb capital deployment for hydroxide conversion capacity serving high-nickel cathode formulations.
United Arab Emirates
Technical-grade lithium consumption from ceramics and glass manufacturing clusters sustains baseline demand through predictable volume contracts. MOHAP-equivalent industrial regulators maintain standards alignment with European chemical safety protocols for re-export processing. Jebel Ali and Khalifa Port free zones concentrate logistics infrastructure for bulk concentrate transit to Asian cathode manufacturers.
Nigeria
Nascent pegmatite discoveries in Kaduna and Nasarawa states attract greenfield development interest ahead of regulatory framework crystallization. The country's mining investment promotion agencies structure fiscal incentives for lithium-specific exploration and early-stage extraction. Northern Nigeria's emerging pegmatite belt hosts modular concentrator pilot programs evaluating distributed processing architectures.
Middle-East and Africa Lithium Market Competitive Landscape
Zimbabwean hard-rock specialists anchor one tier; Saudi and South African downstream processors hold conversion and logistics advantages. The market structure concentrates around integrated mine-to-cathode operators, merchant concentrate traders, and port-dependent processing joint ventures. Three archetypes dominate: brine-to-cathode integrators, hard-rock offtake aggregators, and beneficiation-compliant domestic developers. Competitive moves center on captive supply arrangements through equity stakes and beneficiation-compliant joint venture structures that satisfy domestic processing mandates.
Among Americas-based lithium majors, Albemarle Corporation and FMC Corporation occupy positions as integrated brine-to-cathode operators leveraging established chemical conversion expertise. Chilean specialist SQM S.A. represents the South American brine extraction archetype with technical knowledge transferable to African hard-rock assessments. Chinese fabricator Jiangxi Ganfeng Lithium Co., Ltd. anchors the hard-rock offtake aggregator tier through regional offtake agreements with Zimbabwean concentrate producers. These three exemplify how geographic origin and corporate structure shape competitive positioning across the Middle-East and Africa lithium corridor.
| Leading Market Players |
|---|
| Albemarle Corporation |
| SQM S.A. |
| FMC Corporation |
| Lepidico Ltd |
| Orocobre Limited Pty Ltd |
| Pilbara Minerals Limited |
| Lithium Americas Corp |
| Jiangxi Ganfeng Lithium Co., Ltd. |
| Zimbabwe Lithium Company |
| Others |
Supply & Pricing Matrix
Battery-grade hydroxide certification tiers command steep premiums over technical-grade carbonate alternatives, with REACH-compliant traceability documentation separating European-bound material from commodity spot sales. This bifurcation concentrates pricing power among integrated operators who control mine-to-converter pathways through Zimbabwe's beneficiation corridors and Saudi Red Sea processing hubs, while marginal producers face margin compression from energy input volatility and currency retention compliance costs.
Pricing Analysis
Short lead-time premiums for qualified battery-grade hydroxide now exceed spot carbonate discounts by substantial spreads, reflecting automotive OEM urgency to secure cathode-ready material. Contract-based long-term offtake structures dominate procurement, with price differentiation hinging on REACH certification tier and volume scale commitments. Pricing pressure stems from Zimbabwe's domestic processing mandates that extend capital deployment timelines and raise unit costs for export-only developers. Tier-one battery manufacturers exhibit lowest price sensitivity due to captive supply imperatives, while ceramics and glass buyers negotiate aggressively on technical-grade volumes.
Supply Chain Analysis
REACH qualification gating restricts European-bound supply to operators with documented chain-of-custody systems, eliminating unaudited African concentrate from premium tiers. Geographic supply concentrates in Zimbabwe, South Africa, and Saudi Arabia, with raw material dependencies on spodumene ore, sulfuric acid reagents, and diesel fuel for remote mining fleets. Single-source vulnerability runs through Zimbabwe's Bikita and Arcadia districts, where beneficiation enforcement risks concentrate supply security. Distribution runs through South African port infrastructure at Richards Bay and Coega, with Red Sea hubs emerging as alternative logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle-East and Africa lithium market sits in a technology-transition phase, with direct acid-roast hydroxide pathways displacing legacy carbonate intermediate stages. This shift rewards capital deployment into integrated conversion capacity and penalizes export-only concentrate strategies.
For Market Incumbents: Hedge against beneficiation policy tightening by accelerating domestic converter construction in Zimbabwe and South Africa ahead of regulatory threshold increases. Secure captive offtake through equity participation in Saudi Red Sea hub developments, insulating volume from merchant market volatility. Prioritize REACH certification investment to maintain European pricing tier access as traceability requirements intensify.
For New Entrants and Emerging Players: Capture underpenetrated Nigerian pegmatite provinces in Kaduna and Nasarawa states before regulatory framework crystallization locks in incumbent positions. Target distributed modular concentrator architectures that reduce grid dependency and enable phased capital deployment. Lead with direct shipping ore qualification programs that bypass carbonate stages and align with high-nickel cathode manufacturer feedstock requirements.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated mine-to-hydroxide developers given beneficiation enforcement intensity and automotive OEM captive supply imperatives. Long-term viability favors operators with secured port access and renewable energy offtake agreements that dampen diesel price exposure. Watch Zimbabwe's central bank currency retention rule modifications as the critical inflection signal for foreign operator working capital structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conversion Capacity | Zimbabwe's beneficiation mandates require domestic hydroxide circuits to maintain export licensing eligibility. |
| REACH Certification Program | European Chemicals Agency traceability requirements create premium pricing tiers for compliant African suppliers. |
| Red Sea Hub Joint Venture | Saudi SFDA-aligned processing partnerships reduce logistics costs for European-bound battery-grade material. |
| Hybrid Microgrid Deployment | Solar-diesel generation blends address energy input cost volatility at remote spodumene extraction sites. |
| Direct Shipping Ore Qualification | Acid-roast technology enables bypassing carbonate intermediates to capture hydroxide margin premiums. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews across mine operators, chemical conversion engineers, and cathode manufacturer procurement leads. Zimbabwe's central bank published retention rules, South Africa's Department of Mineral Resources and Energy licensing databases, and Saudi industrial investment framework disclosures provided jurisdictional policy baselines. Bottom-up project economics modeling triangulated against top-down demand forecasts from automotive OEM electrification roadmaps.
Data-stream reconciliation across concentrate export volumes, converter capacity announcements, and battery cell production schedules shaped the analytical framework. Segmentation dimensions modeled include product type, end-use application, deployment configuration, and market channel across the projection horizon. CAGRs derived from capacity-weighted supply growth and demand pull from high-nickel cathode formulations. Lithium-specific inputs encompassed spodumene head grades, acid-roast energy intensities, and beneficiation compliance cost structures.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Zimbabwean regulatory enforcement intensity, European REACH protocol expansion, and automotive OEM platform electrification commitments. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Bauxite Mining Market
Metals & Minerals
Moissanite Market
Metals & Minerals
North America and EMEA Ferrosilicon Market
Metals & Minerals
India CRNO Steel Lamination Market
Metals & Minerals
Cobalt Sulphate Market
Metals & Minerals
Global Artificial Rutile Market
Metals & Minerals
Direct Reduced Iron (DRI) Market
Metals & Minerals
Wegscheiderite Market
Metals & Minerals
Global Antimony Market
Metals & Minerals
Chromite Market
Metals & Minerals
20MnCr5 Steel Market
Metals & Minerals
Californium Market
Metals & Minerals
Global Magnesium Oxide Market
Metals & Minerals
Chromium Mining Market
Metals & Minerals
Global Magnesium Carbonate Minerals Market
Metals & Minerals
Titanium Ore Market