
 Global Lithium Market | 2026-2036
Global Lithium Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lithium Market Outlook
Battery-grade specification upgrades are unwinding across cathode supply chains as automakers enforce stricter purity thresholds. Albemarle Corporation leverages its Chilean brine assets and vertical processing footprint to sustain long-term cathode partnerships. Ganfeng Lithium anchors its position through captive offtake agreements with Australian spodumene miners and integrated refining in China.
Lithium is a soft, highly reactive alkali metal with atomic number 3, extracted primarily from spodumene hard-rock deposits and continental brine aquifers, then converted into lithium carbonate or hydroxide for electrochemical applications. Battery-grade material commands premium positioning due to sub-20 ppm impurity ceilings demanded by nickel-cobalt-manganese cathode formulations. Electric vehicles dominate offtake volumes, while renewable energy storage represents the fastest-expanding application segment as grid-scale battery installations multiply. The automotive manufacturer end-user channel captures the deepest margin pools through multi-year supply contracts with volume floors.
The EPA enforces lithium extraction wastewater standards in the United States, while China's MEE administers dual carbon compliance for domestic refining capacity expansions. REACH and the EU Green Deal mandate supply-chain carbon disclosures for lithium imported into European battery plants. Stakeholders must monitor brine extraction water rights adjudications and hard-rock permitting timelines as the primary variables affecting supply elasticity.
Market Dynamics
The global lithium market operates under acute supply-side tension as battery-grade purification requirements tighten faster than brine and hard-rock expansion timelines. Automakers now enforce sub-20 ppm impurity ceilings that strain incumbent processing infrastructure.
Growth Catalysts
- EU Green Deal battery mandates:Carbon disclosure requirements for imported lithium are accelerating European cathode plant localization and direct offtake contracting with Chilean and Australian producers.
- Grid-scale energy storage deployment:Utility-scale battery installations are diversifying lithium demand beyond automotive channels into multi-hour duration storage systems.
- Direct shipping ore (DSO) to chemical-grade conversion:Australian spodumene miners are bypassing intermediate concentrate stages, tightening feedstock-to-cathode timelines.
Market Restraints
- Atacama water rights adjudication:Chilean environmental courts have suspended expansion permits pending groundwater impact reviews, freezing brine extraction growth in the world's lowest-cost production zone.
- Sulfuric acid and reagent cost volatility:Hard-rock conversion facilities face margin compression from energy-intensive acid roasting inputs tied to natural gas and sulfur markets.
- Sodium-ion cathode substitution:CATL and BYD are commercializing sodium-ion cells for sub-300 km range vehicles, threatening lithium's monopoly in entry-level electric mobility.
Strategic Opportunities
- Argentina's Cauchari-Olaroz development corridor:Greenfield brine projects in Jujuy Province offer untapped low-carbon extraction potential with favorable provincial fiscal terms.
- Solid-state battery electrolyte precursor demand:Next-generation sulfide and oxide solid electrolytes require ultra-high-purity lithium metal, opening premium pricing tiers.
- US Inflation Reduction Act critical mineral credits:Domestic content bonuses are incentivizing North American hard-rock development and refining joint ventures.
Industry Challenges
- Process engineer scarcity in hydrometallurgy:The talent pipeline for solvent extraction and crystallization optimization cannot match capacity expansion schedules.
- Battery-grade certification timelines:Cathode manufacturers require 12-18 month qualification cycles for new lithium sources, delaying revenue recognition from greenfield projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lithium Market |
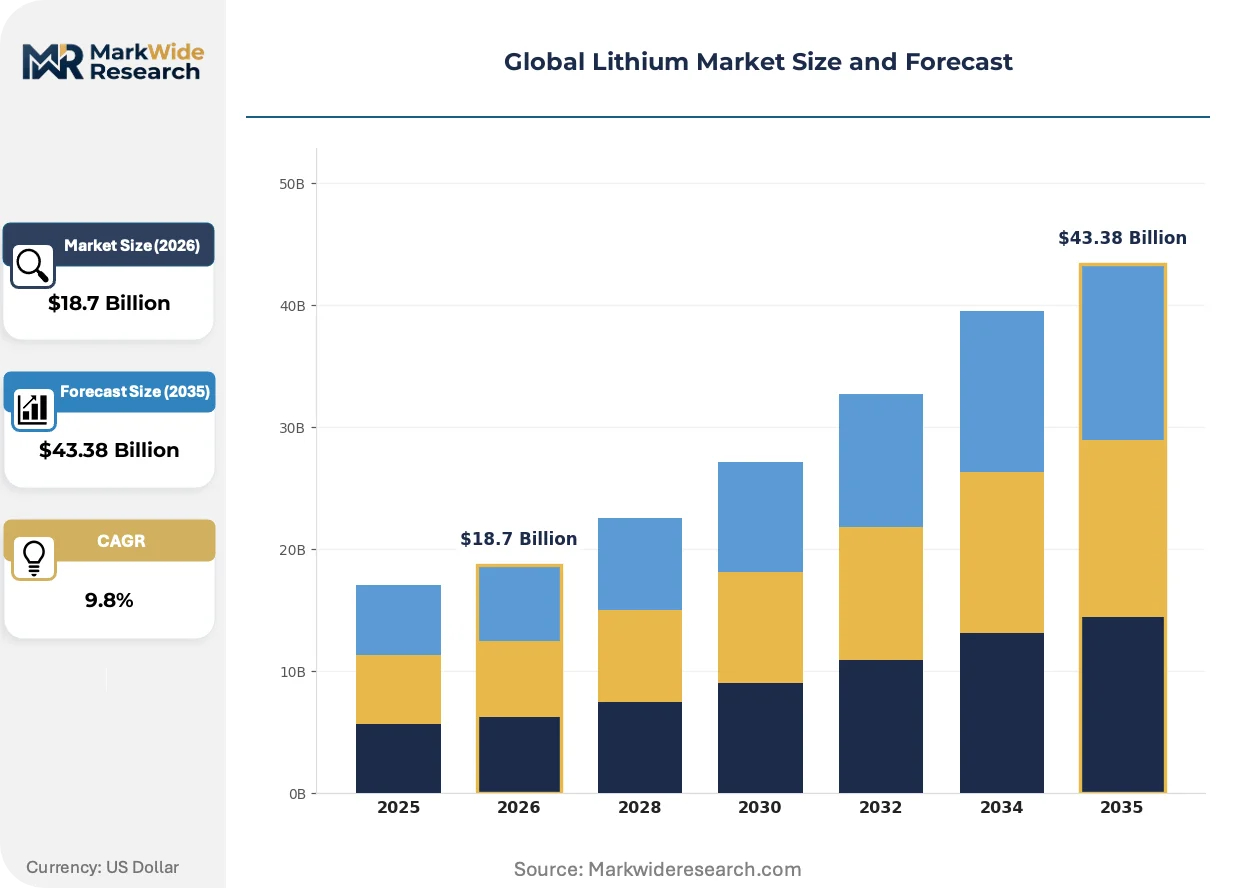
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $43.38 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Grade, Industrial Grade, Pharmaceutical Grade, Alloy Grade Application: Electric Vehicles, Smartphones, Laptops, Renewable Energy Storage End User: Automotive Manufacturers, Electronics Companies, Energy Providers, Aerospace Industry Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | Albemarle Corporation, Sociedad Química y Minera (SQM), Ganfeng Lithium, Tianqi Lithium, Rio Tinto, Mineral Resources Limited, Livent Corporation, Lithium Americas Corp., Arcadium Lithium, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lithium Market Strategic Shifts
Direct lithium extraction technologies are compressing production timelines from years to months, while regulatory carbon accounting is rewiring trade flows and procurement geography.
Direct lithium extraction (DLE) using selective sorbents and electrochemical cells is supplanting traditional solar evaporation in brine processing. Rio Tinto and Controlled Thermal Resources are deploying DLE pilots in Argentina and California that bypass 18-month evaporation ponds. This compression is enabling battery-grade output within 90 days of brine pumping, restructuring project finance assumptions around working capital and offtake timing.
REACH and the EU Battery Regulation now mandate supply-chain carbon intensity disclosures for lithium imported into European gigafactories. The industrial consequence is a bifurcation between low-carbon Chilean brine and higher-emission Australian hard-rock in contract negotiations. German and Hungarian cathode plants are responding by securing long-term offtake from Atacama producers with verified water recycling and renewable energy integration.
Automakers are consolidating cathode procurement through multi-year supply contracts with volume floors and price collars, displacing spot-market purchasing. This behavioral shift concentrates negotiating power with vertically integrated lithium-chemical producers. The pattern is most visible in China, where BYD and CATL have locked five-year hydroxide supply directly with Ganfeng and Tianqi, bypassing traditional trading houses and merchant processors.
Global Lithium Market Segmentation
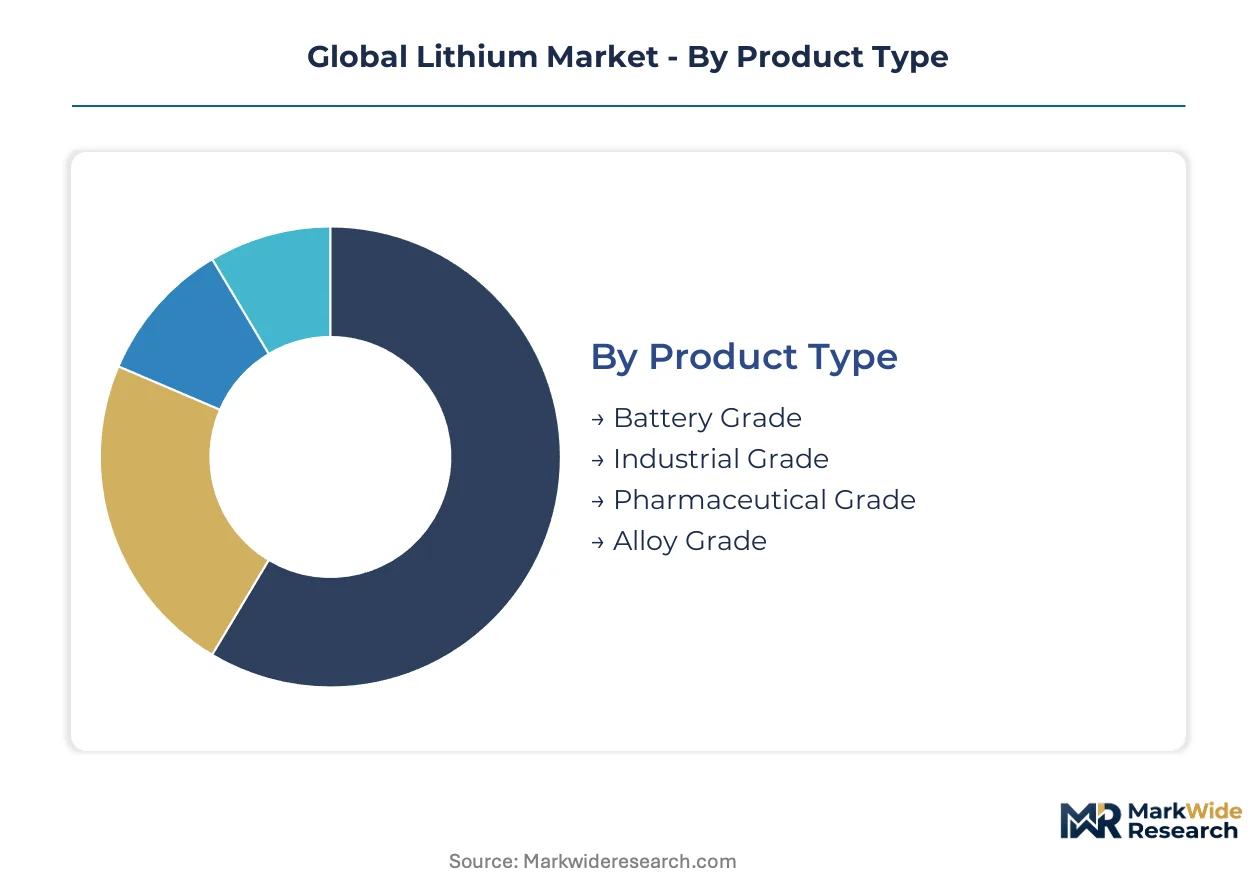
Lithium market segmentation reveals how purity specifications and application requirements split procurement across distinct commercial channels. Each segment carries different certification burdens, pricing tiers, and supply chain security protocols that reshape competitive positioning.
Product Type:
Battery-grade material flows predominantly through direct sales channels with multi-year offtake agreements, while industrial and pharmaceutical grades circulate via distributors with shorter contract horizons.
- Battery Grade:Lithium carbonate and hydroxide meeting sub-20 ppm impurity ceilings for nickel-cobalt-manganese cathode formulations. Demand concentrates with German and Hungarian cathode plants under EU Battery Regulation carbon disclosure mandates, forcing qualification cycles that freeze out unverified sources.
- Industrial Grade:Moderate-purity lithium compounds serving glass, ceramics, and lubricant manufacturing with less stringent trace-metal limits. Procurement runs through specialty chemical distributors in China and the United States, where EPA wastewater standards for hard-rock processing add compliance overhead.
- Pharmaceutical Grade:Ultra-high-purity lithium salts for psychiatric and medical applications requiring GMP certification.
- Alloy Grade:Metallurgical lithium for aluminum smelting and lightweight aerospace alloys.
Battery Grade dominates installed base. Pharmaceutical Grade is where expansion concentrates.
Application:
Volume distribution across applications correlates directly with cathode chemistry evolution and grid-scale deployment timelines, creating divergent margin profiles.
- Electric Vehicles:Long-range battery packs utilizing high-nickel cathode chemistries demanding battery-grade hydroxide with tight particle size distribution. BYD and CATL in China have locked five-year supply directly with integrated producers, bypassing merchant traders entirely.
- Renewable Energy Storage:Utility-scale lithium iron phosphate installations for multi-hour grid buffering. Installations are climbing the fastest as California and Texas interconnection queues swell, though sodium-ion substitution threatens the segment's lithium intensity.
- Smartphones:Cobalt-dense lithium cobalt oxide cells for premium consumer electronics.
- Laptops:Mid-tier energy density requirements with established supply chains through electronics contract manufacturers.
Electric Vehicles anchors procurement volume. Renewable Energy Storage is where contract innovation concentrates.
End User:
Customer concentration determines whether lithium moves through captive supply arrangements or open market purchasing, with automotive channels demanding the deepest integration.
- Automotive Manufacturers:OEMs enforcing direct cathode partnerships with volume floors and price collars, displacing spot-market exposure. German automakers are securing long-term offtake from Atacama producers with verified renewable energy integration to satisfy EU Green Deal benchmarks.
- Energy Providers:Utility and independent power developers procuring for grid-scale battery installations. Procurement concentrates through engineering-procurement-construction contractors in the United States leveraging IRA critical mineral credits for domestic content bonuses.
- Electronics Companies:Consumer device assemblers with established distributor relationships.
- Aerospace Industry:Specialized alloy and battery applications with stringent traceability requirements.
Automotive Manufacturers dominate contract value. Energy Providers is where procurement modality innovation concentrates.
Distribution Channel:
Channel selection reflects buyer scale and certification burden, with large-volume end users abandoning intermediaries to secure supply certainty.
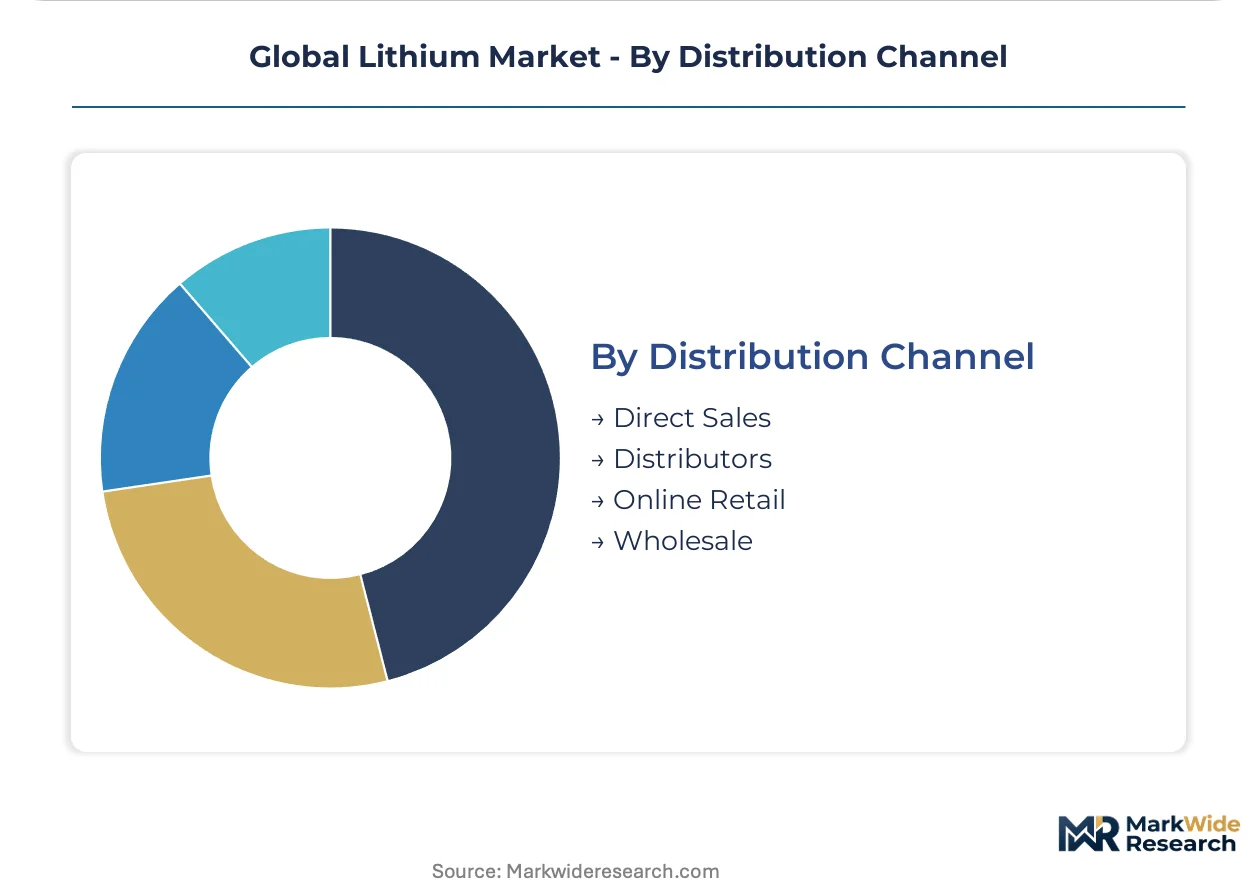
- Direct Sales:Multi-year supply contracts with automakers and cathode plants specifying volume floors, price collars, and carbon intensity verification. This channel is gaining share fastest as REACH-mandated supply-chain disclosures make provenance tracking mandatory for European gigafactory access.
- Distributors:Specialty chemical handlers serving mid-scale industrial and pharmaceutical accounts with shorter-term availability.
- Online Retail:Small-laboratory and research-grade quantities through certified chemical suppliers.
- Wholesale:Bulk industrial grade movement through commodity trading houses.
Direct Sales dominates contract value. Distributors is where service differentiation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chilean brine operations and Australian hard-rock mines concentrate over three-quarters of battery-grade lithium feedstock. This geographic dualism creates divergent carbon footprints that REACH-mandated disclosures are amplifying in European procurement decisions.
Chile
Atacama salt flats supply the lowest-cost battery-grade lithium carbonate globally. Chilean environmental courts have suspended expansion permits pending groundwater impact reviews under domestic water rights adjudication. Antofagasta and Calama host Albemarle and SQM processing infrastructure where direct shipping ore conversion timelines are compressing.
Australia
Pilbara and Goldfields spodumene belts dominate hard-rock concentrate exports to Chinese refiners. The country's critical minerals strategy channels investment into downstream chemical-grade conversion. Kwinana and Kemerton host integrated hydroxide plants where sulfuric acid roasting energy intensity draws EPA-equivalent state scrutiny.
China
Jiangxi and Sichuan provinces anchor integrated refining from Australian concentrate imports. MEE-administered dual carbon compliance is tightening emissions benchmarks for domestic capacity expansions. Yichun and Shehong chemical parks concentrate Ganfeng and Tianqi processing assets with captive offtake from Qinghai brine.
Argentina
Jujuy Province's Cauchari-Olaroz corridor offers untapped low-carbon brine extraction potential. Provincial fiscal terms favor greenfield development against Chilean regulatory freeze. Salta and Catamarca salt flats host Rio Tinto and Lithium Americas pilots where direct lithium extraction is supplanting solar evaporation.
United States
California's Salton Sea geothermal brines and Nevada's Thacker Pass clay deposits represent North American hard-rock alternatives. IRA critical mineral credits incentivize domestic content bonuses for cathode manufacturers. Silver Peak and Imperial Valley host Controlled Thermal Resources and Berkshire Hathaway Energy pilots where DLE timelines are restructuring project finance assumptions.
Global Lithium Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the lithium value chain. The market structure splits between vertically integrated brine-chemical producers and hard-rock miners dependent on Chinese refining partnerships. Three archetypes dominate: Atacama-based low-carbon brine operators, Australian spodumene exporters with captive Chinese offtake, and integrated Chinese refiners with backward control over Qinghai brine. Competitive moves concentrate on direct lithium extraction licensing and multi-year automaker supply contracts with carbon intensity verification clauses.
Among Chilean brine-chemical specialists, Albemarle Corporation and Sociedad Química y Minera exemplify the low-carbon extraction archetype that German automakers are prioritizing under EU Battery Regulation mandates. Ganfeng Lithium and Tianqi Lithium occupy positions within the integrated Chinese refining tier where captive Australian concentrate offtake and Qinghai brine integration create supply security. These four entities represent the dominant competitive anchors across the cost-carbon spectrum that is bifurcating contract negotiations.
| Leading Market Players |
|---|
| Albemarle Corporation |
| Sociedad Química y Minera (SQM) |
| Ganfeng Lithium |
| Tianqi Lithium |
| Rio Tinto |
| Mineral Resources Limited |
| Livent Corporation |
| Lithium Americas Corp. |
| Arcadium Lithium |
| Others |
Value Chain & Pricing Dynamics
EU Battery Regulation carbon disclosure mandates gate both supply qualification and price differentiation simultaneously, forcing cathode manufacturers to pay premiums for Atacama-sourced material with verified renewable energy integration while discounting unverified hard-rock alternatives.
Pricing Analysis
EU Battery Regulation carbon disclosure mandates dictate the pricing tier structure across battery-grade lithium procurement. Three-tier pricing stratifies across premium certified-low-carbon, standard traceable-origin, and economy unverified-source levels. Price differentiation hinges on certification grade and volume scale, with German automakers locking five-year offtake at volume floors. Cost compression in economy-tier hard-rock material is intensifying because sulfuric acid reagent volatility squeezes conversion margins. Spot-market buyers in industrial-grade channels exhibit highest price sensitivity, while automotive OEMs with volume-floor contracts demonstrate lowest sensitivity due to supply security prioritization.
Supply Chain Analysis
Container availability constraints on the Australia-China spodumene concentrate trade lane compress working capital cycles for hard-rock exporters. Geographic supply concentrates in Chile, Australia, and Argentina, with Atacama brine and Pilbara spodumene feeding divergent processing pathways. Raw material dependencies center on sulfuric acid for acid roasting, natural gas for calcination energy, and freshwater for brine extraction operations. Single-source vulnerability runs through Chilean environmental court adjudications freezing expansion permits in the lowest-cost production zone. Distribution runs through direct multi-year offtake contracts displacing spot-market purchasing for battery-grade volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lithium market approaches a platform-economics inflection as solid-state battery electrolyte precursors demand ultra-high-purity lithium metal, rewiring interoperability standards between cathode manufacturers and upstream refiners.
For Market Incumbents: Shield market position through backward integration into Argentine Cauchari-Olaroz brine assets and captive DLE technology licensing. Sodium-ion cathode substitution from CATL and BYD threatens lithium's monopoly in entry-range electric mobility, making carbon-intensity verification investment the priority defensive lever against European procurement exclusion. For New Entrants and Emerging Players: Anchor in Argentina's Jujuy Province greenfield corridor where provincial fiscal terms favor development against Chilean regulatory freeze. The most penetrable white-space sits in solid-state battery electrolyte precursor supply, with direct lithium extraction joint ventures offering the strongest go-to-market angle through compressed production timelines. For Investors and Strategic Acquirers: IRA critical mineral credits reshape the acquisition landscape toward North American hard-rock development and refining joint ventures qualifying for domestic content bonuses. Long-term viability centers on vertically integrated producers with captive brine or concentrate supply and certified low-carbon processing infrastructure. The signal to monitor is Atacama water rights court rulings as inflection indicator for Chilean supply elasticity.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Lithium Extraction Licensing | Rio Tinto and Controlled Thermal Resources pilots compress battery-grade output from 18-month evaporation to 90-day timelines. |
| Carbon Intensity Certification Investment | Verified renewable energy integration at Atacama processing plants secures German automaker offtake under EU Battery Regulation. |
| Argentine Greenfield Development | Jujuy Province fiscal terms attract capital fleeing Chilean environmental court permit suspensions. |
| Automotive Direct Offtake Lock-in | BYD and CATL five-year hydroxide supply contracts with Ganfeng bypass merchant traders entirely. |
| Solid-State Electrolyte Precursor Supply | Ultra-high-purity lithium metal demand from sulfide and oxide solid electrolytes opens premium pricing tiers. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with lithium extraction executives, cathode plant procurement leads, and automotive supply chain strategists; and secondary validation through SEC filings, Chilean environmental court dockets, customs trade data, and EU Battery Regulation implementation guidance. Bottom-up project-level capacity modeling triangulated against top-down end-use demand aggregation across electric vehicle and grid-scale storage applications.
Across the analysis window, the forecast framework modeled segmentation dimensions spanning product grade tier, cathode chemistry application, end-user concentration, and regional production hub regulatory cluster. CAGRs derived from supply elasticity functions incorporating permitting timeline distributions and DLE technology adoption curves. Industry-specific inputs included brine extraction water rights adjudication schedules and sulfuric acid reagent cost volatility indices.
Underlying assumptions cover sustained electric vehicle penetration trajectories and grid-scale storage deployment rates, with deviation risk concentrated in sodium-ion substitution velocity and Chilean regulatory reopening timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Andalusite Market
Metals & Minerals
Saudi Arabia and GCC Ferrosilicon Market
Metals & Minerals
Global Magnesium Carbonate Minerals Market
Metals & Minerals
Zinc Sulfate Market
Metals & Minerals
Cobalt Nitrate Market
Metals & Minerals
Wegscheiderite Market
Metals & Minerals
Nickel Nano Powder Market
Metals & Minerals
Lithium Ingots Market
Metals & Minerals
Diamond Market
Metals & Minerals
Californium Market
Metals & Minerals
US Coated Steel Market
Metals & Minerals
Sodium Tungstate Market
Metals & Minerals
Silver Salt Market
Metals & Minerals
Iron Ore Pellets Market
Metals & Minerals
Global Gold Potassium Cyanide Market
Metals & Minerals
Gemstones Market