
 Chromite Market | 2026-2036
Chromite Market Size, Share, and Industry Trends Forecast 2026-2036
Chromite Market Analysis
Qualified metallurgical engineers in Bushveld Complex mining districts is collapsing as aging cohorts retire faster than universities replenish pipelines. Samancor Chrome leverages its integrated smelter network to sustain ferrochrome output despite ore grade decline. Glencore Plc anchors its position through captive logistics from Limpopo mines to Richards Bay export terminals. Tata Steel Mining Ltd. differentiates via captive chromite supplies feeding its Jamshedpur stainless steel complex.
Chromite is an iron chromium oxide mineral (FeCr₂O₄) with chromium content typically ranging from 46% to 55% Cr₂O₃, extracted through open-pit and underground methods before concentration via gravity separation and flotation. Its primary industrial purpose is serving as the exclusive commercial source of chromium for stainless steel alloying, chemical chromate production, and high-temperature refractory linings. Metallurgical grade dominates value capture due to ferrochrome's irreplaceable role in austenitic steel formulations, while chemical grade claims the fastest expansion trajectory as dichromate derivatives penetrate water treatment and pigment applications. Refractory grade occupies a stable niche serving cement kiln and glass furnace operators who prioritize MgO-Cr₂O₃ brick performance under thermal shock above 1700°C.
South Africa's Department of Mineral Resources and Energy enforces beneficiation thresholds that restrict raw ore exports and compel domestic ferrochrome investment, while India's Ministry of Mines monitors Odisha Mining Corporation leases under National Mineral Exploration Trust guidelines. REACH registration requirements in Europe classify hexavalent chromium compounds as Substances of Very High Concern, redirecting chemical-grade demand toward trivalent processing routes. Turkey's mining environmental permits under its Environmental Impact Assessment Regulation shape expansion timelines for Eskisehir chemical-grade concentrators. Stakeholders must weigh ore reserve depletion against smelter power cost structures when committing capital to integrated versus merchant processing configurations.
Market Dynamics
South Africa's beneficiation mandates are redirecting chromite ore flows toward domestic ferrochrome smelters, compressing export availability while Asian stainless steel mills scramble for metallurgical-grade supply security.
Growth Catalysts
- Beneficiation Mandates:South Africa's Department of Mineral Resources and Energy enforces domestic processing thresholds that compel ferrochrome investment and anchor smelter capacity expansion.
- Stainless Steel Alloy Specifications:Nickel-chrome ratio tightening in austenitic formulations is pulling additional chromite units into Asian mill offtake contracts.
- Eskisehir Chemical Clusters:Turkey's integrated processing infrastructure concentrates dichromate derivative output for European refractory and water treatment buyers.
Market Restraints
- Power Cost Volatility:Ferrochrome smelters in South Africa face Eskom tariff instability that erodes margin structures on energy-intensive submerged arc furnace operations.
- Reserve Grade Decline:Bushveld Complex ore bodies exhibit falling Cr₂O₃ head grades, forcing deeper stripping ratios and concentration circuit upgrades.
- Hexavalent Chromium Restrictions:REACH Substances of Very High Concern classification redirects chemical-grade demand toward trivalent processing routes with higher capital intensity.
Strategic Opportunities
- Odisha Lease Rationalization:India's National Mineral Exploration Trust guidelines create consolidation pathways for chromite tenements under unified exploration frameworks.
- Trivalent Conversion Infrastructure:Greenfield chemical-grade facilities in Turkey and India bypass legacy hexavalent liability exposure while capturing pigment and water treatment demand.
- Refractory Recycling Loops:MgO-Cr₂O₃ brick recovery from cement kiln rebuilds is opening secondary chromium feedstock channels in European circular economy frameworks.
Industry Challenges
- Qualified Engineer Scarcity:Bushveld Complex mining districts face collapsing metallurgical engineering pipelines as university graduation rates trail retirement cohorts.
- Environmental Permit Timelines:Turkey's Environmental Impact Assessment Regulation stretches Eskisehir concentrator expansion schedules, delaying capacity commissioning.
- Smelter Configuration Lock-In:Integrated versus merchant processing commitments freeze capital for decades, constraining flexibility against power cost and ore grade trajectories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chromite Market |
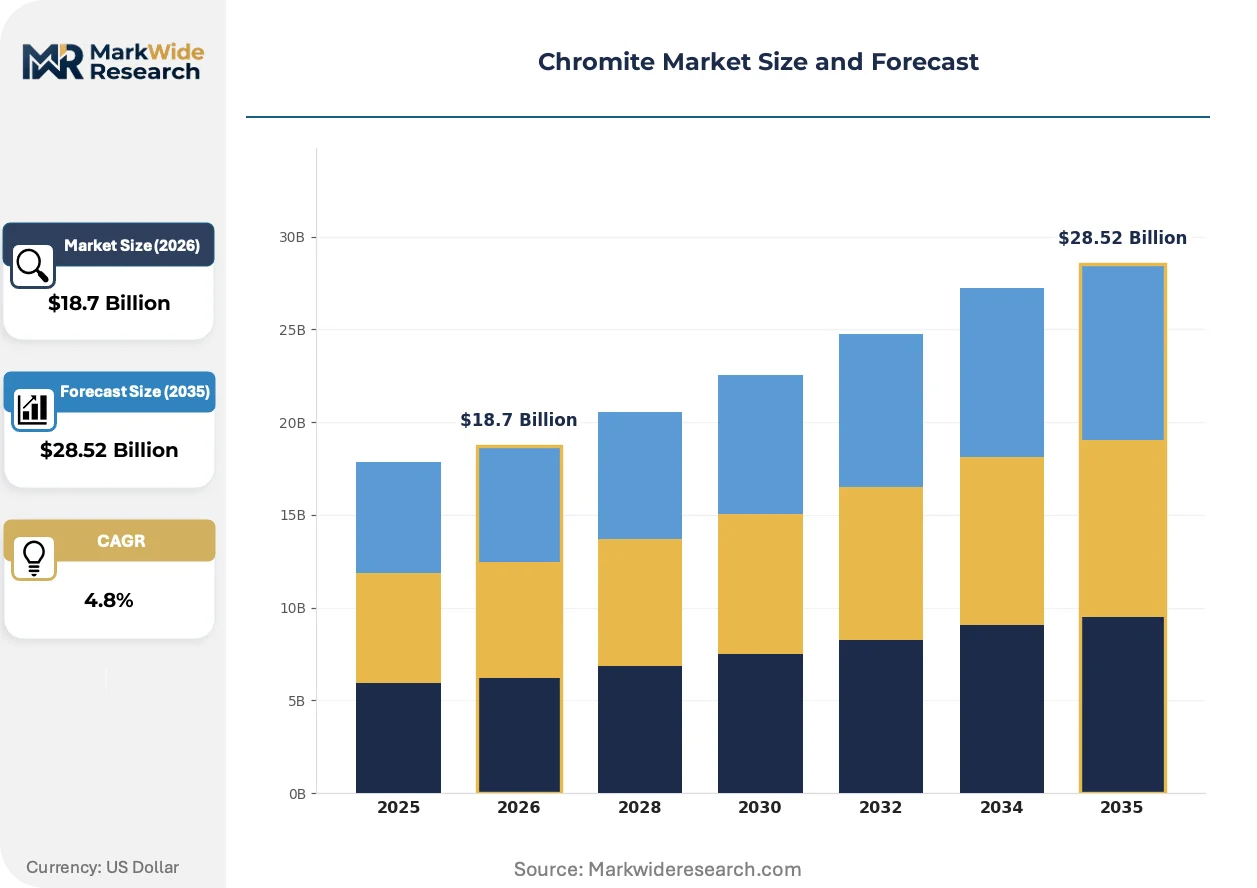
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metallurgical Grade, Chemical Grade, Refractory Grade, Foundry Grade Application: Steel Production, Production of Ferrochrome, Chemical Manufacturing, Refractory Materials End User: Metals and Mining, Chemicals, Construction, Automotive Distribution Channel: Direct Sales, Distributors, E-commerce, Traders |
| Companies Covered | Tata Steel Mining Ltd., Assmang Proprietary Limited, Glencore Plc, Tharisa Plc, CVK Madencilik, Samancor Chrome, Odisha Mining Corporation Ltd., Kermas Investment Group, Eurasian Resources Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chromite Market Emerging Trajectories
Chromite value chains are bifurcating between energy-intensive ferrochrome consolidation in southern Africa and chemical-grade specialization around Turkish processing clusters serving European environmental compliance.
Pre-reduced pellet technology is displacing conventional lumpy ore charging in submerged arc furnaces. Chinese stainless steel mills adopt prereduced feed at accelerating rates to cut specific power consumption per ton of contained chromium. This shift is displacing traditional lump ore premiums and compressing merchant ore trader margins across Richards Bay export channels.
REACH authorization requirements for hexavalent chromium compounds are forcing dichromate producers toward trivalent electrolytic conversion or alternative feedstock chemistry. European refractory and pigment manufacturers now audit supplier processing routes for SVHC exposure liability. Chemical-grade chromite demand is concentrating in Turkish and Indian supply bases with pre-certified trivalent output streams.
Long-term offtake contracting is displacing spot market procurement for metallurgical-grade chromite. Asian stainless steel mills now secure multi-year supply agreements directly with South African integrated producers, bypassing traditional merchant traders. This pattern is most visible in nickel-chrome alloy specifications where mills prioritize concentrate consistency over price arbitrage.
Chromite Market Segmentation
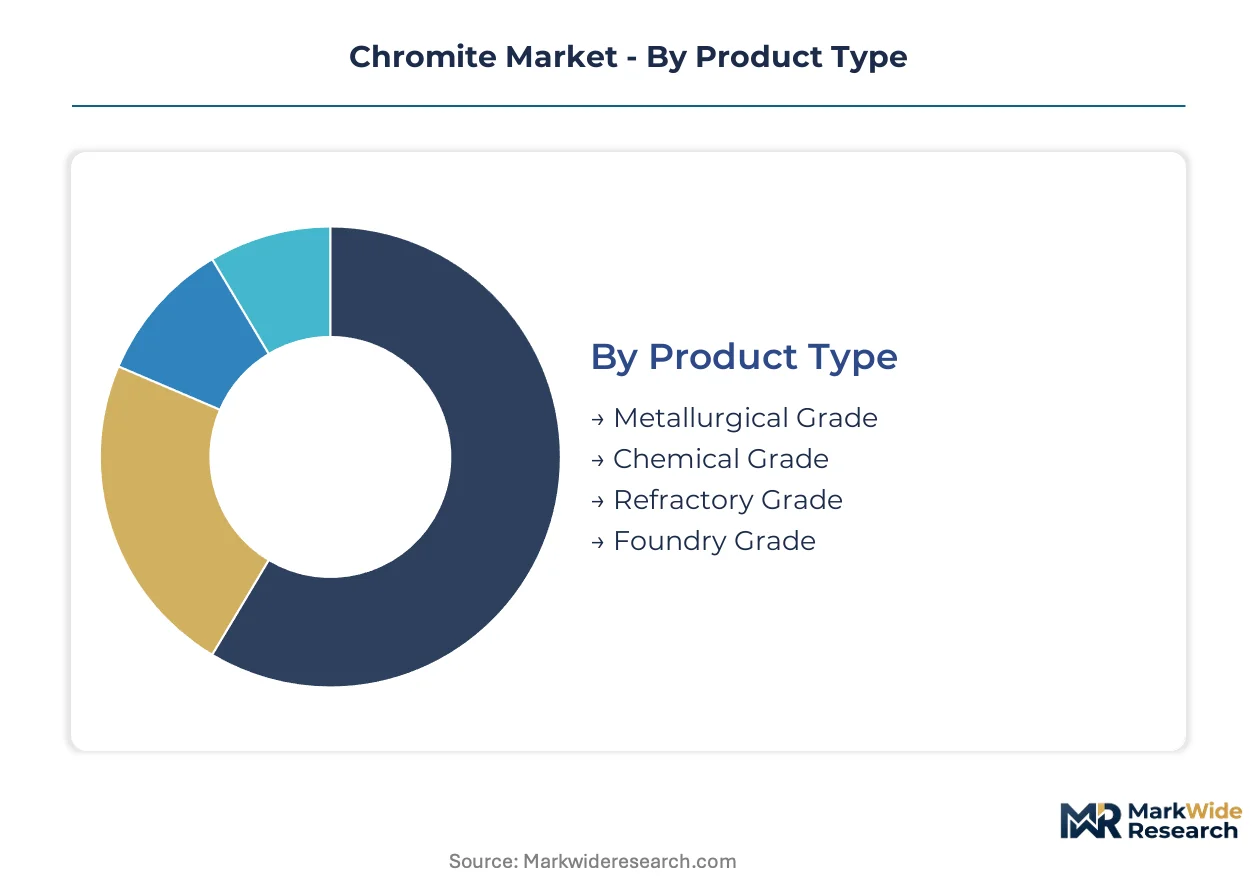
Chromite market segmentation reveals how substitution pressures and value chain positioning determine margin capture across processing routes. Grade specifications and end-use requirements create distinct competitive arenas where ore quality, energy costs, and regulatory compliance intersect.
Product Type:
Metallurgical grade faces intensifying substitution risk from scrap-based stainless steel recycling and nickel-only austenitic formulations, while chemical grade confronts hexavalent chromium regulatory phase-outs driving trivalent process conversions.
- Metallurgical Grade:Cr₂O₃ content of 46-55% with low silica specifications serves submerged arc furnace ferrochrome production. Demand concentrates in Asian stainless steel mills under tightening nickel-chrome alloy ratios that pull additional chromite units into long-term offtake contracts.
- Chemical Grade:Higher chromium purity with controlled iron levels enables dichromate and chromic acid synthesis. Turkey's Eskisehir processing clusters dominate European supply as REACH SVHC classifications redirect demand toward pre-certified trivalent output streams.
- Refractory Grade:MgO-Cr₂O₃ brick formulations for cement and glass furnaces above 1700°C thermal shock thresholds.
- Foundry Grade:Specialized sand applications in metal casting with specific AFS grain fineness requirements.
Metallurgical grade retains volume leadership; chemical grade holds the steepest expansion curve.
Application:
Cost tier stratification separates energy-intensive pyrometallurgical routes from lower-temperature hydrometallurgical and refractory fabrication processes.
- Steel Production:Direct chromite addition in stainless steelmaking bypasses ferrochrome intermediate steps for specific alloy grades. South African beneficiation mandates compress raw ore export availability, forcing Asian mills toward integrated producer direct contracts.
- Production of Ferrochrome:Submerged arc furnace reduction of lumpy ore or pre-reduced pellets generates chromium units for austenitic steel alloying. Eskom tariff volatility erodes smelter margins and accelerates Chinese adoption of prereduced feed technologies.
- Chemical Manufacturing:Dichromate derivatives for pigments, water treatment, and leather tanning face trivalent conversion capital requirements.
- Refractory Materials:MgO-Cr₂O₃ brick linings for cement kilns and glass furnaces operate in stable replacement-demand cycles.
Ferrochrome production commands the largest volume share; chemical manufacturing applications are climbing the fastest.
End User:
Customer type fragmentation splits between vertically integrated stainless steel producers securing captive supply and merchant chemical processors exposed to feedstock price volatility.
- Metals and Mining:Integrated ferrochrome smelters and stainless steel complexes dominate procurement through long-term offtake agreements. Samancor Chrome and Glencore Plc anchor supply security via captive logistics from Bushveld Complex mines to Richards Bay terminals.
- Chemicals:Dichromate and chromic acid producers in Turkey and India serve European pigment and water treatment markets under trivalent certification requirements.
- Construction:Refractory brick demand from cement kiln operators prioritizes thermal shock performance over chromium unit cost.
- Automotive:Stainless steel exhaust and trim specifications drive ferrochrome demand through tiered supplier networks.
Metals and mining retains volume leadership; chemicals holds the steepest expansion curve.
Distribution Channel:
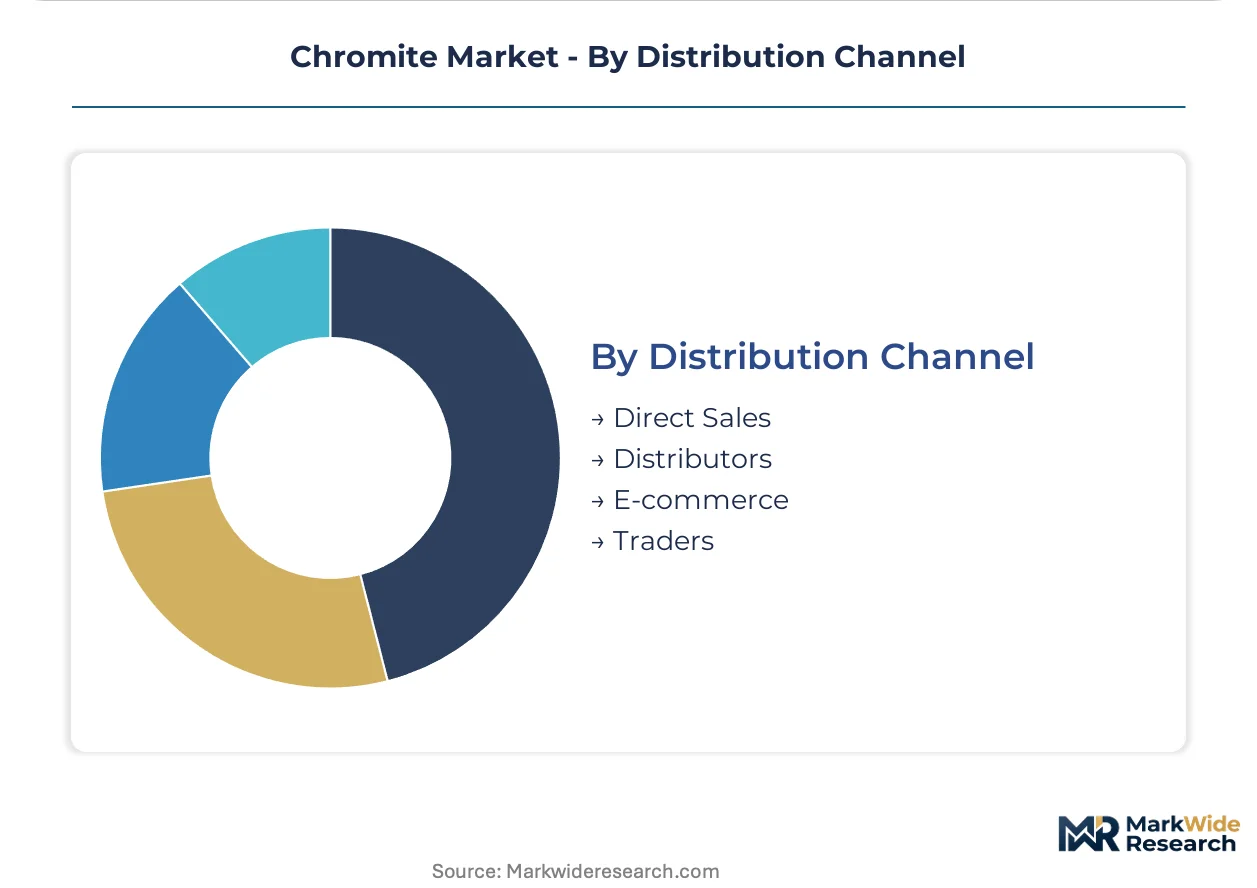
Supply concentration geography determines channel viability, with integrated producer direct sales displacing traditional merchant traders in metallurgical-grade flows.
- Direct Sales:Long-term offtake contracts between South African integrated producers and Asian stainless steel mills eliminate intermediary margins. Tata Steel Mining Ltd. exemplifies captive supply feeding its Jamshedpur complex.
- Distributors:Regional stockholding for refractory and foundry grades serves fragmented end-user bases with just-in-time delivery requirements.
- E-commerce:Limited penetration in bulk mineral commodities constrained by logistics complexity and quality verification needs.
- Traders:Merchant ore traders face margin compression as pre-reduced pellet adoption displaces traditional lump ore premiums across Richards Bay export channels.
Direct sales retains volume leadership; distributor networks hold the steepest expansion curve in specialty grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. South African ore flows predominantly into domestic ferrochrome smelters under beneficiation mandates, while Turkish chemical-grade output serves European environmental compliance markets. Asian stainless steel mills secure metallurgical-grade supply through direct long-term contracts rather than spot procurement.
South Africa
The Bushveld Complex hosts the world's largest chromite reserves, with ferrochrome smelters consuming the bulk of domestic ore output. The Department of Mineral Resources and Energy enforces beneficiation thresholds that restrict raw ore exports and compel investment in submerged arc furnace capacity. Limpopo mining districts feed integrated logistics corridors terminating at Richards Bay export terminals.
Turkey
Eskisehir province concentrates chemical-grade chromite processing infrastructure for dichromate derivative production. The Environmental Impact Assessment Regulation shapes expansion timelines for concentrator capacity serving European refractory and pigment buyers. REACH Substances of Very High Concern classifications redirect demand toward pre-certified trivalent output streams from Turkish facilities.
India
Odisha's chromite belt supplies captive requirements for Tata Steel's Jamshedpur stainless steel complex and merchant ferrochrome producers. The National Mineral Exploration Trust monitors lease compliance under Ministry of Mines guidelines. Sukinda Valley mining districts face consolidation pressure as smaller tenements rationalize under unified exploration frameworks.
China
Stainless steel mills accelerate adoption of pre-reduced pellet feed to cut specific power consumption in nickel-chrome alloy production. MIIT industrial policy encourages domestic ferrochrome capacity expansion to reduce import dependence. Inner Mongolian and Shanxi smelter clusters source metallurgical-grade concentrate through multi-year offtake agreements with South African integrated producers.
Kazakhstan
Eurasian Resources Group anchors chromite output from the Donskoy ore mining and processing complex in the Aktobe region. The national mining code incentivizes downstream ferroalloy investment through tax stabilization agreements. Aksu ferrochrome plant capacity expansion targets Asian stainless steel mill procurement specifications.
Chromite Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in chromite value chains. Tier-one positions cluster around miners with captive smelter networks and terminal logistics control, while tier-two players concentrate in regional chemical-grade processing or merchant ore trading. Strategic archetypes span integrated ferrochrome producers, chemical-grade specialists, and diversified mining conglomerates with chromium units. Competitive moves center on long-term offtake contracting and backward integration into ore reserves.
Among South Africa-based integrated producers, Samancor Chrome and Glencore Plc exemplify the captive logistics archetype, while Tharisa Plc represents the platinum-group-metals co-product mining model with chromite as a strategic by-product stream.
| Leading Market Players |
|---|
| Tata Steel Mining Ltd. |
| Assmang Proprietary Limited |
| Glencore Plc |
| Tharisa Plc |
| CVK Madencilik |
| Samancor Chrome |
| Odisha Mining Corporation Ltd. |
| Kermas Investment Group |
| Eurasian Resources Group |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day concentrate inventory cycles at Richards Bay export terminals concentrate pricing power among South African integrated producers with captive smelter networks, while Turkish chemical-grade processors extract premiums through REACH-compliant trivalent certification. Long-term offtake contracting now dominates metallurgical-grade flows, compressing spot market liquidity and amplifying margin capture for ore reserve holders.
Pricing Analysis
Long-term offtake contracts between South African integrated producers and Asian stainless steel mills anchor pricing structures, displacing spot market benchmarks for metallurgical-grade concentrate. Price differentiation separates lumpy ore premiums from pre-reduced pellet discounts as Chinese mills adopt energy-efficient feed technologies. Cost compression in conventional lump ore channels intensifies because Eskom tariff volatility erodes smelter margins and redirects buyer procurement toward processed feed alternatives. Merchant traders exhibit highest price sensitivity as direct producer-mill contracting eliminates intermediary margins, while integrated producers with captive logistics maintain lowest sensitivity through supply security premiums.
Supply Chain Analysis
South Africa and Turkey anchor chromite supply through divergent specializations: Bushveld Complex ore bodies feed domestic ferrochrome smelters under beneficiation mandates, while Eskisehir chemical-grade concentrators serve European refractory and pigment markets. Raw material dependencies center on metallurgical coke for submerged arc furnace reduction, electricity supply from Eskom and regional grids, and sodium carbonate for dichromate synthesis. Single-source vulnerability concentrates in South Africa's Limpopo-to-Richards Bay logistics corridor where rail capacity constraints bottleneck export flows. Distribution runs through integrated producer direct sales for metallurgical grades, regional distributors for refractory and foundry specialties, and chemical processors for dichromate derivative channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chromite value chains are approaching a platform-economics inflection as REACH-compliant trivalent processing infrastructure becomes the interoperability standard for European chemical-grade procurement, locking in Turkish and Indian supply bases as certified network nodes.
For Market Incumbents: Consolidate ore reserve positions through lease rationalization in Odisha's Sukinda Valley and Bushveld Complex tenement consolidation under National Mineral Exploration Trust frameworks. Anchor smelter capacity against power cost volatility through captive renewable energy offtake or grid tariff hedging structures. Defensive positioning requires preemptive trivalent certification investment before REACH authorization deadlines eliminate hexavalent processing routes from European supply chains.
For New Entrants and Emerging Players: Lead with trivalent chemical-grade processing infrastructure in Turkey or India to capture pigment and water treatment demand migrating from hexavalent liability exposure. Target refractory recycling loops in European circular economy frameworks as the most penetrable white-space segment, leveraging MgO-Cr₂O₃ brick recovery from cement kiln rebuilds as secondary chromium feedstock. Go-to-market positioning should emphasize pre-certified REACH compliance to bypass incumbent legacy conversion costs.
For Investors and Strategic Acquirers: Long-term, this sits as a resource-nationalism hedge play because beneficiation mandates across South Africa and India are structurally redirecting ore flows toward domestic processing and compressing export availability for merchant traders. Acquisition target archetype: integrated producers with captive logistics from mine to terminal and long-term offtake contracts with Asian stainless steel mills. The signal to watch is Eskisehir concentrator commissioning timelines under Turkey's Environmental Impact Assessment Regulation, which indicate capacity inflection points for chemical-grade supply.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ore Reserves | Captive supply security insulates against South African beneficiation export restrictions and grade decline. |
| Trivalent Processing Capacity Expansion | REACH SVHC compliance unlocks European pigment and water treatment procurement channels. |
| Pre-reduced Pellet Technology Adoption | Chinese stainless steel mills cut specific power consumption in nickel-chrome alloy production. |
| Refractory Recycling Loop Development | MgO-Cr₂O₃ brick recovery opens secondary chromium feedstock under circular economy frameworks. |
| Long-term Offtake Contracting | Direct producer-mill agreements eliminate merchant trader margins and anchor volume commitments. |
Methodological Framework
A standing panel of ferrochrome smelter operations managers, stainless steel procurement leads at Asian mills, Turkish chemical-grade processing executives, and South African mining engineering consultants provided ongoing calibration across primary interview rounds. Secondary validation drew from customs and trade data, Department of Mineral Resources and Energy regulatory filings, ECHA REACH authorization databases, and SEC 10-K disclosures from diversified mining conglomerates. Bottom-up concentrate production estimates and top-down stainless steel demand modeling were triangulated against export flow data from Richards Bay and Eskisehir processing cluster output records.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. The forecast framework modeled segmentation dimensions including grade tier (metallurgical, chemical, refractory, foundry), end-use application (ferrochrome production, direct steel addition, dichromate synthesis, refractory fabrication), and regional production hub (Bushveld Complex, Eskisehir, Odisha, Kazakhstan). CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity commissioning schedules, with specific inputs including Eskom tariff trajectory assumptions and REACH authorization timeline scenarios for hexavalent chromium compounds.
The analysis sits within stated boundaries; outcomes outside sustained stainless steel demand growth, stable electricity supply for submerged arc furnace operations, or unimpeded Richards Bay logistics capacity would require recalibration. Forecasts reflect assumptions regarding beneficiation mandate enforcement continuity, trivalent conversion technology adoption curves, and nickel-chrome alloy specification stability in austenitic formulations. Recalibration cycles align with material shifts in South African energy policy, REACH authorization rulings, and Asian stainless steel mill procurement pattern changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Recycled Lead Market
Metals & Minerals
Cobalt Carbonate Market
Metals & Minerals
Global Magnesium Market
Metals & Minerals
Andalusite Market
Metals & Minerals
Silver Mining Market
Metals & Minerals
Cobalt Sulphate Market
Metals & Minerals
Recycled Scrap Metal Market
Metals & Minerals
Garnet Market
Metals & Minerals
Dead Sea Mineral Market
Metals & Minerals
Lithium Ingots Market
Metals & Minerals
Zinc Hydroxide Market
Metals & Minerals
Middle East and Africa Aluminum Extrusion Market
Metals & Minerals
Silver Salt Market
Metals & Minerals
Manganese Mining Market
Metals & Minerals
Direct Reduced Iron (DRI) Market
Metals & Minerals
Dolomite Market