
 Magnesium Phosphate Market | 2026-2036
Magnesium Phosphate Market Size, Share, and Industry Trends Forecast 2026-2036
Magnesium Phosphate Market Analysis
Market Context
Pharmaceutical-grade demand is consolidating around nutraceuticals and veterinary medicine end users as supplement manufacturers reformulate for bioavailability. Jost Chemical Co leverages its US-based cGMP production to anchor high-purity supply chains for pharmaceutical and food additive customers. American Elements competes through rare-earth adjacent specialization, while Innophos Holdings, Inc. sustains broad phosphate portfolio diversification across multiple industrial verticals.
Technical Definition and Segment Structure
Magnesium phosphate encompasses a family of inorganic salts—monomagnesium, dimagnesium, trimagnesium, and complex forms—typically manufactured through controlled neutralization of phosphoric acid with magnesium oxide or hydroxide, with purity grades spanning feed-grade to EP/USP pharmaceutical specifications. Trimagnesium phosphate dominates fertilizer and feed applications where lower solubility and cost efficiency matter, while monomagnesium phosphate commands premium positioning in food processing and pharmaceuticals where rapid dissolution and precise stoichiometry are critical. The direct sales channel controls bulk agricultural and industrial volumes, whereas distributor networks capture fragmented food processing and nutraceuticals demand.
Regulatory Frame and Outlook
EPA and OSHA frameworks govern US manufacturing emissions and worker exposure limits for phosphate processing facilities, while REACH and EFSA evaluations in Europe restrict cadmium and heavy-metal contaminants in fertilizer-grade material. India's FSSAI and China's SAMR enforce divergent food-additive purity thresholds that fragment import qualification requirements. Stakeholders must monitor evolving pharmaceutical monograph revisions and carbon-intensity disclosure rules that threaten to bifurcate the supplier base between certified and commodity-tier producers.
Market Dynamics
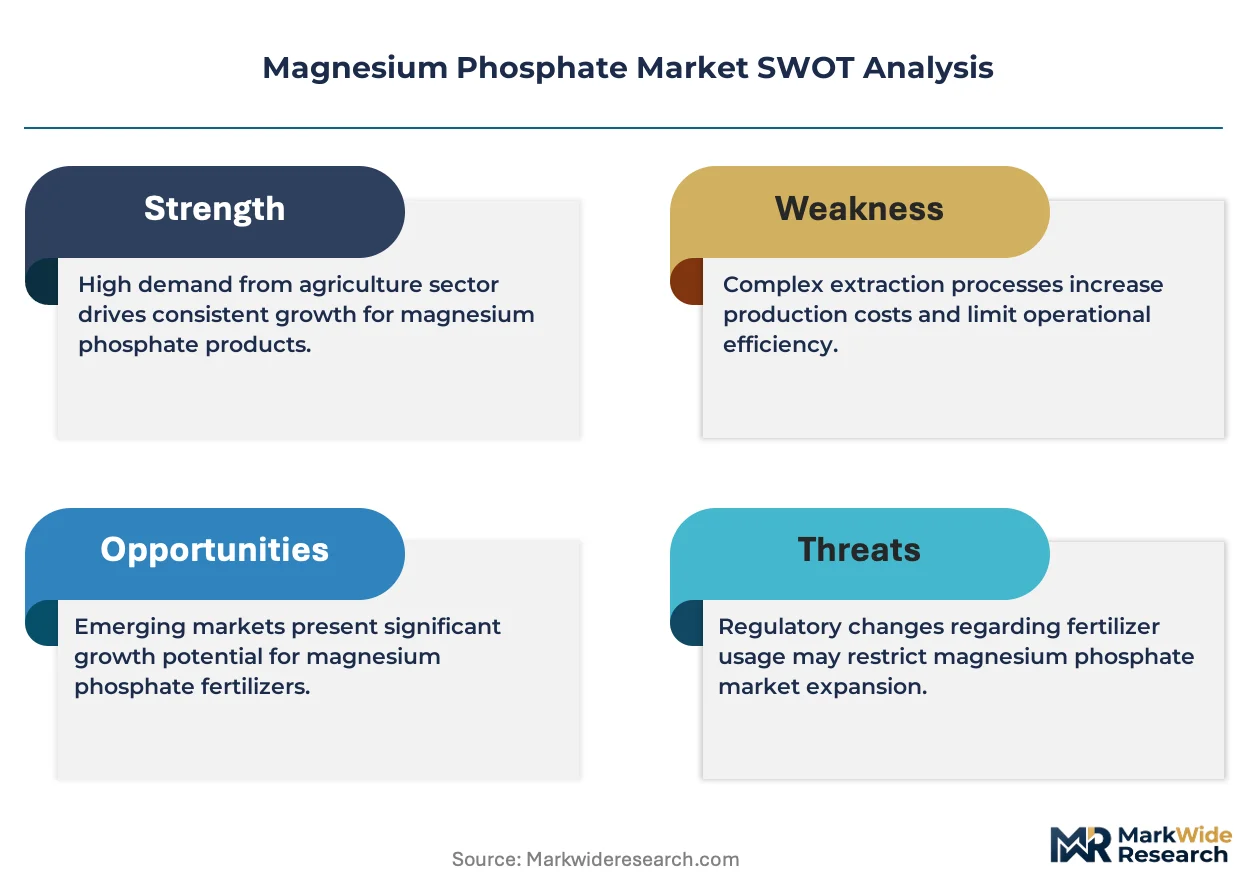
REACH cadmium limits and India's FSSAI purity mandates are bifurcating the supplier base between certified pharmaceutical-grade producers and commodity fertilizer suppliers, compressing margins for uncertified manufacturers while rewarding cGMP-compliant facilities with premium pricing power.
Growth Catalysts
- REACH Heavy-Metal Limits:European fertilizer and feed additive buyers are redirecting procurement toward certified producers with verified cadmium controls, tightening supply qualification and locking in premium pricing for compliant manufacturers.
- Pharmaceutical-Grade Nutraceuticals:Supplement manufacturers are reformulating magnesium phosphate inputs for enhanced bioavailability, pulling higher-purity monomagnesium phosphate volumes into encapsulation and tablet production.
- China Fertilizer Demand:Agricultural phosphate consumption in China's primary grain belts anchors regional offtake for trimagnesium phosphate, sustaining bulk volume throughput despite quality-tier fragmentation elsewhere.
Market Restraints
- Phosphoric Acid Volatility:Feedstock cost swings tied to sulfur and phosphate rock concentrate pricing compress margin predictability for neutralization-process manufacturers serving cost-sensitive fertilizer segments.
- Supplier Concentration Risk:High-purity magnesium oxide and hydroxide inputs concentrate among limited specialty chemical producers, creating single-source vulnerability for pharmaceutical-grade output scaling.
- Alternative Magnesium Sources:Magnesium oxide and magnesium chloride substitutes compete in feed and fertilizer applications where solubility requirements permit lower-specification inputs.
Strategic Opportunities
- Veterinary Medicine Formulations:Livestock mineral premix manufacturers in Brazil and Mexico are qualifying pharmaceutical-grade trimagnesium phosphate for injection-grade applications, opening premium pricing tiers in animal health.
- Carbon-Intensity Disclosure Mandates:EU CSRD reporting requirements are creating first-mover advantage for producers with verified low-carbon neutralization processes and renewable energy integration.
- Direct-to-Manufacturer Channels:Nutraceutical contract manufacturers are bypassing traditional chemical distributors to secure multi-year offtake agreements with cGMP-certified producers, compressing channel margins and deepening supplier relationships.
Industry Challenges
- Pharmacopeial Compliance Timelines:USP and EP monograph revision cycles delay product recertification for existing pharmaceutical-grade lines, freezing capacity allocation decisions during transition periods.
- Multi-Site Audit Burden:Food additive and pharmaceutical customers are imposing simultaneous cGMP, FSSC 22000, and customer-specific quality audits, stretching quality assurance staffing across manufacturing locations.
Report Scope
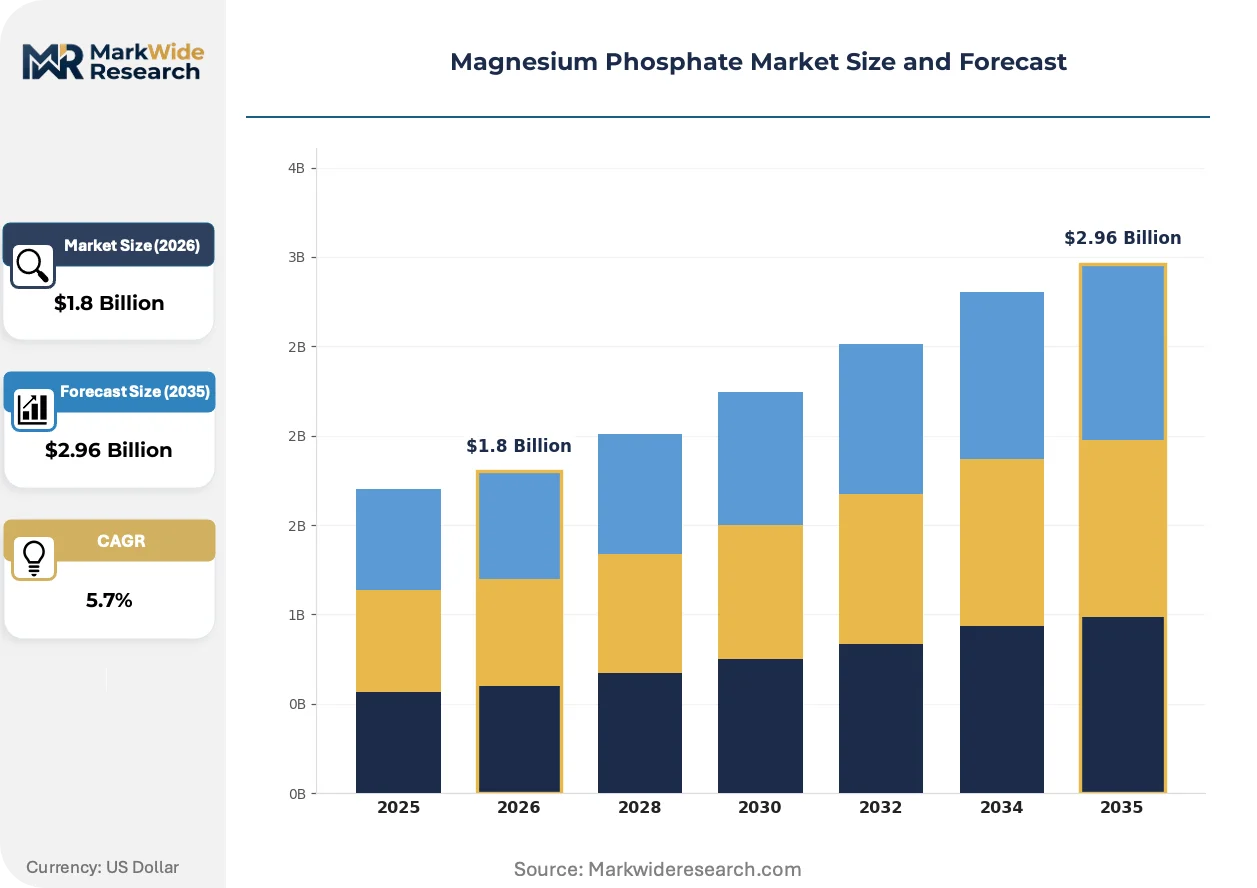
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnesium Phosphate Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monomagnesium Phosphate, Dimagnesium Phosphate, Trimagnesium Phosphate, Magnesium Phosphate Complex Application: Fertilizers, Food Additives, Pharmaceuticals, Animal Feed End User: Agriculture, Food Processing, Nutraceuticals, Veterinary Medicine Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Refractory Minerals, KRONOX Lab Sciences Ltd., Jost Chemical Co, Anmol Chemicals, American Elements, Innophos Holdings, Inc., Celtic Chemicals Ltd, Nikunj Chemicals, Triveni Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnesium Phosphate Market Emerging Trajectories
Electrification of process heat and precision crystallization control are reshaping cost structures and purity thresholds simultaneously, while regulatory disclosure mandates and buyer consolidation are rewiring commercial relationships across quality tiers.
Continuous crystallization with real-time particle-size monitoring is electrifying pharmaceutical-grade production economics. European and North American nutraceutical contract manufacturers are adopting these systems at replacement-cycle pace. The technology is compressing batch-to-batch variation and enabling just-in-time inventory models that reduce working capital requirements for high-purity monomagnesium phosphate.
EFSA's evolving evaluations on heavy-metal carryover in phosphate fertilizers are tightening cadmium thresholds beyond REACH baselines. Fertilizer blenders in Germany and France are now demanding certified low-cadmium trimagnesium phosphate, forcing feedstock sourcing changes upstream. Agricultural cooperatives are responding by locking in multi-year supply contracts with certified producers, accelerating supplier base consolidation.
Consolidation among North American supplement brands is compressing supplier qualification cycles and privileging manufacturers with integrated quality documentation portals. Direct API-to-capsule-filler relationships are displacing traditional chemical distributor intermediaries for pharmaceutical-grade volumes. This pattern is most visible in California and New Jersey, where contract manufacturing clusters concentrate purchasing power among fewer, larger buyers demanding auditable supply chain transparency.
Magnesium Phosphate Market Segmentation
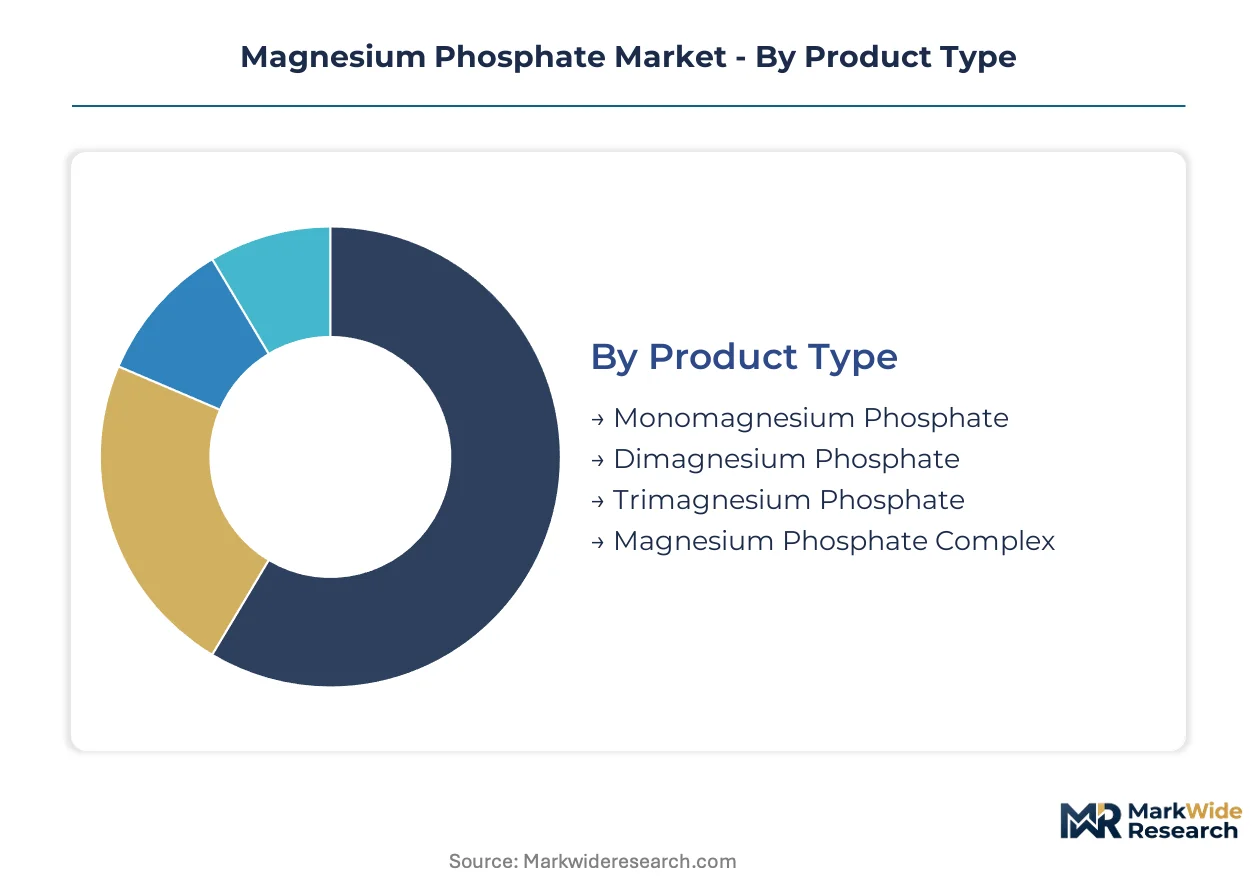
Magnesium phosphate segmentation reveals a market split between standalone commodity applications and embedded high-purity systems. Understanding where each segment sits on this integration spectrum exposes margin architecture and supplier qualification intensity.
Product Type:
Standalone commodity grades dominate bulk volume, while embedded pharmaceutical and food-grade variants command integrated supply relationships.
- Monomagnesium Phosphate:Highly soluble salt with rapid dissolution kinetics suited to precise stoichiometry requirements. Nutraceutical contract manufacturers in California and New Jersey are locking in multi-year offtake for tablet and encapsulation applications, driven by bioavailability reformulation trends.
- Trimagnesium Phosphate:Lower solubility and cost-optimized specification anchors fertilizer and feed-grade demand. China's primary grain belts sustain bulk throughput for this grade, with agricultural cooperatives securing certified low-cadmium supply under tightening EFSA evaluations.
- Dimagnesium Phosphate:Intermediate solubility profile serving specialty feed premix and industrial buffer applications.
- Magnesium Phosphate Complex:Blended and modified forms targeting niche pharmaceutical excipient and veterinary injection-grade specifications.
Volume placements concentrate in Trimagnesium Phosphate; the faster expansion belongs to Monomagnesium Phosphate.
Application:
Cost-tier stratification separates price-sensitive agricultural bulk buyers from premium pharmaceutical and food additive purchasers.
- Fertilizers:Largest-volume application consuming trimagnesium phosphate for soil amendment and nutrient delivery. REACH cadmium limits and EFSA heavy-metal thresholds are redirecting European procurement toward certified producers with verified upstream controls.
- Pharmaceuticals:EP/USP-grade monomagnesium phosphate for tablet binders, excipients, and mineral supplements. cGMP compliance and pharmacopeial monograph alignment freeze capacity decisions during USP and EP revision cycles.
- Food Additives:pH buffering and leavening agent functions across processed food manufacturing.
- Animal Feed:Mineral premix ingredient competing with magnesium oxide and chloride substitutes where solubility permits lower-specification inputs.
Margin concentration sits in Pharmaceuticals; volume leadership remains with Fertilizers.
End User:
Customer-type fragmentation drives divergent procurement patterns, from cooperative bulk purchasing to direct API relationships.
- Nutraceuticals:Supplement manufacturers reformulating for enhanced bioavailability pull high-purity monomagnesium phosphate into encapsulation lines. Consolidation among North American brands compresses supplier qualification cycles and privileges integrated quality documentation portals.
- Agriculture:Fertilizer blenders and agricultural cooperatives anchor trimagnesium phosphate offtake. German and French cooperatives are locking in multi-year contracts with certified low-cadmium producers ahead of EFSA threshold tightening.
- Food Processing:Fragmented bakery and processed food manufacturers sourcing through distributor networks.
- Veterinary Medicine:Livestock mineral premix and injection-grade applications in Brazil and Mexico are qualifying pharmaceutical-grade trimagnesium phosphate, opening premium pricing tiers in animal health.
Procurement consolidation is advancing fastest in Nutraceuticals; price sensitivity persists in Agriculture.
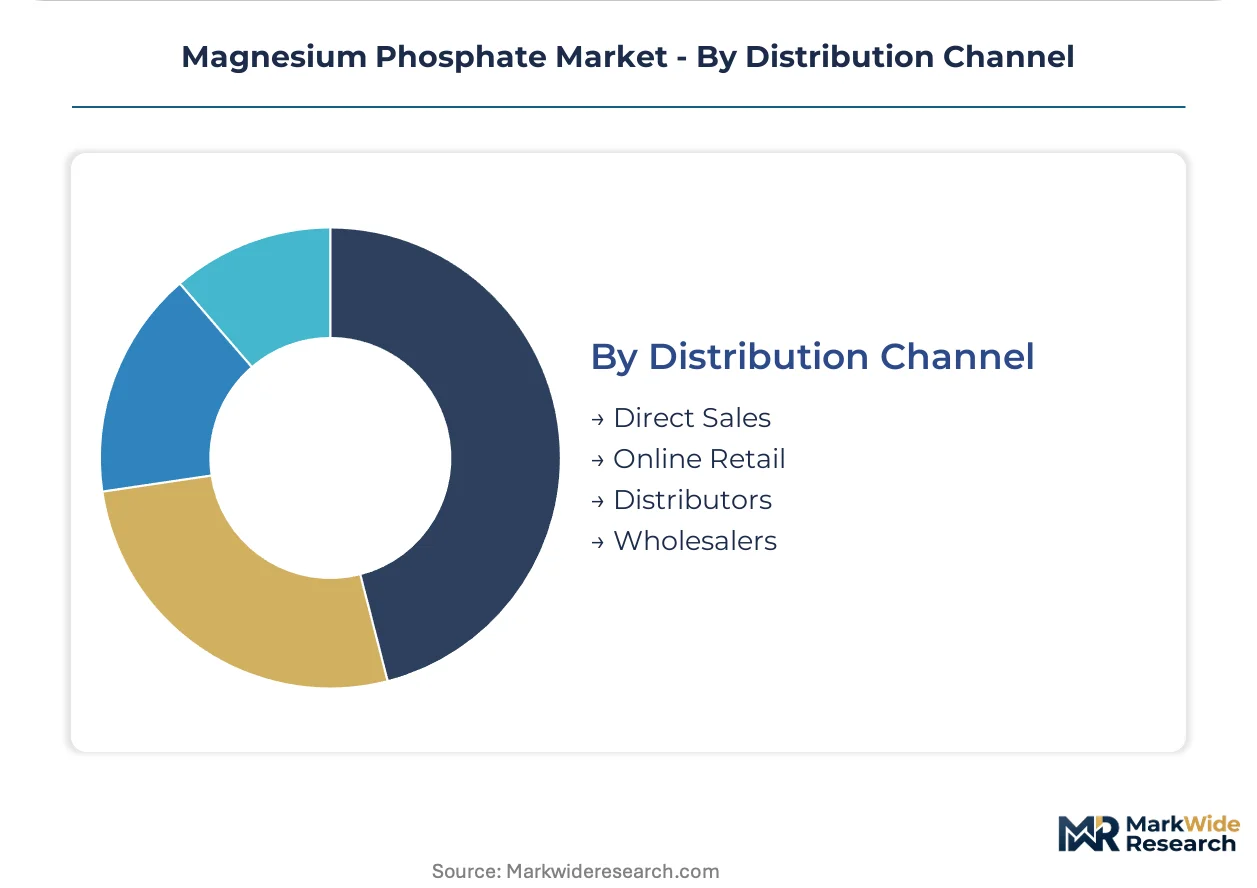
Distribution Channel:
Supply concentration and margin capture vary sharply between direct manufacturer relationships and intermediated wholesale channels.
- Direct Sales:Controls bulk agricultural and industrial volumes with multi-year supply agreements. cGMP-certified producers are bypassing traditional chemical distributors to secure direct relationships with nutraceutical contract manufacturers, compressing channel margins.
- Distributors:Captures fragmented food processing and nutraceutical demand through qualified chemical distribution networks. Quality audit burdens stretch assurance staffing across manufacturing locations serving this channel.
- Online Retail:Emerging channel for small-volume pharmaceutical-grade and specialty nutraceutical ingredients.
- Wholesalers:Aggregates commodity-grade fertilizer and feed additive demand in price-sensitive segments.
Relationship depth is concentrating in Direct Sales; Distributors retain relevance in fragmented buyer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate fertilizer-grade production capacity, while India's pharmaceutical clusters in Hyderabad and Ahmedabad pull high-purity imports. Regulatory divergence across EPA, REACH, and SAMR frameworks fragments qualification requirements for multinational suppliers.
United States
Fertilizer blenders in the Midwest corn belt anchor trimagnesium phosphate offtake for soil amendment programs. EPA emissions frameworks and OSHA exposure limits govern phosphate processing facilities in the Ohio River Valley. Jost Chemical Co operates cGMP-certified production from St. Louis, supplying pharmaceutical-grade material to nutraceutical contract manufacturers in New Jersey and California.
China
Agricultural cooperatives in Hebei and Shandong provinces sustain bulk volume demand for fertilizer-grade material. SAMR food-additive purity thresholds and MEE environmental discharge rules tighten upstream controls on phosphate rock processing. The Yangtze River Delta chemical corridor hosts neutralization facilities serving both domestic fertilizer blenders and export pharmaceutical customers.
Germany
Fertilizer blenders in Lower Saxony and North Rhine-Westphalia are locking in multi-year contracts ahead of EFSA cadmium threshold revisions. REACH compliance and the EU Green Deal carbon-intensity disclosure rules privilege certified low-cadmium producers. The BASF-adjacent chemical cluster in Ludwigshafen coordinates technical-grade phosphate distribution across continental agricultural cooperatives.
India
Supplement manufacturers in Hyderabad's Genome Valley and Ahmedabad's pharmaceutical zone import pharmaceutical-grade monomagnesium phosphate for tablet reformulation. FSSAI tightening on food-additive heavy-metal limits redirects procurement toward certified producers with verified upstream controls. CDSCO pharmaceutical monograph alignment delays recertification timelines for existing import suppliers.
Brazil
Livestock mineral premix manufacturers in São Paulo state are qualifying pharmaceutical-grade trimagnesium phosphate for veterinary injection applications. ANVISA regulatory convergence with USP standards opens premium pricing tiers in animal health formulations. The Campinas agricultural technology corridor anchors regional distribution for fertilizer-grade material into Mato Grosso soybean belts.
Magnesium Phosphate Market Vendor Landscape
Top-tier vendors anchor pharmaceutical-grade supply with cGMP certification, while commodity fertilizer producers compete on phosphoric acid feedstock access and sulfur cost positioning. The supplier base stratifies across three archetypes: integrated phosphate miners with captive neutralization capacity, specialty chemical houses with pharmacopeial compliance infrastructure, and regional blenders with agricultural distribution lock-in. Capacity expansion and backward integration into magnesium oxide sourcing represent the dominant competitive vectors.
Among US-based specialty chemical producers, Jost Chemical Co and American Elements occupy positions within the high-purity tier, with the former exemplifying cGMP-anchored supply relationships and the latter representing rare-earth adjacent diversification strategies. Innophos Holdings, Inc. sits within the portfolio-diversified segment, spanning multiple phosphate verticals without singular reliance on magnesium salts. These three entities collectively illustrate the competitive tension between purity-grade specialization and broad phosphate portfolio breadth.
| Leading Market Players |
|---|
| Refractory Minerals |
| KRONOX Lab Sciences Ltd. |
| Jost Chemical Co |
| Anmol Chemicals |
| American Elements |
| Innophos Holdings, Inc. |
| Celtic Chemicals Ltd |
| Nikunj Chemicals |
| Triveni Chemicals |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between cGMP-compliant pharmaceutical producers and uncertified commodity suppliers manifests in divergent pricing power and sourcing configurations across the magnesium phosphate value chain. Pharmaceutical-grade monomagnesium phosphate commands premium contract structures with multi-year offtake guarantees, while fertilizer-grade trimagnesium phosphate trades on spot-indexed phosphoric acid feedstock costs with compressed margin profiles.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid fulfillment with premium positioning, particularly for nutraceutical contract manufacturers facing compressed tablet production schedules. Three-tier pricing structure across pharmaceutical-grade, food-additive, and fertilizer-grade levels reflects certification burden and purity verification costs. Pricing pressure intensifies in commodity fertilizer tiers due to phosphoric acid volatility and sulfur cost swings. Agricultural cooperatives exhibit highest price sensitivity, while pharmaceutical buyers prioritize supply security over unit economics.
Supply Chain Analysis
Domestic-content mandates under India's FSSAI and China's SAMR frameworks are reshaping sourcing patterns toward certified local producers with verified upstream controls. Manufacturing gravity centers on China, the United States, and Germany, with each hub serving distinct quality tiers. Feedstock supply draws from phosphate rock concentrate, magnesium oxide, and sulfuric acid inputs. Single-source vulnerability concentrates in high-purity magnesium oxide from limited specialty chemical producers. Distribution runs through direct manufacturer relationships for pharmaceutical volumes and qualified chemical distributors for fragmented food processing demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints around cGMP-certified capacity are propping pricing power for qualified producers, as pharmacopeial compliance timelines freeze expansion decisions and lock in incumbent advantages.
For Market Incumbents: Deploy pharmacopeial pre-certification investments to capture capacity-constrained pharmaceutical-grade demand before USP and EP revision cycles complete. Anchor backward integration into magnesium oxide sourcing to neutralize single-supplier vulnerability. Fortify direct relationships with nutraceutical contract manufacturers in California and New Jersey to compress distributor channel margins. For New Entrants and Emerging Players: Enter via veterinary medicine formulations in Brazil and Mexico, where ANVISA convergence with USP standards creates qualification pathways without incumbent lock-in. Target carbon-intensity disclosure mandates under EU CSRD rules as a greenfield positioning angle. Pursue joint development agreements with livestock mineral premix manufacturers seeking pharmaceutical-grade trimagnesium phosphate for injection applications. For Investors and Strategic Acquirers: Re-rating potential sits with cGMP-certified specialty chemical houses given REACH cadmium limit enforcement and EFSA threshold tightening accelerating supplier base consolidation. Long-term viability favors producers with integrated quality documentation portals and renewable energy neutralization processes. Watch EFSA heavy-metal evaluation timelines as the inflection signal for certified-premium tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnesium Oxide | Captive supply of high-purity inputs neutralizes single-source vulnerability for pharmaceutical-grade expansion. |
| Continuous Crystallization Technology Deployment | Real-time particle-size monitoring compresses batch variation for nutraceutical contract manufacturers. |
| Carbon-Intensity Certification Program | Verified low-carbon neutralization processes unlock EU CSRD disclosure advantages and premium pricing tiers. |
| Direct-to-Manufacturer Channel Development | Bypassing chemical distributors deepens relationships with nutraceutical contract manufacturers in California and New Jersey. |
| Pharmacopeial Pre-Certification Investment | USP and EP alignment ahead of revision cycles locks in capacity allocation for pharmaceutical-grade lines. |
Methodological Framework
Document review covered SEC 10-K filings, customs and trade data, REACH registration databases, and pharmacopeial monograph revisions, complemented by interviews with plant managers at neutralization facilities, procurement leads at fertilizer blenders, technical R&D directors at specialty chemical houses, and quality assurance heads at nutraceutical contract manufacturers. Bottom-up volume modeling triangulated against top-down industry association data from ACC and Cefic.
Segment-level projections across product type, application, end user, and distribution channel dimensions were generated through demand-driver elasticity modeling and supply-side capacity assessment throughout the forecast period. CAGRs were derived from regression analysis against phosphate rock pricing indices, agricultural acreage forecasts, and pharmaceutical formulation trends. Industry-specific inputs included EFSA cadmium evaluation timelines and USP monograph revision schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under phosphoric acid price volatility and REACH enforcement intensity shifts. Projections reflect assumptions on regulatory compliance timelines and substitution elasticity between magnesium phosphate grades. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
North America Calcium Chloride Market
Bulk Chemicals
Sodium Dichromate Market
Bulk Chemicals
Saudi Arabia Formic Acid Market
Bulk Chemicals
Palmitic Acid Market
Bulk Chemicals
Ethyleneamines Market
Bulk Chemicals
Furfural Derivatives Market
Bulk Chemicals
FT Wax Market
Bulk Chemicals
Asia Pacific Dry PVC Compound Market
Bulk Chemicals
Phthalic Anhydride Market
Bulk Chemicals
Iodine Market
Bulk Chemicals
Caprolactam Market
Bulk Chemicals
Gluconic Acid Market
Bulk Chemicals
Manganese Sulfate Market
Bulk Chemicals
Zinc Gluconate Granules Market
Bulk Chemicals
Global Acrylic Esters Market
Bulk Chemicals
Global Plastics Market