
 North America Calcium Chloride Market | 2026-2036
North America Calcium Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
North America Calcium Chloride Market Intelligence
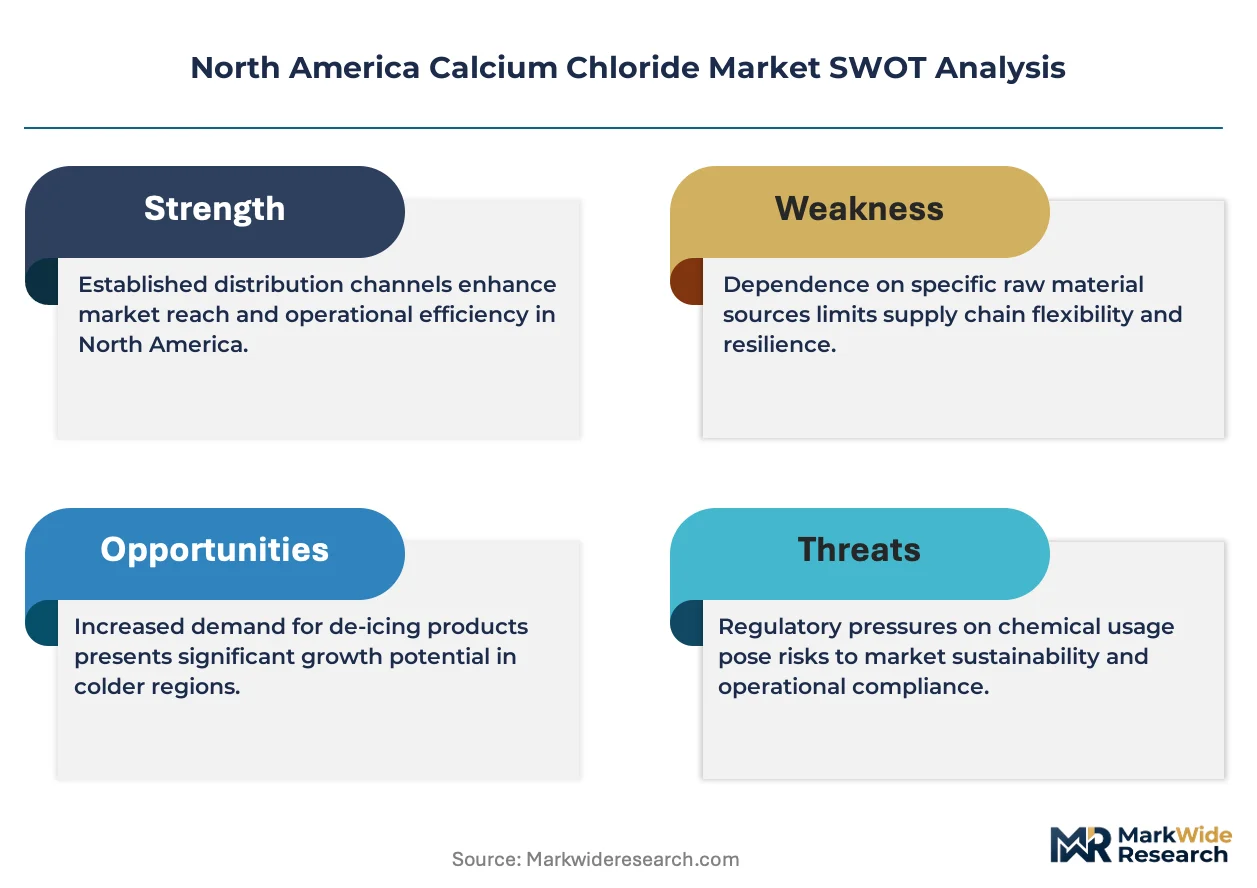
Dry-blend manufacturing automation is tilting production economics toward higher-purity flake and pellet grades. Occidental Chemical Corporation leverages its integrated brine sourcing across West Texas to sustain cost leadership in liquid calcium chloride. TETRA Technologies, Inc. anchors its position through captive supply chains serving energy sector customers. Great Lakes Chloride, Inc. specializes in seasonal deicing logistics, dominating winter distribution networks across the Upper Midwest.
Calcium chloride is a hygroscopic inorganic salt with the chemical formula CaCl₂, typically produced via the Solvay process or natural brine extraction, and functions primarily as a desiccant, freezing-point depressant, and dust suppression agent. The flake segment leads volume due to its superior handling characteristics in municipal deicing spreaders, while liquid formulations capture margin in oilfield completion fluids where rapid dissolution matters. Dust control applications in unpaved road maintenance represent the fastest-growing demand pool, particularly in rural counties and mining access routes. Construction end users drive premium pricing for certified food-grade and pharmaceutical-grade pellets.
The EPA's National Pollutant Discharge Elimination System and Environment Canada's Fisheries Act shape chloride discharge limits, pushing municipalities toward optimized application rates and storage protocols. OSHA workplace exposure standards and DOT hazardous materials classifications govern packaging, labeling, and transport across interstate corridors. State-level procurement specifications in Minnesota, Wisconsin, and Michigan increasingly mandate corrosion-inhibited formulations. Stakeholders must monitor evolving chloride load thresholds in Great Lakes watershed agreements and calibrate product portfolios between bulk commodity grades and value-added specialty formulations.
Market Dynamics
The EPA's National Pollutant Discharge Elimination System is forcing municipal deicing programs to optimize application rates and adopt corrosion-inhibited formulations, compressing margins for commodity-grade suppliers while rewarding specialty chemical producers.
Growth Catalysts
- Oilfield completion fluids:Alberta's oil sands and West Texas shale corridors sustain demand for high-purity liquid calcium chloride in hydraulic fracturing operations.
- Dust control mandates:Rural counties across Kansas, Oklahoma, and Montana are formalizing unpaved road maintenance programs, expanding the fastest-growing application segment.
- Great Lakes chloride protocols:Watershed agreements between Minnesota, Wisconsin, and Michigan are accelerating adoption of precision application technologies.
Market Restraints
- Natural brine concentration:West Texas and Michigan basin supply geography creates weather-dependent extraction volatility and transport cost premiums to coastal markets.
- Magnesium chloride substitution:Road authorities in Iowa and Ohio are piloting alternative deicing salts where corrosion inhibition specifications permit.
- OSHA workplace exposure limits:Stricter dust particulate thresholds are elevating handling equipment costs and warehouse ventilation requirements.
Strategic Opportunities
- Mexican mining corridors:Sonora and Chihuahua copper-gold operations lack established dust control chemical supply chains, creating first-mover positioning for bulk liquid distributors.
- Food-grade pellet certification:FDA-compliant pharmaceutical and food processing applications command 40-60% price premiums over industrial grades.
- Seasonal storage infrastructure:Dedicated liquid calcium chloride terminals in Chicago and Minneapolis-St. Paul enable year-round contracting and margin capture.
Industry Challenges
- Brine chemist talent scarcity:Specialized expertise in chloride purification and corrosion inhibitor formulation concentrates among retiring cohorts at legacy producers.
- DOT hazmat classification complexity:Interstate transport permits and tank car specifications vary across U.S. states and Canadian provinces, fragmenting logistics planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Calcium Chloride Market |
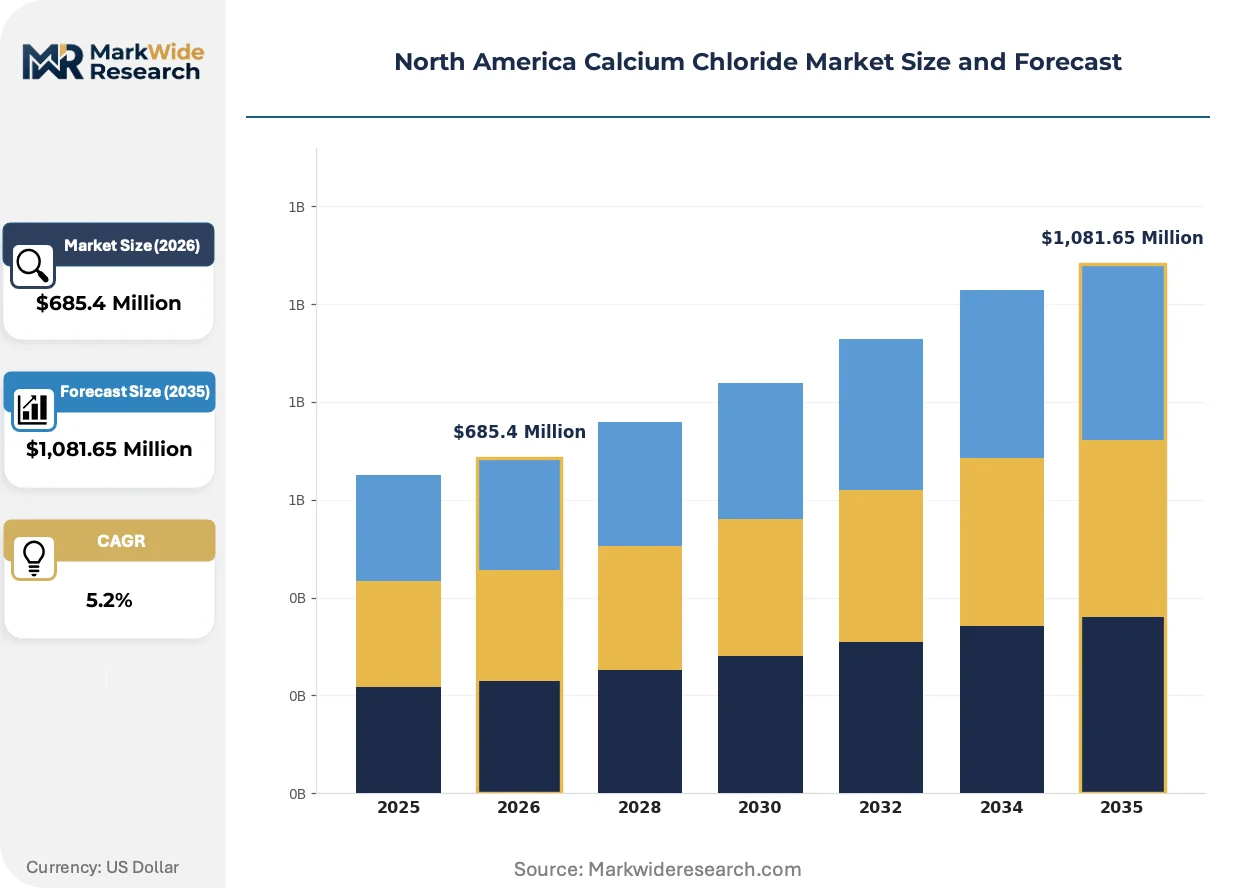
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flake, Pellet, Liquid, Granular Application: Deicing, Dust Control, Soil Stabilization, Water Treatment End User: Construction, Agriculture, Chemicals, Food Processing Distribution Channel: Online, Direct Sales, Retail, Distributors |
| Companies Covered | Ward Chemical Ltd., Pinnacle Oil Holdings, LLC, Occidental Chemical Corporation, Cargill, Nedmag Industries Mining & Manufacturing B.V., TETRA Technologies, Inc., Solvay Chemicals, Inc., Great Lakes Chloride, Inc., Tiger Calcium Services Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Calcium Chloride Market Strategic Shifts & Innovations
Automation in dry-blend manufacturing is collapsing production economics for higher-purity flake and pellet grades, while regulatory pressure on chloride discharge is accelerating formulation innovation across municipal and industrial end uses.
Pre-wetted deicing systems are collapsing traditional spreader economics by enabling 30% lower application rates while maintaining equivalent ice-melt performance. Municipal fleets in Milwaukee, Detroit, and Toronto are retrofitting equipment to accommodate liquid-injection capabilities. This technology is collapsing the volume premium historically captured by dry flake suppliers in the Upper Midwest.
Environment Canada's Fisheries Act amendments are tightening chloride discharge thresholds into receiving waters, compelling Alberta and Saskatchewan oilfield operators to recycle completion fluids rather than discharge to evaporation ponds. Brine treatment infrastructure investments are concentrating around Lloydminster and Grande Prairie.
County-level procurement consolidation is aggregating demand across rural road networks, with Minnesota's township associations and Wisconsin's county highway departments shifting from spot purchases to multi-year supply agreements. This pattern is most visible in the Red River Valley and Driftless Area, where transportation costs favor single-source liquid delivery contracts over bagged product distribution.
North America Calcium Chloride Market Segmentation
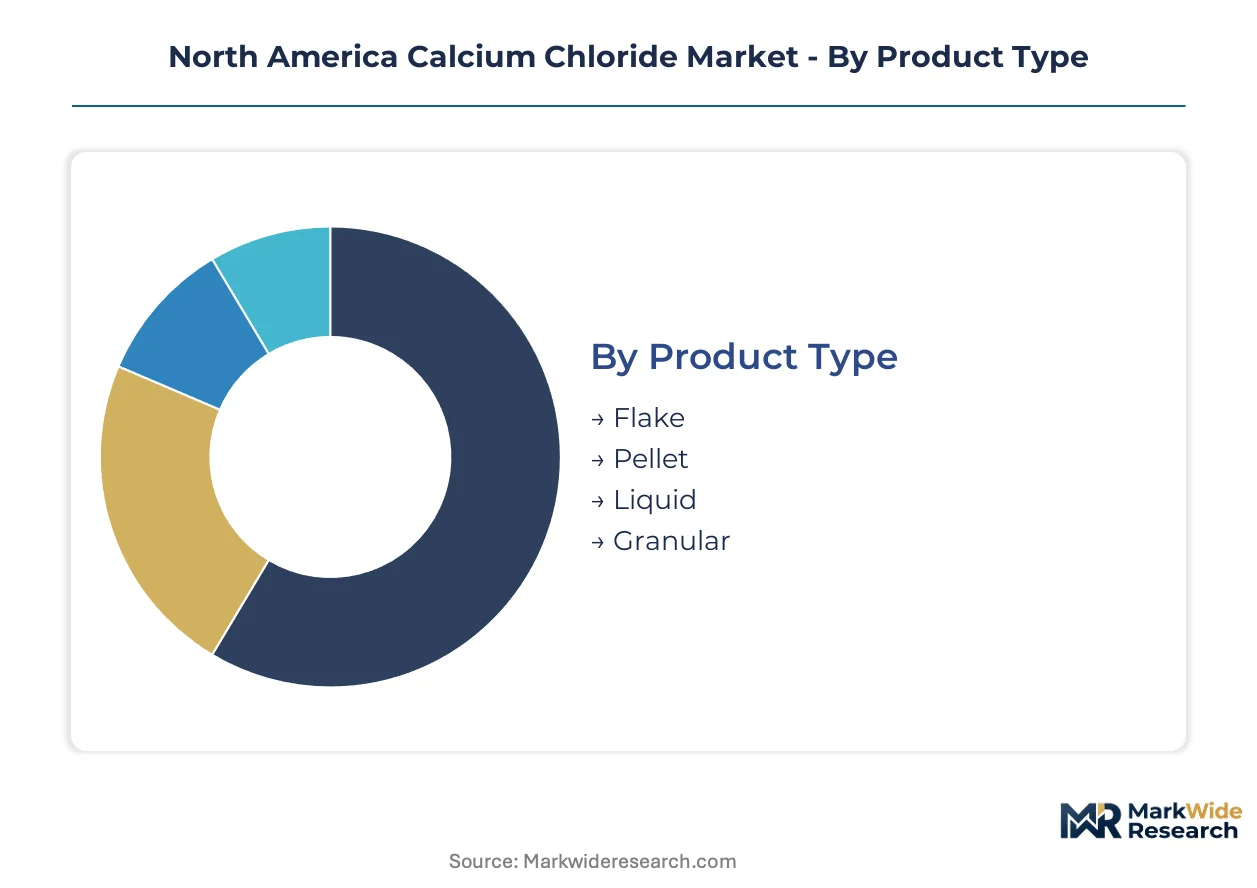
Calcium chloride's hygroscopic chemistry and freezing-point depression properties create distinct performance requirements across product formats. Segmentation in this market reflects divergent handling economics, seasonal demand patterns, and regulatory compliance thresholds that reshape supplier positioning.
Product Type:
After-sales service intensity varies sharply by physical form—liquid demands tank maintenance and pumping infrastructure, while solid grades require dust suppression and caking prevention protocols.
- Flake:Flat, irregular crystals produced through evaporative concentration of natural brine or synthetic processes, optimized for municipal spreader compatibility. Demand concentrates across Minnesota, Wisconsin, and Michigan highway departments where bulk handling equipment dominates procurement specifications. EPA chloride discharge scrutiny is accelerating precision application investments that favor flake's controlled dissolution rates.
- Liquid:Aqueous solutions ranging from 28% to 42% concentration by weight, delivered via tanker or railcar for industrial integration. Alberta's oil sands operators and West Texas shale corridors sustain captive demand for high-purity completion fluids where rapid dissolution and density control matter. Brine recycling mandates under Environment Canada's Fisheries Act amendments are tightening quality specifications for liquid grades.
- Pellet:Spherical, compressed forms engineered for low-dust handling and precise metering in automated systems. Food processing and pharmaceutical certification requirements command premium positioning.
- Granular:Coarse, crystalline particles bridging flake handling ease with pellet flow characteristics. Rural county dust control programs favor granular for unpaved road maintenance.
Flake holds the largest share; momentum sits with liquid formulations.
Application:
Cost tier differentiation separates commodity bulk applications from certified specialty uses where compliance documentation commands price premiums.
- Deicing:Road surface treatment leveraging calcium chloride's exothermic dissolution and lower effective temperature limit versus sodium chloride. Municipal fleets across the Great Lakes region and Canadian prairie provinces drive volume procurement through state-level cooperative purchasing agreements. Corrosion-inhibited formulations are displacing commodity grades where infrastructure protection budgets permit.
- Dust Control:Surface binding on unpaved roads, mining haul routes, and construction sites through hygroscopic moisture retention. Kansas, Oklahoma, and Montana county highway departments are formalizing maintenance programs, expanding the fastest-growing application segment. Seasonal contracting patterns favor multi-year liquid supply agreements over spot purchasing.
- Soil Stabilization:Subgrade moisture management and compaction aid for road base construction. State DOT specifications in Texas and Alberta govern acceptance criteria.
- Water Treatment:Hardness adjustment and contaminant precipitation in industrial and municipal systems. Food-grade certification requirements segment this application sharply.
Deicing retains volume leadership; dust control is climbing the fastest.
End User:
Customer type determines procurement modality—public infrastructure entities favor competitive bidding while industrial users negotiate framework contracts.
- Construction:Concrete curing acceleration, soil compaction, and dust suppression across commercial and residential projects. Unionized labor agreements in major metropolitan areas influence seasonal demand timing.
- Agriculture:Soil amendment and livestock feed additive applications where FDA compliance documentation is mandatory. Midwest grain belt counties represent concentrated demand geography.
- Chemicals:Intermediate feedstock for calcium salts, desiccant manufacturing, and refrigeration brines. Integrated producers with captive brine sourcing dominate supply relationships.
- Food Processing:Firming agent and preservative applications requiring USP or FCC certification. Pharmaceutical-grade specifications command steepest price premiums.
Construction absorbs the highest volume; food processing captures the steepest margins.
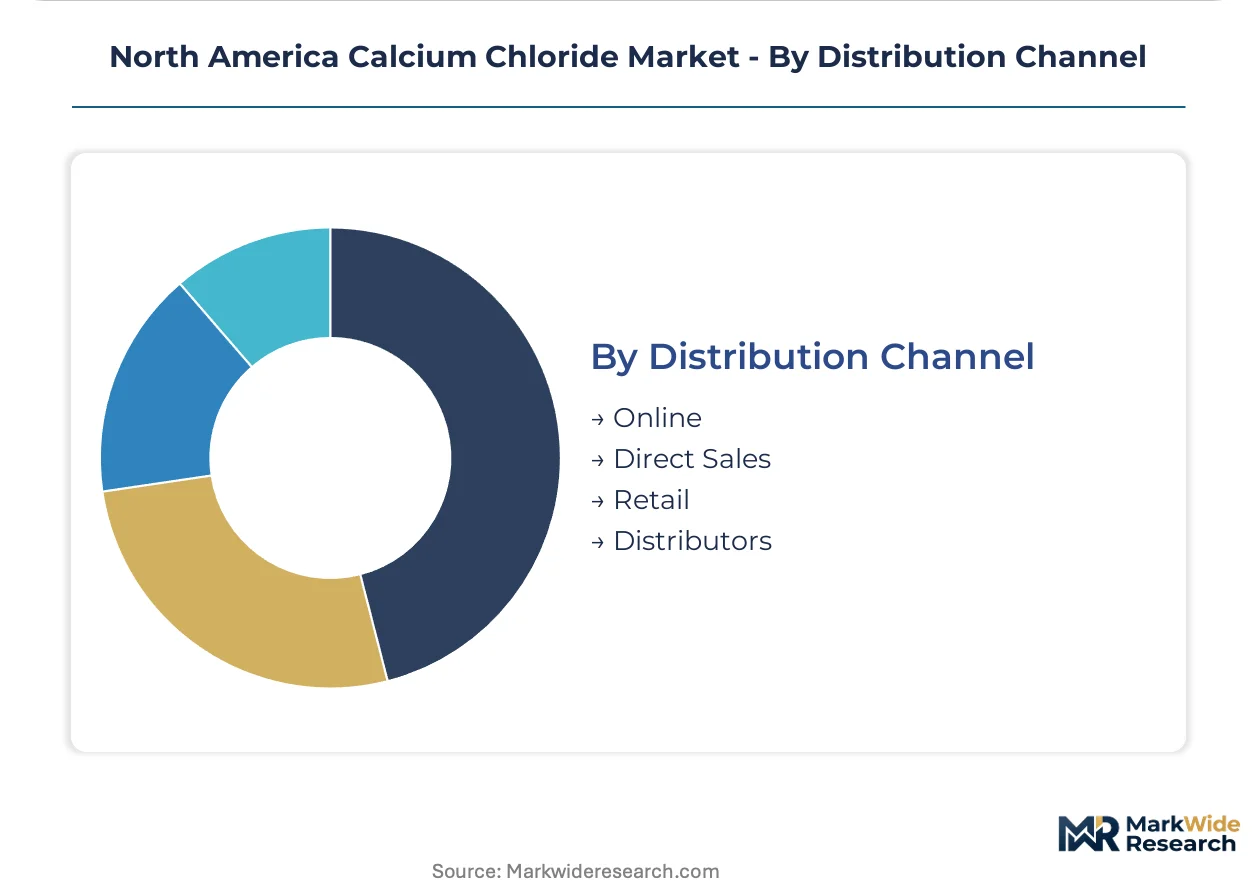
Distribution Channel:
Supply concentration in West Texas and Michigan basin brine fields dictates logistics economics and channel viability for coastal and remote markets.
- Direct Sales:Long-term supply agreements between producers and large municipal or industrial accounts. Tank terminal infrastructure in Chicago and Minneapolis-St. Paul enables year-round liquid contracting.
- Distributors:Regional warehousing and seasonal inventory positioning for smaller municipal and agricultural customers. Upper Midwest winter demand surges require advance stockpiling.
- Retail:Bagged consumer and small commercial sales through hardware and agricultural supply stores. Limited to solid grades given packaging constraints.
- Online:Emerging procurement channel for technical documentation and reagent-grade specifications. Institutional buyers utilize platforms for competitive quotation.
Direct sales command the largest share; distributor relationships are gaining share fastest in consolidated county procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian producers ship bulk liquid calcium chloride southward to Minnesota and Wisconsin highway departments, while West Texas brine operations supply Alberta oilfield corridors through cross-border rail terminals.
United States
Great Lakes municipal fleets in Milwaukee, Detroit, and Minneapolis-St. Paul drive flake procurement through state cooperative purchasing agreements. EPA National Pollutant Discharge Elimination System permits now mandate corrosion-inhibited formulations for watershed-adjacent roadways. West Texas shale operators in the Permian Basin sustain captive demand for high-purity completion fluids.
Canada
Alberta oil sands producers consume liquid grades for hydraulic fracturing and drilling mud density control. Environment Canada Fisheries Act amendments are tightening chloride discharge thresholds, forcing operators near Lloydminster to recycle completion fluids rather than discharge to evaporation ponds. Saskatchewan's agricultural belt represents expanding dust control adoption.
Mexico
Sonora and Chihuahua copper-gold mining corridors lack established dust control chemical supply chains, creating positioning opportunities for bulk liquid distributors. Mexican federal environmental standards under SEMARNAT govern industrial discharge permits for mining operations. Baja California construction projects import certified pellets for concrete curing acceleration.
North America Calcium Chloride Market Key Industry Players
Channel-controlling players compete with product-specialist players across distinct logistics and certification vectors. The vendor base clusters around three strategic archetypes: integrated brine producers with captive sourcing, seasonal logistics specialists with dedicated storage infrastructure, and diversified chemical conglomerates with cross-product scale. Consolidation pressure concentrates among regional distributors as county-level procurement aggregates demand. Dominant competitive moves include backward integration into brine extraction and multi-year supply contracting to lock seasonal demand.
Within the integrated producer tier, Occidental Chemical Corporation and TETRA Technologies, Inc. exemplify upstream control strategies. Occidental leverages West Texas brine fields for cost-positioned liquid supply. TETRA anchors energy sector relationships through captive completion fluid logistics. Great Lakes Chloride, Inc. represents the seasonal specialization archetype, dominating Upper Midwest winter distribution networks through dedicated terminal infrastructure.
| Leading Market Players |
|---|
| Ward Chemical Ltd. |
| Pinnacle Oil Holdings, LLC |
| Occidental Chemical Corporation |
| Cargill |
| Nedmag Industries Mining & Manufacturing B.V. |
| TETRA Technologies, Inc. |
| Solvay Chemicals, Inc. |
| Great Lakes Chloride, Inc. |
| Tiger Calcium Services Inc. |
| Others |
Cost & Logistics Intelligence
Undercapacity signals across West Texas brine fields and Michigan basin extraction sites are compressing spot availability for high-purity liquid grades, compelling suppliers to prioritize long-term offtake contracts over spot sales and pushing procurement officers toward multi-year supply agreements with built-in price escalators.
Pricing Analysis
Grade-certification pricing gaps separate USP-certified pharmaceutical pellets from industrial flake by substantial multiples, while food-grade intermediates occupy a mid-tier position. Three-tier pricing structure across premium, standard, and economy levels reflects corrosion inhibitor content and purity specifications. Cost compression in commodity flake is intensifying because EPA discharge mandates favor precision application technologies that reduce volumetric demand. Municipal highway departments exhibit highest price sensitivity, while oilfield completion fluid buyers prioritize supply security over unit cost.
Supply Chain Analysis
Extended payment terms from 30 to 90 days are becoming standard for liquid bulk purchasers, with supply-chain finance facilities emerging around Chicago and Minneapolis-St. Paul terminal operators. Production concentrates in the United States, Canada, and Mexico's northern border states. Raw material draws from natural brine reservoirs, synthetic Solvay process inputs, and magnesium chloride byproduct streams. Single-source vulnerability runs through West Texas weather-dependent extraction. Distribution runs through dedicated liquid terminals, regional distributors with seasonal stockpiling, and direct rail-to-plant delivery for energy sector accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a service-attach opportunity because liquid tank maintenance contracts and precision application equipment leasing are expanding faster than commodity flake sales, embedding suppliers into customer operations through recurring technical service revenue.
For Market Incumbents: Pre-empt magnesium chloride substitution in Iowa and Ohio by accelerating corrosion-inhibited formulation certification and securing multi-year Great Lakes watershed procurement contracts before 2025 chloride protocol updates finalize. Backward integration into brine treatment infrastructure around Lloydminster and Grande Prairie locks captive recycling demand from Alberta oil sands operators.
For New Entrants and Emerging Players: Build out dust control chemical distribution networks in Sonora and Chihuahua mining corridors where SEMARNAT enforcement is tightening but established supply chains remain absent. County-level procurement consolidation in Kansas and Oklahoma represents the most penetrable entry point, with equipment-leasing bundled contracts offering differentiation against commodity suppliers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across liquid terminal infrastructure and brine recycling equipment, favoring asset-heavy platforms with captive supply positions. Acquisition targets should display integrated brine sourcing or dedicated seasonal storage assets with year-round contracting capability. The signal to watch is Environment Canada Fisheries Act enforcement intensity around Lloydminster, which would accelerate recycling infrastructure deployment and concentrate value in treatment-capable suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brine Extraction | Captive supply from West Texas or Michigan basin fields insulates margin from spot price volatility. |
| Corrosion-Inhibited Formulation Certification | EPA NPDES compliance positions suppliers for Minnesota, Wisconsin, and Michigan state procurement mandates. |
| Seasonal Storage Terminal Development | Chicago and Minneapolis-St. Paul liquid terminals enable year-round contracting and margin capture. |
| Long-term Supply Agreement Structuring | Multi-year county highway contracts in Kansas and Oklahoma lock dust control demand growth. |
| Brine Recycling Infrastructure Investment | Environment Canada Fisheries Act amendments concentrate value in treatment-capable Alberta suppliers. |
Research Approach
A spread of perspectives from plant managers at integrated brine operations, procurement leads at Alberta oil sands operators, county highway department engineers, and distribution channel partners converged on the working assumptions. Primary interview insights were validated against customs and trade data, American Chemistry Council regional reports, SEC 10-K filings from listed chemical producers, and Environment Canada discharge permit databases. Bottom-up volume estimates from end-use application modeling were triangulated against top-down value projections derived from producer revenue disclosures.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by product form, application end-use, and regional production hub. Grade tier differentiation, corrosion inhibitor content, and certification level were incorporated as pricing dimensions. CAGRs were derived from historical volume trajectories adjusted for regulatory inflection points and infrastructure buildout timelines. Oilfield completion fluid intensity per well and county-level dust control program formalization rates served as industry-specific forecast inputs.
Stress conditions across brine extraction weather volatility, magnesium chloride substitution elasticity, and EPA chloride discharge threshold stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement trajectories and infrastructure investment timing. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Europe Titanium Dioxide Market
Bulk Chemicals
Dimethyl Disulphide (DMDS) Market
Bulk Chemicals
Antimony Trioxide Market
Bulk Chemicals
Isatoic Acid Anhydride Market
Bulk Chemicals
Para Nitrophenol Market
Bulk Chemicals
Global Ammonium Sulphate Market
Bulk Chemicals
Sulfamic Acid Market
Bulk Chemicals
Caprolactam Market
Bulk Chemicals
Nonprotein Nitrogen Market
Bulk Chemicals
Global Purified Terephthalic Acid (PTA) Market
Bulk Chemicals
Nickel Carbonate Market
Bulk Chemicals
Paraxylene(PX) Market
Bulk Chemicals
North America Potassium Formate Market
Bulk Chemicals
Green Petroleum Coke and Calcined Petroleum Coke Market
Bulk Chemicals
Ethylene Glycol Market
Bulk Chemicals
Metallurgical Coke Market