
 Iodine Market | 2026-2036
Iodine Market Size, Share, and Industry Trends Forecast 2026-2036
Iodine Market Intelligence
REACH compliance in Europe is pivoting the cost-of-entry calculus for iodine derivatives entering pharmaceutical and chemical supply chains. SQM leverages its Atacama Desert brine operations to sustain one of the world's lowest-cost iodine production positions. Iofina specializes in extracting iodine from oilfield brines in the United States, competing outside traditional caliche-based supply models. ISE Chemicals Corporation anchors Japanese domestic supply through integrated brine processing and downstream iodine chemistry capabilities.
Iodine is a halogen element with atomic number 53, occurring naturally in caliche ores, underground brines, and seaweed; manufacturers typically extract it through blow-out reduction from nitrate ores or ion-exchange recovery from brine effluents, with commercial grades ranging from resublimed crystals to pharmaceutical-grade potassium iodide exceeding 99.5% purity. The element serves as an essential precursor for X-ray contrast media, disinfectants, and catalytic intermediates in organic synthesis. Crystalline iodine and potassium iodide together command the dominant share of product-type value pools, reflecting their indispensability in pharmaceutical and chemical fabrication end uses. Animal feed additives represent the fastest-expanding application segment, driven by livestock nutrition mandates across major protein-producing regions.
The FDA enforces current Good Manufacturing Practice standards for iodine-containing drug substances, while the EPA monitors discharge limits from brine extraction facilities under the Clean Water Act; Japan's Ministry of Health, Labour and Welfare maintains pharmaceutical-grade iodine specifications through PMDA oversight. These frameworks collectively elevate purity thresholds and environmental compliance costs for new market entrants. Stakeholders must monitor evolving pharmaceutical serialization requirements and brine source depletion timelines to secure long-term feedstock positions.
Market Dynamics
Caliche ore and brine extraction concentration in Chile and Japan creates supply-side rigidity that pharmaceutical-grade buyers must navigate through long-term offtake contracts and vertical qualification programs.
Growth Catalysts
- Pharmaceutical-grade potassium iodide demand:Thyroid therapeutics and X-ray contrast media formulations require 99.5% purity minimums, pulling volume through FDA-validated supply chains.
- REACH compliance pivot:European chemical registration mandates are filtering non-compliant iodine derivatives from pharmaceutical and disinfectant supply chains, consolidating qualified supplier pools.
- Animal feed additive mandates:Livestock nutrition regulations across major protein-producing regions are embedding iodine supplementation into standard feed formulations.
Market Restraints
- Caliche ore supply concentration:Chilean nitrate deposits host the majority of economically recoverable reserves, creating single-source vulnerability for derivative manufacturers.
- Brine extraction discharge limits:EPA Clean Water Act monitoring elevates environmental compliance costs for US-based ion-exchange recovery operations.
- Seaweed-derived iodine substitution:Algal extraction methods compete on sustainability credentials in cosmetic and niche pharmaceutical applications.
Strategic Opportunities
- Oilfield brine valorization:Produced water streams in petroleum basins contain recoverable iodine concentrations, enabling geographic diversification of extraction sources.
- PMDA pharmaceutical-grade specifications:Japanese Ministry of Health, Labour and Welfare purity standards create premium positioning for qualified exporters into Asian pharmaceutical supply chains.
- Dual-use disinfectant-catalyst applications:Iodine's redox chemistry enables convergence between infection control and organic synthesis intermediate markets.
Industry Challenges
- Active pharmaceutical ingredient qualification timelines:FDA current Good Manufacturing Practice validation for iodine-containing drug substances extends supplier onboarding to 18-24 months.
- Legacy ion-exchange capacity reconfiguration:Brine processing facilities require substantial capital redeployment to shift between agricultural and pharmaceutical grade outputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iodine Market |
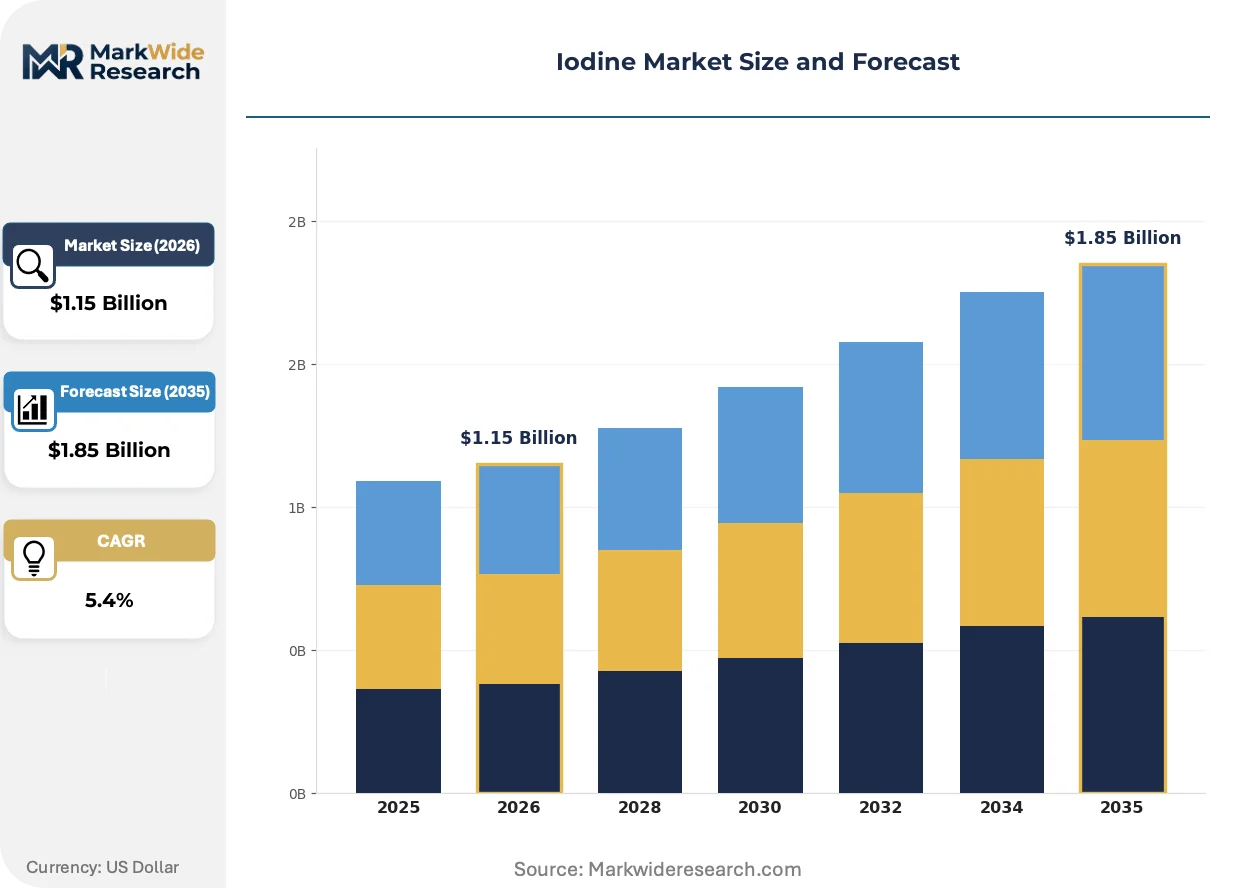
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $1.85 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crystalline Iodine, Potassium Iodide, Iodine Solution, Iodine Tincture, Iodine Tablets Application: Pharmaceuticals, Catalyst Production, Animal Feed Additive, Water Purification, Print Industry, Analytical Testing End User Industry: Pharmaceutical Manufacturers, Chemical Fabricators, Agriculture Suppliers, Textile Producers, Research Laboratories Packaging Type: Plastic Bottles, Glass Containers, Metal Drums, Paper Bags, Bulk Containers |
| Companies Covered | Iochem Corporation, GODO SHIGEN Co. Ltd, Cosayach, Itochu Chemical Frontier Corporation, Algorta Norte, Iofina, ISE Chemicals Corporation, ACF Minera SA, SQM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iodine Market Strategic Shifts & Innovations
Extraction technology maturation and regulatory serialization requirements are compressing supplier qualification cycles while fragmenting end-use specifications across pharmaceutical, agricultural, and industrial chemical channels.
Membrane-based selective ion recovery is integrating into brine processing flowsheets, replacing traditional blow-out reduction methods. Pharmaceutical manufacturers in the United States are adopting these systems to secure domestic feedstock positions. The technology is integrating purification and concentration steps, reducing intermediate handling and contamination risk for high-purity potassium iodide production.
Japan's PMDA has tightened pharmaceutical-grade iodine impurity profiles through revised pharmacopeial standards. This regulatory compression is disqualifying legacy caliche-derived material that previously met USP specifications. European and Asian contract manufacturers are responding by dual-qualifying Chilean and Japanese sources against the stricter Japanese benchmark.
Long-term offtake contracting is displacing spot purchasing among large pharmaceutical formulators. Procurement functions at contrast media producers now prioritize supply security over unit cost minimization. This behavioral shift is most visible in United States and German buying patterns, where three-to-five-year supply agreements now dominate volume planning for iodine derivatives.
Iodine Market Segmentation
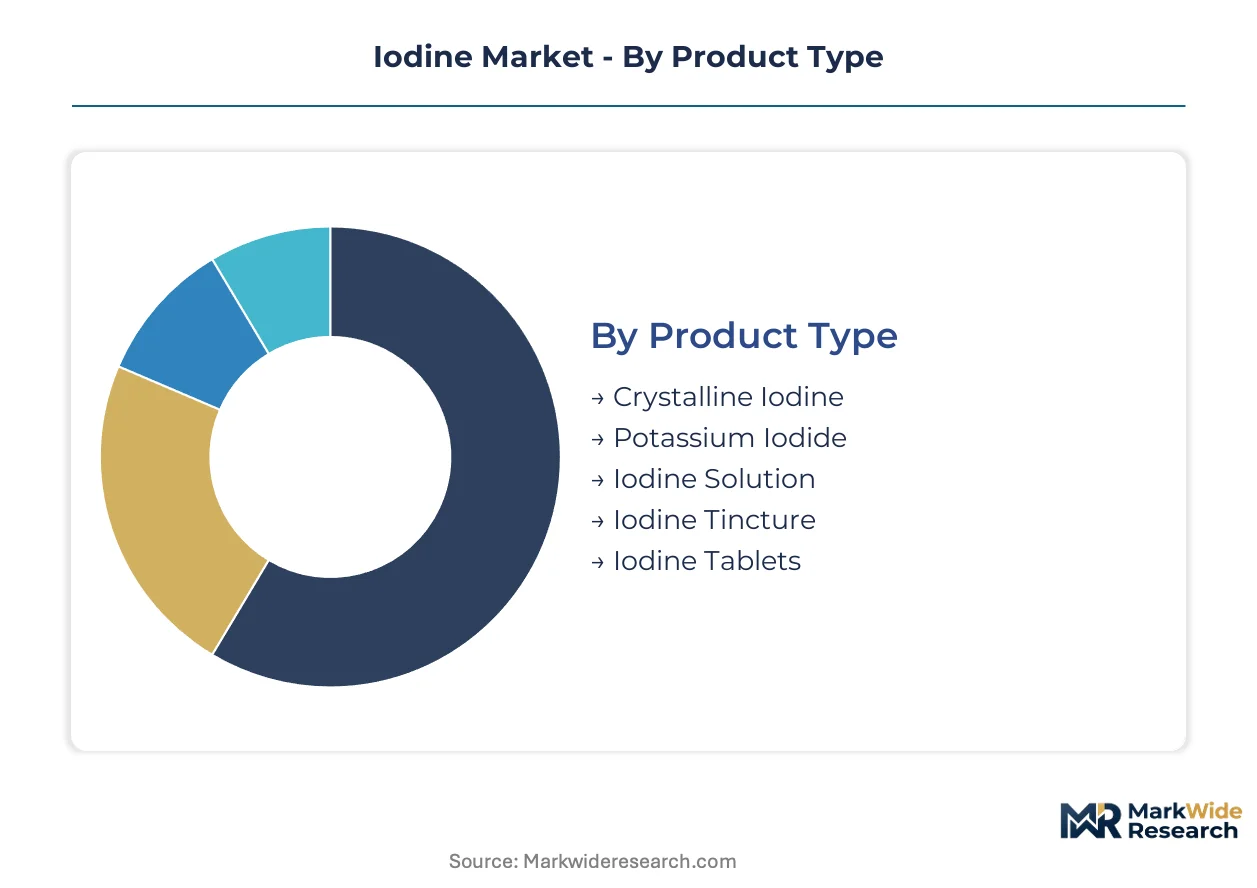
Iodine derivatives serve divergent purity requirements across pharmaceutical, agricultural, and industrial channels. Product specifications cascade from resublimed crystalline grades through formulated solutions, each demanding distinct extraction and handling protocols.
Product Type:
Upgrade cycles differentiate pharmaceutical-grade refinements from industrial commodity streams, with membrane-based ion recovery displacing legacy blow-out reduction for high-purity outputs.
- Crystalline Iodine:Resublimed solid form exceeding 99.8% purity serves as the foundational feedstock for downstream iodine chemistry. Demand concentrates among Japanese and United States pharmaceutical manufacturers seeking PMDA-validated and FDA-registered supply chains for contrast media synthesis.
- Potassium Iodide:Pharmaceutical-grade salt meeting 99.5% purity minimums functions as the preferred thyroid therapeutic precursor and dietary supplement active. United States formulators prioritize potassium iodide for emergency preparedness stockpiles and routine therapeutic compounding.
- Iodine Solution:Aqueous formulations at standardized concentrations support disinfectant and laboratory applications.
- Iodine Tincture:Alcohol-based preparations retain niche demand in antiseptic and veterinary wound care markets.
- Iodine Tablets:Compressed dosage forms concentrate in consumer health and emergency radiation protection segments.
Volume placements concentrate in crystalline iodine; the faster expansion belongs to potassium iodide.
Application:
Cost tier stratification separates pharmaceutical-grade premiums from agricultural commodity pricing, with regulatory qualification timelines widening the spread between validated and unvalidated supply channels.
- Pharmaceuticals:X-ray contrast media, thyroid therapeutics, and disinfectant actives require PMDA, FDA, and EMA-aligned impurity profiles. Japanese and German formulators drive specification tightening through revised pharmacopeial standards.
- Animal Feed Additive:Iodine supplementation in livestock nutrition mandates across major protein-producing regions embeds steady volume demand. Brazil, China, and United States feed compounders scale additive incorporation to meet export certification requirements.
- Catalyst Production:Redox chemistry intermediates support organic synthesis in specialty chemical manufacturing.
- Water Purification:Residual disinfection applications compete with chlorine and UV alternatives in municipal and recreational treatment systems.
- Print Industry:Silver halide photography and ink formulations sustain declining but persistent iodine consumption.
- Analytical Testing:Laboratory reagent-grade material supports titration and detection methodologies.
Pharmaceutical applications command the steepest margin premiums; animal feed additives are climbing the fastest.
End User Industry:
Customer concentration patterns reflect vertical integration incentives, with pharmaceutical manufacturers pursuing captive iodine recovery and chemical fabricators consolidating multi-source qualification programs.
- Pharmaceutical Manufacturers:Contrast media producers and generic drug formulators in the United States, Japan, and Germany enforce 18-24 month supplier onboarding timelines. FDA current Good Manufacturing Practice validation and PMDA pharmaceutical-grade specifications filter qualified sources.
- Chemical Fabricators:Specialty and commodity chemical producers in China and India absorb intermediate-purity iodine for catalytic and disinfectant derivative synthesis.
- Agriculture Suppliers:Feed premix and mineral supplement blenders distribute iodine across integrated livestock operations.
- Textile Producers:Dye and finishing chemical applications sustain regional demand in South Asian manufacturing clusters.
- Research Laboratories:Analytical and experimental consumption remains fragmented across institutional and commercial R&D facilities.
Procurement scale concentrates with pharmaceutical manufacturers; chemical fabricators are gaining share fastest.
Packaging Type:
Supply chain configuration determines containment selection, with pharmaceutical-grade material requiring inert, contamination-resistant formats and bulk agriculture shipments prioritizing cost-minimized logistics.
- Plastic Bottles:High-density polyethylene and fluoropolymer containers dominate pharmaceutical and laboratory distribution, with United States and European suppliers adopting serialization-ready labeling for FDA and EMA traceability mandates.
- Metal Drums:Stainless steel and epoxy-lined carbon steel drums handle intermediate bulk quantities for chemical fabricator and agriculture supplier deliveries.
- Glass Containers:Amber and clear borosilicate formats retain preference for light-sensitive and high-purity pharmaceutical applications.
- Paper Bags:Multi-wall industrial packaging serves non-hygroscopic agricultural and technical-grade shipments.
- Bulk Containers:ISO tanks and flexible intermediate bulk containers enable ocean freight optimization for large-volume chemical and agriculture customers.
Shipment volumes concentrate in metal drums; flexible bulk formats are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chile's Tarapacá Region hosts the Atacama Desert caliche deposits that concentrate global extraction capacity. Japanese brine operations in Chiba and Niigata prefectures anchor Asian pharmaceutical-grade supply. United States oilfield brine recovery in Oklahoma and Texas diversifies sourcing outside traditional nitrate ore dependence.
Chile
Caliche ore mining in the Atacama Desert supplies the majority of globally traded iodine feedstock. The country's national mining regulator enforces environmental compliance for nitrate extraction operations under updated tailings management protocols. Antofagasta and Iquique host integrated processing clusters where raw caliche undergoes blow-out reduction to crystalline grades.
Japan
Brine extraction from natural gas fields in Chiba and Niigata prefectures feeds domestic pharmaceutical chemistry demand. PMDA pharmaceutical-grade specifications set purity thresholds that disqualify lower-grade imports for thyroid therapeutic applications. Osaka and Tokyo pharmaceutical formulators maintain long-term offtake contracts with domestic brine processors to secure validated supply chains.
United States
Oilfield brine valorization in Oklahoma, Texas, and California enables geographic diversification of iodine recovery outside Chilean caliche dependence. FDA current Good Manufacturing Practice standards extend supplier qualification timelines to 18-24 months for contrast media manufacturers. New Jersey and Massachusetts pharmaceutical clusters drive specification tightening for potassium iodide used in emergency preparedness stockpiles.
Germany
REACH compliance mandates filter non-compliant iodine derivatives from pharmaceutical and disinfectant supply chains entering European customs territory. EMA-aligned impurity profiles now exceed legacy USP specifications for contrast media precursors. Frankfurt and Leverkusen chemical fabricators dual-qualify Chilean and Japanese sources against stricter pharmacopeial benchmarks.
China
Livestock nutrition mandates across Hebei, Shandong, and Henan provinces embed iodine supplementation into standard feed formulations for export-certified protein production. The country's national pharmaceutical regulator enforces Good Manufacturing Practice standards for iodine-containing drug substances through NMPA oversight. Shanghai and Jiangsu chemical clusters absorb intermediate-purity iodine for catalytic derivative synthesis.
Iodine Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across extraction and downstream chemistry tiers. Market structure concentrates upstream caliche and brine extraction among three geographic clusters, while derivative fabrication fragments across pharmaceutical, agricultural, and industrial channels. Strategic archetypes span integrated mining-chemical conglomerates, brine technology specialists, and regional trading houses. Dominant competitive moves include long-term offtake contracting and backward integration into captive feedstock recovery.
Among Chilean-based caliche operators, SQM and ACF Minera SA occupy positions within the integrated extraction tier, leveraging Atacama Desert brine and nitrate ore access. Iofina exemplifies the technology-driven specialist archetype, extracting iodine from oilfield brines in the United States through ion-exchange recovery systems. ISE Chemicals Corporation anchors Japanese domestic supply through integrated brine processing capabilities in Chiba and Niigata.
| Leading Market Players |
|---|
| Iochem Corporation |
| GODO SHIGEN Co. Ltd |
| Cosayach |
| Itochu Chemical Frontier Corporation |
| Algorta Norte |
| Iofina |
| ISE Chemicals Corporation |
| ACF Minera SA |
| SQM |
| Others |
Cost & Logistics Intelligence
Captive brine processing by Japanese pharmaceutical formulators anchors both supply security and premium pricing power for PMDA-validated iodine derivatives. This integration pattern insulates qualified suppliers from spot-market volatility while concentrating margin capture among vertically positioned domestic processors.
Pricing Analysis
Short-lead-time premiums dominate pharmaceutical procurement, with FDA-validated potassium iodide commanding substantial markups over standard crystalline grades. Three-tier pricing structure across pharmaceutical-grade, feed-grade, and technical-grade levels reflects certification investment and purity thresholds. Cost compression in feed-grade segments is intensifying because Brazilian and Chinese compounders scale volume purchases. Animal feed additive buyers exhibit the highest price sensitivity, while contrast media manufacturers prioritize supply security over unit cost minimization.
Supply Chain Analysis
Regional distribution centers in Antofagasta, Osaka, and Houston consolidate iodine flows before downstream pharmaceutical and chemical fabrication. Supply concentrates in Chile, Japan, and the United States, with Atacama caliche deposits, Chiba-Niigata brine fields, and Oklahoma-Texas oilfield recovery feeding distinct grade tiers. Raw material dependencies center on caliche ore nitrate content, brine iodine concentration, and ion-exchange resin capacity. Single-source vulnerability from Chilean caliche dominance creates structural exposure. Distribution runs through long-term offtake contracts rather than spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane-based selective ion recovery is displacing legacy blow-out reduction across pharmaceutical-grade extraction, compressing qualification timelines and reshaping competitive positioning.
For Market Incumbents: To counter membrane technology disruption from oilfield brine specialists, SQM and ISE Chemicals should deepen backward integration into captive resin manufacturing and accelerate PMDA dual-qualification programs for Chilean material. Certification investment represents the critical defensive lever against Japanese purity standard escalation. For New Entrants and Emerging Players: Capture underserved demand in animal feed premix distribution across Southeast Asian protein-producing regions, where iodine supplementation mandates are embedding but qualified local blending capacity remains scarce. Partner with regional agriculture suppliers for co-located iodine recovery from geothermal brines. For Investors and Strategic Acquirers: Exit pathways concentrate in trade-sale acquisition by diversified chemical conglomerates seeking iodine chemistry integration. Long-term viability hinges on securing brine source positions with depletion timelines extending across the analysis window. Watch PMDA pharmacopeial revision cycles as inflection indicators for grade-tier repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Technology Deployment | Oilfield brine processors in Oklahoma and Texas secure FDA-validated supply chains without caliche dependence. |
| PMDA Dual-Qualification Program | < td>Chilean exporters access Japanese pharmaceutical formulators previously blocked by impurity profile restrictions.|
| Long-Term Offtake Contracting | Contrast media manufacturers in New Jersey and Massachusetts lock in potassium iodide supply security. |
| Backward Integration into Brine Recovery | Pharmaceutical formulators reduce single-source exposure to Atacama production concentration. |
| Feed-Grade Capacity Expansion | Brazilian and Chinese compounders meet export certification requirements for iodine-supplemented livestock nutrition. |
Research Approach
Trade statistics from customs authorities, pharmacopeial regulatory filings, and chemical industry association reports formed the secondary backbone of this analysis. Primary interviews with iodine extraction plant managers, pharmaceutical procurement leads at contrast media manufacturers, feed premix compounders, and ion-exchange technology suppliers validated supply-side and demand-side assumptions. Bottom-up volume modeling triangulated against top-down market sizing from extraction capacity and grade-tier production data.
Historical trendline analysis of caliche ore extraction rates, brine field iodine concentration declines, and pharmaceutical-grade price spreads informed the projection framework. Segmentation modeling covered product purity tiers, end-use applications across pharmaceutical and agricultural channels, packaging formats, and regional production hub classifications. CAGRs derived from regression analysis of extraction capacity expansion timelines and downstream demand elasticity across the forecast period. Forecast inputs incorporated PMDA specification revision schedules and EPA discharge limit enforcement trajectories.
The model holds under stable brine source depletion rates and unchanged pharmacopeial standards; deviation in Japanese impurity threshold tightening or Chilean tailings regulation would shift volume and value outputs. Forecasts reflect documented assumptions about membrane technology adoption curves and long-term contracting penetration. Periodic stress-testing of base assumptions against regulatory filing patterns and extraction technology deployment is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Propionic Anhydride Market
Bulk Chemicals
Pivaloyl Chloride Market
Bulk Chemicals
Asia-Pacific Formaldehyde Market
Bulk Chemicals
Meta Tartaric Acid Market
Bulk Chemicals
Global Linear Alpha Olefins Market
Bulk Chemicals
Global Ammonium Chloride Market
Bulk Chemicals
Cesium Hydroxide Market
Bulk Chemicals
Magnesium Phosphate Market
Bulk Chemicals
Global Bitumen Market
Bulk Chemicals
North America Hydrochloric Acid Market
Bulk Chemicals
Acetyl Tributyl Citrate Market
Bulk Chemicals
Sodium Bromide Market
Bulk Chemicals
Caprylic Acid Market
Bulk Chemicals
Sodium Selenite Market
Bulk Chemicals
Calcium Hydrogen Sulphite Market
Bulk Chemicals
Global Linear Alkyl Benzene Market