
 FT Wax Market | 2026-2036
FT Wax Market Size, Share, and Industry Trends Forecast 2026-2036
FT Wax Market Analysis
Technical service contracts for viscosity modification and custom melt-point blending are recalibrating how FT wax suppliers monetize long-term relationships. Sasol leverages its Fischer-Tropsch integration from coal-to-liquids feedstock to sustain cost-advantaged supply of high-melt synthetic waxes. Shell plc anchors its position through backward integration into gas-to-liquids facilities that secure consistent feedstock quality. Evonik Industries AG differentiates via specialized micronization capabilities that serve exacting coating and personal care specifications.
Fischer-Tropsch wax consists of saturated linear paraffinic hydrocarbons produced via catalytic hydrogenation of carbon monoxide, with typical congealing points ranging from 60°C to 115°C and low oil content below 0.5 percent. These properties deliver precise hardness, gloss control, and thermal stability for adhesives, inks, and polymer processing aids. Synthetic wax within the product type spectrum leads volume contribution due to its superior consistency and regulatory acceptance, while microcrystalline wax retains entrenched positions in food packaging where pliability and moisture barrier performance command premium positioning. The coatings application segment generates concentrated margin pools as automotive and industrial formulators specify narrow melt-range grades for powder coating additives and can lining systems.
REACH registration requirements administered by ECHA mandate full substance characterization and toxicity profiling for FT wax imports into European Union member states, elevating compliance costs for non-integrated distributors. The EPA oversees wax incorporation into food-contact coatings under 21 CFR 175.105, with specific migration limits that constrain formulation flexibility for suppliers targeting United States food processors. ISO 22000 and FSSC 22000 certifications increasingly function as market access prerequisites for wax suppliers seeking entry into multinational food and cosmetics supply chains. Stakeholders must monitor evolving PFAS restrictions in coating applications and assess captive blending capabilities against third-party technical service dependencies.
Market Dynamics
REACH compliance thresholds in Europe are tightening impurity specifications for food-contact wax applications, forcing reformulation investments across coating and personal care supply chains while consolidating procurement toward integrated suppliers with captive analytical capabilities.
Growth Catalysts
- Coal-to-liquids integration:South African and Chinese producers leverage Fischer-Tropsch synthesis from synthetic gas feedstocks to secure cost-advantaged paraffin supply for high-melt wax grades.
- Cosmetics-grade purity mandates:Skincare formulators in Germany and France specify sub-0.5% oil content synthetic waxes for emulsion stability, pulling volume toward hydrogenated Fischer-Tropsch grades.
- REACH substance characterization:ECHA registration requirements for FT wax imports elevate compliance barriers that favor established registrants with existing toxicity dossiers.
Market Restraints
- Crude oil price linkage:Naphtha-derived synthetic wax alternatives expose Fischer-Tropsch producers to feedstock cost volatility when petroleum benchmarks swing.
- South African supply concentration:Coal-to-liquids wax output clusters in the Secunda corridor, creating geographic single-point vulnerability for global high-melt supply.
- Microcrystalline substitution:Petroleum-derived microcrystalline wax retains entrenched positions in food packaging where pliability and moisture barrier performance command premium positioning.
Strategic Opportunities
- Indian coating expansion:Industrial powder coating growth in Maharashtra and Gujarat creates demand for narrow melt-range FT wax additives with precise gloss control.
- PFAS-free coating mandates:EPA and state-level restrictions on fluorinated compounds in can linings and industrial coatings open formulation windows for paraffin-based alternatives.
- Technical service unbundling:Custom viscosity modification and melt-point blending contracts allow suppliers to capture recurring revenue beyond commodity wax sales.
Industry Challenges
- Catalytic hydrogenation expertise:Fischer-Tropsch wax production requires specialized process engineers familiar with cobalt and iron catalyst management, a skill set concentrated at legacy coal-to-liquids facilities.
- ISO 22000 certification timelines:Food and cosmetics supply chain entry demands 12-18 month audit cycles that delay market access for new FT wax entrants.
- Legacy coating formulation lock-in:Automotive and industrial powder coating customers maintain qualified supplier lists that resist rapid switching even when alternative wax grades offer performance advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FT Wax Market |
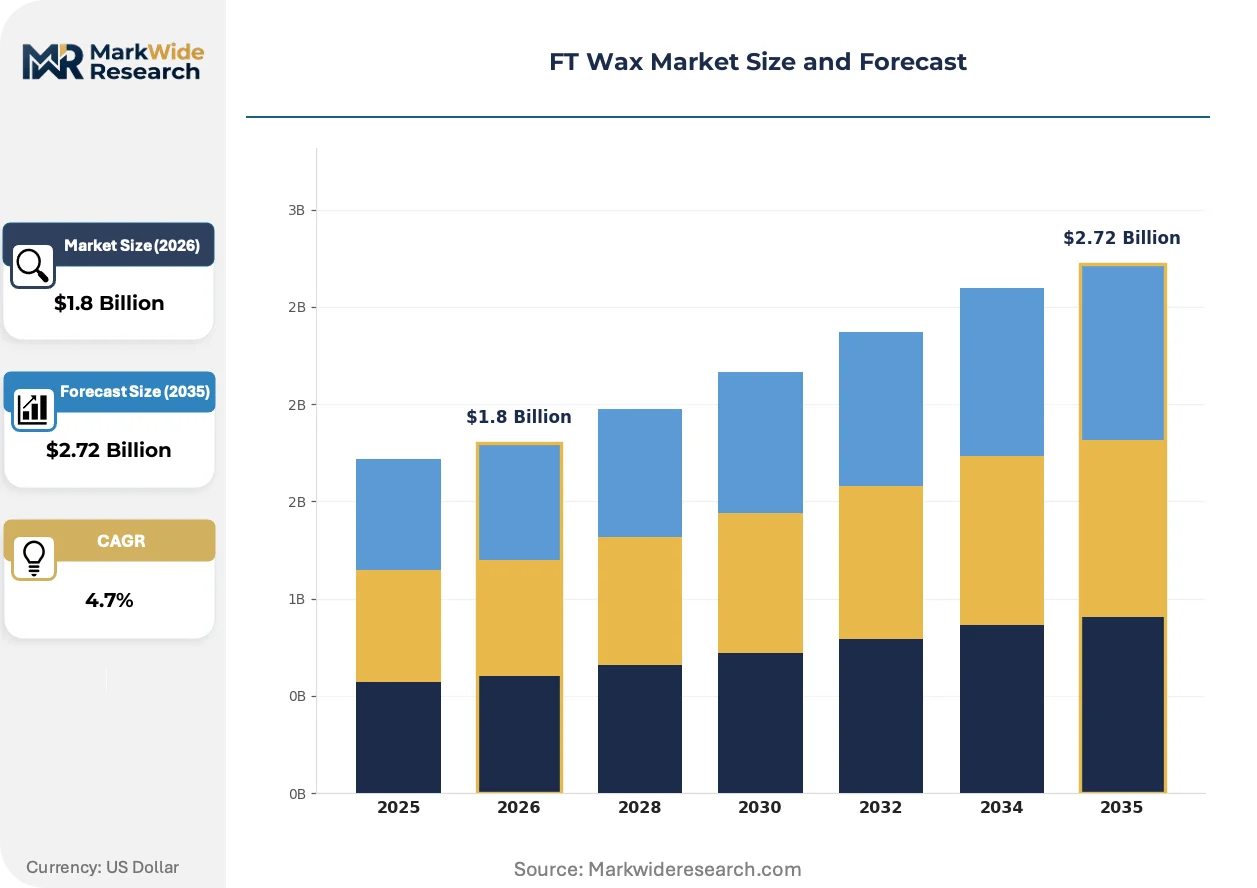
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paraffin Wax, Microcrystalline Wax, Beeswax, Synthetic Wax Application: Candles, Coatings, Personal Care, Food Packaging End User: Cosmetics Manufacturers, Food Processors, Industrial Users, Artisans Distribution Channel: Online Retail, Wholesale Distributors, Direct Sales, Specialty Stores |
| Companies Covered | Sasol, Shell plc, Evonik Industries AG, Clariant, Deurex AG, Nippon Seiro Co. Ltd., Honeywell International Inc., Mitsui Chemicals, Inc., Hywax GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FT Wax Market Emerging Trajectories
Process intensification and regulatory chemistry are reshaping how Fischer-Tropsch wax producers compete. Synthesis optimization, compliance-driven purification, and service-model reinvention now separate margin leaders from commodity suppliers.
Micronization technology is overtaking conventional crushing and spray-cooling methods for coating-grade wax production. Precision particle size control below 20 microns enables superior dispersion in powder coating formulations. Automotive OEMs in Germany and Japan specify micronized grades for consistent film formation, compressing demand for standard-mesh waxes in premium applications.
REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons are tightening maximum allowable PAH content in waxes used for food-contact coatings and toys. ECHA enforcement is pushing importers toward hydrogenated Fischer-Tropsch grades with inherently lower aromatic content. Coating formulators in France and the Netherlands are accelerating qualification of synthetic paraffin alternatives to petroleum-derived slack wax.
Technical service contracts now bundle viscosity modification, melt-point blending, and application testing into multi-year supply agreements. Coating and adhesive manufacturers in the US Midwest and German Ruhr region favor suppliers offering captive formulation support over commodity distributors. This service integration locks in volume commitments while capturing margin pools that previously flowed to third-party compounders.
FT Wax Market Segmentation
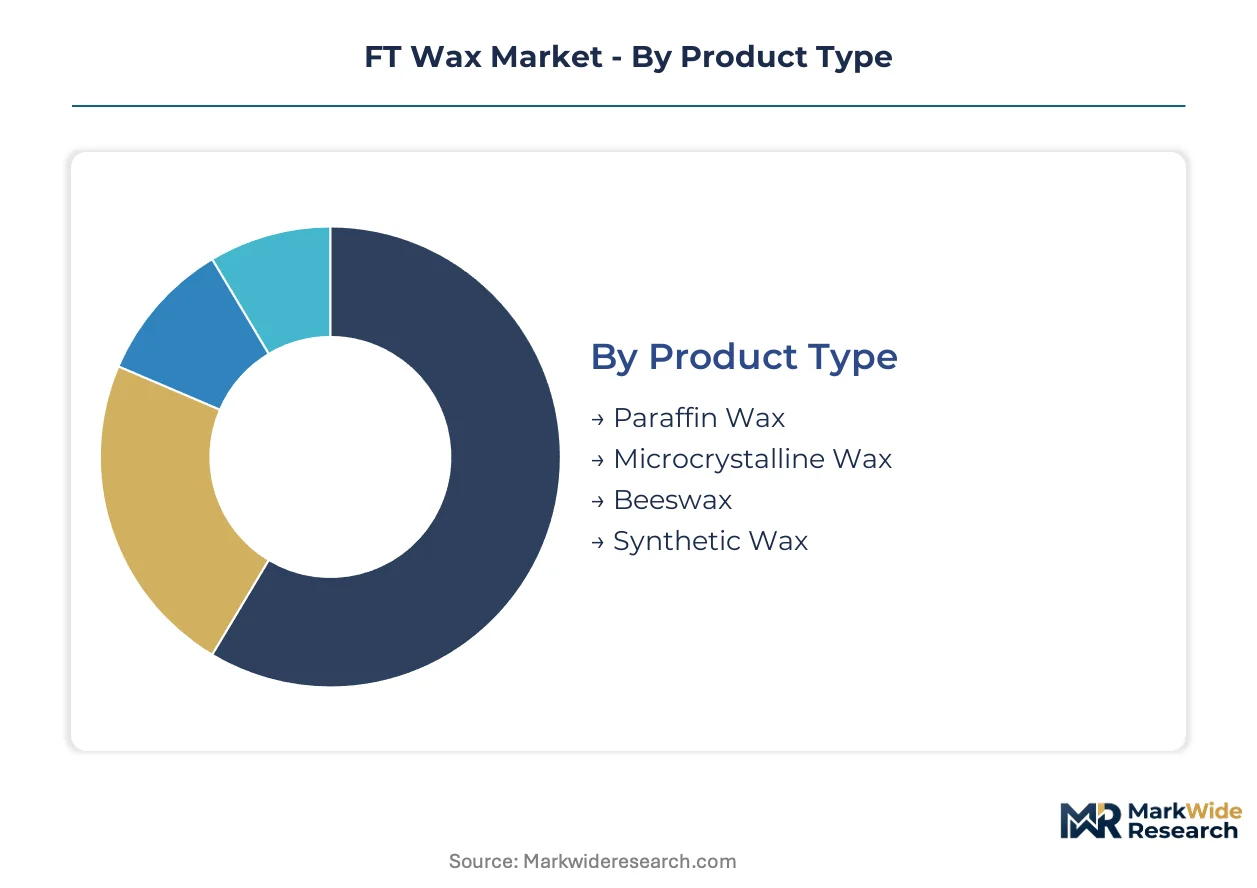
FT wax buyers segment procurement across purity grades, application performance, and regulatory compliance tiers. Suppliers configure production runs around melt-point specifications and end-use certification requirements rather than commodity volume alone.
Product Type:
Synthetic wax commands volume leadership through Fischer-Tropsch hydrogenation consistency, while beeswax and microcrystalline alternatives defend premium niches through natural-origin positioning or barrier performance.
- Synthetic Wax:Saturated linear paraffinic hydrocarbons produced via catalytic hydrogenation of carbon monoxide, delivering sub-0.5% oil content and congealing points from 60°C to 115°C. German cosmetics manufacturers specify these grades for emulsion stability in skincare formulations, pulling volume toward hydrogenated Fischer-Tropsch supply with REACH-compliant impurity profiles.
- Paraffin Wax:Petroleum-derived straight-chain alkanes with broader molecular weight distribution and higher oil content than Fischer-Tropsch equivalents. Price-sensitive candle manufacturers in India and Poland blend paraffin with synthetic wax to manage raw material costs while maintaining burn characteristics.
- Microcrystalline Wax:Branched and cyclic hydrocarbons with amorphous structure providing pliability and moisture barrier performance. Food packaging applications in France and Italy specify microcrystalline grades for flexible wrap coatings where conformability trumps thermal stability.
- Beeswax:Natural ester-based wax from honeycomb with distinctive aroma and color variation. Artisan candle makers and organic cosmetics formulators in California and Bavaria pay premiums for certified organic beeswax despite batch-to-batch inconsistency.
Today's leader: Synthetic Wax. Tomorrow's challenger: Microcrystalline Wax.
Application:
Coatings generate concentrated margin pools through technical service bundling, while personal care and food packaging segments demand escalating purity certification.
- Coatings:Powder coating additives and can lining systems specify narrow melt-range grades with precise gloss control. Automotive OEMs in Germany and Japan require micronized wax below 20 microns for consistent film formation, compressing demand for standard-mesh products in premium applications.
- Personal Care:Skincare and color cosmetics formulations leverage synthetic wax for viscosity modification and emulsion stabilization. French and German formulators specify sub-0.5% oil content grades, accelerating qualification of hydrogenated Fischer-Tropsch alternatives to petroleum-derived slack wax.
- Candles:Container and pillar candle production blends paraffin, synthetic, and natural waxes to optimize burn time and fragrance throw. Artisan producers in Poland and the US Midwest source through wholesale distributors with custom melt-point blending capabilities.
- Food Packaging:Coatings for paperboard and flexible films require FDA 21 CFR 175.105 compliance with specific migration limits. US food processors maintain qualified supplier lists that resist rapid switching even when alternative wax grades offer performance advantages.
Coatings dominate current margins. Personal care climbs fastest on purity mandates.
End User:
Industrial users drive volume through technical service contracts, while cosmetics manufacturers concentrate procurement on certified high-purity grades.
- Cosmetics Manufacturers:Skincare and color cosmetics formulators in Germany and France specify REACH-registered synthetic wax grades with full substance characterization. ECHA registration requirements elevate compliance barriers that favor established registrants with existing toxicity dossiers.
- Industrial Users:Adhesive, ink, and polymer processing compounders negotiate multi-year supply agreements bundling viscosity modification and application testing. Coating manufacturers in the US Midwest and German Ruhr region favor suppliers offering captive formulation support over commodity distributors.
- Food Processors:Can lining and paperboard coating operations require FDA-compliant wax grades with documented migration testing. ISO 22000 and FSSC 22000 certifications function as market access prerequisites for suppliers seeking entry into multinational food supply chains.
- Artisans:Small-batch candle makers and craft producers purchase through specialty stores and online retail channels. Price sensitivity drives blending of paraffin and synthetic wax, with limited penetration of premium Fischer-Tropsch grades.
Industrial users anchor volume. Cosmetics manufacturers command premium pricing.
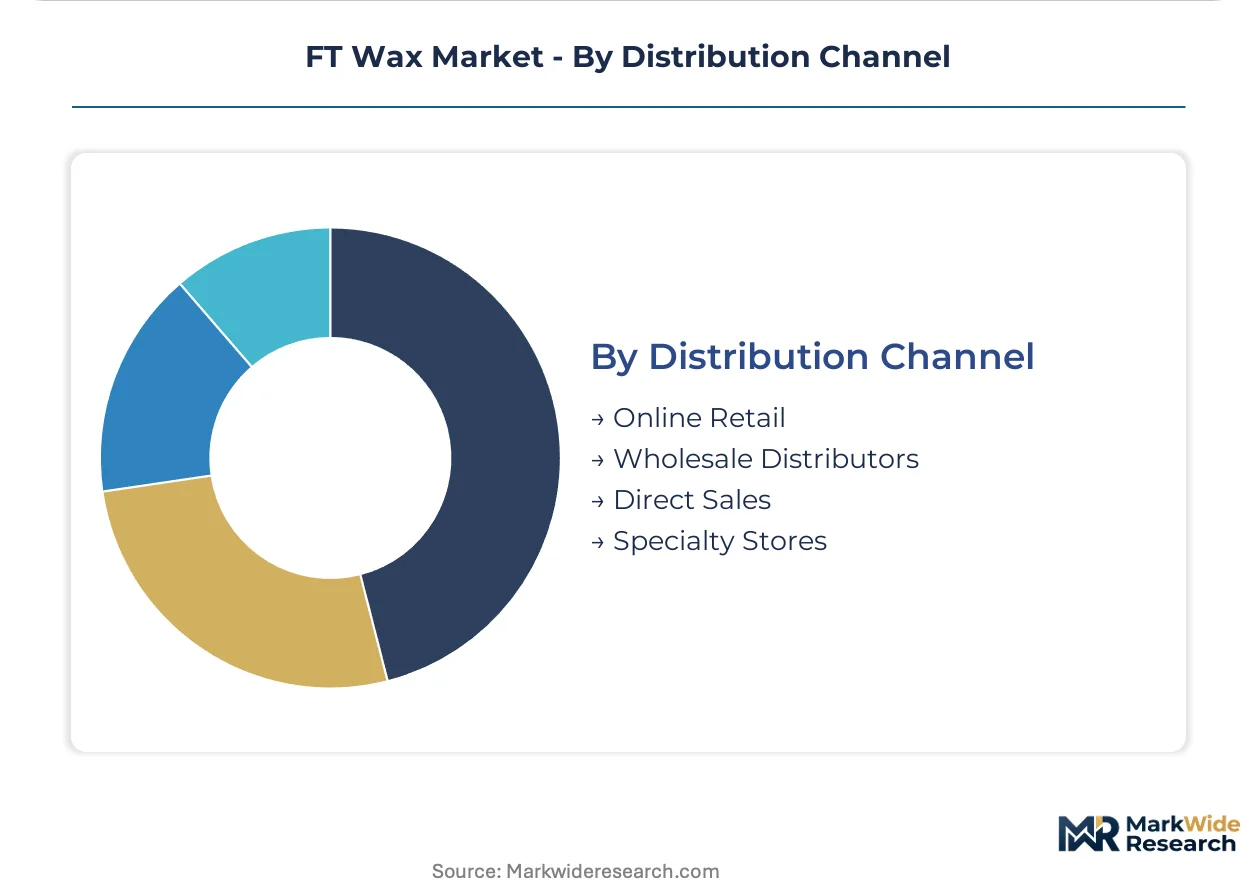
Distribution Channel:
Wholesale distributors retain channel power through technical inventory and blending services, while direct sales capture strategic accounts with formulation integration needs.
- Wholesale Distributors:Regional chemical distributors stock multiple melt-point grades and provide custom blending for mid-size coating and adhesive manufacturers. Inventory carrying costs and technical service capabilities create switching costs that lock in supplier relationships.
- Direct Sales:Integrated Fischer-Tropsch producers sell directly to multinational cosmetics and food packaging customers, bypassing distributor margins on high-volume contracts. Sasol and Shell plc leverage backward integration into coal-to-liquids and gas-to-liquids feedstock to sustain cost-advantaged supply.
- Online Retail:E-commerce platforms serve artisan candle makers and small cosmetics formulators with packaged wax quantities below distributor minimums. Price transparency pressures regional distributors on commodity grades.
- Specialty Stores:Local suppliers stock beeswax and premium natural wax grades for organic cosmetics producers and craft markets. Limited geographic reach constrains volume contribution.
Wholesale distributors defend channel position. Direct sales expand through technical service bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redrawing production footprints as compliance-cost differentials between jurisdictions widen. Integrated Fischer-Tropsch producers migrate capacity toward regions with captive feedstock and streamlined chemical registration pathways.
Germany
Specialty chemical clusters in North Rhine-Westphalia and Bavaria drive procurement of sub-0.5% oil content synthetic waxes for cosmetics emulsion stability. ECHA REACH registration requirements mandate full substance characterization, elevating compliance barriers that favor established registrants with existing toxicity dossiers. The Ruhr industrial corridor concentrates coating formulators specifying narrow melt-range grades for automotive powder coating applications.
United States
Food processors in the Midwest and Southeast maintain qualified supplier lists for FDA 21 CFR 175.105-compliant wax grades used in can lining systems. EPA oversight of food-contact coatings constrains formulation flexibility with specific migration limits. Technical service bundling in Ohio and Michigan locks in multi-year supply agreements with captive viscosity modification capabilities.
China
Coal-to-liquids integration in Shanxi and Inner Mongolia secures cost-advantaged paraffin supply for high-melt wax grades serving domestic coating expansion. MIIT standards and evolving environmental compliance reshape hydrogenation facility permitting. The Yangtze River Delta concentrates industrial powder coating growth creating demand for micronized wax additives below 20 microns.
South Africa
The Secunda corridor anchors global high-melt Fischer-Tropsch wax output from synthetic gas feedstock, creating geographic supply concentration. Domestic regulatory frameworks align with export market requirements for REACH-registered grades. Sasol's captive coal-to-liquids integration sustains cost positioning for international specialty wax distribution.
India
Industrial powder coating growth in Maharashtra and Gujarat generates demand for narrow melt-range FT wax additives with precise gloss control. BIS standards and import registration requirements elevate barriers for unqualified foreign suppliers. The Mumbai-Pune chemical belt concentrates formulation technical service providers serving domestic coating manufacturers.
FT Wax Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated Fischer-Tropsch producers commanding premium positioning in regulated applications while regional compounders serve price-sensitive blending demand. The vendor base organizes around three archetypes: backward-integrated feedstock owners with captive hydrogenation assets, specialized micronization and technical service providers, and regional distributors with custom blending capabilities. Competitive intensity concentrates on M&A-driven consolidation of formulation expertise and geographic expansion through technical service bundling rather than commodity volume alone.
Among integrated feedstock owners, Sasol, Shell plc, and Evonik Industries AG exemplify distinct strategic positioning archetypes. Sasol represents the coal-to-liquids integration model with synthetic gas feedstock control. Shell plc anchors the gas-to-liquids pathway securing consistent feedstock quality from upstream hydrocarbon positions. Evonik Industries AG occupies the specialized capabilities tier, with micronization and application testing services differentiating beyond commodity wax supply. These three entities illustrate how feedstock access, regulatory compliance infrastructure, and technical service depth combine to define sustainable competitive position in a market where purity mandates and certification timelines increasingly determine procurement decisions.
| Leading Market Players |
|---|
| Sasol |
| Shell plc |
| Evonik Industries AG |
| Clariant |
| Deurex AG |
| Nippon Seiro Co. Ltd. |
| Honeywell International Inc. |
| Mitsui Chemicals, Inc. |
| Hywax GmbH |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed producers in South Africa and state-linked coal-to-liquids operators in China anchor supply concentration, translating captive feedstock control into pricing discipline that resists commodity volatility. Their integrated hydrogenation assets compress procurement alternatives for European and Indian coating formulators, tightening margin capture at the production node.
Pricing Analysis
Capacity additions in China's Shanxi province are reshaping price floors for high-melt Fischer-Tropsch grades. Contract-based long-term offtake dominates procurement, with price differentiation driven by REACH certification tier and micronization capability. Cost compression in standard-mesh waxes is intensifying because South African supply concentration limits spot-market liquidity. Artisan candle makers exhibit highest price sensitivity, while German cosmetics manufacturers accept premiums for sub-0.5% oil content grades.
Supply Chain Analysis
Direct-to-industrial channels handle multinational coating and adhesive demand, while wholesale distributors serve mid-size compounders with custom blending. Supply concentrates in South Africa, China, and Germany. Production draws from synthetic gas feedstocks, cobalt and iron catalysts, and hydrogen supply. Single-source vulnerability runs through the Secunda corridor's dominance of high-melt output. Distribution runs through technical service-integrated agreements that bundle formulation support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Fischer-Tropsch wax rests on purification technology cost-down curves and cosmetics-grade purity tier shifts. Hydrogenation efficiency gains and REACH compliance automation compress production economics while premium grades capture widening spreads.
For Market Incumbents: Deploy captive micronization capabilities to lock in automotive OEM specifications in Germany and Japan. Consolidate formulation technical service contracts in the US Midwest before regional compounders scale blending capacity. Microcrystalline substitution in food packaging threatens volume retention; counter with ECHA-registered hydrogenated grades that satisfy tightening PAH thresholds. For New Entrants and Emerging Players: Specialty chemical distributors in India's Mumbai-Pune belt offer the most penetrable channel for narrow melt-range wax qualification. Target industrial powder coating expansion in Maharashtra and Gujarat with technical service partnerships that bypass ISO 22000 certification timelines. Qualify PFAS-free coating mandates as the fastest route to specification wins against entrenched fluorinated alternatives. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors with custom blending capabilities but limited REACH registration infrastructure. Five-to-ten year viability favors acquisition of micronization technology specialists serving coating applications. Watch ECHA enforcement patterns on PAH content as the inflection signal for hydrogenated grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Gas Production | Sasol's Secunda coal-to-liquids complex secures cost-advantaged paraffin supply for high-melt wax output. |
| Micronization Capacity Expansion | Precision particle control below 20 microns qualifies suppliers for German automotive powder coating specifications. |
| REACH Registration Dossier Completion | ECHA substance characterization elevates compliance barriers that favor established registrants with existing toxicity profiles. |
| Technical Service Contract Bundling | Multi-year agreements with viscosity modification lock in volume commitments from US Midwest coating manufacturers. |
| PFAS-Free Formulation Qualification | EPA restrictions on fluorinated compounds in can linings open specification windows for paraffin-based alternatives. |
Methodological Framework
Multiple input streams — procurement directors at coating manufacturers, technical R&D leads at Fischer-Tropsch producers, distribution channel partners in Europe and India, and regulatory affairs specialists — were reconciled against customs trade data, ECHA registration databases, SEC filings from integrated energy majors, and Cefic chemical industry reports. Bottom-up volume builds from end-use consumption patterns were cross-validated against top-down production capacity assessments across the analysis window.
Historical volume trajectories were cross-referenced against panel input from plant managers and OEM procurement leads to construct the analytical framework. Segmentation modeling incorporated grade tier, end-use industry, regional production hub, and certification status. CAGRs were derived from slope analysis of normalized growth curves, with hydrogenation capacity utilization rates and REACH compliance cost trajectories serving as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to South African supply disruption, Chinese environmental permitting shifts, and ECHA PAH threshold revisions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Calcium Hypophosphite Market
Bulk Chemicals
Isophorone Market
Bulk Chemicals
Lignin Waste Market
Bulk Chemicals
Potassium Chlorate Market
Bulk Chemicals
Glyceryl Triacetate (Triacetin) Market
Bulk Chemicals
Global Bulk Ferroalloys Market
Bulk Chemicals
Sodium Bromate Market
Bulk Chemicals
Cobalt (II) Sulfate Market
Bulk Chemicals
Putty Powder Market
Bulk Chemicals
Atrazine Market
Bulk Chemicals
Barium Sulfite Market
Bulk Chemicals
Aluminum Sulfate Market
Bulk Chemicals
Sodium Hypophosphite Market
Bulk Chemicals
Asia-Pacific Starch Derivatives Market
Bulk Chemicals
Europe Acetic Acid Market
Bulk Chemicals
M, P-Cresol Market