
 Ethyleneamines Market | 2026-2036
Ethyleneamines Market Size, Share, and Industry Trends Forecast 2026-2036
Ethyleneamines Market Analysis
Specialty epoxy formulators is redrawing procurement patterns in the ethyleneamines value chain, shifting volume toward higher-purity grades for electronics and wind turbine blade applications. Nouryon leverages its integrated ethylene oxide pipeline to sustain cost-competitive positions in European ethylenediamine supply. Huntsman Corporation anchors North American demand through captive consumption at its downstream epoxy resin facilities. Evonik Industries differentiates via specialized higher molecular weight polyamine grades for fuel additive and gas treatment markets.
Ethyleneamines comprise a family of nitrogen-containing organic compounds produced through the reaction of ethylene dichloride with ammonia, yielding linear and cyclic polyamines with varying nitrogen content and molecular weights. These compounds function primarily as chemical intermediates, curing agents, chelating agents, and surfactant precursors across industrial manufacturing processes. Ethylenediamine dominates volume consumption as the foundational building block for chelating agents and pharmaceutical synthesis, while triethylenetetramine commands premium positioning in high-performance epoxy curing applications for aerospace and wind energy composites. The agrochemicals application segment is gaining structural importance as manufacturers formulate advanced fungicide and nematicide products requiring precise amine functionality.
EPA emissions standards under the Clean Air Act and OSHA workplace exposure limits govern US manufacturing facility operations, while REACH registration and CLP classification requirements in Europe impose substantial compliance documentation burdens on importers and producers. China's MEE enforces wastewater discharge standards that affect ethylene dichloride-based production economics at domestic amine complexes. Stakeholders must monitor regulatory divergence between jurisdictions as carbon border adjustment mechanisms and green chemistry initiatives reshape competitive access to key end-use markets.
Market Dynamics
Specialty agrochemical formulators are redrawing procurement specifications toward higher-purity ethylenediamine grades, forcing producers to reconfigure purification trains and quality certification protocols across integrated amine complexes.
Growth Catalysts
- REACH Registration Requirements:European ECHA mandates for full substance dossiers are filtering out marginal producers and consolidating supply among compliant integrated manufacturers with dedicated regulatory affairs capabilities.
- Wind Turbine Blade Manufacturing:Triethylenetetramine demand is accelerating from epoxy composite fabricators serving offshore wind installation programs in the North Sea and China's coastal provinces.
- Eastern China Chemical Corridor:Integrated ethylene oxide-amine complexes in Jiangsu and Zhejiang provinces are capturing export volume through captive chlorine-alkali integration and port logistics advantages.
Market Restraints
- Ethylene Dichloride Feedstock Volatility:Chlor-alkali energy intensity and European natural gas pricing swings transmit directly to ethyleneamines variable cost structures.
- MEA Substitution in Gas Treatment:Monoethanolamine reformulation is displacing higher molecular weight polyamines in selective carbon capture retrofits at North American power generation facilities.
- EPA NESHAP Compliance Burden:Hazardous air pollutant monitoring and control technology investments at US Gulf Coast production sites compress operating margins for non-integrated producers.
Strategic Opportunities
- India Agrochemical Formulation:CDSCO accelerated registration pathways for technical-grade intermediates are opening procurement relationships with domestic fungicide manufacturers in Gujarat and Maharashtra.
- EU Green Deal Carbon Border Adjustments:CBAM implementation on imported chemicals creates margin protection for European producers with verified low-carbon ethylene oxide supply chains.
- Bio-Based Ethylene Oxide Convergence:Ethanol-to-ethylene process integration with conventional amination technology is enabling certified renewable content claims for pharmaceutical-grade ethylenediamine.
Industry Challenges
- Process Safety Expertise Scarcity:Experienced operations personnel for high-pressure amination reactor management are retiring faster than training programs replace them at legacy production facilities.
- Pharmaceutical GMP Certification Timelines:FDA and EMA active pharmaceutical ingredient qualification protocols extend 18-24 months, freezing capacity allocation decisions until regulatory approval confirms.
- Legacy Control System Integration:Distributed control system upgrades at 1990s-era plants require extended shutdown windows that conflict with continuous operation requirements for per-unit cost competitiveness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethyleneamines Market |
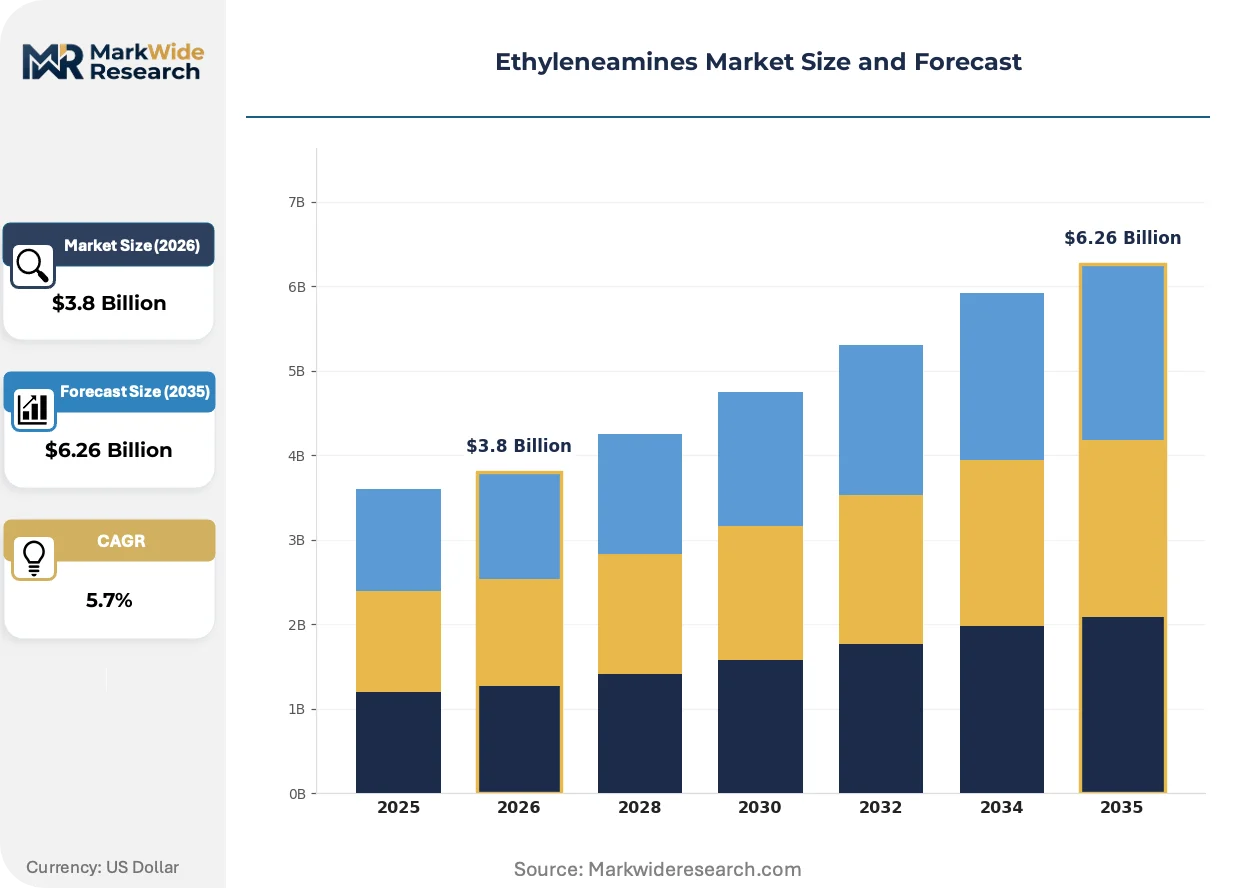
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diethylenetriamine, Triethylenetetramine, Ethylenediamine, Aminopropyltriethoxysilane Application: Epoxy Resin, Agrochemicals, Gas Treatment, Fuel Additives End User: Aerospace, Automotive, Construction, Pharmaceuticals Technology: Chemical Synthesis, Polymerization, Surface Treatment, Coating |
| Companies Covered | Nouryon, Delamine BV, Huntsman Corporation, Evonik Industries, Arabian Amines Company, Dow, Tosoh Corporation, Akzo Nobel N.V., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethyleneamines Market Emerging Trajectories
Continuous processing technology and modular purification units are displacing batch operations across ethyleneamines manufacturing, enabling tighter product distribution curves and reduced solvent waste generation.
Membrane-based separation technology is fragmenting conventional distillation-dominated purification economics. Thin-film composite membranes for water-amine separation are reducing energy consumption by half at pilot installations. Specialty epoxy formulators in Germany and Japan are qualifying membrane-purified triethylenetetramine for aerospace prepreg applications. The technology is compressing capital requirements for new entrant producers in lower-wage manufacturing jurisdictions.
China's MEE wastewater discharge standards are tightening total nitrogen limits for ethylene dichloride-based production facilities. The regulation is forcing caustic scrubber upgrades and biological treatment expansion at integrated complexes in the Yangtze River Delta. Domestic producers with captive electrolysis and chlorine recovery systems are absorbing compliance costs more readily than merchant chlorine-dependent competitors.
Specification-driven spot purchasing is replacing annual volume contracts among North American specialty chemical distributors. Large epoxy resin compounders are unbundling logistics and inventory management from product pricing, selecting providers through competitive tendering each quarter. The pattern is most pronounced in Texas and Ohio manufacturing corridors where multiple distributor options create price transparency.
Ethyleneamines Market Segmentation
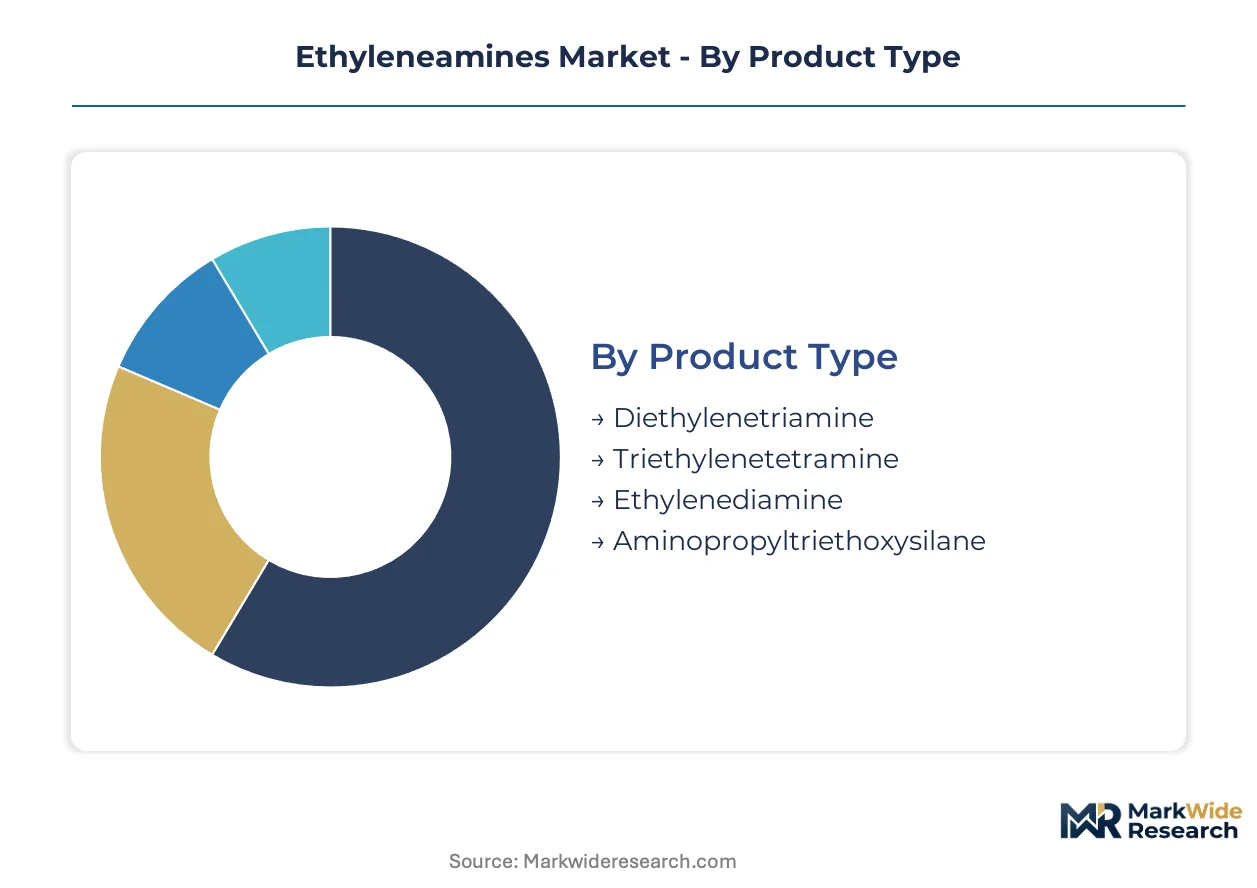
Ethyleneamines exhibit sharply divergent purity and certification requirements across end-use applications. Pharmaceutical and aerospace specifications impose GMP and AS9100 traceability that commodity-grade producers cannot satisfy. Segmentation strategy must align production assets with the regulatory intensity of target segments rather than pursuing volume indiscriminately.
Product Type:
REACH registration dossiers differentiate ethyleneamines by molecular weight and impurity profiles, with higher homologs facing stricter hazard classification thresholds under CLP.
- Ethylenediamine:The foundational diamine serves as the primary building block for chelating agents and pharmaceutical intermediates. Demand concentrates in China's eastern chemical corridor, where integrated ethylene oxide-amine complexes supply both domestic agrochemical formulators and export pharmaceutical manufacturers. EPA NESHAP compliance costs at US Gulf Coast facilities compress margins for non-integrated producers serving this volume segment.
- Triethylenetetramine:This higher molecular weight polyamine delivers superior crosslinking density for high-performance epoxy systems. Offshore wind turbine blade manufacturers in Germany and China's coastal provinces are expanding procurement of aerospace-qualified grades. The segment commands substantial price premiums over standard industrial specifications due to batch certification requirements.
- Diethylenetriamine:Intermediate molecular weight polyamine bridging ethylenediamine and triethylenetetramine applications.
- Aminopropyltriethoxysilane:Silane-functional amine coupling agent for adhesion promotion in coatings and composites.
Ethylenediamine handles the majority of throughput; triethylenetetramine is gaining share fastest on wind energy composite demand.
Application:
Cost tier differentiation separates specification-grade applications from commodity volume plays.
- Epoxy Resin:The dominant application consumes ethyleneamines as curing agents for coatings, adhesives, and structural composites. Formulators in Texas and Ohio manufacturing corridors are unbundling logistics contracts from product pricing, selecting suppliers through quarterly competitive tendering. Huntsman Corporation's captive consumption at downstream facilities anchors North American demand.
- Agrochemicals:Advanced fungicide and nematicide formulations require precise amine functionality for crop protection efficacy. CDSCO accelerated registration pathways in India are opening procurement relationships with domestic technical-grade manufacturers in Gujarat and Maharashtra.
- Gas Treatment:Higher molecular weight polyamines face displacement pressure from monoethanolamine reformulation in carbon capture retrofits.
- Fuel Additives:Specialized polyamine detergents and dispersants for gasoline and diesel performance enhancement.
Epoxy resin commands the largest volume allocation; agrochemicals is expanding most quickly on precision agriculture adoption.
End User:
Customer type maturity determines contract structure and technical service intensity.
- Pharmaceuticals:FDA and EMA active pharmaceutical ingredient qualification protocols extend 18-24 months, freezing capacity allocation until regulatory approval confirms. GMP-certified ethylenediamine for chelating agent synthesis commands substantial premiums over technical grades.
- Aerospace:AS9100 traceability and batch certification requirements for prepreg curing agents create substantial barriers to supplier qualification. German and Japanese specialty formulators are qualifying membrane-purified triethylenetetramine for primary structural applications.
- Automotive:Lightweight composite adoption in electric vehicle platforms is driving specification-grade epoxy consumption.
- Construction:Infrastructure coating and flooring applications represent the most price-sensitive demand tier.
Pharmaceuticals absorbs the highest service burden per ton; aerospace is climbing fastest on composite substitution trends.
Technology:
Process technology selection determines capital intensity and product distribution control.
- Chemical Synthesis:High-pressure amination of ethylene dichloride with ammonia remains the dominant production route. Experienced operations personnel for reactor management are retiring faster than training programs replace them at legacy facilities.
- Polymerization:Controlled molecular weight extension for higher polyamine homologs serving premium applications.
- Surface Treatment:Functionalization processes for adhesion promotion and substrate modification.
- Coating:Formulation integration technologies for end-use application performance.
Chemical synthesis underpins the bulk of installed capacity; polymerization is advancing fastest on specialty grade demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam-Antwerp pipeline corridor underwrites European ethyleneamines supply security, while China's Ningbo-Zhoushan port complex anchors Asia-Pacific export logistics. These infrastructure assets determine regional competitive access and cost structures across the forecast window.
United States
Gulf Coast epoxy resin compounders drive ethylenediamine consumption for wind turbine blade manufacturing and aerospace composites. EPA NESHAP hazardous air pollutant standards mandate scrubber upgrades at Texas and Louisiana production facilities. Houston Ship Channel chemical terminals concentrate import logistics for non-integrated formulators seeking spot supply flexibility.
Germany
Offshore wind installation programs in the North Sea accelerate triethylenetetramine procurement from specialty epoxy formulators. ECHA REACH registration dossiers filter supply to compliant integrated producers with dedicated regulatory affairs capabilities. Ludwigshafen and Marl chemical parks host backward-integrated amine complexes serving pharmaceutical and aerospace qualification protocols.
China
Jiangsu and Zhejiang province epoxy manufacturers consume captive ethylene oxide-amine output for domestic composite production and export markets. MEE wastewater discharge standards tighten total nitrogen limits, forcing caustic scrubber investments at Yangtze River Delta facilities. Ningbo-Zhoushan port infrastructure enables integrated producers to capture Southeast Asian export volume through chlorine-alkali integration advantages.
India
Gujarat and Maharashtra fungicide formulators expand technical-grade ethylenediamine procurement under CDSCO accelerated registration pathways. Central Pollution Control Board effluent norms affect merchant chlorine-dependent production economics at Gujarat chemical estates. Dahej and Mundra port zones concentrate import logistics for domestic agrochemical manufacturers seeking API-grade certification.
Saudi Arabia
Jubail Industrial City petrochemical complexes leverage ethylene feedstock integration for regional amine supply to construction and coatings markets. Saudi Standards, Metrology and Quality Organization (SASO) technical regulations govern product import specifications for downstream formulation. Yanbu port infrastructure on the Red Sea enables export positioning toward African and Mediterranean demand centers.
Ethyleneamines Market Vendor Landscape
Listed leaders compete with private specialists across capital access and regulatory compliance capabilities. The vendor base stratifies into three tiers: integrated petrochemical majors with captive ethylene oxide supply, regional specialists serving qualification-intensive pharmaceutical and aerospace segments, and merchant producers dependent on spot ethylene dichloride procurement. Strategic moves concentrate on backward integration into ethylene oxide production and membrane purification technology licensing to compress capital requirements for specialty grade expansion.
Among European integrated producers, Nouryon anchors supply security through Rotterdam pipeline infrastructure. Huntsman Corporation exemplifies North American captive consumption models at downstream epoxy resin facilities. Evonik Industries occupies a position within the specialty polyamine tier, serving fuel additive and gas treatment qualification protocols. These three represent distinct competitive archetypes: infrastructure-secured supply, vertical demand integration, and molecular-weight specialization.
| Leading Market Players |
|---|
| Nouryon |
| Delamine BV |
| Huntsman Corporation |
| Evonik Industries |
| Arabian Amines Company |
| Dow |
| Tosoh Corporation |
| Akzo Nobel N.V. |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
REACH registration dossiers and FDA active pharmaceutical ingredient qualification protocols simultaneously gate supply access and stratify price tiers across ethyleneamines procurement. Buyers without GMP certification pathways face exclusion from pharmaceutical-grade premiums, while compliant integrated producers capture margin protection through regulatory moats that commodity merchants cannot replicate.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical GMP-certified ethylenediamine from technical-grade industrial specifications and spot-market commodity volumes. Price differentiation rests on certification grade and volume scale, with aerospace-qualified triethylenetetramine commanding substantial premiums over standard epoxy curing agents. Cost compression in the economy tier is intensifying because merchant chlorine-dependent producers absorb ethylene dichloride feedstock volatility without captive integration buffers. Construction coating formulators exhibit highest price sensitivity, while pharmaceutical manufacturers prioritize supply security over unit economics.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes and Houston Ship Channel congestion elevate inbound logistics costs for non-integrated North American formulators. Supply concentrates in China, Germany, and the United States, with Jiangsu province complexes and Ludwigshafen chemical parks anchoring regional output. Raw material dependencies center on ethylene dichloride, ethylene oxide, and anhydrous ammonia feedstocks. Single-source vulnerability from European natural gas pricing swings threatens margin stability at chlor-alkali integrated facilities. Distribution runs through specialty chemical distributors in Texas and Ohio corridors, with quarterly competitive tendering replacing annual volume contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity is opening as precision agriculture adoption and offshore wind composite demand splinter procurement specifications beyond commodity-grade standardization. Specialty formulators now require batch-certified higher homologs that integrated majors serve reluctantly, creating niche entry points.
For Market Incumbents: Secure backward integration into ethylene oxide production to buffer ethylene dichloride feedstock volatility and sustain cost positions against Yangtze River Delta exporters. Lock pharmaceutical GMP certification capacity ahead of CDSCO and EMA qualification protocol expansions, as 18-24 month approval timelines freeze competitor allocation decisions. Defend against membrane purification technology licensing by acquiring pilot-scale separations expertise before capital requirements compress for new entrants. For New Entrants and Emerging Players: Differentiate on membrane-based triethylenetetramine purification for aerospace prepreg applications, where German and Japanese formulators are actively qualifying alternative suppliers. Target India's Gujarat and Maharashtra agrochemical corridors under CDSCO accelerated registration pathways for technical-grade ethylenediamine, where domestic fungicide manufacturers seek procurement relationships outside Chinese supply concentration. Pursue toll manufacturing arrangements with existing ethylene oxide pipeline infrastructure to bypass chlor-alkali capital intensity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across membrane purification sub-segments, enabling asset-light entry into specialty grade production previously requiring integrated complex economics. Long-term viability favors producers with verified low-carbon ethylene oxide supply chains positioned for EU Green Deal carbon border adjustment protection. Acquisition target archetype: regional specialists with pharmaceutical GMP certification and captive aerospace customer relationships. Signal to watch: membrane technology licensing announcements from German pilot installations indicating technology transfer acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Nouryon's Rotterdam pipeline infrastructure demonstrates cost-competitive supply security against merchant feedstock volatility. |
| Membrane Purification Technology Licensing | Thin-film composite separations reduce energy consumption by half at pilot installations, compressing capital barriers for specialty grade entrants. |
| Pharmaceutical GMP Certification Investment | FDA and EMA qualification protocols extend 18-24 months, freezing capacity allocation until regulatory approval confirms. |
| Long-term Supply Agreement with Wind Turbine Blade Manufacturers | Offshore wind installation programs in the North Sea and China's coastal provinces anchor triethylenetetramine offtake visibility. |
| Joint Venture in Eastern China Chemical Corridor | Jiangsu and Zhejiang province complexes capture export volume through captive chlorine-alkali integration and Ningbo-Zhoushan port logistics. |
Methodological Framework
Cross-validation between plant manager interviews at integrated amine complexes and customs/trade data anchors the qualitative findings on supply concentration and procurement pattern shifts. Primary fieldwork engaged procurement leads at downstream epoxy resin compounders, distribution channel partners in Texas and Ohio corridors, and technical R&D directors at specialty formulators. Secondary validation drew from SEC 10-K filings, Cefic industry reports, and EPA NESHAP compliance disclosures. Bottom-up capacity modeling and top-down demand segmentation triangulate volume estimates across the projection horizon.
Sensitivity analysis tested forecast robustness against ethylene dichloride feedstock volatility, European natural gas pricing scenarios, and membrane technology adoption curves. The analytical framework segments by grade tier, end-use industry, and regional production hub, with CAGRs derived from regression against historical capacity utilization and forward-looking qualification pipeline data. Forecast inputs include offshore wind installation program announcements, CDSCO registration pathway velocity, and MEE wastewater discharge standard implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained chlor-alkali energy economics and stable regulatory compliance cost trajectories would require recalibration. Forecasts reflect assumptions on membrane technology scale-up rates and pharmaceutical qualification timeline stability. Practitioners should keep alternative scenarios live as carbon border adjustment mechanisms and green chemistry initiatives evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Sodium Hydrogen Sulphite Market
Bulk Chemicals
Mercaptan Market
Bulk Chemicals
Bulk Molding Compounds Market
Bulk Chemicals
Hydrochloric Acid Electrolysis Market
Bulk Chemicals
Magnesium Nitrate Hexahydrate Market
Bulk Chemicals
Benzyl Acetate Market
Bulk Chemicals
Zinc Carbonate Market
Bulk Chemicals
Sulfamic Acid Market
Bulk Chemicals
Hydrated Lime Market
Bulk Chemicals
United States Starch Derivatives Market
Bulk Chemicals
Sodium Bicarbonate Market
Bulk Chemicals
Global Cyclohexylbenzene Market
Bulk Chemicals
Di-Isobutylene Market
Bulk Chemicals
Global Silica Flour Market
Bulk Chemicals
2-Nitrothiophene Market
Bulk Chemicals
Cyclohexylamine Market