
 Gluconic Acid Market | 2026-2036
Gluconic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Gluconic Acid Market Analysis
China is reconfiguring gluconic acid supply dynamics through concentrated fermentation capacity in Shandong province. Evonik Industries AG leverages biosynthetic process expertise to sustain premium-grade output for pharmaceutical applications. Jungbunzlauer Suisse AG anchors European supply with certified production for food and personal care segments. Shandong Kaison Biochemical Co., Ltd. competes on volume, dominating regional feedstock integration for sodium gluconate.
Gluconic acid is a C6 carboxylic acid produced via aerobic fermentation of glucose with Aspergillus niger, typically supplied as aqueous solution or crystalline salt with purity grades spanning technical to pharmaceutical specification. Its primary industrial purpose centers on chelation, pH buffering, and biodegradability across construction, food preservation, and pharmaceutical formulation. Sodium gluconate leads product type revenue due to concrete admixture demand, while glucono delta-lactone captures margin concentration in artisanal food applications. Construction application volumes outpace other segments, though pharmaceutical-grade material commands superior unit economics through certification overhead.
EPA guidelines govern industrial discharge thresholds for fermentation-derived organic acids in US manufacturing. REACH registration requirements in Europe restrict market access for non-compliant Asian exporters. FDA food additive regulations shape purity specifications for glucono delta-lactone in acidulant applications. Stakeholders must monitor regulatory divergence between jurisdictions when allocating certification investments across product grades.
Market Dynamics
Fermentation capacity clustering in Shandong province concentrates supply-side leverage among Chinese biochemical producers, while REACH compliance costs in Europe stratify market access by purity grade certification overhead.
Growth Catalysts
- Concrete admixture demand:Construction firms across Asia-Pacific specify sodium gluconate for retardation in large-scale infrastructure pours, sustaining volume pull through project pipelines.
- REACH registration tiering:European pharmaceutical-grade certification creates margin premiums for compliant producers serving EMA-regulated formulation markets.
- Fermentation yield improvements:Strain optimization in Aspergillus niger biocatalysts reduces glucose input intensity per ton of acid output.
Market Restraints
- Feedstock glucose volatility:Corn starch and dextrose pricing fluctuates with agricultural commodity cycles, compressing margins for non-integrated fermenters.
- Shandong supply concentration:Over 60 percent of global fermentation capacity sits within one Chinese province, exposing buyers to localized disruption risks.
- Organic acid substitution:Citric acid and EDTA compete for chelation applications in industrial cleaning and metal finishing end-uses.
Strategic Opportunities
- Pharmaceutical-grade white space:USP and EP certification gaps exist among second-tier Asian exporters targeting FDA-regulated markets.
- Biodegradable chelation mandate expansion:EU Green Deal procurement guidelines favor gluconate-based formulations over phosphonate alternatives in institutional cleaning contracts.
- Precision fermentation convergence:CRISPR-edited Aspergillus strains combined with continuous bioprocessing enable pharmaceutical-grade titer improvements.
Industry Challenges
- Pharmaceutical certification timelines:EMA and FDA master file submissions require 18-24 month validation cycles for new production facilities.
- Downstream purification capex:Crystallization and ion-exchange systems for USP-grade material demand specialized stainless-steel infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gluconic Acid Market |
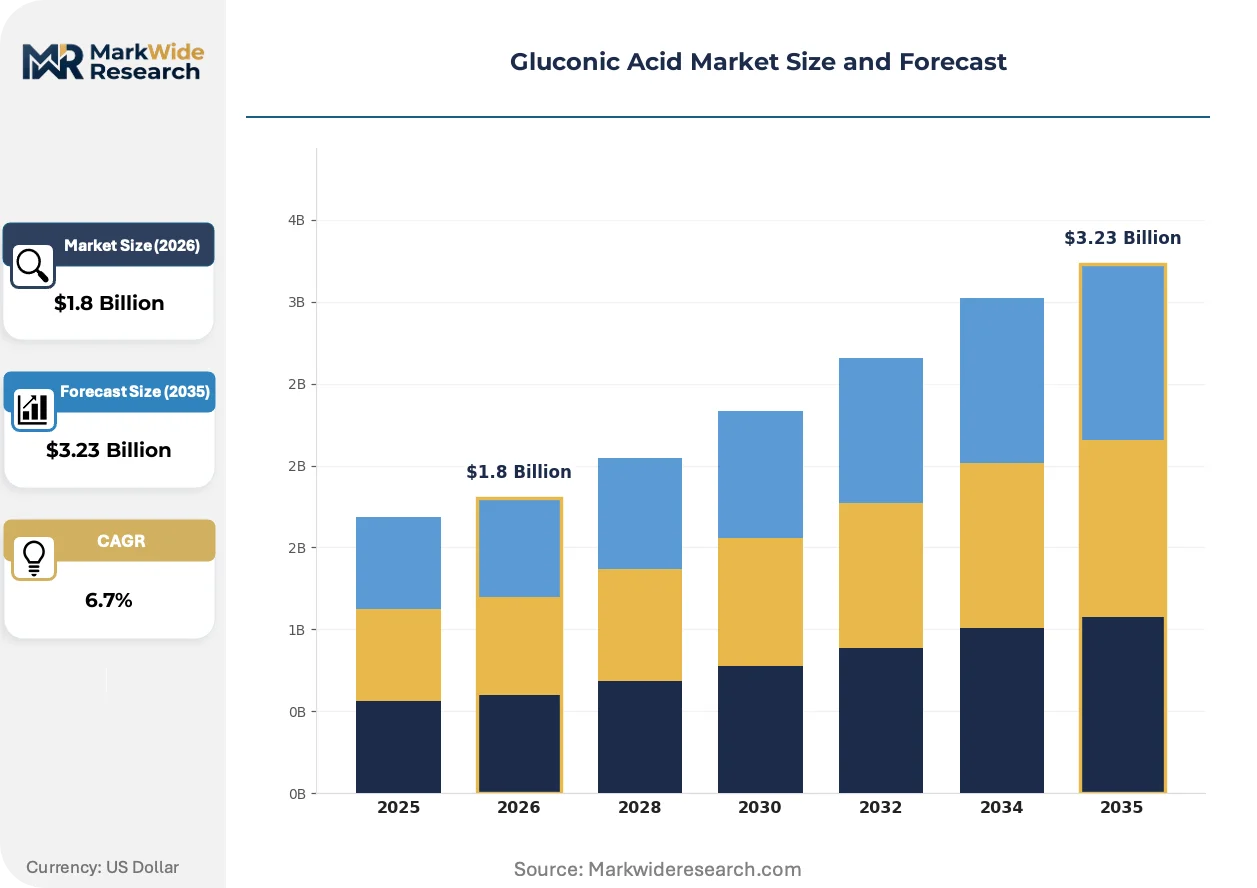
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gluconic Acid, Sodium Gluconate, Calcium Gluconate, Glucono Delta-Lactone Application: Food Additive, Pharmaceutical, Construction, Personal Care End User: Food Industry, Healthcare Sector, Construction Firms, Cosmetic Manufacturers Form: Liquid, Powder, Granular, Crystals |
| Companies Covered | Evonik Industries AG, Fuso Chemical Co., Ltd., Jungbunzlauer Suisse AG, Ruibang Laboratories, Shandong Fuyang Bio-Tech CO. LTD., Roquette Frères, Merck KGaA, Shandong Kaison Biochemical Co., Ltd., PMP Fermentation Products, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gluconic Acid Market Emerging Trajectories
Process intensification and regulatory tiering are bifurcating competitive strategy between volume-commodity and certified-specialty positioning. Digital integration now penetrates fermentation control and supply chain traceability simultaneously.
Continuous bioprocessing with real-time metabolite monitoring is digitizing fermentation control architecture. Mid-scale Chinese producers deploy sensor arrays for dissolved oxygen and pH optimization, reducing batch-to-batch variability. This digitizing of process control compresses quality deviation costs and accelerates pharmaceutical-grade qualification timelines.
REACH substance evaluation under SVHC candidate listing is tightening impurity thresholds for gluconic acid derivatives in consumer applications. ECHA dossier updates now require comprehensive ecotoxicology data for salts and lactone forms. European food and personal care formulators are consolidating supplier bases to pre-registered, full-dossier holders.
Direct procurement from fermentation sites is displacing layered distribution for sodium gluconate in concrete admixture markets. Large construction chemical blenders in Germany and the United States negotiate offtake agreements with Shandong producers, bypassing traditional chemical distributors. This channel compression is most visible in project-scale infrastructure contracts where volume certainty outweighs service bundling.
Gluconic Acid Market Segmentation
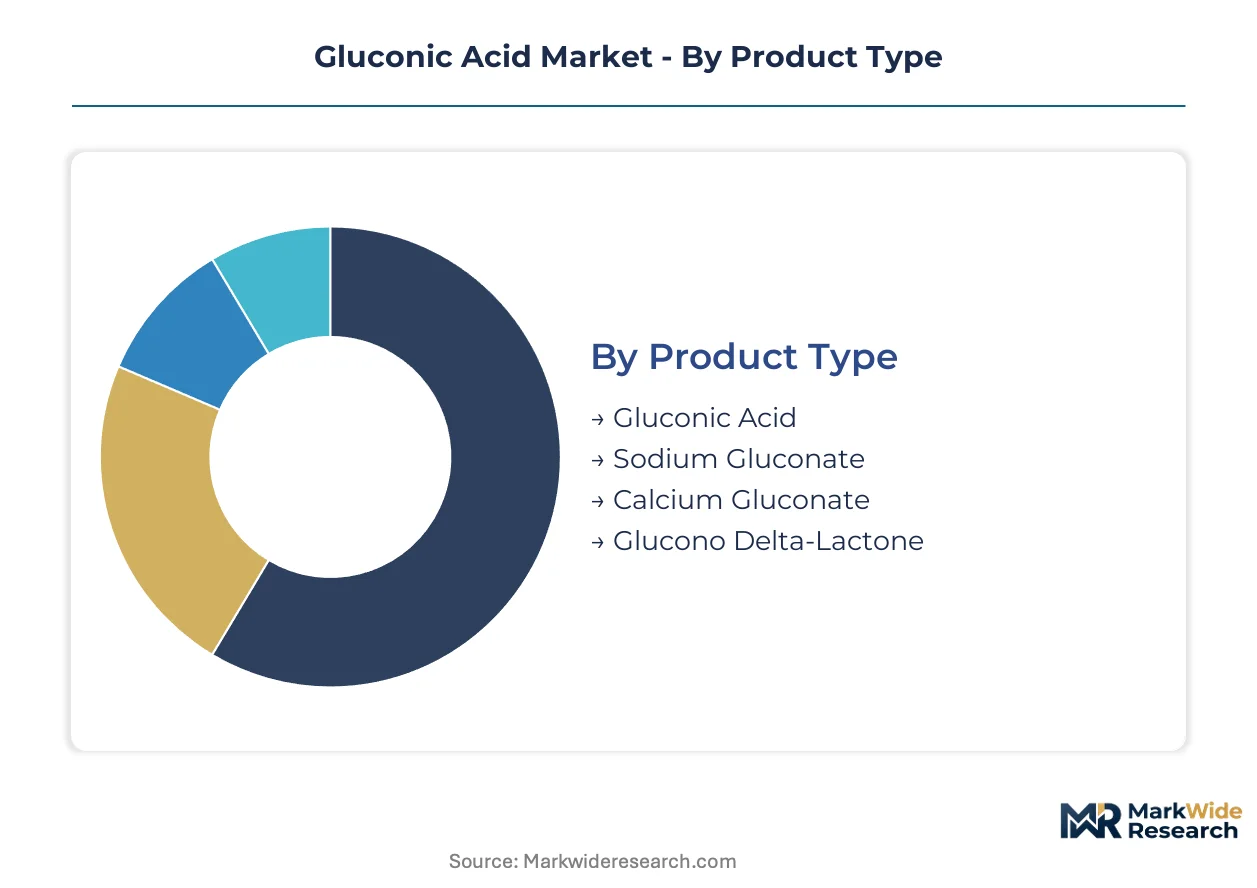
Gluconic acid derivatives serve distinct technical specifications across construction chelation, pharmaceutical buffering, and food acidulation. Segmentation by product type and application reveals divergent margin structures, certification requirements, and supply chain configurations that shape procurement strategy.
Product Type:
After-sales service intensity varies sharply across product types, with pharmaceutical-grade materials demanding batch traceability and technical support that commodity sodium gluconate does not require.
- Sodium Gluconate:The sodium salt of gluconic acid functions as a concrete retarder and industrial chelating agent with technical-grade purity sufficing for most construction applications. Demand concentrates in China's Shandong province, where fermentation capacity clusters serve Asia-Pacific infrastructure projects facing tight pour schedules.
- Glucono Delta-Lactone:This cyclic ester hydrolyzes slowly in aqueous solution, providing controlled acid release for food applications. Artisanal cheese production and tofu coagulation in Japan and South Korea drive premium pricing for food-grade certification.
- Gluconic Acid:The free acid form supplies pH buffering and mild chelation for industrial cleaning formulations and metal surface treatment baths.
- Calcium Gluconate:Pharmaceutical-grade calcium salt serves intravenous mineral supplementation and oral nutraceutical applications requiring USP or EP certification.
By volume, sodium gluconate leads. By growth pace, glucono delta-lactone is ahead.
Application:
Cost tier stratification separates construction commodity volumes from pharmaceutical certification premiums that absorb specialized purification capex.
- Construction:Concrete admixture specifications for retardation and workability extension consume sodium gluconate in bulk quantities. Large-scale infrastructure pours across Germany, the United States, and China specify gluconate-based retarders for mass concrete placements where thermal cracking control matters.
- Pharmaceutical:Parenteral formulations, dialysis solutions, and mineral supplements demand USP-grade material with impurity profiles validated through FDA master file submissions. EMA-regulated markets in Europe enforce REACH dossier completeness for excipient qualification.
- Food Additive:Glucono delta-lactone serves as a slow-release acidulant in processed meats, dairy, and baked goods where pH control timing affects texture development.
- Personal Care:Mild chelation and pH adjustment in cosmetic formulations leverage gluconic acid derivatives as EDTA alternatives under EU Green Deal procurement preferences.
Construction commands absolute tonnage. Pharmaceutical applications capture the steepest expansion trajectory through biosimilar and generic formulation growth.
End User:
Customer type determines procurement pattern, with construction firms negotiating direct offtake agreements while healthcare sector buyers consolidate around certified suppliers.
- Construction Firms:Project-scale concrete suppliers in Germany and the United States bypass distributors to contract directly with Shandong fermentation sites, trading service bundling for volume certainty and price transparency.
- Healthcare Sector:Hospital systems, dialysis clinics, and pharmaceutical manufacturers require validated supply chains with batch documentation and pharmacovigilance support that commodity channels cannot provide.
- Food Industry:Processed meat and dairy processors specify glucono delta-lactone for clean-label acidulation, with Japanese and South Korean manufacturers leading formulation innovation.
- Cosmetic Manufacturers:European personal care formulators consolidate supplier bases to REACH-registered, full-dossier holders as ECHA tightens impurity thresholds under SVHC evaluation.
Construction firms purchase the largest single volumes. Healthcare sector procurement is climbing the fastest through parenteral nutrition and dialysis market expansion.
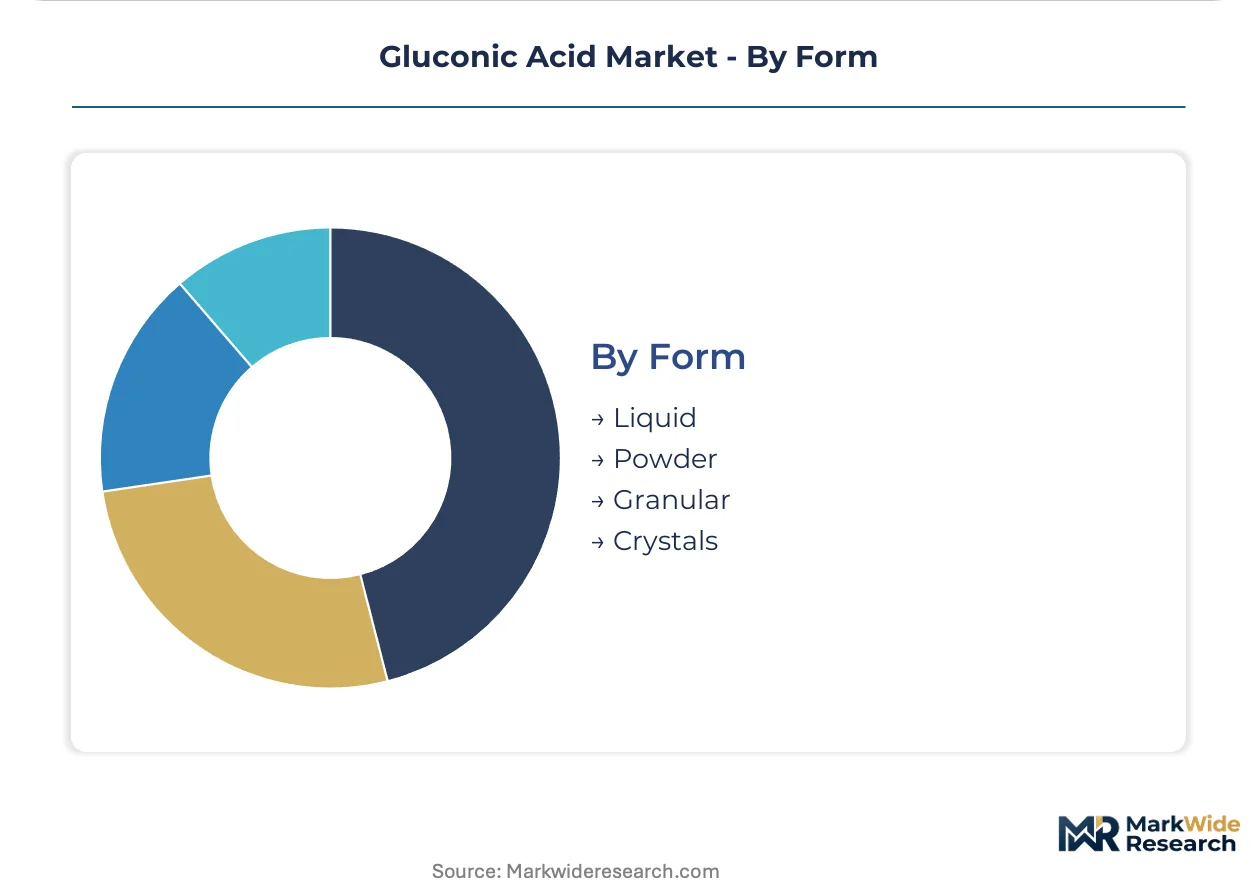
Form:
Supply concentration in aqueous solution production shapes liquid form availability, while powder and crystalline grades demand downstream processing investment that stratifies producer capabilities.
- Liquid:Aqueous solutions dominate industrial applications where concentration and handling efficiency outweigh shipping cost considerations. Fermentation sites in Shandong province ship bulk liquid to concrete admixture blenders across Asia-Pacific.
- Powder:Spray-dried material serves food and pharmaceutical applications requiring dry blending compatibility and extended shelf stability.
- Crystals:High-purity crystalline grades meet USP and EP specifications for injectable formulations, with specialized stainless-steel crystallization infrastructure limiting qualified suppliers.
- Granular:Intermediate particle size distribution supports controlled dissolution in tablet formulations and industrial cleaning tablets.
Liquid form leads by volume through fermentation site proximity to construction demand. Crystalline grades are gaining share fastest through pharmaceutical certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation capacity clusters overwhelmingly in Shandong province, while REACH compliance costs and pharmaceutical-grade certification requirements stratify market access across developed economies. Demand patterns diverge sharply between bulk construction applications and regulated healthcare formulations.
China
Construction firms specify sodium gluconate for concrete retardation in infrastructure megaprojects spanning high-speed rail and urban development. SAMR enforces GB standards for food-grade material purity in domestic supply chains. Shandong province hosts over sixty percent of global fermentation capacity, with biochemical producers integrating corn starch feedstock processing adjacent to fermentation tanks.
Germany
Concrete admixture blenders negotiate direct offtake agreements with Asian fermentation sites, bypassing traditional chemical distributors for project-scale volume certainty. ECHA administers REACH registration requirements that restrict market access for non-compliant exporters. The Rhine-Ruhr industrial corridor anchors European distribution infrastructure for construction chemical applications.
United States
Pharmaceutical manufacturers demand USP-grade material with validated impurity profiles for parenteral formulations and dialysis solutions. FDA master file submissions govern excipient qualification timelines for new production facilities. The Gulf Coast petrochemical corridor processes imported aqueous solutions into downstream admixture formulations for domestic construction markets.
Japan
Artisanal food processors specify glucono delta-lactone for tofu coagulation and fermented dairy applications where controlled acid release affects texture development. METI oversees JIS standards compliance for food additive specifications. The Kansai region around Osaka maintains specialized distribution networks for premium-grade lactone material serving traditional food manufacturers.
Switzerland
Personal care formulators consolidate supplier bases around REACH-registered, full-dossier holders as ECHA tightens SVHC impurity thresholds. Swissmedic enforces pharmaceutical-grade certification requirements for mineral supplement applications. Jungbunzlauer Suisse AG anchors European supply with certified production capacity serving EMA-regulated formulation markets.
Gluconic Acid Market Vendor Landscape
Integrated biochemical conglomerates and specialized fermentation houses split the market between volume-commodity and certified-specialty positioning. Three archetypes dominate: Shandong-based producers leveraging feedstock integration for sodium gluconate cost leadership, European specialists commanding pharmaceutical-grade premiums through REACH dossier completeness, and Japanese precision fermenters capturing artisanal food application margins. Capacity expansion and direct procurement channel compression represent the dominant competitive moves, with construction chemical blenders negotiating offtake agreements that displace layered distribution.
Among German chemical conglomerates, Evonik Industries AG occupies a position exemplifying biosynthetic process expertise for premium-grade pharmaceutical applications. Swiss fermentation specialists anchor European supply security, with Jungbunzlauer Suisse AG representing the certified-production archetype for food and personal care segments. Chinese biochemical producers compete on volume and feedstock integration, with Shandong Kaison Biochemical Co., Ltd. sitting within the regional-capacity cluster serving Asia-Pacific infrastructure demand.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Fuso Chemical Co., Ltd. |
| Jungbunzlauer Suisse AG |
| Ruibang Laboratories |
| Shandong Fuyang Bio-Tech CO. LTD. |
| Roquette Frères |
| Merck KGaA |
| Shandong Kaison Biochemical Co., Ltd. |
| PMP Fermentation Products, Inc. |
| Others |
Supply Flow & Price Mechanics
Shandong province's fermentation capacity clustering concentrates supply-side leverage among Chinese biochemical producers, enabling direct offtake negotiations that compress distributor margins and transfer pricing power to integrated manufacturers serving construction chemical blenders.
Pricing Analysis
REACH registration dictates the pricing tier structure across European pharmaceutical-grade material, separating full-dossier holders from technical-grade commodity suppliers. Three-tier pricing stratifies across USP-certified, food-grade, and technical-grade levels, with certification overhead and batch traceability driving premium capture. Cost compression in technical-grade sodium gluconate is intensifying because corn starch feedstock volatility squeezes non-integrated fermenters. Construction chemical blenders exhibit the highest price sensitivity, while pharmaceutical formulators absorb certification premiums for validated supply security.
Supply Chain Analysis
Export-control restrictions on precision fermentation technology limit Western bioprocessing equipment flows into Chinese production facilities, constraining capacity expansion timelines for pharmaceutical-grade output. Supply concentrates in China, Germany, and Switzerland, with raw material dependencies on corn starch, dextrose, and specialized ion-exchange resins. Single-source vulnerability runs through Shandong's dominance of global fermentation capacity. Distribution runs through direct procurement contracts displacing traditional chemical distributors for sodium gluconate volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward large construction chemical blenders consolidating procurement through direct offtake agreements, fragmenting traditional distributor influence across project-scale infrastructure contracts.
For Market Incumbents: Entrench certification advantages by deepening FDA master file portfolios and EMA dossier completeness before REACH substance evaluation tightens further. Capacity addition in Switzerland or Germany anchors European supply security against Shandong disruption risks. Citric acid and EDTA substitution threats in industrial cleaning applications demand R&D investment in biodegradable chelation performance to defend formulation share. For New Entrants and Emerging Players: Establish a beachhead in pharmaceutical-grade calcium gluconate where USP certification gaps exist among second-tier Asian exporters. The most penetrable segment is parenteral mineral supplementation for dialysis clinics and hospital systems requiring validated batch documentation. A go-to-market angle emphasizing pharmacovigilance support and master file submission assistance differentiates against commodity channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision fermentation specialists with CRISPR-edited strain libraries and continuous bioprocessing capabilities. Long-term viability hinges on biosimilar and generic formulation growth expanding pharmaceutical-grade demand. Acquisition targets should display REACH dossier completeness and stainless-steel crystallization infrastructure. The signal to watch is ECHA SVHC candidate listing decisions tightening impurity thresholds for gluconate derivatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Starch Processing | Shandong producers captive supply of fermentation feedstock buffers agricultural commodity cycles. |
| Continuous Bioprocessing Scale-Up | Real-time metabolite monitoring reduces batch-to-batch variability for pharmaceutical qualification. |
| FDA Master File Submission | Validated impurity profiles unlock parenteral formulation markets with superior unit economics. |
| Direct Procurement Channel Development | Bypassing distributors transfers margin to construction chemical blenders negotiating volume certainty. |
| REACH Full-Dossier Registration | ECHA compliance secures European market access as SVHC evaluation tightens thresholds. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with plant managers at fermentation facilities, procurement leads at concrete admixture blenders, pharmaceutical regulatory affairs directors, and EMA excipient qualification specialists; and secondary validation through customs trade data, Cefic chemical industry reports, FDA master file databases, and ECHA registration dossiers. Bottom-up capacity modeling triangulated against top-down demand segmentation across construction, pharmaceutical, and food additive applications.
Forecast inputs considered grade tier stratification, end-use industry demand patterns, regional production hub concentration, and certification requirement evolution across the projection horizon. CAGRs derived from segment-level volume trajectories weighted by purity-grade pricing differentials. Strain optimization timelines and REACH registration completion rates shaped pharmaceutical-grade supply expansion assumptions.
Sensitivities concentrate around corn starch price volatility, Shandong capacity disruption scenarios, and ECHA SVHC listing decisions affecting formulation qualification. Forecasts reflect documented assumptions on fermentation yield improvements and regulatory compliance timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Carbonate Market
Bulk Chemicals
North America Acrylamide Monomer Market
Bulk Chemicals
Monoethylene Glycol (MEG) Market
Bulk Chemicals
Aluminum Sulfide Market
Bulk Chemicals
Global Linear Alkyl Benzene Market
Bulk Chemicals
Global Hydroiodic Acid (Hydriodic Acid) Market
Bulk Chemicals
Cyclohexane Market
Bulk Chemicals
Castor Wax Market
Bulk Chemicals
Carbamide Market
Bulk Chemicals
Sodium Hydrosulfide Market
Bulk Chemicals
India Lime Market
Bulk Chemicals
China Lime Market
Bulk Chemicals
Methyl Chloroform Market
Bulk Chemicals
Asia-Pacific Ammonia Market
Bulk Chemicals
North America Copper Sulphate Market
Bulk Chemicals
Ammonium Molybdate Market