
 Lutein Market | 2026-2036
Lutein Market Size, Share, and Industry Trends Forecast 2026-2036
Lutein Market Intelligence
Expertise in agronomic practices for high-carotenoid marigold cultivation is reorganizing the raw material supply chain for lutein. Kemin Industries, Inc. leverages its vertically integrated model from seed to finished ingredient. OmniActive Health Technologies specializes in clinically validated, branded lutein ingredients for the nutraceutical space. BASF SE competes through its broad portfolio of human nutrition ingredients and extensive global distribution network.
Lutein is a naturally occurring xanthophyll carotenoid, an antioxidant pigment synthesized by plants. It is primarily extracted from marigold flowers (Tagetes erecta) and is known for its concentration in the macula of the human eye, where it filters blue light. The dietary supplements application constitutes the largest end-use category, driven by consumer focus on ocular health. Within product types, powder and oil extract forms dominate due to their versatility in formulations ranging from soft gel capsules to functional foods.
Market access is governed by food additive and supplement regulations, with bodies like the US FDA, the European Food Safety Authority (EFSA), and the Food Safety and Standards Authority of India (FSSAI) setting purity standards and permissible health claims. These frameworks directly influence ingredient sourcing, manufacturing practices, and the types of marketing claims producers can make. Future competitive advantage will hinge on a manufacturer's ability to substantiate health claims with robust clinical data and demonstrate supply chain traceability.
Market Dynamics
The lutein market's structure is reorganizing around control of the raw material supply chain, where agronomic expertise in cultivating high-carotenoid marigold flowers dictates competitive advantage and pricing power for finished ingredients.
Growth Catalysts
- FDA GRAS Status:The US FDA's Generally Recognized as Safe (GRAS) designation for certain lutein esters has expanded its application, providing a clear regulatory pathway for use in a variety of functional foods and beverages.
- Preventative Healthcare in China:An aging population and rising disposable incomes in China are fueling a focus on preventative health, specifically driving demand for dietary supplements aimed at mitigating age-related eye conditions.
- Dietary Supplement Focus:The mainstreaming of ocular health as a key consumer wellness concern sustains strong demand from the dietary supplements sector, which remains the largest end-use application for lutein ingredients.
Market Restraints
- Agricultural Dependency:The supply chain is highly dependent on the marigold flower harvest, making it vulnerable to climate change, crop diseases, and agricultural price volatility in key cultivation regions like India and China.
- Extraction Complexity:The solvent extraction and purification process for lutein is capital-intensive and requires specialized technical expertise, creating significant barriers to entry for new, smaller-scale manufacturers.
- Substitution from Zeaxanthin:While often used synergistically, zeaxanthin can compete with lutein for certain eye health formulations, particularly as consumer awareness and specific clinical research on zeaxanthin grows.
Strategic Opportunities
- Functional Food Expansion:There is significant opportunity to incorporate lutein into a broader range of functional foods beyond supplements, such as yogurts, snack bars, and fortified dairy products, targeting mainstream consumers.
- Underpenetrated Geographies:Markets in Southeast Asia and Latin America, particularly Brazil, represent new growth frontiers where awareness of eye health supplements is rising but market penetration remains relatively low.
- Bioavailability Enhancement:Developing novel delivery systems like nano-emulsions or microencapsulated powders can improve lutein's bioavailability, justifying premium pricing and creating product differentiation.
Industry Challenges
- Supply Chain Traceability:Meeting increasing consumer and regulatory demands for full traceability from seed to final extract, including non-GMO and pesticide-free certifications, adds complexity and cost to the supply chain.
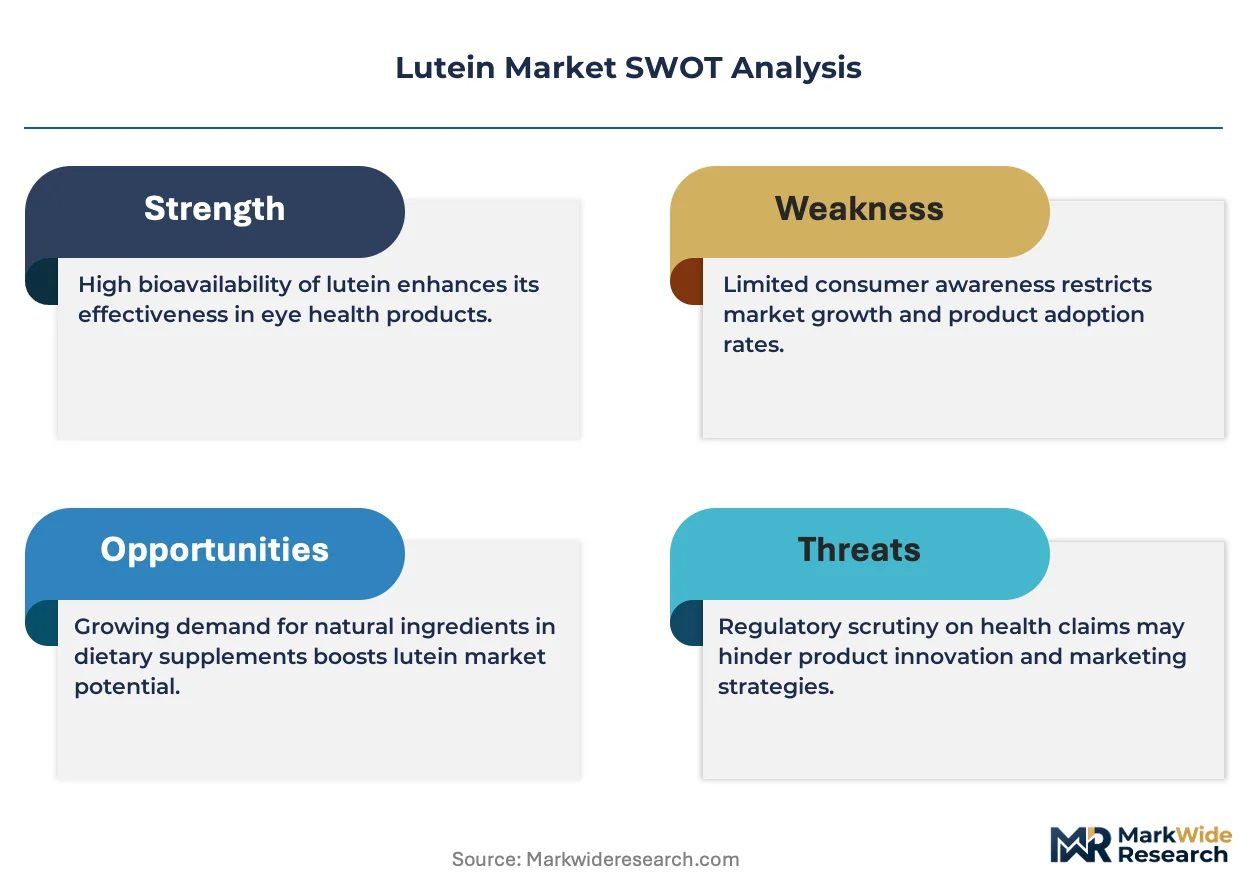
- Health Claim Substantiation:The high cost and long duration of conducting robust human clinical trials required to substantiate new or specific health claims under frameworks like EFSA's limits marketing innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lutein Market |
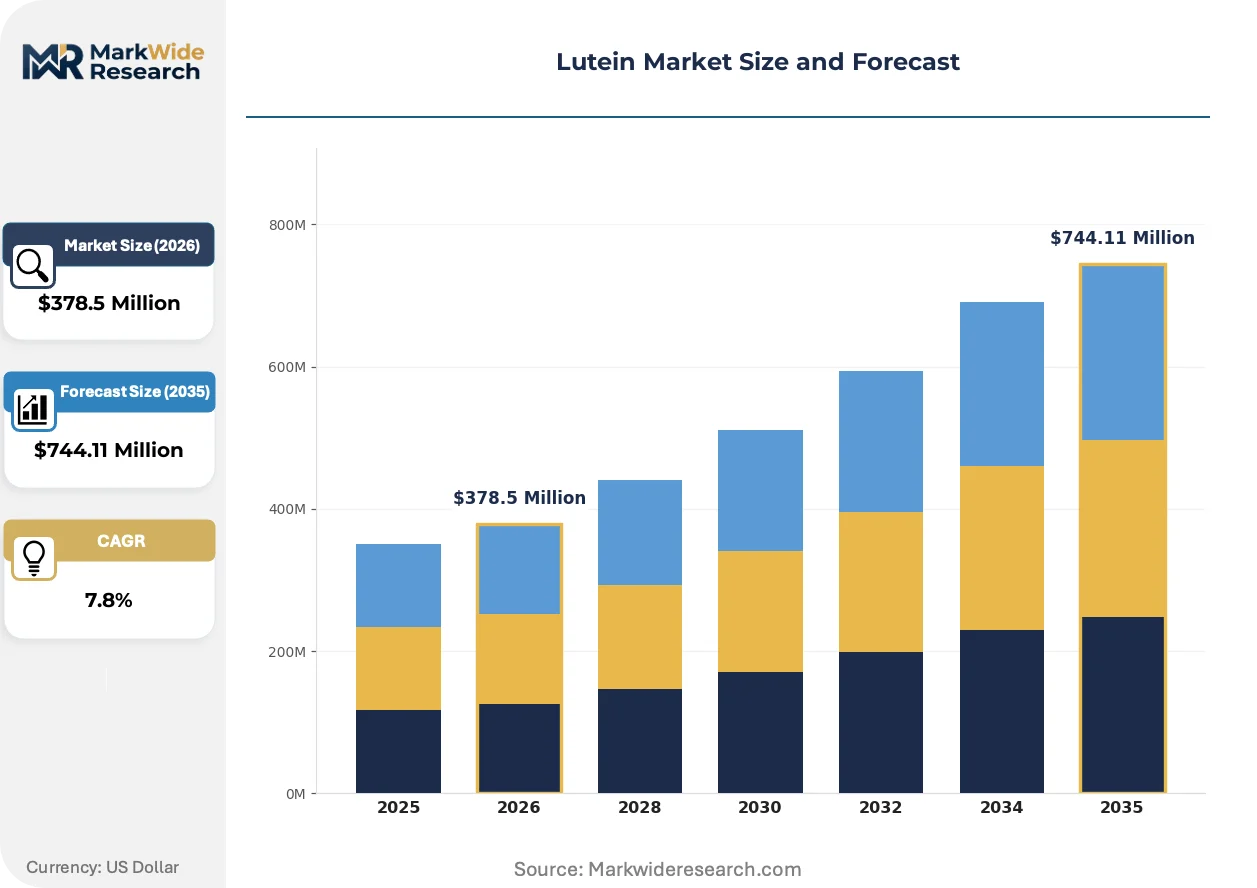
| Market Size in 2026 | $378.5 Million |
| Market Size in 2035 | $744.11 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Oil Extract, Esterified, Granules Application: Dietary Supplements, Functional Food, Pharmaceuticals, Cosmetics, Animal Nutrition End User: Manufacturers, Nutraceutical Companies, Food Processors, Pharmaceutical Firms Formulation: Soft Gel Capsules, Tablets, Liquids, Chewables, Powder Mixes |
| Companies Covered | Allied Biotech Corporation, Koninklijke DSM N.V., BASF SE, Divi’s Laboratories, India Glycols Limited, Kemin Industries, Inc., Chr. Hansen Holding A/S, Synthite Industries Ltd., OmniActive Health Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lutein Market Strategic Shifts & Innovations
A fundamental transition from a bulk commodity to a value-added, branded ingredient is defining the lutein market. This evolution is driven by demands for clinical substantiation and supply chain transparency, impacting formulation and marketing strategies across the board.
Microencapsulation and nano-emulsion technologies are advanced formulation methods that protect lutein from degradation and improve its water dispersibility. Functional food and beverage manufacturers are adopting these techniques to incorporate lutein into products like clear drinks and gummies. This technology is miniaturizing the ingredient's delivery system at a particle level, overcoming previous formulation barriers tied to lutein's oil-soluble nature.
Heightened scrutiny from regulatory bodies like the European Food Safety Authority (EFSA) on health claims is becoming a standard. This pressure compels manufacturers to move beyond simple purity specifications and invest heavily in human clinical trials to validate specific benefits. The dietary supplements segment is most affected, leading to a market bifurcation between generic lutein and premium, clinically-proven branded ingredients.
A significant behavioral shift is underway as finished product manufacturers prioritize ingredient traceability and scientific backing over pure cost. The practice of sourcing generic lutein from traders is being displaced by direct partnerships with specialized suppliers offering branded, study-supported ingredients. This trend is most prominent in the North American and European nutraceutical sectors, where consumer trust is a primary brand asset.
Lutein Market Segmentation
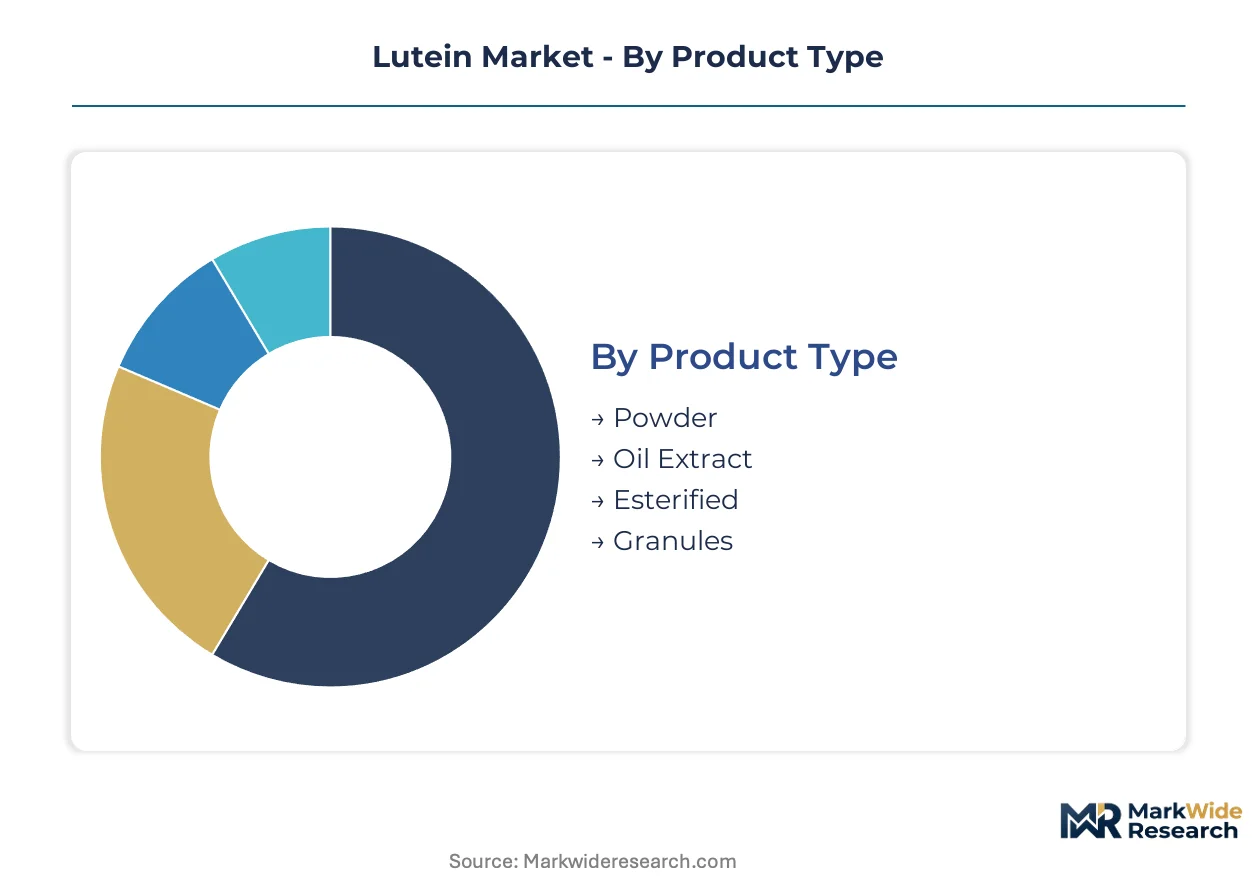
The lutein market is dynamically segmented by product type, application, end user, and formulation, providing a granular view of demand patterns. Understanding these distinctions is critical for manufacturers aiming to align their production capabilities with specific market needs and regulatory requirements. Each segment reflects unique processing demands and consumer preferences.
Product Type:
The channels through which lutein ingredients are distributed often depend on their physical form, influencing their integration into various finished products.
- Powder:This form consists of fine particles of lutein, often encapsulated or spray-dried, offering excellent stability and ease of handling in dry mix formulations. Demand concentrates in the dietary supplements sector, where its versatility allows for incorporation into capsules, tablets, and functional food powders.
- Oil Extract:A concentrated liquid form of lutein, typically dissolved in a carrier oil, providing high bioavailability and suitability for soft gel capsules. This extract form finds strong demand in ocular health supplements, driven by consumer preference for easily digestible formats and its natural oil-soluble nature.
- Esterified:Lutein esters are more stable than free lutein and are often used in food fortification due to their improved shelf life and heat stability. These esters are gaining traction in functional food applications, especially in regions with stringent food preservation standards.
- Granules:Granulated lutein offers superior flowability and reduced dust, making it ideal for direct compression in tablet manufacturing and certain animal nutrition applications.
Powder dominates the installed base of ingredient forms. Oil Extract is where expansion concentrates for high-value applications.
Application:
The intended use of lutein ingredients dictates specific purity standards and formulation requirements, influencing the market's value chain.
- Dietary Supplements:This category encompasses a broad range of products aimed at enhancing health, with lutein primarily targeting ocular health and cognitive function. The segment experiences significant demand from North America and Europe, where consumer awareness of preventative eye care is high.
- Functional Food:Lutein is incorporated into everyday food and beverage items to provide added health benefits beyond basic nutrition, such as fortified yogurts and snack bars. The US FDA's GRAS designation has significantly expanded its use in this sector, particularly for products targeting an aging demographic.
- Pharmaceuticals:Lutein used in pharmaceutical products adheres to the highest purity and regulatory standards, often for specific medical indications related to eye diseases. This application requires extensive clinical validation and strict adherence to good manufacturing practices.
- Cosmetics:In cosmetics, lutein is valued for its antioxidant properties, contributing to skin health and protection against environmental damage. It is increasingly found in anti-aging creams and sun protection formulations.
- Animal Nutrition:Lutein serves as a natural pigment and antioxidant in animal feed, particularly for poultry to improve egg yolk color and for aquaculture.
Demand from the dietary supplements sector is consistently strong. Functional food applications are climbing the fastest, driven by regulatory support.
End User:
The type of business consuming lutein ingredients directly impacts purchasing volumes, technical support needs, and long-term partnership strategies.
- Manufacturers:These entities produce raw lutein extracts and ingredients, often supplying to other businesses for further processing or formulation. Kemin Industries, Inc. represents a vertically integrated manufacturer controlling the supply chain from marigold cultivation.
- Nutraceutical Companies:Specialized firms that formulate and market dietary supplements and functional foods containing lutein. OmniActive Health Technologies focuses on supplying clinically validated lutein ingredients to these companies.
- Food Processors:Large-scale food and beverage companies that incorporate lutein into a wide array of consumer products. These processors often require lutein in forms that are stable and easily integrated into existing production lines.
- Pharmaceutical Firms:Companies engaged in the research, development, and manufacturing of pharmaceutical drugs containing lutein. These firms demand the highest quality and regulatory compliance for their ingredients.
Nutraceutical companies drive significant purchasing power. Food processors are increasingly influencing ingredient specifications for new product development.
Formulation:
The final delivery method of lutein to the consumer influences ingredient specifications, stability requirements, and consumer acceptance.
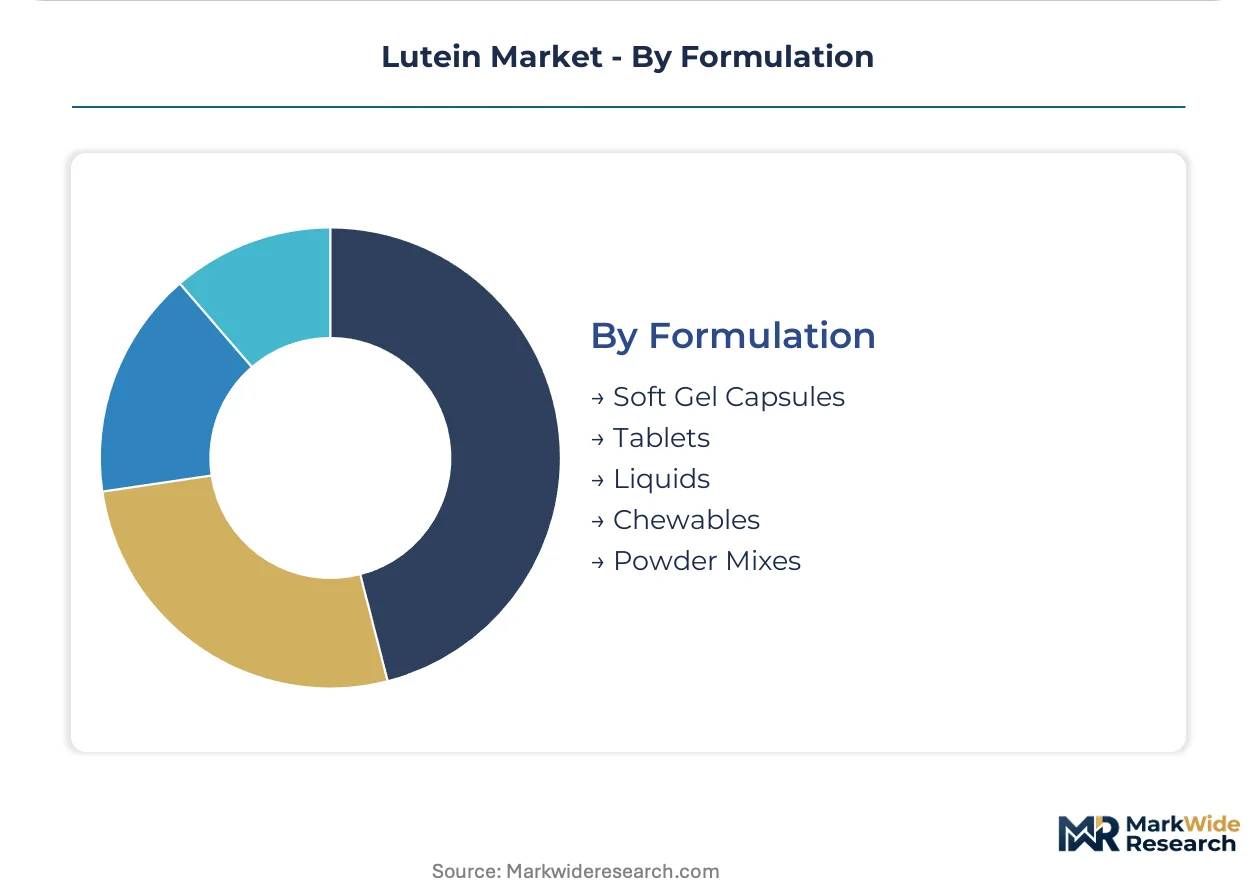
- Soft Gel Capsules:A popular formulation for dietary supplements, providing excellent bioavailability for oil-soluble nutrients like lutein. This format is widely adopted in North America and Europe for eye health supplements.
- Tablets:Solid dosage forms that are cost-effective and offer precise dosing, often incorporating lutein powders or granules. Tablets are a common choice for multi-vitamin and mineral supplements.
- Liquids:Lutein can be formulated into liquid supplements, often utilizing nano-emulsion technologies to improve dispersibility and absorption. This format is gaining popularity for children's supplements and those seeking alternative delivery methods.
- Chewables:These formulations offer an appealing option for consumers who prefer not to swallow pills, particularly children and the elderly. Gummies are a prominent example within this category.
- Powder Mixes:Lutein is incorporated into powder blends for shakes, smoothies, and other functional beverages, offering versatility and customizable dosing. This form is particularly suited for functional foods and sports nutrition products.
Soft Gel Capsules hold a mature market position. Powder Mixes are exhibiting the steepest expansion trajectory in new product launches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US FDA's GRAS designation significantly influences the global lutein market, establishing a clear regulatory benchmark that encourages broader application in functional foods and beverages worldwide. This regulatory clarity supports market expansion, particularly in regions with developing food safety frameworks. Consumer demand for preventative health solutions drives regional growth patterns.
United States
Demand for lutein in the United States concentrates in ocular health supplements and functional foods, driven by a health-conscious aging population. The US FDA's GRAS designation for specific lutein esters has significantly broadened its application in diverse product categories. California's robust nutraceutical industry leads innovation, developing new delivery systems and product formats for lutein ingredients.
China
China's lutein market experiences strong demand from its aging population, which increasingly prioritizes preventative health measures and dietary supplements. The NMPA (National Medical Products Administration) regulates health foods, influencing product formulation and market entry for lutein-containing products. The Yangtze River Delta region, with its dense urban centers, sees increasing consumption of lutein supplements and fortified foods.
India
India serves as a crucial raw material supplier for lutein, with extensive marigold cultivation supporting global supply chains, alongside a growing domestic market for supplements. The FSSAI (Food Safety and Standards Authority of India) sets standards for food ingredients, impacting the quality and safety of lutein extracts. Andhra Pradesh and Karnataka are primary cultivation and extraction hubs, driving both domestic supply and international exports.
Germany
German consumers exhibit high awareness of preventative health, fueling demand for premium nutraceuticals containing lutein for eye health and cognitive support. EFSA (European Food Safety Authority) regulations govern health claims for lutein, requiring robust clinical data for market substantiation. Bavaria's advanced pharmaceutical and nutraceutical sector focuses on developing clinically validated and highly bioavailable lutein formulations.
Brazil
Brazil's lutein market benefits from a rising middle class and increasing awareness of eye health supplements, representing a relatively underpenetrated growth frontier. ANVISA (National Health Surveillance Agency) oversees dietary supplements and food additives, ensuring product safety and efficacy. São Paulo state emerges as a significant hub for functional food and supplement manufacturing, integrating lutein into new consumer products.
Lutein Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the lutein market, dictating competitive dynamics and pricing structures. The market structure emphasizes control over the raw material supply chain as a critical competitive advantage. Strategic archetypes include vertically integrated raw material processors, specialized ingredient formulators, and broad-portfolio human nutrition suppliers. Dominant competitive moves involve securing raw material access and investing in clinical substantiation for health claims.
Specialized ingredient providers like OmniActive Health Technologies focus on clinically validated, branded lutein ingredients for the nutraceutical space. Kemin Industries, Inc. exemplifies a vertically integrated manufacturer, controlling the supply chain from marigold seed to finished ingredient. BASF SE, a German-based chemical company, competes through its broad portfolio of human nutrition ingredients and extensive global distribution networks, serving diverse end-use applications.
| Leading Market Players |
|---|
| Allied Biotech Corporation |
| Koninklijke DSM N.V. |
| BASF SE |
| Divi’s Laboratories |
| India Glycols Limited |
| Kemin Industries, Inc. |
| Chr. Hansen Holding A/S |
| Synthite Industries Ltd. |
| OmniActive Health Technologies |
| Others |
Cost & Logistics Intelligence
Lutein extraction lead times, influenced by marigold flower seasonality, directly impact the supply chain's inventory holding costs and finished ingredient pricing power for manufacturers. This dynamic reinforces the strategic advantage of vertically integrated players.
Pricing Analysis
Significant price variances exist between generic lutein from Asian suppliers and branded, clinically validated ingredients from Western manufacturers. The dominant pricing structure reflects a tiered model, with premium-mid-economy pricing differentiation based on purity grades and clinical substantiation. Price differentiation drivers include FDA GRAS status, specific health claim validation, and supply chain traceability certifications. Pricing softness runs through the generic lutein segment due to intense competition and commodity price volatility, while nutraceutical companies show less price sensitivity for premium, clinically-backed ingredients.
Supply Chain Analysis
India and China anchor marigold flower cultivation and initial lutein extraction, serving as critical raw material suppliers for the global market. The supply chain relies heavily on marigold flowers, making it vulnerable to agricultural dependency risks like climate change and crop diseases. Kemin Industries, Inc. exemplifies a vertically integrated model, controlling production from seed to finished ingredient. Distribution runs through direct partnerships with specialized ingredient suppliers for branded products, alongside a robust network of traders for generic lutein volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lutein market presents an early-cycle expansion story, driven by its increasing penetration into functional food categories and growing consumer awareness of ocular health benefits.
For Market Incumbents: Consolidate raw material sourcing through long-term contracts with marigold growers in India and China, mitigating agricultural supply volatility. Invest heavily in clinical trials to differentiate branded lutein ingredients, countering generic competition and substitution from zeaxanthin. Expand vertical integration capabilities to enhance supply chain control and cost efficiency. Prioritize robust traceability systems to meet evolving regulatory and consumer demands.
For New Entrants and Emerging Players: FDA GRAS certification fast-tracking for novel lutein esters offers new entrants a clear regulatory pathway into functional food applications. Target underpenetrated geographies like Brazil and Southeast Asia, where awareness of eye health supplements is rising. Focus on developing bioavailability-enhanced formulations, such as nano-emulsions, to justify premium pricing and create product differentiation. Partner with local food processors for rapid market entry and functional food integration.
For Investors and Strategic Acquirers: Long-term, this sits as a value-added ingredient play because preventative health trends and an aging global population underpin sustained demand. Identify specialized ingredient formulators with proprietary delivery technologies or strong clinical data as prime acquisition targets. A key signal to watch is the adoption rate of bioavailability-enhanced lutein products in mainstream functional foods, indicating market maturation and premiumization opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Substantiation Investment | Validates specific health claims for premium lutein products, building consumer trust. |
| Backward Integration into Marigold Cultivation | Secures raw material supply, mitigating agricultural dependency risks in India. |
| Novel Delivery System Development | Improves lutein bioavailability and water dispersibility for functional beverages. |
| Geographic Expansion into Brazil | Captures rising demand for eye health supplements in underpenetrated Latin American markets. |
| Functional Food Formulation Partnerships | Broadens lutein application beyond supplements, targeting mainstream consumers. |
Research Approach
The analysis maps lutein ingredient types, application segments, and end-user categories, each validated through extensive interviews with nutraceutical R&D directors and marigold cultivation experts. Primary insights from food processor procurement leads and regulatory affairs specialists were triangulated with secondary data from FDA GRAS notifications, EFSA opinions, and FSSAI standards. This approach combined bottom-up market sizing with top-down validation to ensure comprehensive coverage.
Forecast outputs were consistently checked against industry growth benchmarks and historical consumption patterns across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end user, formulation, and regional regulatory clusters. Compound annual growth rates were derived from a detailed assessment of market drivers, restraints, and strategic opportunities. Key industry-specific forecast inputs included marigold crop yields and the pace of new regulatory approvals.
Underlying assumptions cover stable marigold supply and consistent regulatory frameworks, with deviation risk concentrated in unforeseen agricultural disruptions or shifting food safety standards. Forecasts reflect these assumptions. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Liquid Dietary Supplements Market
Nutritional Supplements
Global Algal DHA and ARA Market
Nutritional Supplements
High-Concentrated Protein Market
Nutritional Supplements
Japan Dietary Supplements Market
Nutritional Supplements
Fish Collagen Market
Nutritional Supplements
Digestive Health Supplements Market
Nutritional Supplements
North America Spirulina Extract Market
Nutritional Supplements
Global Proanthocyanidins Market
Nutritional Supplements
Nutritional Lipids Market
Nutritional Supplements
Marine Hydrolyzed Collagen Market
Nutritional Supplements
Lactoferrin Products Market
Nutritional Supplements
Multivitamin and Mineral Supplements Market
Nutritional Supplements
EPA and DHA Market
Nutritional Supplements
Selenium Yeast Market
Nutritional Supplements
Smart Nutrition Scale Market
Nutritional Supplements
Heart Health Supplement Market