
 Vitamin D3 Oil Market | 2026-2036
Vitamin D3 Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Vitamin D3 Oil Market Analytics
ISO 22000 food safety management certification is rotating as the primary gating mechanism for new entrants seeking pharmaceutical and fortified food supply contracts. DSM leverages backward integration into 7-dehydrocholesterol fermentation to sustain European supply security. Zhejiang Garden Biochemical High-Tech anchors China's export dominance through captive production of vitamin D3 crystalline intermediates. Kingdomway competes aggressively on synthetic ethyl ester specifications for Southeast Asian feed additive buyers.
Vitamin D3 oil denotes cholecalciferol dissolved in edible carrier oils such as medium-chain triglycerides or sunflower oil, typically standardized between 1 and 4 million IU per gram for industrial dosing accuracy. Manufacturers employ molecular distillation or cold-pressing followed by saponification to achieve pharmaceutical-grade purity thresholds. Synthetic formulations currently occupy the largest value share due to cost scalability, while natural lanolin-derived variants command premium positioning in organic dietary supplements. The dietary supplements application leads volume consumption, though fortified food channels are expanding fastest as bakery and dairy processors reformulate with microencapsulated D3 oil to meet label claim stability requirements.
The US FDA maintains strict identity standards for cholecalciferol under 21 CFR 172.380, while the EU EFSA evaluates novel food applications and health claim substantiation for D3-fortified products. China's NMPA and SAMR jointly oversee active pharmaceutical ingredient registration, creating dual compliance burdens for exporters. India's CDSCO mandates import testing protocols that delay market entry for non-registered suppliers. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and ChP monographs, as divergence in assay methods directly impacts cross-border batch acceptance and inventory planning cycles.
Market Dynamics
Pharmaceutical-grade purity requirements under tightening EU F-Gas Regulation and REACH frameworks are restructuring supplier qualification criteria, forcing reformulation investments across fortified food and supplement channels.
Growth Catalysts
- REACH compliance acceleration:The European Union's tightened purity thresholds for imported active ingredients are filtering substandard suppliers and consolidating procurement toward certified manufacturers with ISO 22000 food safety management systems.
- Feed additive specification upgrading:Southeast Asian livestock operations are adopting synthetic ethyl ester formulations to meet export market residue standards, expanding industrial dosing demand for standardized 1-4 million IU per gram oils.
- Microencapsulation technology maturation:Bakery and dairy processors are reformulating with stabilized D3 oil to achieve label claim stability, opening fortified food as the fastest-expanding consumption channel.
Market Restraints
- 7-dehydrocholesterol feedstock concentration:Precursor manufacturing clusters in Zhejiang province create geographic supply vulnerability for non-integrated buyers lacking captive fermentation capacity.
- Lanolin-derived natural premium compression:Organic dietary supplement positioning commands price premiums that synthetic alternatives cannot match, segmenting volume accessibility.
- Dual registration burden friction:China's NMPA and SAMR joint oversight of active pharmaceutical ingredient registration creates compliance duplication that delays exporter market entry timelines.
Strategic Opportunities
- Pharmacopeial harmonization arbitrage:Divergence between USP, EP, and ChP assay methods creates inventory planning inefficiencies that agile suppliers can exploit through cross-border batch acceptance expertise.
- Cold-pressed natural segment white space:Underpenetrated organic certification channels in North American dietary supplements offer premium positioning for lanolin-derived variants with molecular distillation purity credentials.
- Import testing protocol specialization:India's CDSCO mandated inspection requirements favor pre-registered suppliers with established analytical documentation, creating barrier-protected niche positions.
Industry Challenges
- Fermentation scale-up talent scarcity:Backward integration into 7-dehydrocholesterol production requires specialized biochemical engineering expertise that competes with broader biopharma sector hiring.
- Carrier oil volatility management:Medium-chain triglyceride and sunflower oil input cost swings compress margin predictability for toll manufacturers without long-term supply contracts.
- Novel food substantiation timelines:EU EFSA health claim evaluation cycles for D3-fortified products extend product development pipelines and tie up regulatory affairs resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitamin D3 Oil Market |
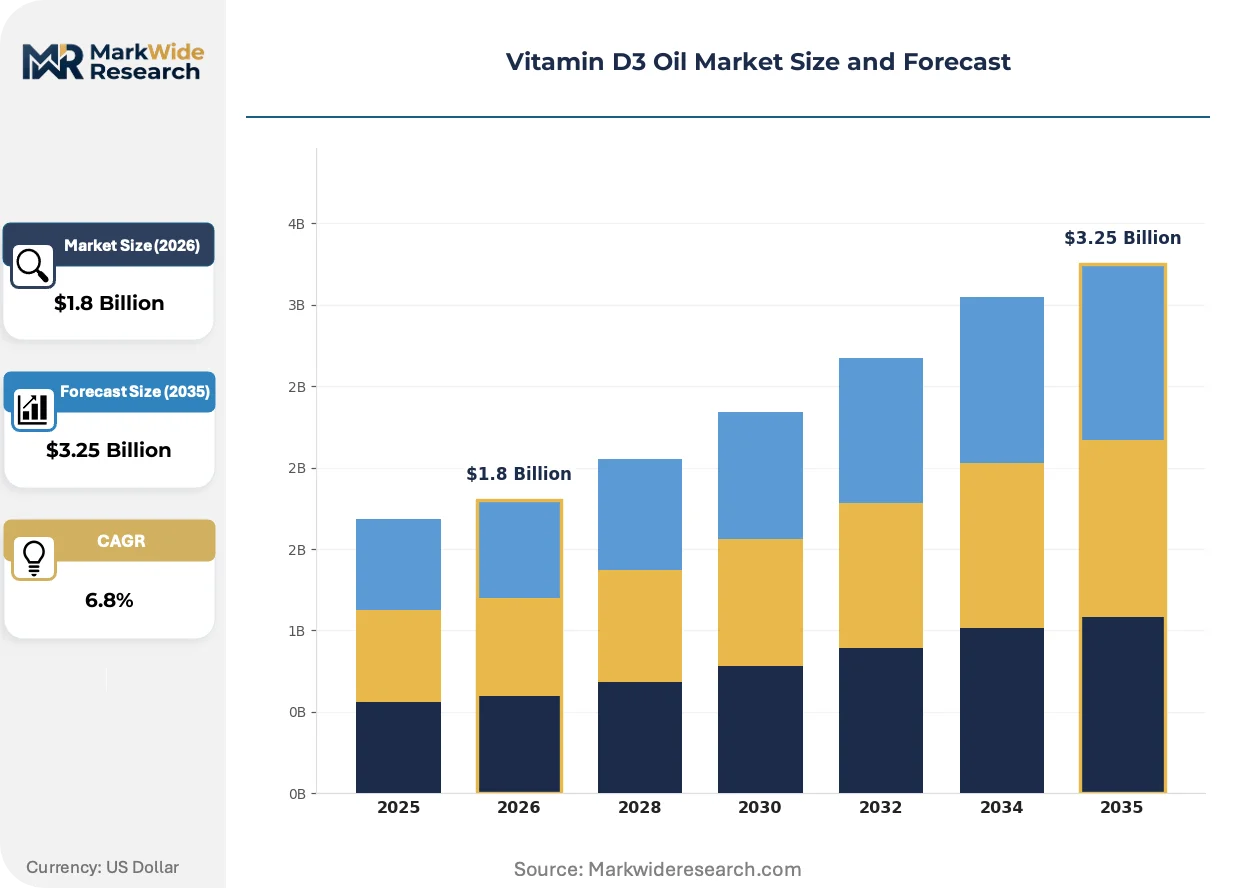
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Synthetic, Natural, Ethyl Ester Application: Dietary Supplements, Fortified Food, Pharmaceuticals, Cosmetics End User: Healthcare Providers, Retail Consumers, Fitness Enthusiasts, Manufacturers Distribution Channel: Online Retail, Pharma Stores, Supermarkets, Specialty Shops |
| Companies Covered | Xiamen Jindawei Vitamin Co. Ltd., Kingdomway, Zhejiang Garden Biochemical High-Tech, BASF, Taizhou Hisound Pharmaceutical, DSM, Fermenta Biotech Ltd., Zhejiang Medicine, NHU, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitamin D3 Oil Market Evolving Landscape
Molecular distillation refinement is compressing purity thresholds while regulatory divergence between pharmacopeias forces analytical method investments. Buyers are rotating procurement criteria toward integrated certification packages.
Supercritical CO2 extraction is displacing traditional saponification for pharmaceutical-grade cholecalciferol isolation. European supplement manufacturers are adopting this technology to meet residual solvent limits under tightening EP monographs. The process is displacing older cold-pressing methods in premium positioning, compressing acceptable impurity windows and raising capital requirements for new entrants.
EU F-Gas Regulation phase-down schedules are forcing refrigerant-dependent crystallization facilities toward alternative temperature control systems. Industrial consequence includes accelerated capital expenditure cycles for Zhejiang-based precursor manufacturers serving European export markets. Feed additive specification buyers are responding by diversifying supplier qualification toward facilities with confirmed compliance documentation.
Certification-driven procurement consolidation is compressing vendor lists among fortified food processors. Bakery and dairy reformulation projects are unbundling ingredient sourcing from traditional distribution channels, with direct manufacturer relationships replacing broker-mediated transactions. This pattern is most visible in German and Dutch dairy processing clusters where EFSA novel food approvals determine formulation feasibility.
Vitamin D3 Oil Market Segmentation
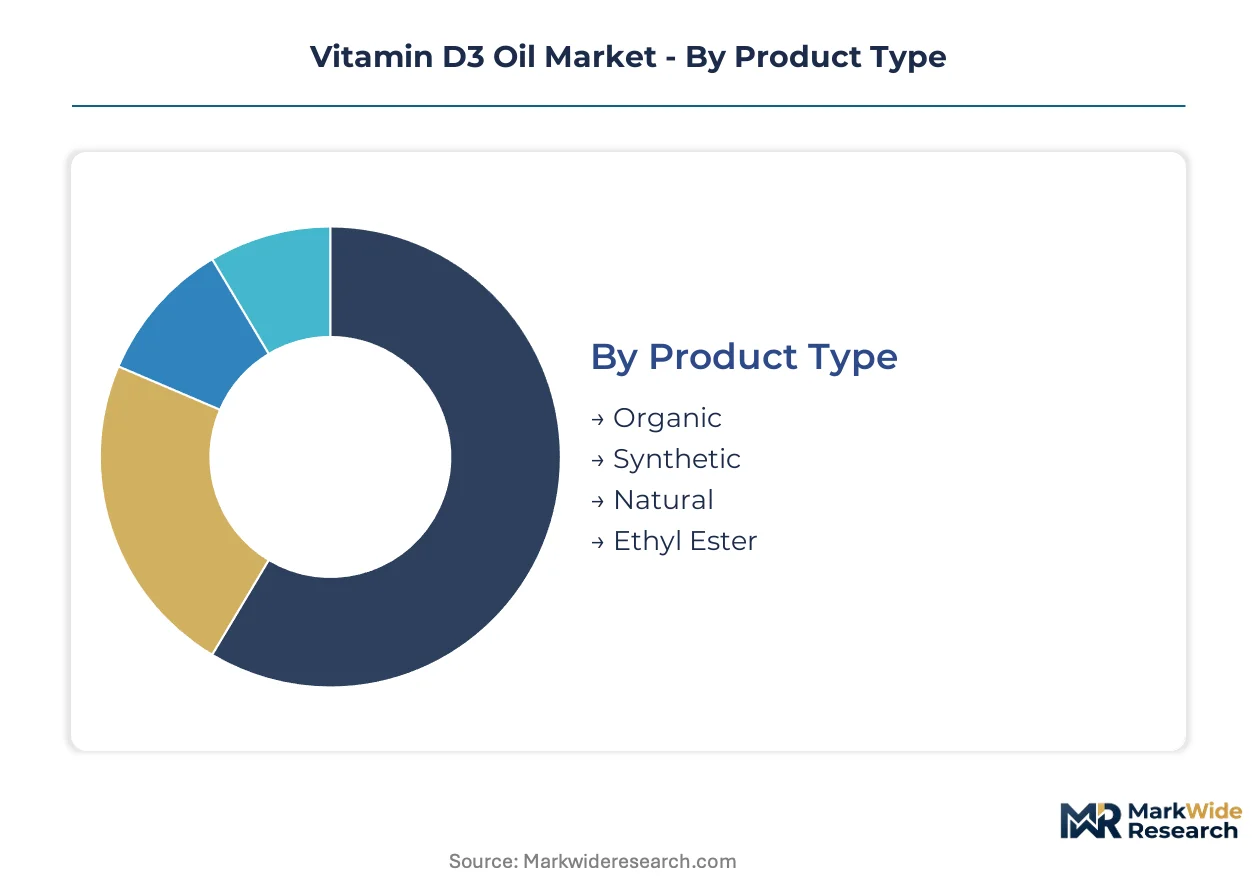
Segmentation in the Vitamin D3 Oil Market reveals how purity grades, application channels, and buyer sophistication stratify pricing power. Manufacturers calibrate formulation investments against certification requirements that vary sharply across end-use segments.
Product Type:
Margins concentrate in differentiated purity tiers where fermentation control and extraction method determine pharmaceutical eligibility versus commodity feed positioning.
- Organic:Lanolin-derived cholecalciferol processed through molecular distillation meets EU organic certification for premium dietary supplements. German and Dutch supplement manufacturers source this grade for EFSA novel food approvals, though limited precursor availability constrains volume scaling.
- Synthetic:Fermentation-based 7-dehydrocholesterol conversion dominates industrial supply through cost-scalable standardized dosing at 1-4 million IU per gram. DSM's backward integration into precursor fermentation secures European pharmaceutical security against Zhejiang supply concentration.
- Natural:Cold-pressed carrier oil suspensions serve North American organic positioning with residual solvent thresholds stricter than synthetic alternatives.
- Ethyl Ester:Southeast Asian feed additive buyers specify this formulation for livestock export residue compliance.
Synthetic holds installed capacity. Organic is rotating up the share rankings.
Application:
Volume throughput clusters where microencapsulation investments justify reformulation switching costs for processors facing label stability mandates.
- Fortified Food:Bakery and dairy processors deploy microencapsulated D3 oil to achieve EFSA-mandated label claim stability through temperature and oxidation resistance. German dairy clusters unbundle sourcing from brokers toward direct manufacturer relationships post-novel food approval.
- Dietary Supplements:Softgel and drop formulations consume the largest absolute volumes, with USP-grade specifications filtering supplier qualification toward ISO 22000 certified manufacturers.
- Pharmaceuticals:Injectable and oral dosage APIs require ChP-USP-EP harmonized assay documentation that delays batch release for non-integrated suppliers.
- Cosmetics:Topical serum formulations command stability specifications distinct from ingestible grades, with carrier oil selection driving dermatological tolerance testing.
Dietary Supplements maintains volume leadership. Fortified Food is climbing the fastest.
End User:
Procurement sophistication determines whether buyers absorb compliance documentation burdens or delegate qualification to distributor intermediaries.
- Healthcare Providers:Hospital and clinic systems mandate pharmaceutical-grade documentation with pharmacopeial harmonization across USP, EP, and ChP monographs for therapeutic dosing applications.
- Retail Consumers:Direct-to-purchaser channels favor single-ingredient transparency labeling with organic or natural positioning premiums.
- Fitness Enthusiasts:Sports nutrition formulators prioritize high-potency unit dosing with third-party purity verification.
- Manufacturers:Toll processors and contract packagers manage carrier oil volatility through long-term supply contracts for medium-chain triglyceride and sunflower oil inputs.
Healthcare Providers anchor specification setting. Manufacturers are gaining procurement sophistication.
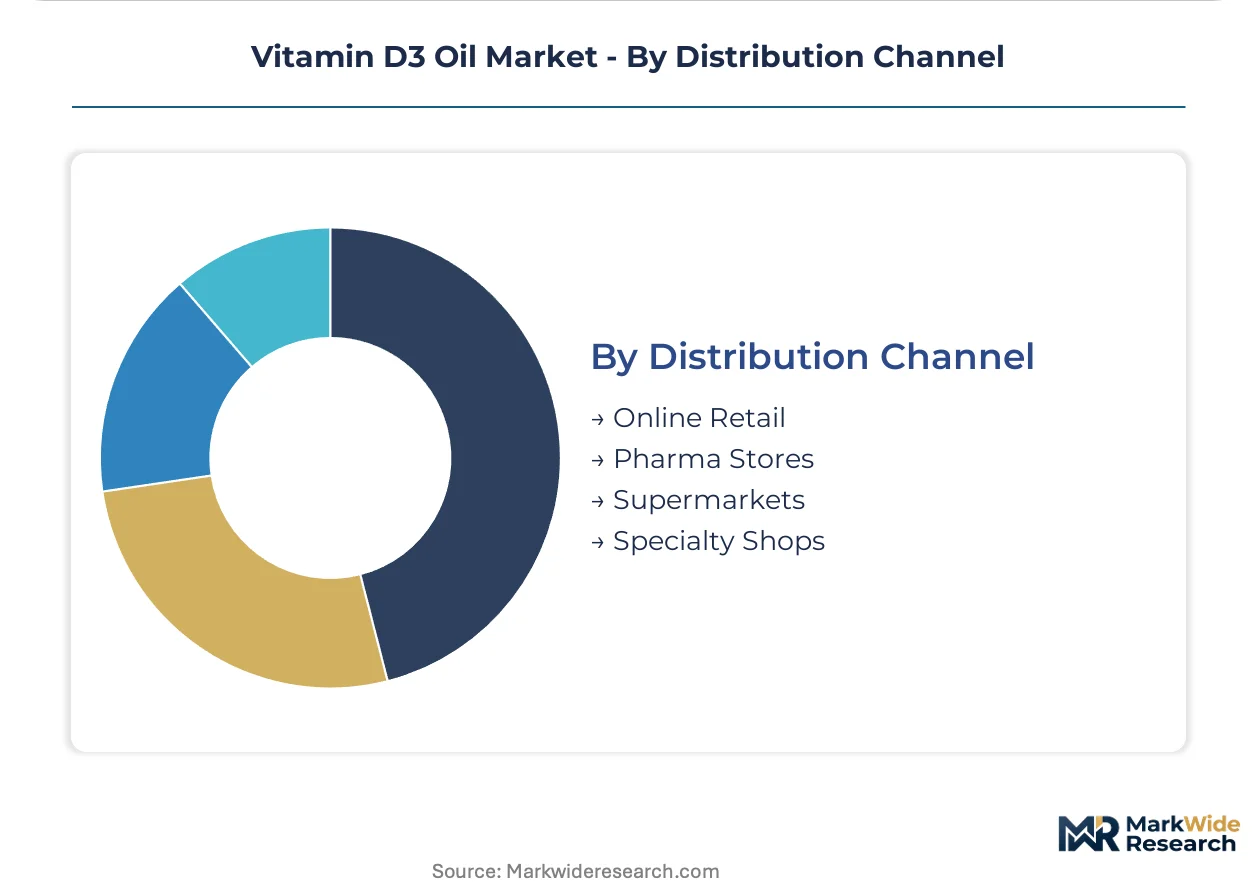
Distribution Channel:
Channel selection locks in margin capture versus customer acquisition cost tradeoffs that vary by buyer education and reorder frequency.
- Online Retail:Direct-to-consumer platforms capture organic and natural segment premiums through subscription replenishment models with certificate of analysis transparency.
- Pharma Stores:Pharmacy chains enforce supplier pre-registration with national pharmaceutical regulators, creating barrier-protected shelf access for documented manufacturers.
- Supermarkets:Mass retail fortified food placement requires processor-level direct relationships bypassing traditional ingredient brokers.
- Specialty Shops:Health food and organic retailers curate lanolin-derived positioning with molecular distillation purity credentials for premium pricing.
Pharma Stores dominate pharmaceutical-grade volume. Online Retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare systems and fortified food processors concentrate procurement authority in Germany, China, and the United States, with secondary demand clustering in India and the Netherlands where regulatory frameworks reshape supplier qualification.
United States
Hospital systems and retail pharmacy chains drive pharmaceutical-grade cholecalciferol consumption through USP-grade specifications. The FDA maintains strict identity standards under 21 CFR 172.380 for fortified food and supplement applications. New Jersey and California host the dominant dietary supplement manufacturing clusters, with softgel and drop formulation facilities unbundling from traditional distribution channels.
Germany
Bakery and dairy processors deploy microencapsulated D3 oil to achieve EFSA-mandated label claim stability through temperature resistance. The EU F-Gas Regulation and REACH compliance frameworks tighten purity requirements for imported active ingredients. The North Rhine-Westphalia dairy processing corridor unbundles sourcing from brokers toward direct manufacturer relationships post-novel food approval.
China
Export-oriented precursor manufacturing and domestic fortified food expansion create dual demand channels for standardized 1-4 million IU per gram oils. The NMPA and SAMR jointly oversee active pharmaceutical ingredient registration, creating dual compliance burdens for exporters. Zhejiang province hosts the dominant share of cholecalciferol precursor manufacturing, with fermentation capacity concentrated in Hangzhou and Ningbo industrial zones.
India
Contract manufacturing for export markets and domestic supplement consumption expand industrial dosing demand. The CDSCO mandates import testing protocols that delay market entry for non-registered suppliers. Maharashtra and Gujarat pharmaceutical clusters absorb compliance documentation burdens through pre-registered supplier relationships with established analytical documentation.
Netherlands
EFSA novel food evaluation expertise and fortified food reformulation services attract pan-European processor demand. The EU EFSA evaluates health claim substantiation for D3-fortified products, extending product development pipelines. The Randstad logistics corridor facilitates cross-border batch distribution to German and Belgian dairy processing clusters.
Vitamin D3 Oil Market Competitive Landscape
Player mix skews toward backward-integrated fermentation specialists and toll manufacturers with pharmacopeial harmonization expertise. The vendor base stratifies across three tiers: captive precursor producers with European supply security, Chinese export platforms with crystalline intermediate dominance, and regional toll processors managing carrier oil volatility. Competitive moves center on fermentation scale-up capacity additions and direct processor relationships bypassing traditional distribution channels.
Among Chinese export platforms, Zhejiang Garden Biochemical High-Tech and Kingdomway occupy positions reflecting distinct strategic archetypes. Zhejiang Garden Biochemical High-Tech anchors export dominance through captive production of vitamin D3 crystalline intermediates. Kingdomway represents aggressive positioning on synthetic ethyl ester specifications for Southeast Asian feed additive buyers. Xiamen Jindawei Vitamin Co. Ltd. sits within the regional toll processor tier serving domestic fortified food and supplement channels. European supply security is exemplified by DSM, which leverages backward integration into 7-dehydrocholesterol fermentation. BASF represents diversified chemical majors with cross-segment vitamin portfolio breadth.
| Leading Market Players |
|---|
| Xiamen Jindawei Vitamin Co. Ltd. |
| Kingdomway |
| Zhejiang Garden Biochemical High-Tech |
| BASF |
| Taizhou Hisound Pharmaceutical |
| DSM |
| Fermenta Biotech Ltd. |
| Zhejiang Medicine |
| NHU |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles for 7-dehydrocholesterol precursors signal supply chain rigidity that amplifies pricing power for Zhejiang-based manufacturers serving European pharmaceutical buyers. Carrier oil input volatility and REACH compliance documentation burdens compress margins for toll processors without backward integration into fermentation capacity.
Pricing Analysis
Cost-plus contracts indexed to sunflower oil and medium-chain triglyceride commodity benchmarks dominate procurement for standardized 1-4 million IU per gram formulations. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certification levels separates DSM's European supply security premium from Chinese export platform competitiveness. Cost compression in synthetic ethyl ester segments is intensifying because Kingdomway and regional competitors prioritize volume share over margin protection in Southeast Asian livestock markets. Feed additive buyers exhibit highest price sensitivity, while German dairy processors absorbing EFSA novel food compliance costs show lowest sensitivity.
Supply Chain Analysis
Strait of Malacca transit underwrites logistics costs for Zhejiang-origin crystalline intermediates reaching Rotterdam and Hamburg pharmaceutical clusters. Manufacturing gravity centers on China, the Netherlands, and Germany, with precursor fermentation drawing from cholesterol feedstocks and 7-dehydrocholesterol conversion chemistry. Single-source vulnerability concentrates in Hangzhou and Ningbo industrial zones where NMPA-SAMR dual registration creates exporter qualification bottlenecks. Distribution runs through direct manufacturer relationships that German and Dutch dairy processors established post-novel food approval, displacing traditional ingredient brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA health claim substantiation timelines and pharmacopeial harmonization gaps fragment competitive space, creating defendable niches for documentation-specialized suppliers across pharmaceutical and fortified food channels.
For Market Incumbents: Consolidate fermentation scale-up talent pools against biopharma sector competition while locking long-term carrier oil supply contracts to neutralize margin volatility. DSM's backward integration into 7-dehydrocholesterol production exemplifies defensive positioning against Zhejiang supply concentration risk. Pre-registration with India's CDSCO creates barrier-protected shelf access that late entrants cannot replicate quickly. For New Entrants and Emerging Players: Lead with cold-pressed natural segment positioning in North American organic certification channels where lanolin-derived variants command premium pricing unmatched by synthetic alternatives. Target import testing protocol specialization for Indian pharmaceutical clusters where CDSCO-mandated inspection requirements favor suppliers with established analytical documentation. Direct-to-consumer subscription models with certificate of analysis transparency offer go-to-market differentiation against broker-mediated legacy channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across supercritical CO2 extraction facilities as European EP monograph tightening raises residual solvent compliance thresholds. Five-to-ten year viability favors toll processors with pharmacopeial harmonization expertise and confirmed ISO 22000 certification rather than undifferentiated commodity manufacturers. Monitor EU F-Gas Regulation phase-down implementation as inflection signal for Zhejiang-based precursor manufacturer capital expenditure cycles and European buyer diversification urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Fermentation | DSM's 7-dehydrocholesterol capacity secures European pharmaceutical supply security against Zhejiang concentration. |
| Supercritical CO2 Extraction Technology Adoption | European supplement manufacturers deploy this process to meet tightening EP residual solvent limits. |
| Microencapsulation Formulation Investment | German dairy processors achieve EFSA-mandated label claim stability through temperature-resistant D3 oil. |
| CDSCO Pre-Registration Completion | Established analytical documentation accelerates Indian market entry against non-registered supplier delays. |
| Direct Manufacturer Relationship Establishment | North Rhine-Westphalia dairy clusters bypass traditional brokers post-novel food approval. |
Research Methodology
A spread of perspectives from fermentation plant managers, pharmaceutical procurement leads, regulatory affairs directors at supplement manufacturers, and EFSA novel food application specialists converged on the working assumptions. Primary interviews combined with secondary validation against USP monograph revisions, EFSA health claim evaluations, NMPA-SAMR registration databases, and CDSCO import testing protocols. Bottom-up capacity assessments across Zhejiang fermentation zones triangulated against top-down fortified food reformulation demand projections.
Segmentation dimensions modeled include purity grade tier, application channel, end-user procurement sophistication, and distribution channel structure across the projection horizon. CAGRs derived from weighted scenario analysis incorporating REACH compliance acceleration timelines and feed additive specification upgrading patterns. Forecast inputs incorporated EU F-Gas Regulation phase-down schedules and microencapsulation technology maturation curves.
Underlying assumptions cover pharmacopeial harmonization progression, carrier oil commodity price bands, and fermentation capacity expansion rates, with deviation risk concentrated in regulatory timeline delays and precursor supply disruption events. Practitioners should keep alternative scenarios live as EFSA novel food evaluation cycles and Zhejiang industrial policy shifts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Fortified Yeast Market
Vitamin Fortified
Middle East Feed Vitamins Market
Vitamin Fortified
Global Fortified Edible Oils Market
Vitamin Fortified
Vitamin B12 Drops Market
Vitamin Fortified
Fortified Beverages Market
Vitamin Fortified
Water Soluble Vitamins Market
Vitamin Fortified
Tocopherols Market
Vitamin Fortified
Vitamin AD Drops Market
Vitamin Fortified
Vitamin K Market
Vitamin Fortified
Food Grade Retinol (Retinene) Market
Vitamin Fortified
Colecalciferol Market
Vitamin Fortified
Natural Source Vitamin E Market
Vitamin Fortified
Europe Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Fortified Cereal Market
Vitamin Fortified
Synthetic Vitamin E Market
Vitamin Fortified
Esterified Vitamins Market