
 Global Lutein and Lutein Esters Market | 2026-2036
Global Lutein and Lutein Esters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lutein and Lutein Esters Market Outlook
Natural marigold extract is broadening its position against synthetic carotenoid alternatives in lutein production economics. Kemin Industries leverages vertically integrated marigold cultivation in India and the United States to secure raw material consistency. OmniActive Health Technologies anchors its portfolio in clinically validated lutein ester formulations for eye health. BASF competes through synthetic lutein capacity that undercuts natural extraction costs in price-sensitive animal feed segments.
Lutein and lutein esters comprise xanthophyll carotenoids with conjugated double-bond systems that filter high-energy blue light and quench reactive oxygen species in retinal tissue; commercial grades typically specify 5-20% active content in oil suspensions or cold-water-dispersible beadlets for beverage and supplement integration. Natural lutein commands premium positioning in dietary supplements where consumers prioritize plant-derived provenance, while synthetic lutein dominates animal feed applications where cost efficiency outweighs sourcing claims. The dietary supplements application draws the deepest margin pools as finished brands absorb ingredient premiums through clinical-positioning pricing.
The FDA oversees lutein as a dietary ingredient under DSHEA with New Dietary Ingredient notification requirements for novel delivery formats, while EFSA in Europe evaluates health claim substantiation for vision-related marketing. China's NMPA and SAMR regulate lutein ester approvals for blue-hat health food registration, constraining market entry timelines for foreign suppliers. India's FSSAI and CDSCO monitor import quality standards for carotenoid premixes used in pharmaceutical and nutraceutical compounding. Stakeholders must track evolving Novel Food consultations in Brussels and pending GRAS self-affirmation pathways in Washington to anticipate formulation and labeling requirements that will determine competitive access.
Market Dynamics
Marigold cultivation concentration in India and the United States is tightening raw material control among vertically integrated extractors, forcing second-tier formulators into contract-manufacturing dependencies and reshaping margin distribution across the value chain.
Growth Catalysts
- EU Novel Food regulation:Clean-label mandates in Germany and France are redirecting formulation choices toward natural-extraction sources, accelerating marigold-derived lutein adoption in premium supplement lines.
- Aging-population supplement demand:Eye health positioning among United States consumers over 55 is concentrating procurement volumes with clinically validated lutein ester suppliers.
- Functional food integration:Beverage developers in Japan and South Korea are incorporating cold-water-dispersible beadlet formats into vision-health positioned ready-to-drink products.
Market Restraints
- Input cost volatility:Marigold flower prices fluctuate with monsoon patterns in India's Madhya Pradesh and Karnataka growing belts, compressing extractor margins during poor harvest cycles.
- Supply concentration risk:Overreliance on Kakinada and Hyderabad processing clusters creates single-point vulnerability for European and North American formulators.
- Synthetic substitution threat:BASF's petrochemical-derived lutein undercuts natural extraction costs in price-sensitive animal feed applications, capping premium pricing power.
Strategic Opportunities
- Brazil's underpenetrated supplement sector:ANVISA's evolving health food regulations are opening registration pathways for lutein ester formulations targeting the country's aging demographic.
- China blue-hat registration tailwind:NMPA and SAMR approvals for eye health claims create first-mover advantages for foreign suppliers navigating extended compliance timelines.
- Direct-to-practitioner channel innovation:Functional medicine clinics in Australia and Canada are bypassing retail intermediaries, creating higher-margin distribution for clinical-grade lutein.
Industry Challenges
- Phytochemical standardization complexity:Batch-to-batch lutein ester ratio consistency requires sophisticated HPLC validation capabilities that mid-tier formulators lack.
- GRAS self-affirmation timeline compression:FDA notification requirements for novel delivery formats extend product launch cycles, straining smaller developers' capital reserves.
- Cross-border customs clearance friction:India's DGFT export documentation for carotenoid premixes creates unpredictable delivery schedules for European compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lutein and Lutein Esters Market |
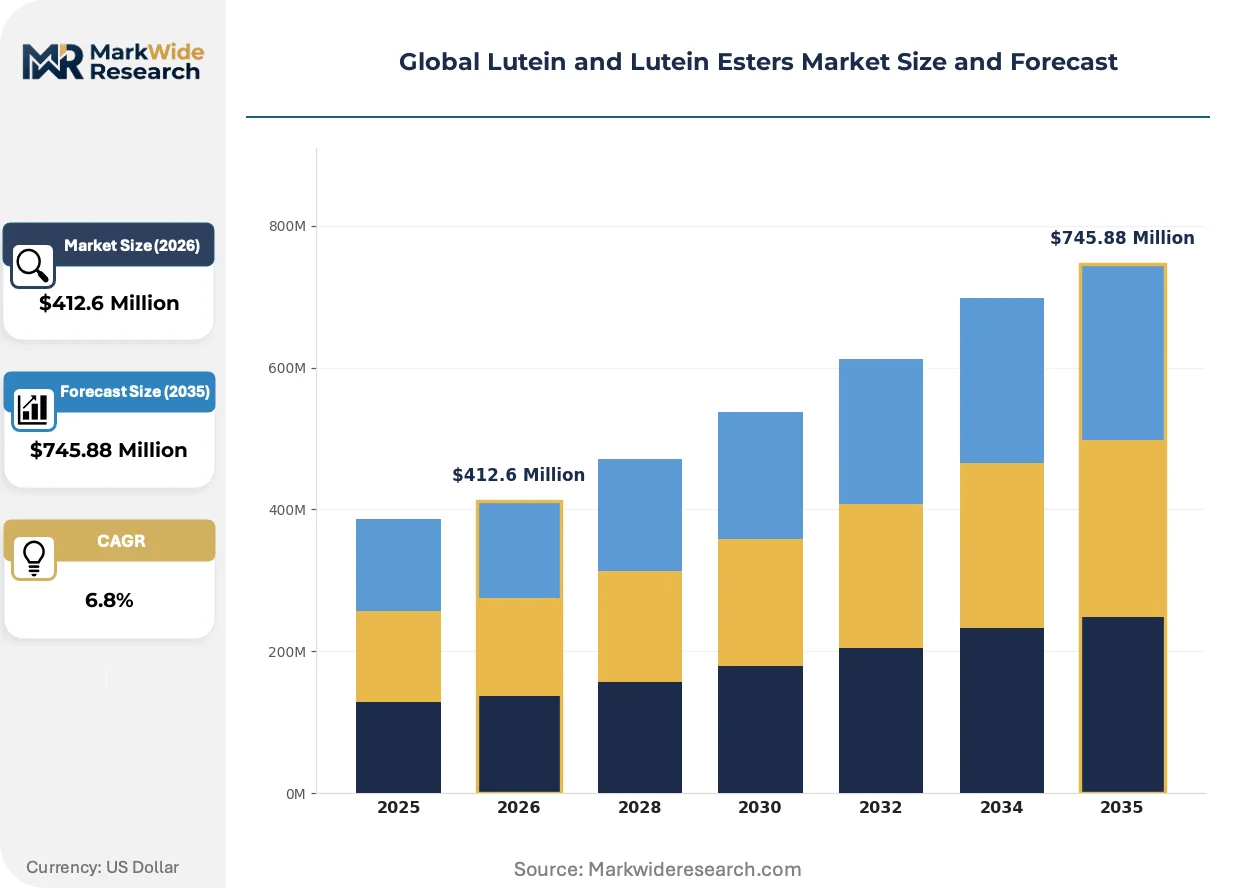
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Lutein, Lutein Esters, Synthetic Lutein, Liquid Lutein Application: Food & Beverage, Dietary Supplements, Animal Feed, Cosmetics End User: Healthcare, Food Industry, Nutraceuticals, Cosmetics Industry Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Kemin Industries, OmniActive Health Technologies, Allied Biotech Corporation, Chenguang Biotech Group, Synthite, BASF, Qingdao Scitech Biotech, Chr. Hansen Holding, Divis Nutraceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lutein and Lutein Esters Market Strategic Shifts
Microencapsulation technology is fragmenting production geography by enabling smaller-scale, regionally distributed lutein processing that challenges centralized extraction economics.
Spray-dried beadlet manufacturing is decentralizing lutein formulation capability. Regional supplement contractors in Poland and Mexico are adopting modular encapsulation units. This technology is compressing minimum order quantities and enabling just-in-time production for mid-sized brands previously excluded from bulk supply contracts.
EFSA's evolving health claim substantiation requirements for vision-related marketing are tightening clinical evidence standards. Finished brands must now fund intervention studies to support packaging claims. Dietary supplement marketers targeting German and Italian consumers are reformulating toward lutein-zeaxanthin combinations with stronger peer-reviewed backing.
Practitioner-channel purchasing is displacing retail-driven procurement in premium eye health segments. Functional medicine networks in the United States and Australia are aggregating demand through group purchasing organizations. This channel rotation is most visible in California and Sydney metropolitan clusters where integrative health practices concentrate.
Global Lutein and Lutein Esters Market Segmentation
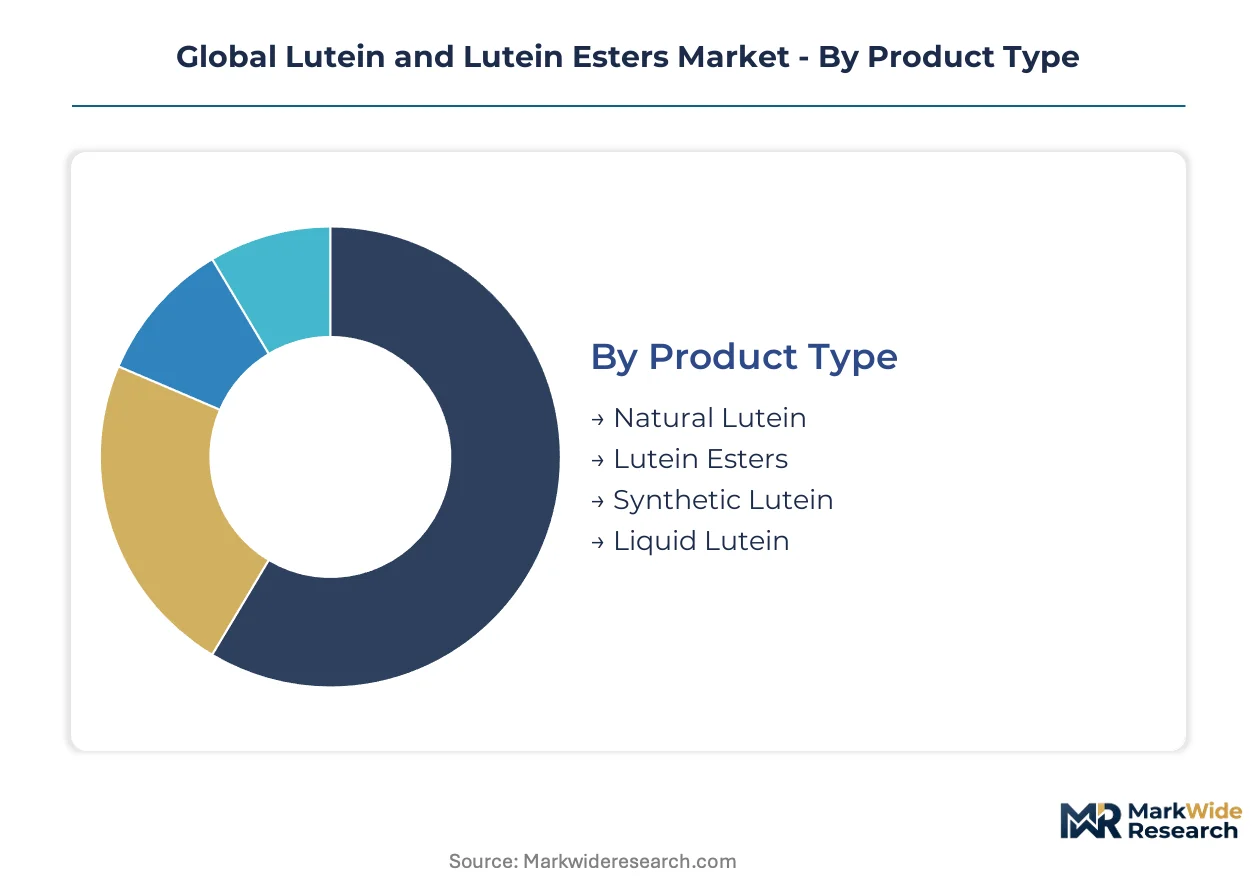
Lutein and lutein esters serve divergent buyer requirements across extraction methods, delivery formats, and end-use specifications. Segmentation reveals how procurement economics split between premium natural positioning and cost-driven synthetic alternatives.
Product Type:
Cost tier differentiation separates buyers seeking clinical-grade provenance from those prioritizing unit economics in bulk applications.
- Natural Lutein:Marigold-derived xanthophyll carotenoids with 5-20% standardized active content in oil suspensions or beadlet formats. Demand concentrates in United States and German dietary supplement brands where clean-label positioning commands formulation premiums despite higher input costs.
- Lutein Esters:Esterified forms requiring enzymatic hydrolysis for bioavailability, specified for clinical validation in eye health positioning. Procurement volumes cluster with aging-population supplement developers in North America seeking EFSA-compliant health claim substantiation.
- Synthetic Lutein:Petrochemical-derived isomers produced through BASF's industrial carotenoid synthesis. Animal feed compounders in price-sensitive markets absorb this grade for poultry pigmentation where sourcing claims carry minimal consumer visibility.
- Liquid Lutein:Oil-dispersed concentrates for beverage fortification and functional food integration. Japanese and South Korean ready-to-drink manufacturers specify cold-water-dispersible variants for vision-health product lines.
Natural lutein leads volumes today; synthetic lutein is gaining share fastest in feed applications.
Application:
Margin structure varies dramatically across end-use channels, with clinical positioning enabling deepest value capture.
- Dietary Supplements:Capsule and tablet formulations targeting macular health and blue-light protection. United States consumers over 55 drive procurement concentration with brands absorbing ingredient premiums through clinical-positioning pricing.
- Food & Beverage:Fortified dairy, juices, and functional drinks incorporating beadlet or emulsion formats. Japanese beverage developers lead adoption of cold-water-dispersible lutein for vision-health ready-to-drink positioning.
- Animal Feed:Poultry and aquaculture pigmentation applications where cost efficiency dominates sourcing decisions. Synthetic lutein from European chemical manufacturers undercuts natural extraction economics in this segment.
- Cosmetics:Topical antioxidant formulations leveraging lutein's photoprotective properties. Korean skincare brands specify ultra-pure grades for premium anti-aging product lines.
Dietary supplements command the steepest margin premiums; food and beverage applications are climbing the fastest.
End User:
Customer sophistication determines specification stringency and validation requirements.
- Nutraceuticals:Dedicated supplement manufacturers requiring batch-to-batch HPLC standardization and clinical trial backing for health claims. German and Italian marketers fund intervention studies to satisfy EFSA substantiation requirements.
- Healthcare:Functional medicine clinics and practitioner channels aggregating demand through group purchasing organizations. Australian integrative health networks in Sydney metropolitan clusters bypass retail intermediaries for clinical-grade supply.
- Food Industry:Mass-market fortification programs with cost-optimized specifications. Brazilian food processors await ANVISA regulatory clarity before scaling eye-health positioned product lines.
- Cosmetics Industry:Formulators seeking photostability and antioxidant synergy in topical applications. South Korean manufacturers lead regional adoption for anti-blue-light skincare positioning.
Nutraceuticals dominate procurement volumes; healthcare channels are expanding most quickly.
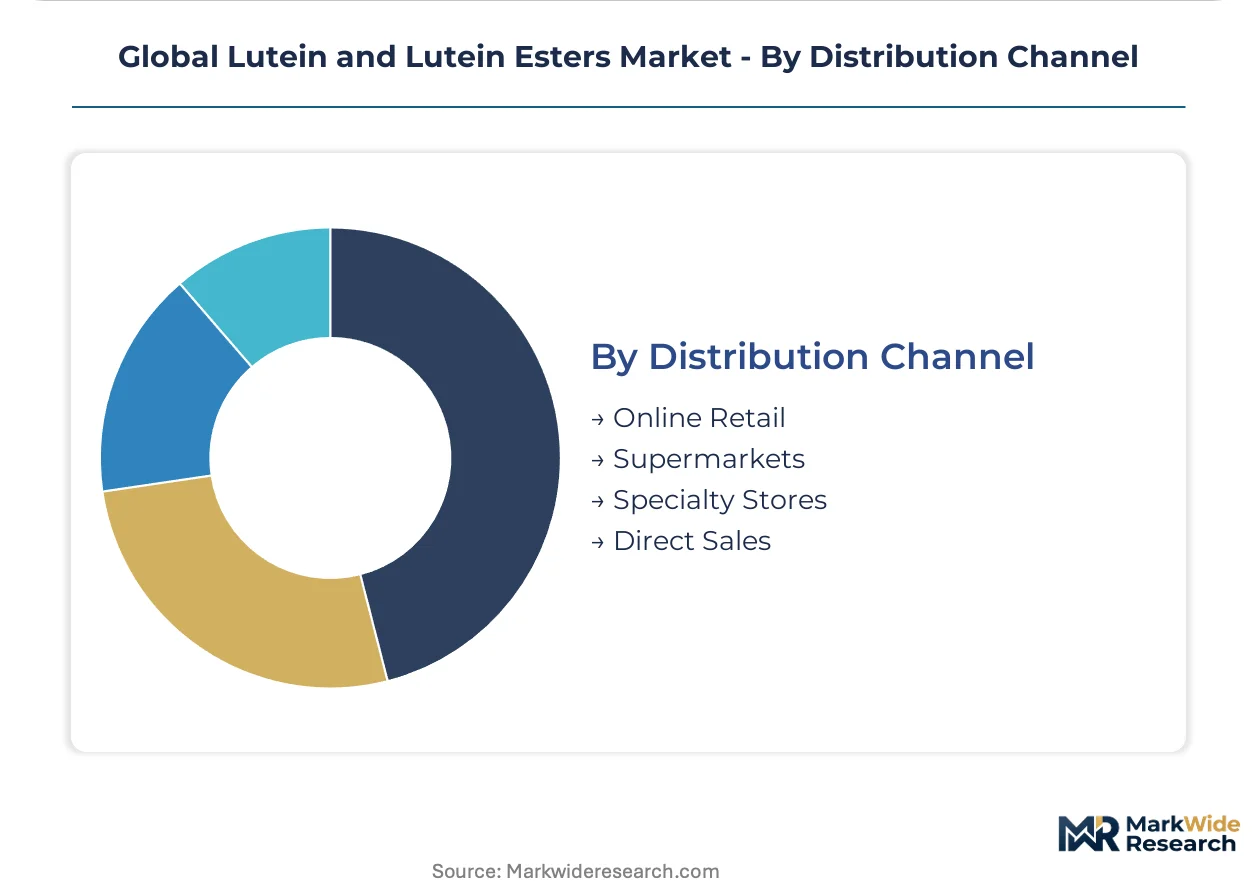
Distribution Channel:
Channel selection reflects buyer scale, technical support needs, and geographic access constraints.
- Direct Sales:Long-term supply contracts between extractors and large-scale formulators ensuring raw material security. Vertically integrated marigold cultivators in India and the United States lock in volume commitments through captive supply arrangements.
- Specialty Stores:Premium supplement retailers curating clinically validated lutein ester brands for discerning consumers. German pharmacy chains emphasize EFSA-approved health claims in their eye health assortments.
- Online Retail:Direct-to-consumer platforms enabling mid-sized brands to bypass traditional distribution markups. United States aging-population demographics drive subscription-model purchasing for macular health formulations.
- Supermarkets:Mass-market fortified food and beverage placement requiring price-competitive sourcing. Japanese convenience retail chains stock vision-health positioned functional drinks with lutein fortification.
Direct sales anchor volume flows; online retail is gaining share fastest among emerging brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kakinada and Hyderabad processing clusters anchor global marigold extraction capacity, concentrating raw material flows for North American and European formulators. FDA and EFSA regulatory frameworks shape import requirements across destination markets. Three countries dominate procurement volumes while two emerging markets reshape competitive access.
United States
Aging-population supplement brands in California and Florida drive concentrated procurement of clinically validated lutein ester formulations. FDA DSHEA oversight requires New Dietary Ingredient notifications for novel delivery formats, extending product launch timelines. Greater Los Angeles and Miami metropolitan clusters host functional food developers seeking vision-health positioning for ready-to-drink beverages.
Germany
Clean-label ingredient demand from Munich and Berlin-based supplement marketers redirects formulation choices toward natural-extraction sources. EFSA health claim substantiation requirements tighten clinical evidence standards for vision-related marketing. Bavaria's pharmacy chains emphasize EFSA-approved eye health assortments, curating premium lutein ester brands for discerning consumers.
India
Madhya Pradesh and Karnataka marigold cultivation belts supply raw material to Kakinada and Hyderabad extraction facilities. FSSAI and CDSCO monitor import quality standards for carotenoid premixes used in pharmaceutical compounding. DGFT export documentation creates unpredictable delivery schedules for European compounders sourcing from these processing clusters.
China
Blue-hat health food registration pathways under NMPA and SAMR constrain market entry timelines for foreign lutein suppliers. Yangtze River Delta supplement manufacturers await regulatory clarity before scaling eye-health positioned product lines. Shanghai and Hangzhou metropolitan areas concentrate domestic demand for vision-health formulations among aging demographics.
Brazil
ANVISA's evolving health food regulations open registration pathways for lutein ester formulations targeting the country's aging demographic. São Paulo and Rio de Janeiro supplement distributors anticipate regulatory finalization before committing procurement volumes. Southeast regional formulators position for first-mover advantages in underpenetrated practitioner channels.
Global Lutein and Lutein Esters Market Competitive Environment
Global majors compete with regional champions across extraction technology and raw material control. The vendor base splits between vertically integrated marigold cultivators and specialized formulation houses. Three archetypes dominate: captive supply operators controlling upstream cultivation, clinical-validation specialists funding intervention studies, and synthetic producers leveraging petrochemical cost structures. Capacity expansion and strategic partnerships represent the dominant competitive moves, with extractors locking in long-term supply contracts and formulators securing validation backing for health claims.
Within the vertically integrated tier, Kemin Industries exemplifies upstream control through captive marigold cultivation spanning multiple continents. OmniActive Health Technologies occupies a position emphasizing clinically validated lutein ester formulations for eye health positioning. BASF anchors the synthetic production archetype, representing cost-driven alternatives that undercut natural extraction economics in price-sensitive applications. These three entities collectively illustrate how procurement economics split between premium natural provenance and industrial-scale unit cost optimization.
| Leading Market Players |
|---|
| Kemin Industries |
| OmniActive Health Technologies |
| Allied Biotech Corporation |
| Chenguang Biotech Group |
| Synthite |
| BASF |
| Qingdao Scitech Biotech |
| Chr. Hansen Holding |
| Divis Nutraceuticals |
| Others |
Value Chain & Pricing Dynamics
Dietary supplement manufacturers in North America and Europe anchor procurement volumes for clinically validated lutein ester grades, concentrating pricing power with vertically integrated extractors who command premium positioning through raw material control.
Pricing Analysis
Input-cost pass-through from marigold flower volatility in India's Madhya Pradesh and Karnataka belts directly compresses extractor margins during poor monsoon harvests. Three-tier pricing structure across premium clinical-grade, standard dietary supplement, and economy feed-grade levels stratifies the market, with EFSA-compliant health claim substantiation and FDA NDI notification status serving as the primary price differentiation drivers. Pricing pressure stems from BASF's synthetic lutein undercutting natural extraction costs in animal feed applications. Animal feed compounders exhibit highest price sensitivity, while aging-population supplement brands in the United States absorb premiums for clinically validated formulations.
Supply Chain Analysis
Reverse-logistics flows for expired or off-specification lutein beadlets remain minimal given the ingredient's stability and shelf-life, though contract manufacturers in Poland and Mexico increasingly handle reprocessing of emulsion formats. Supply concentrates in India, the United States, and China, with marigold cultivation and extraction capacity anchored in Kakinada and Hyderabad processing clusters. Raw material flows depend on petrochemical precursors for synthetic grades and marigold flower biomass for natural extraction. Single-source vulnerability around Indian processing hubs creates structural risk for European and North American formulators. Distribution runs through direct long-term supply contracts for large-scale buyers and specialty distributors serving mid-tier supplement brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Lutein and Lutein Esters Market functions as a stable compounder, with aging-population eye health demand providing consistent procurement volumes that smooth cyclical input cost volatility.
For Market Incumbents: Anchor backward integration into captive marigold cultivation across multiple continents to secure raw material consistency against monsoon-driven supply disruptions. Expand microencapsulation capacity in regional hubs such as Poland and Mexico to capture just-in-time production demand from mid-sized brands previously excluded from bulk contracts. Defend margin position by funding intervention studies that satisfy tightening EFSA health claim substantiation requirements, creating regulatory moats against synthetic substitution threats in premium segments. For New Entrants and Emerging Players: ANVISA's evolving health food regulations in Brazil open a window for lutein ester formulations targeting the country's underpenetrated aging demographic before incumbent suppliers commit procurement volumes. Target China's blue-hat registration pathway under NMPA and SAMR, where extended compliance timelines create first-mover advantages for foreign suppliers navigating regulatory complexity. Pursue direct-to-practitioner channel innovation in Australian and Canadian functional medicine networks, bypassing retail intermediaries for higher-margin clinical-grade distribution. For Investors and Strategic Acquirers: Nutraceutical platform companies are the most active acquirer in this space, seeking clinically validated ingredient portfolios to differentiate against commodity synthetic alternatives. The 5-10 year viability window favors targets with established EFSA-compliant health claims and captive supply arrangements that insulate against raw material volatility. Monitor NMPA blue-hat approval timelines and ANVISA regulatory finalization as inflection indicators for geographic demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Marigold Cultivation | Kemin Industries' multi-continent captive supply secures raw material consistency against Indian monsoon volatility. |
| Microencapsulation Capacity Expansion | Regional beadlet manufacturing in Poland and Mexico compresses minimum order quantities for mid-tier brands. |
| Clinical Validation Investment | Intervention study funding satisfies EFSA's tightening health claim substantiation requirements for German and Italian marketers. |
| Blue-Hat Registration Navigation | NMPA and SAMR approval pathways in China create first-mover positioning for foreign suppliers in vision-health formulations. |
| Direct-to-Practitioner Channel Development | Functional medicine networks in Australia and Canada bypass retail markups for clinical-grade lutein distribution. |
Study Parameters
Bottom-up dietary supplement and functional food modeling reconciled against top-down marigold extraction capacity tracking forms the analytical core of this study. Primary interviews with formulation scientists at leading supplement manufacturers, procurement directors at animal feed compounders, regulatory affairs specialists navigating FDA NDI and EFSA health claim pathways, and extraction facility managers in Indian processing clusters were combined with secondary validation. Data sources include FDA NDI notification filings, EFSA health claim substantiation opinions, FSSAI and CDSCO import quality standards, customs and trade data for carotenoid premix flows, and SEC filings from publicly traded ingredient suppliers.
Historical trendline analysis of procurement volumes across natural and synthetic lutein grades established baseline growth patterns that inform projections across the analysis window. The forecast framework segments by extraction method, delivery format, and end-use specification, with additional modeling of regulatory pathway status and health claim validation level. CAGRs derive from weighted scenario analysis incorporating input cost volatility, substitution elasticity between natural and synthetic grades, and regional regulatory approval timelines. Forecast inputs include marigold harvest yield projections, EFSA opinion issuance cadence, and NMPA blue-hat registration queue depth.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extreme monsoon disruption or accelerated synthetic lutein cost reduction. Practitioners should monitor ANVISA regulatory finalization, NMPA approval velocity, and EFSA health claim opinion issuance for early signals of geographic demand shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Italy Sodium Reduction Ingredients Market
Food Additives and Ingredients
Brazil Food Preservatives Market
Food Additives and Ingredients
China Food Preservatives Market
Food Additives and Ingredients
Low Methoxyl Pectin Market
Food Additives and Ingredients
Flour Whiteners Market
Food Additives and Ingredients
Liquid Caramel Color Market
Food Additives and Ingredients
Japan Feed Additives Market
Food Additives and Ingredients
Australia Food Additives Market
Food Additives and Ingredients
Ammonium Chloride Food Grade Market
Food Additives and Ingredients
Food Protein Ingredient Market
Food Additives and Ingredients
Food Antifoaming Agents Market
Food Additives and Ingredients
North America Dehydrated Onion Market
Food Additives and Ingredients
Cream Emulsifier Market
Food Additives and Ingredients
China Food Enzymes Market
Food Additives and Ingredients
Brazil Food Emulsifiers Market
Food Additives and Ingredients
Egg Wash Substitute Market