
 Baby Formula Ingredients Market | 2026-2036
Baby Formula Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Formula Ingredients Market Insights
EU F-Gas Regulation is consolidating the cost-of-entry calculus for lipid suppliers serving European formula manufacturers. Fonterra Co-operative Group Limited leverages its New Zealand dairy cooperative structure to sustain integrated control over whey protein and milk fat streams. Royal FrieslandCampina N.V. anchors its position through specialized lipid fractionation capabilities that meet infant-grade purity thresholds. Arla Foods amba competes on geographic proximity to Northern European manufacturing clusters with strict cold-chain protocols.
Baby formula ingredients comprise specialized dairy and non-dairy inputs engineered to replicate human milk composition, typically containing protein ratios of 60:40 whey-to-casein, structured triglycerides, and micronutrient premixes meeting Codex Alimentarius standards. Proteins dominate value pools due to functional demands for digestibility and allergen management, while plant-based sourcing is accelerating fastest as manufacturers respond to vegan-formula registrations and sustainability audits. Powder formulation retains manufacturing scale advantages, though ready-to-feed liquid formats command premium positioning in hospital and travel channels.
FDA, EFSA, and China's NMPA each enforce divergent maximum residue limits for pesticides and heavy metals in infant-grade ingredients, forcing suppliers to maintain parallel certification systems. Codex Alimentarius provides harmonization pressure, but national regulators retain authority over novel ingredient approvals like human milk oligosaccharides and specific probiotic strains. Stakeholders must monitor pending EU MDR-style transitions for novel food authorizations and China's evolving GB standards for imported dairy bases.
Market Dynamics
China's NMPA is tightening GB standards for imported dairy bases while domestic brands build captive whey protein supply chains, compressing margin structures for foreign ingredient suppliers serving hospital and retail channels.
Growth Catalysts
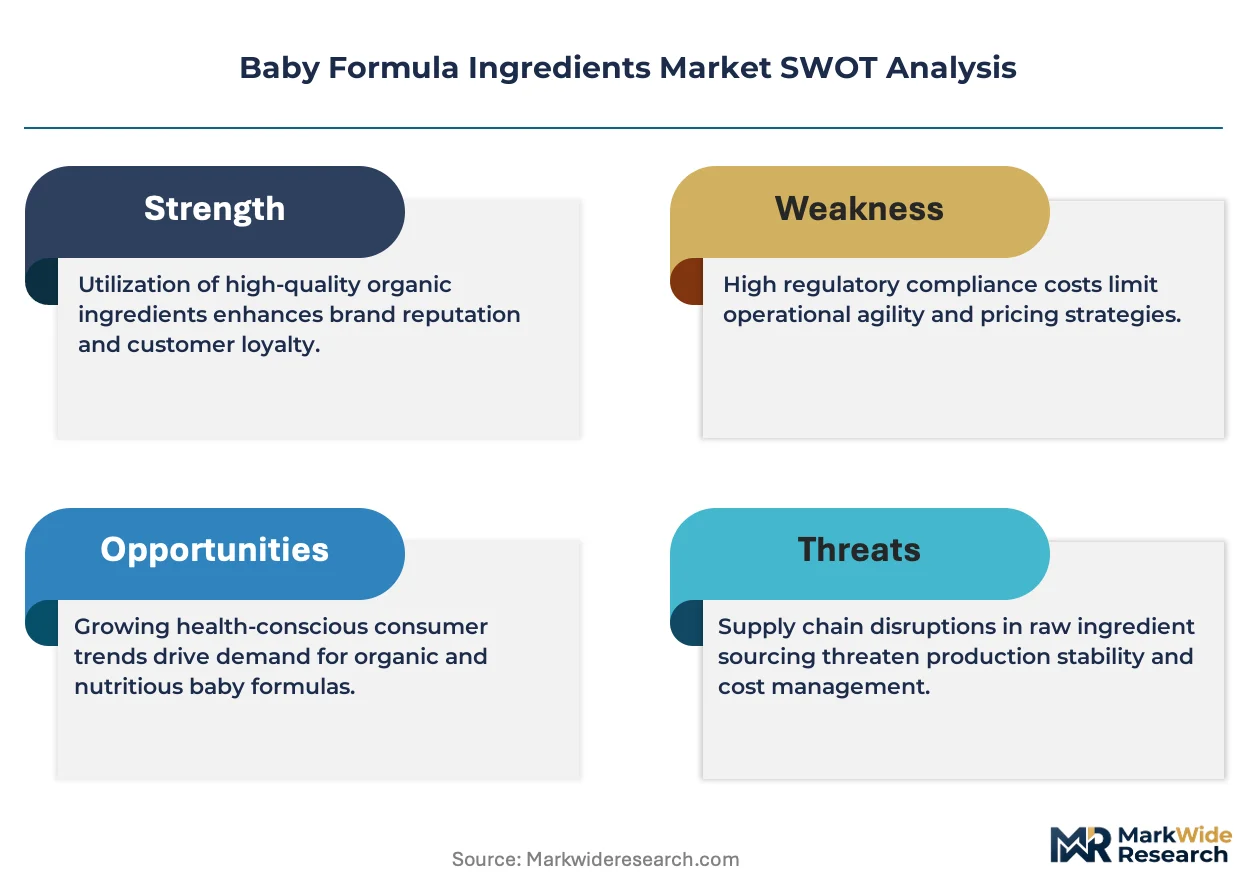
- Specialty formula demand:Pediatric allergists are prescribing hypoallergenic and amino acid-based formulas for infants with cow's milk protein allergy, expanding the addressable patient pool beyond standard nutrition.
- EU F-Gas Regulation:The updated framework on fluorinated greenhouse gases is forcing lipid processors to upgrade cold-chain infrastructure, inadvertently filtering out sub-scale competitors and consolidating qualified supplier pools.
- Precision fermentation:Startups are engineering microbial strains to produce lactoferrin and human milk oligosaccharides without dairy agriculture, attracting venture funding for novel ingredient pipelines.
Market Restraints
- Whey protein supply concentration:New Zealand and EU dairy cooperatives control over 70% of pharmaceutical-grade whey protein isolate, creating single-source vulnerability for Asian formula manufacturers.
- REACH chemical safety compliance:ECHA's evolving substance restrictions on processing aids and residual solvents add 12-18 months to ingredient qualification timelines for European market entry.
- Plant-based protein performance gaps:Pea and rice protein isolates lack the amino acid completeness and digestibility scores of dairy-derived alternatives, limiting substitution in premium infant segments.
Strategic Opportunities
- Sub-Saharan Africa:Underdeveloped formal retail infrastructure and rising birth rates in Nigeria and Kenya create first-mover potential for shelf-stable ready-to-feed liquid formats.
- Human milk oligosaccharide regulatory approvals:EFSA's positive safety opinions on 2'-FL and LNnT are unlocking formula fortification claims that command 15-25% price premiums in EU pharmacy channels.
- Direct-to-hospital procurement:Neonatal intensive care units in Brazil and Mexico are bypassing distributors to contract directly with ingredient suppliers for metabolic disorder formulas.
Industry Challenges
- Clinical trial recruitment:Infant nutrition studies require extended follow-up periods and stringent ethics board approvals, stretching R&D timelines to 4-7 years for novel ingredient substantiation.
- Cross-border cold chain integrity:Maintaining lipid oxidation thresholds below 0.5% peroxide value across multi-modal shipping from New Zealand to Shanghai demands redundant temperature monitoring infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Formula Ingredients Market |
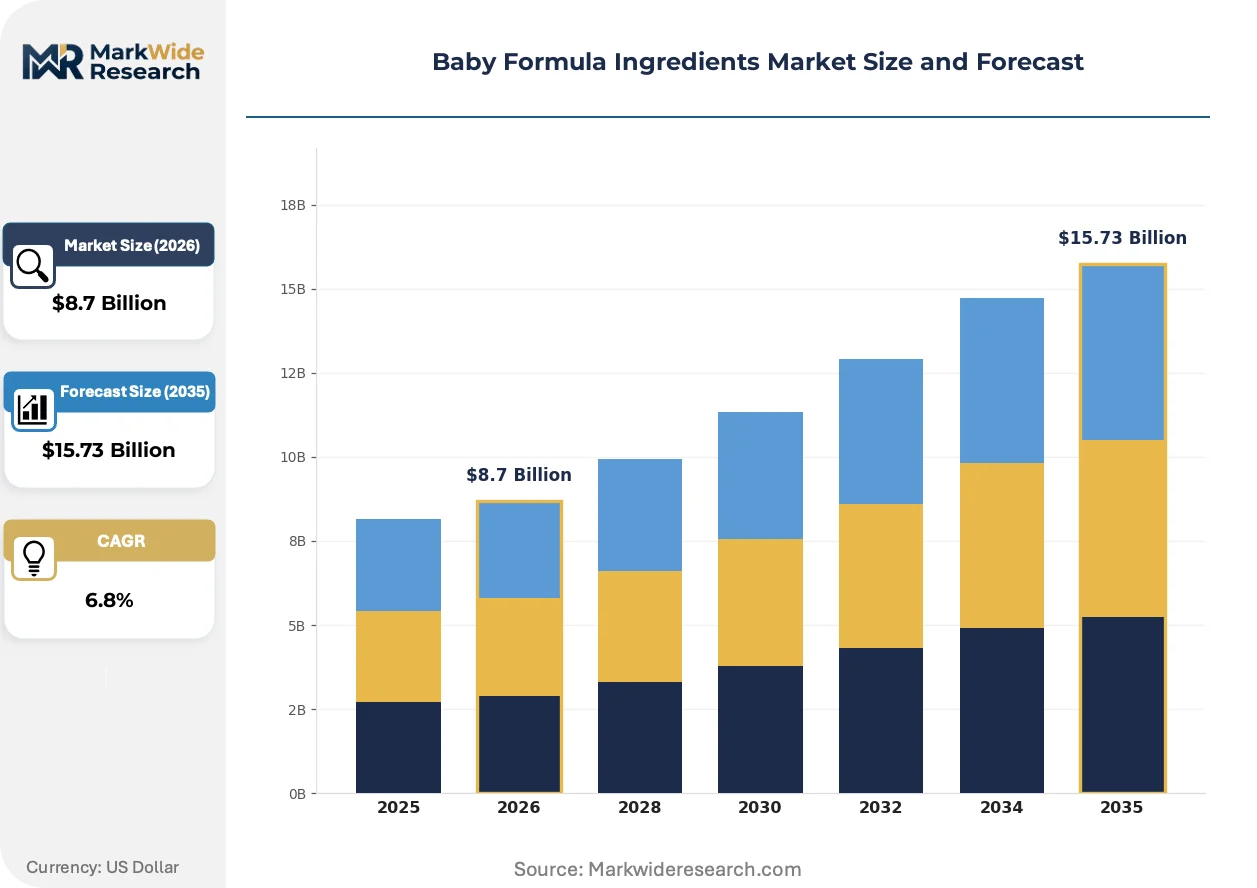
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Proteins, Carbohydrates, Fats, Vitamins Formulation Type: Powder, Liquid, Ready-To-Feed, Concentrated Source: Animal-Based, Plant-Based, Synthetic, Organic Application: Infant Formula, Follow-On Formula, Specialty Formula, Toddler Nutritional |
| Companies Covered | Fonterra Co-operative Group Limited, AAK AB, Royal FrieslandCampina N.V., Arla Foods amba, Glanbia plc, Carbery Food Ingredients Limited, Sachsenmilch Leppersdorf GmbH, Chr. Hansen Holdings A/S, Koninklijke DSM N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Formula Ingredients Market Trends and Innovations
Ingredient sourcing is pivoting from commodity dairy procurement to biotechnology-enabled precision manufacturing, with regulatory science and clinical validation becoming the primary competitive moats rather than scale alone.
Membrane filtration technology is consolidating control over protein fractionation quality. European and Oceania suppliers are deploying ceramic microfiltration and nanofiltration systems to achieve 99.5% purity in whey protein isolate streams. Hospital-grade formula manufacturers in Germany and the Netherlands are consolidating supplier relationships around these certified streams, compressing the viable vendor base to those with capital-intensive filtration assets.
REACH chemical safety standards are tightening residual solvent thresholds for lipid extraction processes. The European Chemicals Agency's 2023 updates on processing aid restrictions have forced palm and coconut oil fractionators to retrofit hexane-free extraction lines. Specialty formula producers targeting EU organic certifications are responding by dual-qualifying suppliers with both REACH compliance and ECOCERT organic processing credentials.
Buyer concentration among Chinese domestic brands is reshaping procurement contracting structures. Feihe, Yili, and Beingmate are consolidating 60% of national volume and demanding multi-year supply agreements with fixed-price clauses for whey protein and lactose derivatives. New Zealand dairy cooperatives are responding by embedding technical service teams in Beijing and Guangzhou to defend long-term contract positions against emerging Australian competitors.
Baby Formula Ingredients Market Segmentation
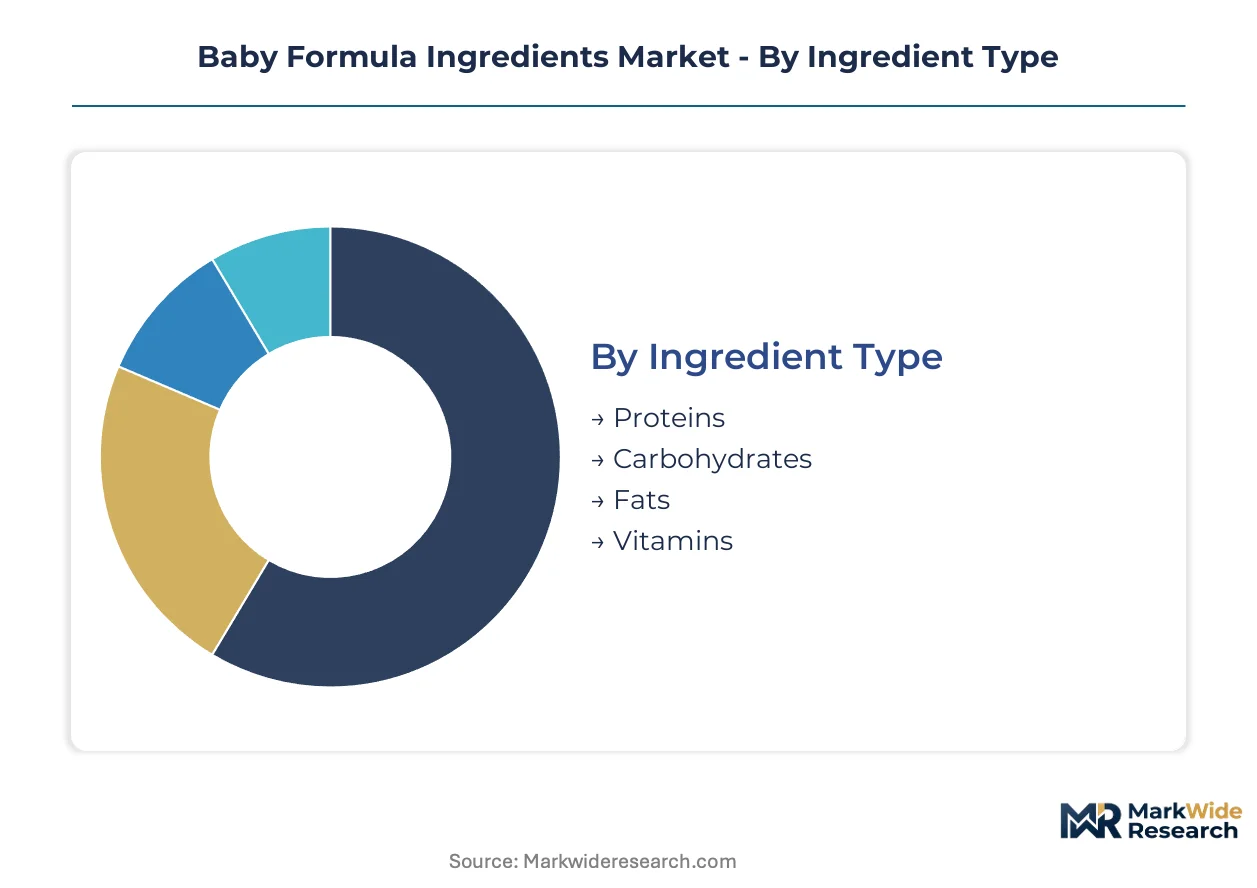
Ingredient differentiation in baby formula determines regulatory pathway complexity, manufacturing capital requirements, and end-use pricing power. Buyers segment procurement strategies across protein functionality, formulation convenience, sourcing ethics, and pediatric application specificity.
Ingredient Type:
Protein buyers prioritize digestibility scores and allergen profiles; carbohydrate and fat purchasers optimize for human milk composition matching.
- Proteins:Whey protein isolates and hydrolysates dominate formulation value due to 60:40 whey-to-casein ratio requirements mimicking breast milk. Demand concentrates in hypoallergenic and amino acid-based specialty formulas for infants with cow's milk protein allergy, where pharmaceutical-grade purity thresholds filter supplier pools.
- Carbohydrates:Lactose and lactose derivatives constitute the primary energy substrate, with human milk oligosaccharides commanding premium positioning in EU pharmacy channels following EFSA safety approvals. Procurement is tilting toward suppliers with dual organic and infant-grade certifications.
- Fats:Structured triglycerides and lipid fractions replicate human milk fat absorption kinetics; EU F-Gas Regulation compliance is consolidating qualified supplier bases for cold-chain-dependent lipid streams.
- Vitamins:Micronutrient premixes meeting Codex Alimentarius standards require batch-level certification against divergent FDA, EFSA, and NMPA maximum residue limits.
Volume sits with Proteins; growth tilts toward Carbohydrates.
Formulation Type:
Manufacturing scale economies separate powder producers from liquid specialists serving convenience-driven and clinical channels.
- Powder:Retains cost and shelf-stability advantages for mass-market retail distribution, with spray-drying infrastructure concentrated among New Zealand and EU dairy cooperatives controlling whey protein isolate supply.
- Liquid:Requires aseptic filling lines and refrigerated distribution, limiting viable production to manufacturers with hospital and pharmacy channel relationships in Germany and the Netherlands.
- Ready-To-Feed:Commands premium positioning in neonatal intensive care units and travel retail; direct-to-hospital procurement in Brazil and Mexico is bypassing traditional distributor networks.
- Concentrated:Targets cost-conscious consumers with dilution flexibility; shelf-stable formats show first-mover potential in Nigeria and Kenya where formal retail infrastructure remains underdeveloped.
Powder captures volume leadership; ready-to-feed liquid climbs the fastest on clinical channel expansion.
Source:
Sustainability auditing and vegan-formula registrations are accelerating procurement shifts away from conventional dairy agriculture.
- Animal-Based:Whey protein and milk fat fractions from dairy cooperatives retain performance benchmarks for digestibility and amino acid completeness; REACH chemical safety compliance adds qualification timeline burdens for European market entry.
- Plant-Based:Pea and rice protein isolates face digestibility score gaps versus dairy alternatives, constraining penetration in premium infant segments despite sustainability credentials.
- Synthetic:Precision fermentation-derived lactoferrin and human milk oligosaccharides bypass agricultural supply chains, attracting venture funding for novel ingredient pipelines.
- Organic:ECOCERT processing credentials and dual REACH compliance are becoming mandatory for EU organic certification targeting; hexane-free extraction retrofits are filtering palm and coconut oil fractionators.
Animal-based sourcing retains volume dominance; synthetic production gains share fastest on biotechnology investment cycles.
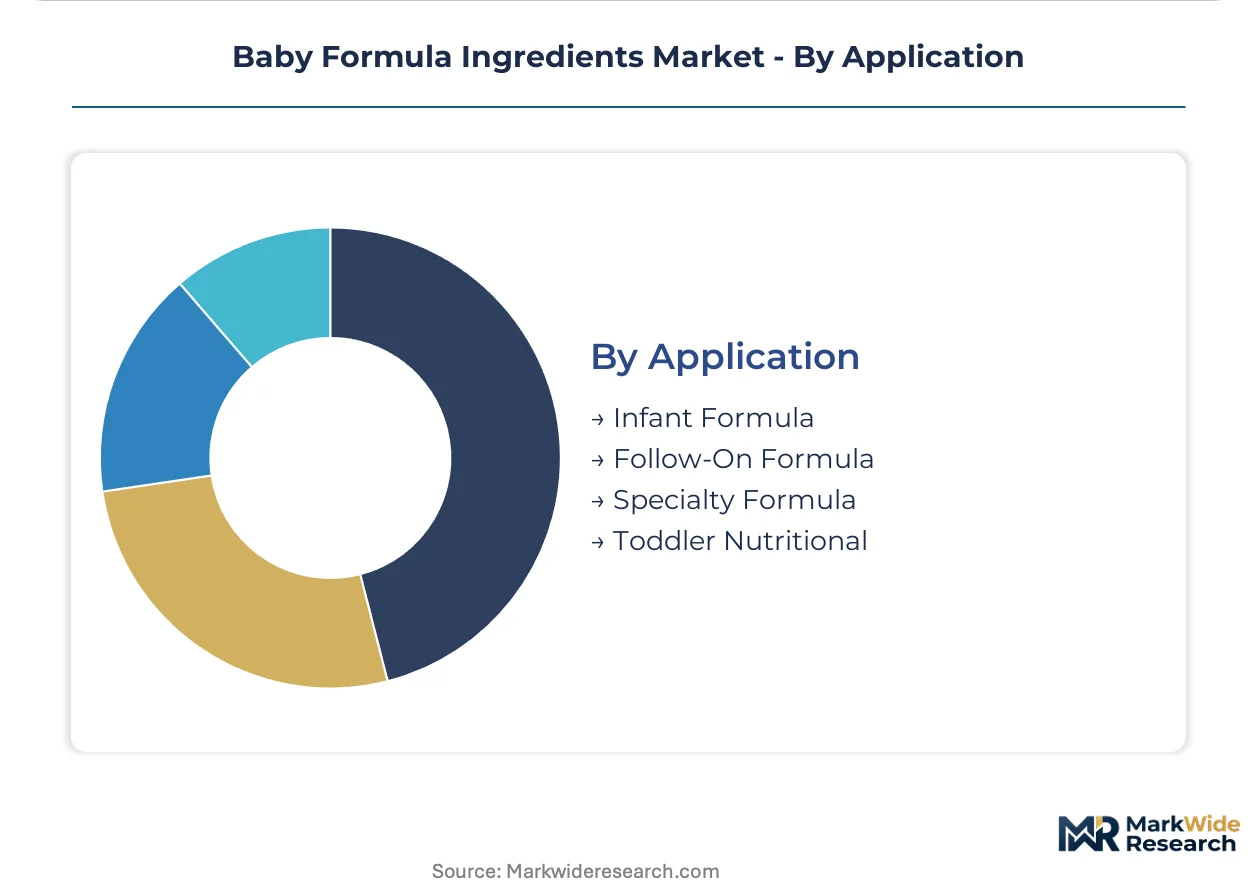
Application:
Clinical indication specificity determines regulatory scrutiny intensity and reimbursement pathway availability.
- Infant Formula:Standard nutrition for 0-6 month cohorts faces intense Codex Alimentarius harmonization pressure alongside persistent national divergence in pesticide and heavy metal maximum residue limits.
- Follow-On Formula:6-12 month transition products compete on brand trust and pediatrician recommendation networks in China where domestic brands Feihe, Yili, and Beingmate consolidate procurement volume.
- Specialty Formula:Hypoallergenic, metabolic disorder, and premature infant formulations expand the addressable patient pool beyond standard nutrition; clinical trial recruitment stretching 4-7 years creates R&D timeline barriers.
- Toddler Nutritional:Positioned outside strict infant-grade regulatory frameworks, allowing faster ingredient innovation cycles but compressing margin structures versus pharmaceutical-grade segments.
Infant formula anchors volume; specialty formula shows steepest expansion trajectory on pediatric allergist prescribing patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates procurement volume among domestic brands building captive whey protein supply chains, while European lipid processors face F-Gas Regulation compliance costs that filter sub-scale competitors from qualified supplier pools.
China
Feihe, Yili, and Beingmate consolidate 60% of national formula volume and demand multi-year supply agreements with fixed-price clauses for whey protein and lactose derivatives. NMPA's tightening GB standards for imported dairy bases compress margin structures for foreign ingredient suppliers. Technical service teams from New Zealand dairy cooperatives embed in Beijing and Guangzhou to defend long-term contract positions.
Germany
Hospital-grade formula manufacturers in Germany consolidate supplier relationships around membrane filtration-certified whey protein isolate streams. ECHA's REACH chemical safety updates on residual solvent thresholds force palm and coconut oil fractionators to retrofit hexane-free extraction lines. Bavaria-based neonatal nutrition specialists source directly from ceramic microfiltration-equipped processors in the Netherlands.
New Zealand
Dairy cooperatives control over 70% of pharmaceutical-grade whey protein isolate supply to Asian formula manufacturers. Fonterra leverages its cooperative structure to sustain integrated control over whey protein and milk fat streams. Canterbury-based spray-drying infrastructure anchors powder formulation scale advantages for mass-market retail distribution.
Netherlands
Royal FrieslandCampina anchors its position through specialized lipid fractionation capabilities that meet infant-grade purity thresholds. FrieslandCampina's specialized fractionation assets serve hospital and pharmacy channels requiring refrigerated liquid distribution. Rotterdam-Antwerp corridor cold-chain infrastructure maintains lipid oxidation thresholds below 0.5% peroxide value for EU-wide distribution.
Brazil
Neonatal intensive care units in São Paulo and Rio de Janeiro bypass distributors to contract directly with ingredient suppliers for metabolic disorder formulas. ANVISA's pediatric nutrition regulations create extended qualification timelines for novel ingredient approvals. Direct-to-hospital procurement patterns concentrate demand among specialty formula producers with local technical service presence.
Baby Formula Ingredients Market Competitive Landscape
Oceania dairy cooperatives anchor one tier; European lipid specialists and biotechnology innovators hold differentiated positions on regulatory compliance and novel ingredient pipelines. Market structure tilts toward consolidated supply bases where membrane filtration assets and cold-chain infrastructure create capital barriers to entry. Three archetypes dominate: integrated dairy cooperatives controlling upstream whey streams, specialized lipid fractionators with pharmaceutical-grade certifications, and precision fermentation startups engineering microbial production of human milk oligosaccharides. Competitive moves concentrate on backward integration into captive protein supply and multi-year procurement contracting with fixed-price mechanisms.
Within the integrated cooperative tier, Fonterra Co-operative Group Limited and Royal FrieslandCampina N.V. exemplify structures that combine upstream dairy control with downstream pharmaceutical-grade processing capabilities. Arla Foods amba occupies a position emphasizing geographic proximity to Northern European manufacturing clusters with strict cold-chain protocols. Among biotechnology specialists, Chr. Hansen Holdings A/S and Koninklijke DSM N.V. represent the precision fermentation archetype targeting novel ingredient categories outside conventional dairy agriculture. These named entities serve as anchors for understanding how competitive positioning stratifies across scale, regulatory compliance depth, and technology platform maturity.
| Leading Market Players |
|---|
| Fonterra Co-operative Group Limited |
| AAK AB |
| Royal FrieslandCampina N.V. |
| Arla Foods amba |
| Glanbia plc |
| Carbery Food Ingredients Limited |
| Sachsenmilch Leppersdorf GmbH |
| Chr. Hansen Holdings A/S |
| Koninklijke DSM N.V. |
| Others |
Pricing and Supply Chain Analysis
Captive whey protein supply chains anchor both procurement security and pricing power for Chinese domestic brands, compressing margin structures for foreign suppliers serving hospital and retail channels. New Zealand dairy cooperatives leverage backward integration into spray-drying infrastructure to defend long-term contract positions against emerging Australian competitors.
Pricing Analysis
Volume concentrates in standard infant-grade whey protein isolates where Fonterra and FrieslandCampina compete on scale, while margins expand fastest in specialty hypoallergenic and amino acid-based formulas. Price differentiation rests on pharmaceutical-grade purity thresholds and EFSA safety certifications for human milk oligosaccharides. Pricing pressure stems from Feihe, Yili, and Beingmate demanding multi-year fixed-price clauses. Hospital-grade manufacturers show least price sensitivity; mass-market powder buyers in Nigeria and Kenya exhibit highest sensitivity.
Supply Chain Analysis
Direct-to-hospital channels handle metabolic disorder formula demand in São Paulo and Rio de Janeiro, bypassing traditional distributor networks. Raw material flows draw from New Zealand whey streams, EU lipid fractionators, and precision fermentation bioreactors. Single-source vulnerability concentrates in pharmaceutical-grade whey protein isolate, where Oceania cooperatives control over seventy percent of Asian supply. Distribution runs through cold-chain corridors from Rotterdam-Antwerp to Shanghai, maintaining lipid oxidation thresholds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The baby formula ingredients market functions as a cost-of-compliance story where ECHA's REACH chemical safety updates create twelve-to-eighteen-month qualification barriers that filter sub-scale competitors and entrench membrane filtration-equipped incumbents.
For Market Incumbents: Deploy membrane filtration asset expansion to capture hospital-grade certification requirements in Germany and the Netherlands. Precision fermentation startups threaten novel ingredient categories; counter by embedding technical service teams in Beijing and Guangzhou to defend multi-year contract positions. Prioritize hexane-free extraction retrofits to maintain EU organic certification access.
For New Entrants and Emerging Players: Enter via shelf-stable ready-to-feed liquid formats targeting Nigeria and Kenya where formal retail infrastructure remains underdeveloped. Sub-Saharan Africa offers lowest competitive density for neonatal intensive care unit procurement. Pursue direct-to-hospital contracting models bypassing distributor networks in Brazil and Mexico.
For Investors and Strategic Acquirers: Exit pathways concentrate in biotechnology specialists with EFSA-positive safety opinions for human milk oligosaccharides. Long-term viability favors precision fermentation platforms over conventional dairy agriculture given sustainability audit pressures. Monitor EFSA novel food authorization timelines as inflection indicator for premium pricing capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Certification | Hospital-grade formula manufacturers in Germany consolidate supplier relationships around 99.5% purity whey streams. |
| Hexane-Free Extraction Retrofit | Palm and coconut oil fractionators achieve ECOCERT organic credentials for EU specialty formula producers. |
| Precision Fermentation Scale-Up | Microbial strain engineering bypasses agricultural supply chains for lactoferrin and human milk oligosaccharides. |
| Direct-to-Hospital Procurement | Brazilian neonatal intensive care units contract directly with metabolic disorder formula ingredient suppliers. |
| Technical Service Embedding | New Zealand cooperatives station teams in Beijing and Guangzhou to defend fixed-price contract positions. |
Research Methodology
Multi-period observation of NMPA GB standard revisions, EFSA novel food authorization timelines, and REACH chemical safety updates anchored the trend analysis, supplemented by interviews with dairy cooperative procurement directors, infant formula brand managers, neonatal nutrition specialists, and lipid fractionation plant managers. Secondary validation drew from Codex Alimentarius standards documentation, ECHA substance restriction databases, Chinese customs trade records, and hospital procurement databases. Bottom-up ingredient demand modeling triangulated against top-down formula manufacturer revenue analysis.
Segment-weighting across ingredient type, formulation format, sourcing origin, and pediatric application specificity structured the analytical framework. CAGRs derived from regression analysis of historical procurement volumes against birth rate projections and regulatory approval timelines. Human milk oligosaccharide regulatory pathway modeling and whey protein supply concentration indices served as industry-specific forecast inputs across the projection horizon.
Revisions become necessary when EFSA delays novel food safety opinions, NMPA accelerates GB standard tightening, or precision fermentation platforms achieve cost parity with dairy-derived alternatives. Forecasts reflect documented assumptions on regulatory approval timelines and supply chain concentration stability. Practitioners should monitor ECHA processing aid restriction updates and Chinese domestic brand captive supply chain buildouts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Global DHA Algae Oil for Infant Formula Market
Baby Food and Infant Formula
Infant Formula Ingredients Market
Baby Food and Infant Formula
Middle East and Africa Baby Food Market
Baby Food and Infant Formula
Pet Milk Replacers Market
Baby Food and Infant Formula
Vietnam Pet Food Market
Baby Food and Infant Formula
Omega 3 Ingredients for Infant Food Market
Baby Food and Infant Formula
Organic Infant Formula Market
Baby Food and Infant Formula
India Baby Food Market
Baby Food and Infant Formula
Human Milk Oligosaccharides in Infant Formula Market
Baby Food and Infant Formula
Functional Milk Replacers Market
Baby Food and Infant Formula
Baby Formula Market
Baby Food and Infant Formula
North America Baby Food Market
Baby Food and Infant Formula
Pureed Food Market
Baby Food and Infant Formula
Russia Pet Food Market
Baby Food and Infant Formula
Baby Infant Formula Market
Baby Food and Infant Formula
Follow on Formula Milk Market