
 Selenium Yeast Market | 2026-2036
Selenium Yeast Market Size, Share, and Industry Trends Forecast 2026-2036
Selenium Yeast Market Analysis
Subscription-based technical advisory for feed formulation is restructuring how selenium yeast suppliers capture recurring revenue. Alltech Inc leverages its global nutritional consulting network to embed yeast-derived selenium into long-term herd health contracts. Lesaffre Group anchors its position through captive biotechnology research and controlled-strain fermentation capacity. Lallemand Inc competes by specializing in live yeast and yeast derivative portfolios that extend into rumen-specific selenium delivery systems.
Selenium yeast comprises Saccharomyces cerevisiae biomass cultivated in selenium-enriched media, where inorganic selenium converts to protein-bound selenomethionine and selenocysteine, achieving bioavailability superior to sodium selenite in monogastric and ruminant species. Its primary commercial purpose centers on delivering standardized organic selenium for animal nutrition, human dietary supplementation, and functional food fortification. Feed Additives within product type segmentation dominate volume flows, while Supplement Formulations command premium positioning through pharmaceutical-grade purification and capsule/tablet delivery. Among applications, Livestock Nutrition sustains the largest installed demand base, though Dietary Supplements for human consumers represent the fastest-growing margin pool as preventive health spending redirects toward trace mineral interventions.
The European Food Safety Authority (EFSA) evaluates and authorizes selenium yeast as a feed additive under Regulation (EC) No 1831/2003, while the U.S. Food and Drug Administration (FDA) exercises oversight through Generally Recognized as Safe (GRAS) notifications and feed ingredient definitions; China's National Health Commission (NHC) and Ministry of Agriculture and Rural Affairs (MARA) jointly administer novel food and feed additive approvals for selenium yeast imports and domestic production. These layered regulatory frameworks elevate compliance costs for new entrants but simultaneously protect incumbent suppliers with established dossiers and analytical validation protocols. Stakeholders must monitor evolving maximum permitted levels for selenium in complete feeds across jurisdictions, as regulatory tightening in one geography typically cascades into revised specifications for export-oriented supply chains.
Market Dynamics
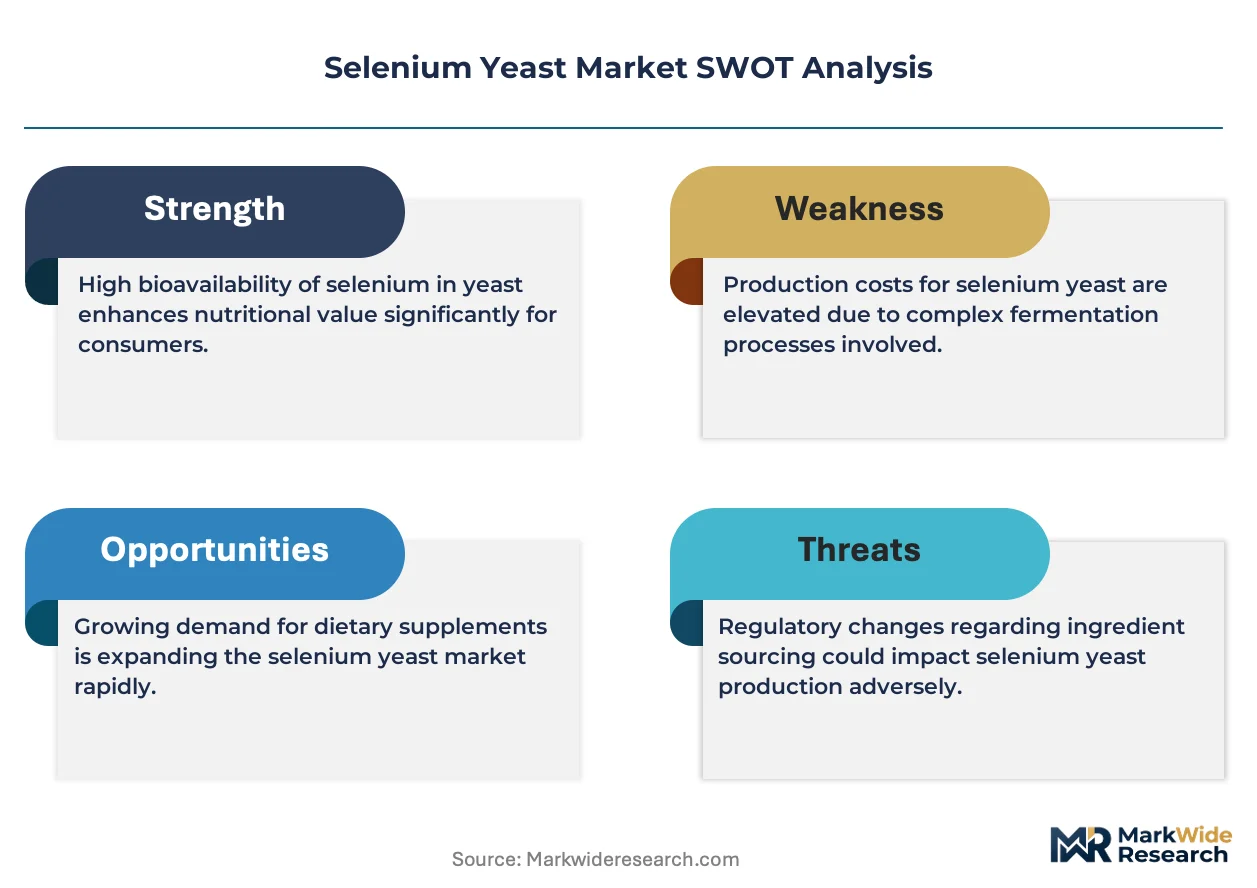
EFSA's tightening feed additive authorizations are compressing supplier margins while elevating analytical validation requirements, forcing selenium yeast producers to recalibrate quality assurance protocols and dossier maintenance costs.
Growth Catalysts
- EFSA Regulation (EC) No 1831/2003 updates:Stricter organic selenium source benchmarks in Denmark and the Netherlands are accelerating herd health contract renewals with premium yeast suppliers.
- Rumen-specific delivery systems:Live yeast derivative portfolios are penetrating dairy operations seeking enhanced bioavailability in high-producing Holstein herds.
- Integrated pork operations:Trace mineral optimization programs in North American finishing facilities are standardizing selenomethionine inclusion rates above sodium selenite baselines.
Market Restraints
- Strain cultivation concentration:Controlled-strain fermentation capacity remains captive to three biotechnology groups, limiting spot market liquidity.
- Sodium selenite substitution:Inorganic selenium persists in price-sensitive poultry layer operations despite inferior bioavailability metrics.
- Dual carbon compliance costs:China's MEE environmental discharge standards are elevating energy recovery investments for fermentation facilities.
Strategic Opportunities
- Human supplement channel expansion:Pharmaceutical-grade purification capacity is capturing preventive health spending redirection toward trace mineral capsules.
- ISO 22000 certification gaps:Mid-tier feed compounders in Poland and Romania present unconsolidated demand for validated organic selenium sourcing.
- Precision livestock convergence:Sensor-enabled mineral intake monitoring is integrating with automated feed dispensing in Dutch dairy cooperatives.
Industry Challenges
- Analytical method standardization:Protein-bound selenomethionine quantification protocols vary across EFSA, FDA, and China's MARA jurisdictions, complicating multi-territory dossier submissions.
- Fermentation scale-up capex:GMP-compliant biomass expansion requires dedicated bioreactor trains with 18-24 month commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Selenium Yeast Market |
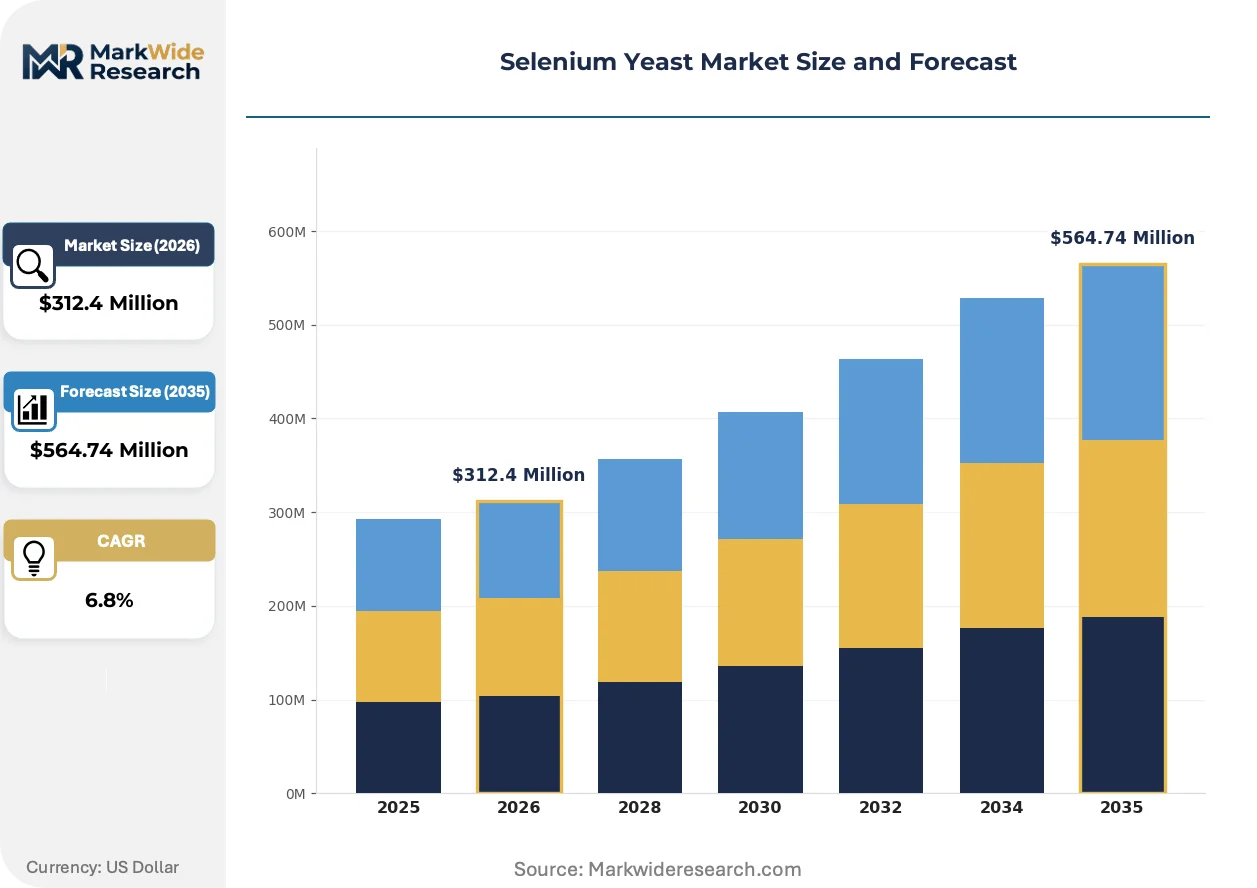
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Yeast, Inactive Yeast, Supplement Formulations, Feed Additives End User: Food Industry, Animal Feed Producers, Nutraceutical Manufacturers, Pharmaceuticals Application: Dietary Supplements, Functional Foods, Livestock Nutrition, Cosmetics Sales Channel: Online Retailers, Specialty Stores, Distributors, Direct Sales |
| Companies Covered | Alltech Inc, Angel Yeast Co., Ltd., Archer Daniels Midland Company, Lallemand Inc., Lesaffre Group, Biorigin, Pharma Nord Inc., Novus International, Inc., Cypress Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Selenium Yeast Market Emerging Trajectories
Biotechnology advancement and regulatory harmonization pressures are restructuring how selenium yeast suppliers differentiate through analytical validation depth and delivery system specialization rather than commodity volume positioning.
Continuous fermentation monitoring via Raman spectroscopy is integrating real-time selenomethionine yield optimization into Saccharomyces cerevisiae cultivation protocols. Danish biotechnology facilities are adopting these systems to compress batch-to-batch variability below 5% coefficient of variation. The technology is integrating quality assurance directly into production workflows, reducing post-harvest analytical rejection rates.
REACH substance evaluation under ECHA's 2023-2025 work program is extending scrutiny to selenium yeast processing aids and residual media components. Industrial consequence includes mandatory extended one-generation reproductive toxicity studies for novel strain variants. Human dietary supplement manufacturers importing into the European Union are accelerating pre-submission dossier preparation to avoid authorization gaps.
Subscription-based technical advisory is displacing transactional ingredient sales in North American livestock nutrition. Alltech's global consulting network embeds selenium yeast into multi-year herd health contracts with guaranteed performance benchmarks. This procurement evolution is most visible in upper Midwest dairy cooperatives where nutritionist access is bundled with mineral premix supply.
Selenium Yeast Market Segmentation
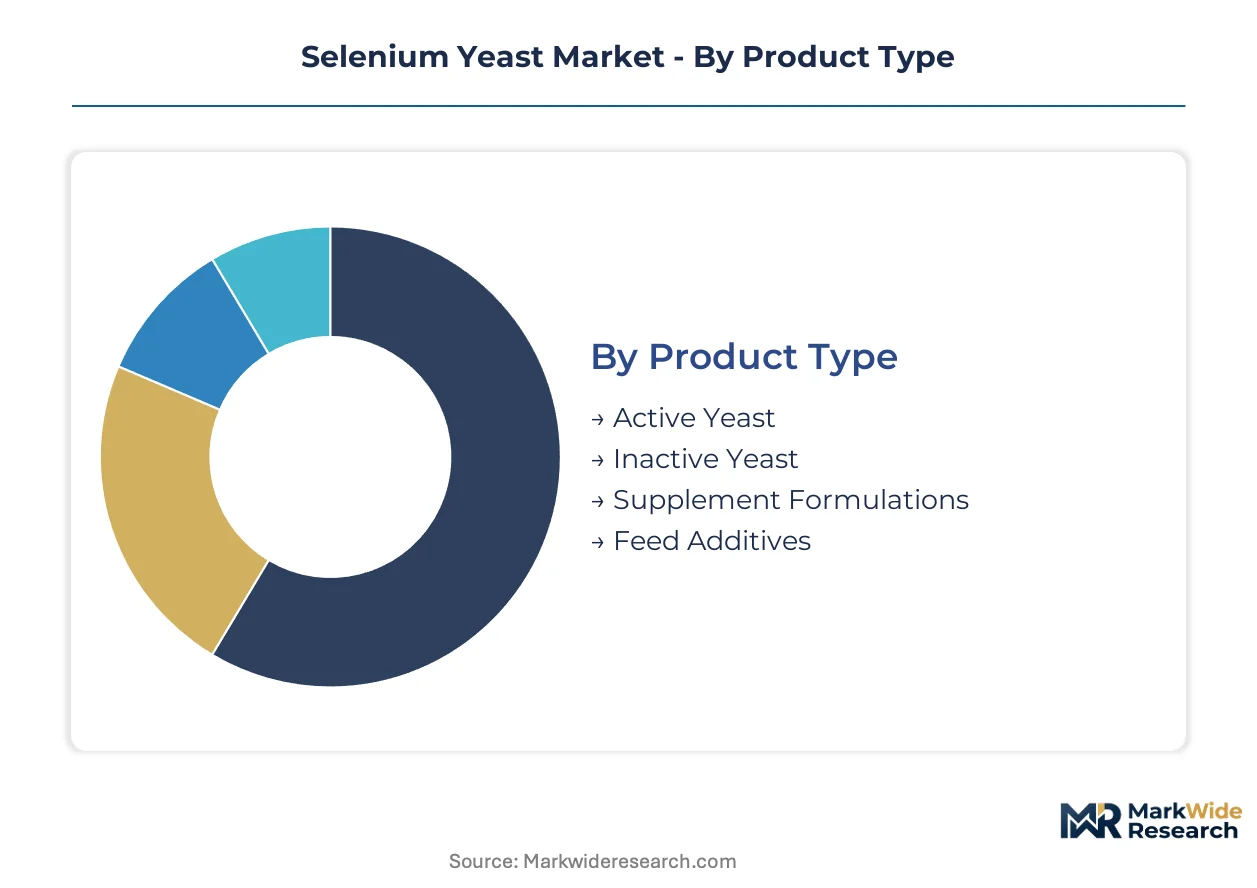
Selenium yeast procurement patterns diverge sharply across product formats and end-use specifications. Buyers prioritize bioavailability certification in feed applications while human supplement channels demand pharmaceutical-grade purity documentation.
Product Type:
Cost tier differentiation separates commodity biomass from value-added formulations with validated selenomethionine content.
- Feed Additives:Standardized Saccharomyces cerevisiae biomass with protein-bound selenomethionine concentrations optimized for monogastric and ruminant absorption. Demand concentrates in Danish and Dutch integrated pork and dairy operations where EFSA organic selenium benchmarks have tightened feed formulation specifications.
- Supplement Formulations:Pharmaceutical-grade purification achieves capsule and tablet delivery with residual heavy metal controls below pharmacopeial limits. Preventive health spending redirection in North American and European consumer markets is accelerating margin capture through direct-to-practitioner distribution.
- Active Yeast:Live cell preparations requiring cold chain integrity for viability maintenance in rumen-specific delivery systems.
- Inactive Yeast:Heat-inactivated biomass with extended shelf stability for premix manufacturing and dry feed compounding.
Feed Additives leads on scale; Supplement Formulations leads on momentum.
End User:
Application maturity determines whether buyers accept generic biomass or demand batch-specific analytical certificates.
- Animal Feed Producers:Volume purchasers integrating selenium yeast into trace mineral premixes for livestock finishing facilities. North American operations are standardizing selenomethionine inclusion rates above sodium selenite baselines in swine nutrition programs.
- Nutraceutical Manufacturers:Formulators requiring ISO 22000 certification and third-party selenomethionine quantification for capsule and tablet production. Human dietary supplement channels are expanding most quickly as preventive health spending redirects toward trace mineral interventions.
- Food Industry:Functional food fortification applications with regulatory constraints on maximum selenium levels in finished consumer products.
- Pharmaceuticals:Prescription and over-the-counter formulations demanding GMP compliance with extended stability documentation.
Animal Feed Producers commands installed volume; Nutraceutical Manufacturers shows steepest expansion trajectory.
Application:
Volume concentration versus margin extraction defines strategic positioning across consumption contexts.
- Livestock Nutrition:The largest installed demand base spanning dairy, beef, swine, and poultry operations with species-specific bioavailability requirements. Danish biotechnology facilities are adopting Raman spectroscopy monitoring to compress batch-to-batch variability below 5% coefficient of variation for contract supply agreements.
- Dietary Supplements:Human consumption formats with premium positioning through pharmaceutical-grade purification and capsule delivery systems. Preventive health spending redirection is gaining share fastest in direct-to-consumer and practitioner-dispensed channels.
- Functional Foods:Bread, dairy, and beverage fortification with regulatory maximum limits constraining formulation flexibility.
- Cosmetics:Topical applications leveraging selenium antioxidant properties with emerging demand in premium skincare formulations.
Livestock Nutrition anchors revenue stability; Dietary Supplements drives margin expansion.
Sales Channel:
Procurement relationship depth determines whether transactions remain spot-market or convert to recurring technical advisory contracts.
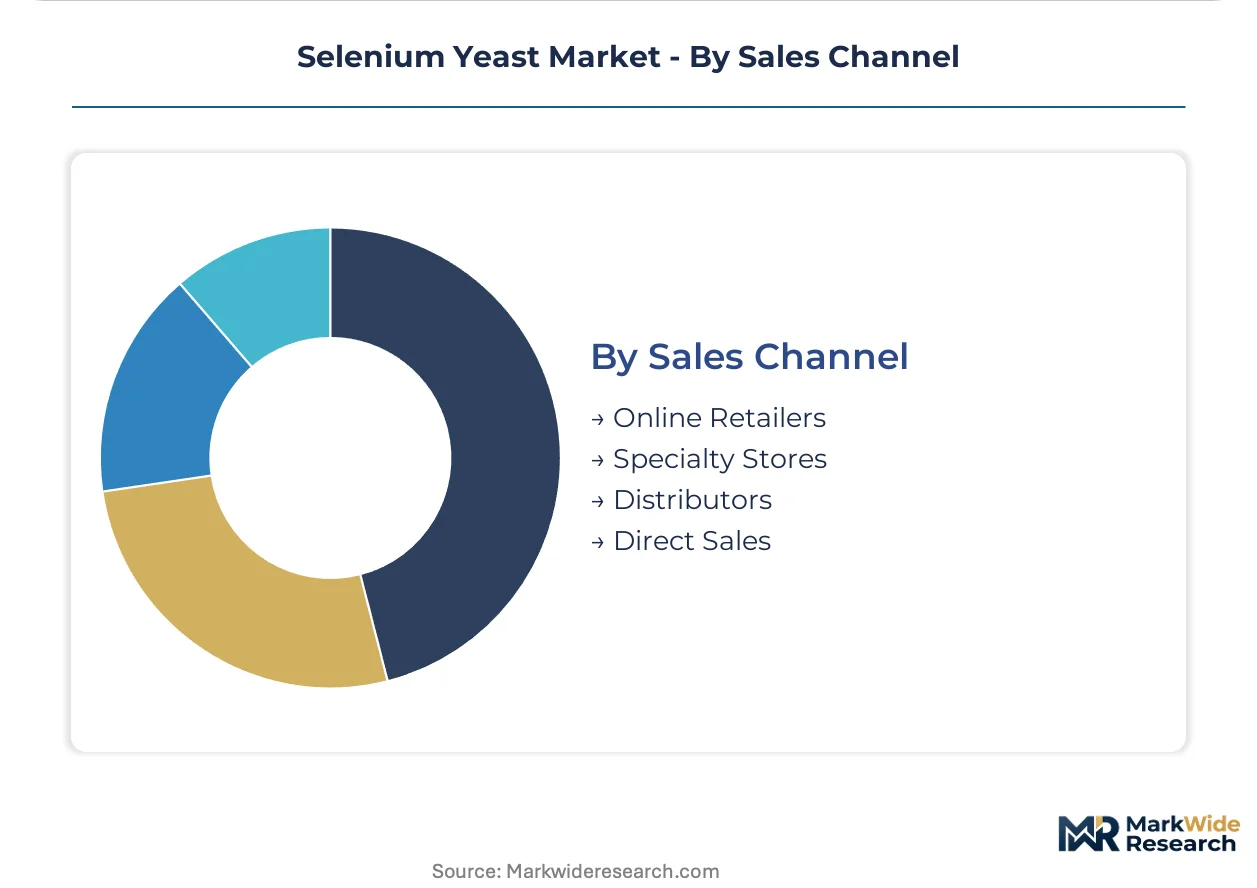
- Distributors:Intermediate stocking points serving mid-tier feed compounders with consolidated mineral premix procurement. Polish and Romanian compounders present unconsolidated demand for validated organic selenium sourcing through regional distribution networks.
- Direct Sales:Multi-year herd health contracts with embedded nutritionist access and guaranteed performance benchmarks. Upper Midwest dairy cooperatives are displacing transactional ingredient sales with subscription-based technical advisory models.
- Online Retailers:Human supplement channels with consumer-facing branding and direct-to-door delivery logistics.
- Specialty Stores:Practitioner-focused and health food retail with educated staff consultation requirements.
Distributors maintains broadest reach; Direct Sales deepens per-account revenue capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denmark and the Netherlands have tightened organic selenium benchmarks faster than North American regulators, creating divergent compliance timelines for multinational feed compounders operating across both jurisdictions.
United States
Integrated pork finishing facilities in Iowa and North Carolina are standardizing selenomethionine inclusion rates above sodium selenite baselines. FDA oversight through GRAS notifications maintains ingredient definition flexibility. Upper Midwest dairy cooperatives in Wisconsin and Minnesota are converting to subscription-based technical advisory contracts with embedded nutritionist access.
Denmark
Integrated pork and dairy operations prioritize trace mineral bioavailability in herd health optimization programs. EFSA Regulation (EC) No 1831/2003 updates have accelerated contract renewals with premium yeast suppliers. Danish biotechnology facilities in the Copenhagen region are adopting Raman spectroscopy monitoring to compress batch-to-batch variability below 5% coefficient of variation.
Netherlands
Sensor-enabled mineral intake monitoring is integrating with automated feed dispensing in Dutch dairy cooperatives. EFSA's tightening feed additive authorizations are compressing supplier margins while elevating analytical validation requirements. The Gelderland and Overijssel provinces concentrate precision livestock farming infrastructure for high-producing Holstein herds.
China
Dual carbon compliance costs under MEE environmental discharge standards are elevating energy recovery investments for fermentation facilities. NHC and MARA jointly administer novel food and feed additive approvals for selenium yeast imports and domestic production. Shandong and Jiangsu provinces host the principal controlled-strain fermentation capacity serving Asian markets.
Germany
REACH substance evaluation under ECHA's 2023-2025 work program is extending scrutiny to selenium yeast processing aids and residual media components. Extended one-generation reproductive toxicity studies are becoming mandatory for novel strain variants. Bavarian and North Rhine-Westphalian feed compounders are accelerating pre-submission dossier preparation to avoid authorization gaps.
Selenium Yeast Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with biotechnology groups controlling captive fermentation capacity while regional distributors serve spot-market demand. Three biotechnology conglomerates anchor supply through controlled-strain Saccharomyces cerevisiae cultivation. The market structure favors incumbents with established EFSA, FDA, and MARA dossiers. Dominant competitive moves include strategic partnerships for Raman spectroscopy integration and geographic expansion through ISO 22000 certification acquisition in Eastern European markets.
Within the biotechnology tier, Alltech Inc, Lesaffre Group, and Lallemand Inc exemplify divergent positioning archetypes. Alltech leverages its global nutritional consulting network to embed yeast-derived selenium into long-term herd health contracts. Lesaffre anchors its position through captive biotechnology research and controlled-strain fermentation capacity. Lallemand competes by specializing in live yeast and yeast derivative portfolios. These three represent the principal strategic archetypes: advisory-embedded supply, captive manufacturing scale, and delivery system specialization.
| Leading Market Players |
|---|
| Alltech Inc |
| Angel Yeast Co., Ltd. |
| Archer Daniels Midland Company |
| Lallemand Inc. |
| Lesaffre Group |
| Biorigin |
| Pharma Nord Inc. |
| Novus International, Inc. |
| Cypress Systems Inc. |
| Others |
Supply Flow & Price Mechanics
Bioprocess engineering talent concentration in Danish and Dutch fermentation clusters compresses labor-cost differentials between premium pharmaceutical-grade and standard feed-grade selenium yeast tiers.
Pricing Analysis
Capacity additions in Shandong and Jiangsu provinces are reshaping price floors for commodity feed-grade biomass. Three-tier pricing structure across pharmaceutical-grade, certified feed-grade, and economy feed-grade levels stratifies buyer segments. Cost compression in economy tiers intensifies as Chinese state-owned fermentation assets expand output. Price-sensitive poultry layer operations in Southeast Asia gravitate toward sodium selenite substitution, while premium dairy cooperatives in Denmark and the Netherlands absorb pharmaceutical-grade premiums for guaranteed selenomethionine content.
Supply Chain Analysis
Domestic-content mandates under China's 14th Five-Year Plan for biomanufacturing are reshaping sourcing patterns for Asian-bound supply. Controlled-strain fermentation capacity draws from Denmark, the Netherlands, and China as principal supply nodes. Saccharomyces cerevisiae master cultures, selenium-enriched growth media, and GMP-compliant bioreactor infrastructure constitute critical input dependencies. Single-source vulnerability concentrates in proprietary strain repositories held by three biotechnology groups. Distribution runs through regional mineral premix compounders serving integrated livestock operations and direct-to-manufacturer contracts for human supplement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Selenium yeast functions as a stable compounder anchored by irreplaceable organic selenium bioavailability in precision livestock nutrition programs.
For Market Incumbents: Acquire Raman spectroscopy-enabled fermentation monitoring assets to compress batch-to-batch variability below competitor thresholds. Secure backward integration into selenium-enriched media production to insulate margin structures from commodity chemical volatility. Sodium selenite substitution pressure in price-sensitive poultry segments demands defensive certification investments in ISO 22000 and FAO/WHO Codex alignment to sustain premium positioning. For New Entrants and Emerging Players: Enter via ISO 22000 certification gaps among mid-tier feed compounders in Poland and Romania where validated organic selenium sourcing remains unconsolidated. Target human dietary supplement channels through direct-to-practitioner distribution partnerships capturing preventive health spending redirection. Pharmaceutical-grade purification capacity in Eastern European markets offers the most penetrable white-space with lower incumbent density than North American or Western European corridors. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale fermentation specialists with captive strain development capabilities but underutilized bioreactor trains. The five-to-ten-year viability window favors targets with established EFSA, FDA, and MARA dossiers rather than greenfield authorization plays. Watch for EFSA maximum permitted level revisions as the inflection signal that would trigger herd health contract renegotiation waves and premium supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Selenium-Enriched Media Production | Captive supply of critical growth substrates insulates margin structures from commodity chemical price volatility. |
| Raman Spectroscopy Fermentation Monitoring Deployment | Real-time selenomethionine yield optimization compresses batch-to-batch variability below 5% coefficient of variation. |
| ISO 22000 Certification Acquisition in Eastern Europe | Validated quality systems unlock mid-tier feed compounder demand in Poland and Romania. |
| Direct-to-Practitioner Distribution Partnership | Channel control captures preventive health spending redirection in human dietary supplement segments. |
| Multi-Year Herd Health Contract Structuring | Subscription-based technical advisory embeds selenium yeast into recurring revenue streams with guaranteed performance benchmarks. |
Methodological Framework
Direct dialogue with feed formulation nutritionists, bioprocess engineering directors at fermentation facilities, regulatory affairs specialists managing EFSA and MARA dossiers, and procurement leads at integrated pork and dairy operations grounded qualitative findings. Secondary validation drew from EFSA feed additive authorization registers, FDA GRAS notification filings, Chinese MARA novel food approval databases, and customs trade data for selenium yeast biomass movements. Bottom-up volume estimates from species-specific inclusion rates and herd counts triangulated against top-down market value reconstructions.
Bottom-up modeling traced selenium yeast consumption through livestock population statistics, species-specific nutritional requirements, and standard inclusion rate ranges across monogastric and ruminant categories. Segmentation dimensions spanned product grade tier, end-use application, regulatory jurisdiction cluster, and sales channel structure. CAGRs were derived from trajectory fitting to historical authorization patterns and projected herd health contract renewal cycles. Forecast inputs incorporated EFSA benchmark tightening timelines and MEE environmental compliance cost pass-through assumptions.
Inputs from regulatory filing databases and fermentation facility capacity disclosures were available through the study window; gaps in real-time contract pricing for multi-year herd health agreements introduce uncertainty bands around revenue concentration estimates. Forecasts reflect documented assumptions regarding EFSA authorization continuity and Chinese domestic production growth trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Collagen Supplements Market
Nutritional Supplements
L Carnitine Market
Nutritional Supplements
Global Antioxidant Market
Nutritional Supplements
Europe Vegan Supplements Market
Nutritional Supplements
Europe Omega 3 Market
Nutritional Supplements
Microencapsulated Omega-3 Powders Market
Nutritional Supplements
Spirulina Extract Market
Nutritional Supplements
Fatty Acid Supplements Market
Nutritional Supplements
Energy Gel Products Market
Nutritional Supplements
United States Botanical Supplements Market
Nutritional Supplements
Germany Whey Protein Market
Nutritional Supplements
Vitamin K2 Market
Nutritional Supplements
Nutritional Food and Drink Market
Nutritional Supplements
Microalgae DHA Market
Nutritional Supplements
Functional Carbohydrates Market
Nutritional Supplements
Europe Dietary Supplements Market