
 Nutritional Lipids Market | 2026-2036
Nutritional Lipids Market Size, Share, and Industry Trends Forecast 2026-2036
Nutritional Lipids Market Analysis
Subscription-based lipid profiling and ongoing formulation support is decoupling ingredient supply from one-time commodity transactions. BASF SE leverages its integrated omega-3 production network across marine and algal sources to sustain long-term supply agreements with infant nutrition brands. Cargill, Incorporated anchors its position through backward integration into specialty oilseeds, while Kerry Group plc differentiates via encapsulated lipid delivery systems that protect bioactive compounds through processing and shelf life.
Nutritional lipids comprise bioactive fatty acids, phospholipids, sterols, and structured triglycerides refined for human metabolic support, typically specified by omega-3 index potency, EPA/DHA ratio, and oxidative stability parameters measured by peroxide and anisidine values. These compounds serve primary commercial purposes in cell membrane integrity, inflammatory modulation, and neurological development across food, supplement, and clinical nutrition applications. Fatty acids and phospholipids dominate current volume flows, yet microbial-sourced DHA from Schizochytrium fermentation is capturing accelerated investment as marine supply constraints tighten. The nutraceuticals and supplements application cluster houses concentrated margin pools, while food and beverage fortification operates at thinner returns but scales through mass-market penetration.
EFSA Novel Food regulations govern algal and microbial lipid entry into European formulations, while FDA GRAS notifications and qualified health claims shape U.S. market access for omega-3 positioning statements. China's NMPA and National Food Safety Standards layer additional testing protocols for imported lipid concentrates intended for infant formula use. Stakeholders must monitor evolving purity thresholds for environmental contaminants like dioxins and PCBs alongside emerging carbon accounting requirements that will reshape sourcing decisions between marine, plant, and fermentation-derived supply chains.
Market Dynamics
Algal DHA fermentation is compressing the omega-3 supply base as marine fishery constraints harden, forcing infant formula manufacturers to requalify ingredient streams under tightening purity protocols.
Growth Catalysts
- EFSA Novel Food pathway tightening:Stricter authorization standards for algal lipid ingredients are accelerating investment in Schizochytrium fermentation capacity across European contract manufacturers.
- Maternal health channel expansion:China's postnatal nutrition segment is absorbing concentrated DHA premix volumes as domestic brands build captive formulation capabilities.
- Encapsulation technology maturation:Advanced lipid delivery systems protecting oxidative stability through shelf life are unlocking beverage fortification applications previously closed to unsaturated fatty acids.
Market Restraints
- Marine raw material volatility:Peruvian anchovy quota fluctuations and North Atlantic fishery management restrictions are injecting unpredictability into fish oil concentrate feedstock costs.
- Single-source fermentation risk:Algal DHA production concentrates among a limited cohort of contract fermentation facilities, creating supply vulnerability absent qualified secondary suppliers.
- Cross-contamination detection thresholds:EFSA and China's NMPA are ratcheting down permissible dioxin and PCB limits, forcing costly reprocessing of legacy marine oil inventories.
Strategic Opportunities
- Sports nutrition white space:Phospholipid-bound omega-3 formats targeting muscle recovery and inflammatory modulation remain underdeveloped relative to standard ethyl ester concentrates.
- Clinical nutrition institutional channels:Hospital and long-term care facilities are expanding parenteral and enteral lipid emulsion specifications, creating pull for structured triglyceride and fish oil-based formulations.
- Carbon accounting alignment:EU Green Deal supply chain disclosure requirements are favoring fermentation-derived lipids with quantifiable carbon footprints against marine extraction alternatives.
Industry Challenges
- Analytical chemistry talent scarcity:Specialized lipid oxidation chemists and mass spectrometry technicians capable of validating peroxide, anisidine, and polymer specifications are concentrated among legacy marine oil processors.
- Multi-jurisdiction dossier management:Simultaneous GRAS notification, Novel Food submission, and NMPA registration for a single algal DHA strain demands dedicated regulatory affairs infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nutritional Lipids Market |
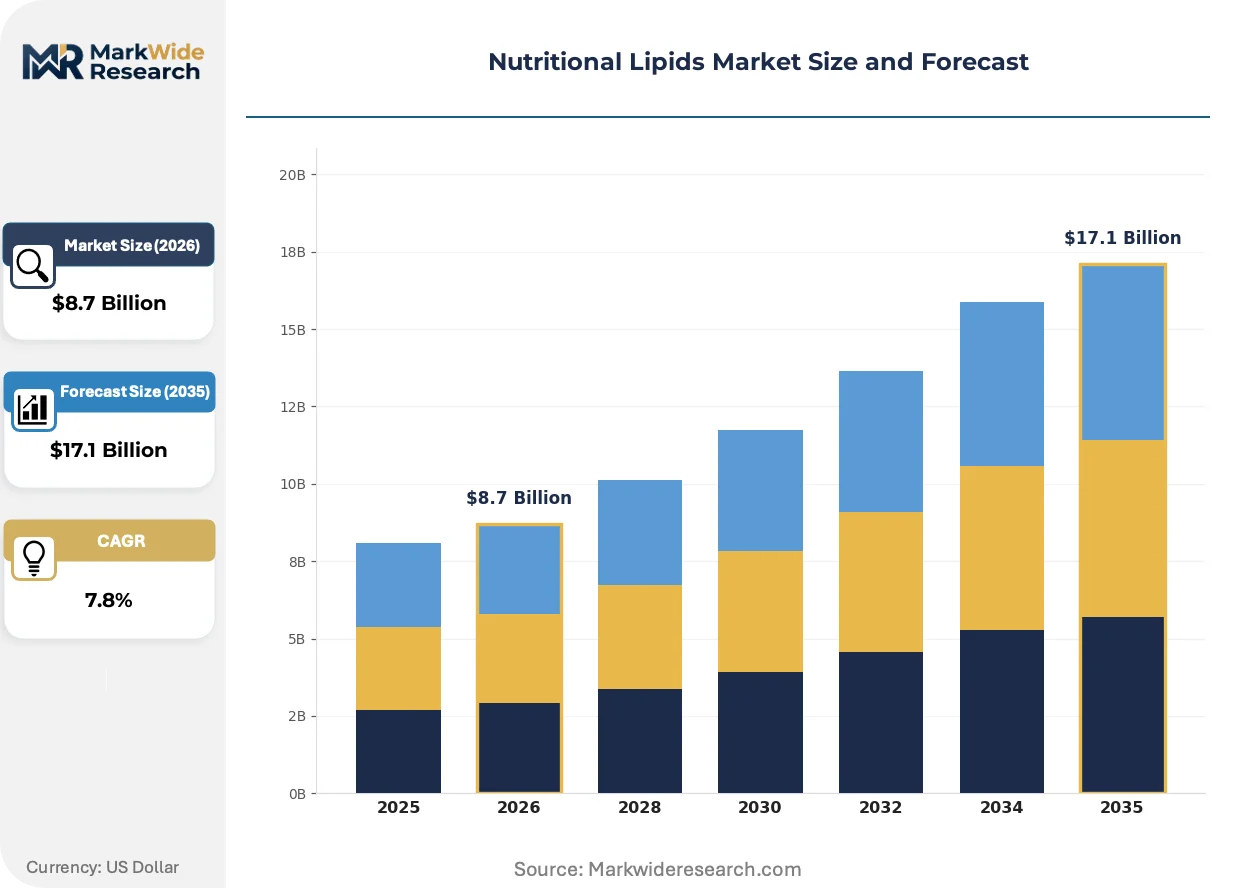
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phospholipids, Triglycerides, Fatty Acids, Sterols Source: Plant-based, Animal-based, Microbial, Synthetic Application: Nutraceuticals, Supplements, Food & Beverages, Pharmaceuticals End User: Health-conscious Consumers, Athletes, Elderly, Pregnant Women |
| Companies Covered | Koninklijke DSM N.V., BASF SE, Cargill, Incorporated, Archer Daniels Midland Company, Kerry Group plc, Clover Corporation, Croda International Plc, Nordic Naturals, Inc., FrieslandCampina, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nutritional Lipids Market Emerging Trajectories
Fermentation-derived lipids are restructuring competitive positioning as sustainability metrics penetrate procurement criteria, while delivery system innovation opens categories previously resistant to lipid fortification.
Precision fermentation of Schizochytrium and related thraustochytrid strains is overtaking traditional marine extraction for high-purity DHA production. Infant formula manufacturers in Asia-Pacific are qualifying these inputs at accelerated pace, compressing timelines for novel ingredient adoption that historically spanned multiple reformulation cycles. The technology is overtaking conventional fish oil in premium positioning segments where oxidation stability and contaminant profiles outweigh cost considerations.
China's NMPA has layered additional testing protocols for imported lipid concentrates intended for infant formula use, including expanded heavy metal screening and fatty acid profile verification. Domestic brands are responding by building in-house analytical capabilities rather than relying on supplier certificates of analysis. The regulation is compressing margins for imported premix suppliers while elevating qualified domestic compounders.
Subscription-based lipid profiling and ongoing formulation support is decoupling ingredient supply from one-time commodity transactions. Nutraceutical brands are absorbing these services as core R&D functions rather than vendor add-ons, particularly in North American direct-to-consumer channels. The model is most visible among omega-3 index testing providers bundling personalized dosing recommendations with recurring product shipments.
Nutritional Lipids Market Segmentation
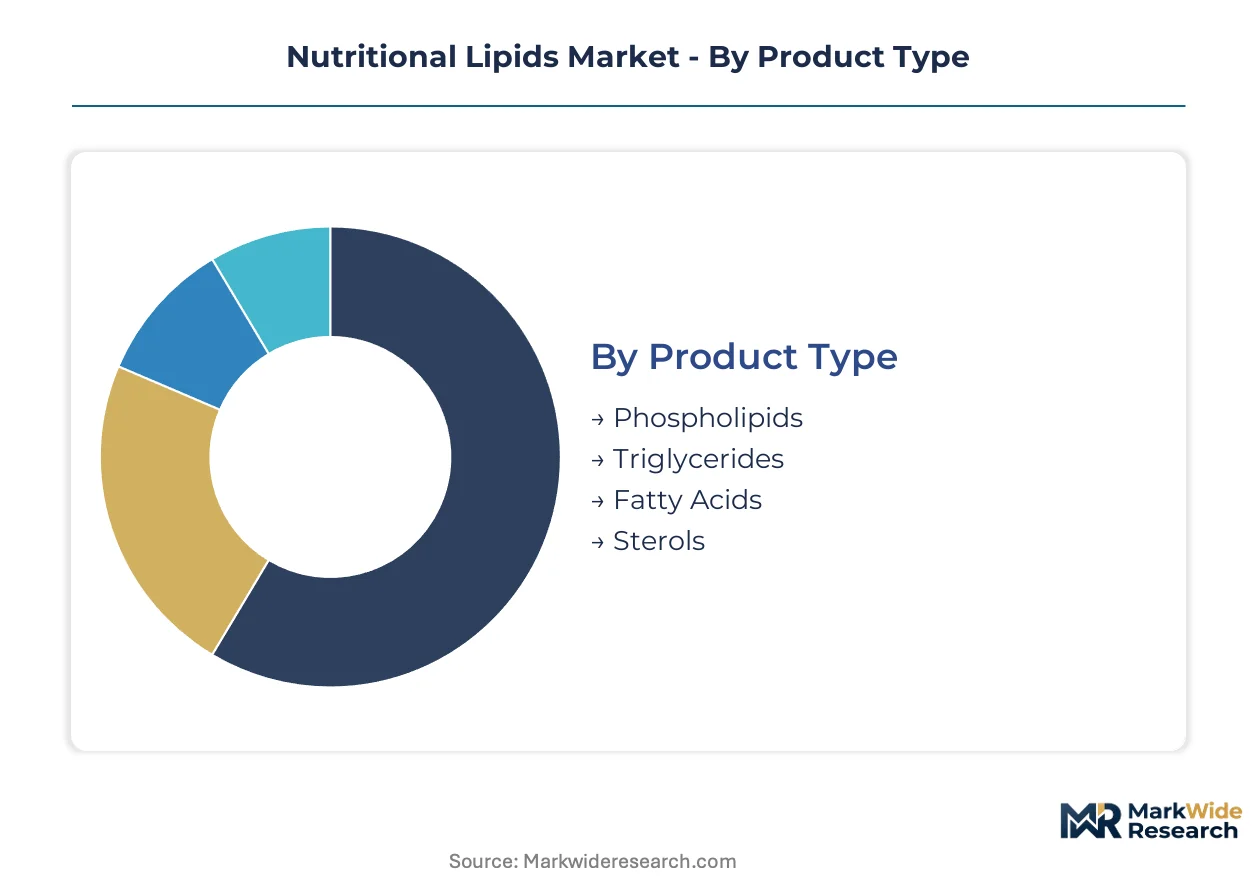
Nutritional lipids serve divergent metabolic functions across life stages and consumption formats, forcing suppliers to calibrate purity specifications, oxidative stability profiles, and delivery mechanisms to distinct buyer requirements. Segmentation reveals where margin pools concentrate versus where volume scales through commodity positioning.
Product Type:
Buyers differentiate primarily by bioactive potency requirements and formulation compatibility with existing processing equipment.
- Fatty Acids:Omega-3 concentrates specified by EPA/DHA ratio and omega-3 index potency dominate infant formula procurement in China, where NMPA protocols mandate expanded heavy metal screening for imported concentrates. Marine-derived ethyl esters face mounting pressure from fermentation-based alternatives as EFSA Novel Food pathways mature.
- Phospholipids:Phosphatidylcholine and phosphatidylserine fractions enable cell membrane integration superior to standard triglyceride formats, commanding premium positioning in sports nutrition applications targeting muscle recovery and inflammatory modulation. Demand concentrates among North American direct-to-consumer brands bundling lipid profiling subscriptions.
- Triglycerides:Structured triglycerides with defined fatty acid positioning support parenteral and enteral nutrition specifications in hospital and long-term care channels.
- Sterols:Plant-derived phytosterols serve cholesterol management positioning in functional food fortification at thinner margins but mass-market scale.
Volume sits with fatty acids; growth tilts toward phospholipids.
Source:
Procurement decisions increasingly weigh carbon footprint quantification against contaminant purity thresholds and supply security.
- Microbial:Schizochytrium fermentation yields DHA with quantifiable carbon footprints favored under EU Green Deal disclosure requirements, compressing adoption timelines historically spanning multiple reformulation cycles. Infant formula manufacturers across Asia-Pacific are qualifying these inputs at accelerated pace as marine fishery constraints harden.
- Plant-based:Specialty oilseed cultivation through backward-integrated supply chains anchors Cargill's positioning, with algal and fungal sources gaining traction where sustainability metrics penetrate procurement criteria.
- Animal-based:Marine fish oil concentrates face Peruvian anchovy quota volatility and North Atlantic fishery management restrictions, injecting unpredictability into feedstock costs.
- Synthetic:Petrochemical-derived fatty acid esters serve industrial applications with limited nutritional positioning.
Microbial sources are expanding most quickly; animal-based retains volume dominance.
Application:
Margin structure varies dramatically between concentrated bioactive positioning and mass-market fortification.
- Nutraceuticals and Supplements:Concentrated margin pools attract Kerry Group's encapsulated delivery systems protecting bioactive compounds through processing and shelf life, with omega-3 index testing providers bundling personalized dosing recommendations in North American direct-to-consumer channels.
- Food and Beverages:Thinner returns scale through mass-market penetration, with advanced lipid delivery systems unlocking beverage fortification applications previously closed to unsaturated fatty acids.
- Pharmaceuticals:Clinical nutrition institutional channels expand parenteral and enteral lipid emulsion specifications, creating pull for structured triglyceride formulations.
Nutraceuticals command premium pricing; food and beverages scale through volume.
End User:
Life-stage specificity drives formulation complexity and regulatory scrutiny intensity.
- Pregnant Women:Maternal health channels in China absorb concentrated DHA premix volumes as domestic brands build captive formulation capabilities, responding to NMPA's layered testing protocols by developing in-house analytical capabilities rather than relying on supplier certificates of analysis.
- Elderly:Long-term care facilities and hospital channels drive clinical nutrition specifications for structured triglyceride and fish oil-based formulations addressing inflammatory modulation.
- Health-conscious Consumers:Subscription-based lipid profiling services decouple ingredient supply from one-time commodity transactions.
- Athletes:Phospholipid-bound omega-3 formats targeting muscle recovery remain underdeveloped relative to standard ethyl ester concentrates.
Pregnant women concentrate premium demand; health-conscious consumers scale through subscription models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors the nutritional lipids procurement corridor, where infant formula compounders cluster around Yangtze River Delta logistics hubs to access both imported marine concentrates and domestic fermentation-derived alternatives.
China
Maternal health channels in Jiangsu and Zhejiang provinces absorb concentrated DHA premix volumes as domestic brands build captive formulation capabilities. NMPA's layered testing protocols for imported lipid concentrates mandate expanded heavy metal screening and fatty acid profile verification. Domestic compounders in Shanghai and Guangzhou are responding by developing in-house analytical capabilities rather than relying on supplier certificates of analysis.
United States
Direct-to-consumer nutraceutical brands bundle omega-3 index testing with personalized dosing recommendations, creating recurring revenue streams beyond commodity ingredient transactions. FDA GRAS notifications and qualified health claims shape market access for omega-3 positioning statements in supplements and functional foods. Kerry Group's encapsulated delivery systems anchor formulation support services in the Midwest dairy and beverage processing corridor.
Germany
EFSA Novel Food pathway tightening accelerates investment in Schizochytrium fermentation capacity across European contract manufacturers serving infant nutrition brands. EU Green Deal supply chain disclosure requirements favor fermentation-derived lipids with quantifiable carbon footprints against marine extraction alternatives. BASF SE leverages integrated omega-3 production networks across Ludwigshafen and Scandinavian algal sources to sustain long-term supply agreements.
Japan
Aging demographics drive clinical nutrition specifications for structured triglyceride formulations in hospital and long-term care channels. METI and PMDA oversight maintains stringent purity thresholds for parenteral and enteral lipid emulsions. Osaka-based processors concentrate phospholipid-bound omega-3 development for muscle recovery applications in sports nutrition segments.
Netherlands
Rotterdam port logistics consolidate marine fish oil concentrate imports from Peruvian and North Atlantic fisheries before redistribution across European formulation facilities. FrieslandCampina anchors dairy lipid innovation in the northern dairy belt, while specialty oilseed backward integration supports plant-based sterol production for cholesterol management positioning. REACH compliance infrastructure enables rapid novel ingredient qualification for pan-European distribution.
Nutritional Lipids Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the nutritional lipids value chain, with integrated fermentation operators and marine extraction specialists maintaining distinct cost structures. The vendor base stratifies between multinational chemical conglomerates with captive omega-3 networks, agribusiness giants with oilseed supply chain control, and specialized encapsulation technology providers. Three archetypes dominate: integrated bioprocess operators, backward-integrated agricultural processors, and formulation service specialists. Competitive moves concentrate on fermentation capacity expansion and strategic partnerships for novel ingredient qualification under tightening regulatory pathways.
Within the integrated bioprocess tier, Koninklijke DSM N.V. and BASF SE exemplify capital-intensive positioning through Schizochytrium fermentation networks and marine-algal hybrid supply architectures. Cargill, Incorporated represents the agricultural processor archetype with oilseed cultivation integration, while Kerry Group plc anchors the formulation specialist vector through encapsulated delivery systems. These three occupy positions that reflect divergent strategic bets on microbial versus plant versus marine feedstock dominance.
| Leading Market Players |
|---|
| Koninklijke DSM N.V. |
| BASF SE |
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Kerry Group plc |
| Clover Corporation |
| Croda International Plc |
| Nordic Naturals, Inc. |
| FrieslandCampina |
| Others |
Supply Flow & Price Mechanics
Backward integration into Schizochytrium fermentation networks anchors supply security for infant formula compounders while compressing pricing power for legacy marine oil processors. Cargill's oilseed cultivation control and BASF's hybrid marine-algal architectures illustrate how upstream asset ownership translates into contract pricing leverage against buyers facing NMPA purity mandates.
Pricing Analysis
Cost compression in standard ethyl ester concentrates accelerates as fermentation-derived DHA achieves parity on oxidation stability metrics. Three-tier pricing structure across premium, standard, and economy levels separates phospholipid-bound formats from ethyl esters and bulk triglyceride commodities. Pricing pressure stems from Chinese domestic brands building captive formulation capabilities rather than importing premixes. Infant formula manufacturers exhibit highest price sensitivity, while clinical nutrition channels absorb premium positioning for structured triglycerides.
Supply Chain Analysis
Dual-sourcing requirements now mandate simultaneous qualification of marine and microbial DHA streams for infant formula approvals in China and Europe. Production concentrates in Germany, China, and the Netherlands, with Rotterdam anchoring marine concentrate redistribution. Feedstock supply rests on Peruvian anchovy fisheries, Schizochytrium fermentation capacity, and specialty oilseed cultivation. Single-source fermentation vulnerability creates structural risk absent qualified secondary suppliers. Distribution runs through Yangtze River Delta logistics hubs serving domestic compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation capacity bottlenecks prop pricing across the analysis window as infant formula manufacturers race to qualify algal DHA under tightening EFSA and NMPA protocols.
For Market Incumbents: Acquire fermentation facility assets in European contract manufacturing corridors to secure Schizochytrium capacity ahead of Novel Food pathway maturation. Build redundant supplier qualification dossiers addressing NMPA's expanded heavy metal screening mandates to defend against domestic Chinese compounders capturing share through in-house analytical capabilities. For New Entrants and Emerging Players: Begin with phospholipid-bound omega-3 formats in North American sports nutrition channels, where muscle recovery positioning remains underdeveloped relative to standard ethyl ester concentrates. Bundle lipid profiling subscriptions with direct-to-consumer distribution to bypass entrenched ingredient supply relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated chemical conglomerates seeking fermentation bioprocess capabilities. Five-to-ten year viability hinges on carbon accounting alignment under EU Green Deal disclosure requirements. Watch NMPA registration timelines for single-strain algal DHA as inflection indicator for domestic Chinese supplier valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Schizochytrium facility buildout secures supply position under EFSA Novel Food tightening. |
| Backward Integration into Oilseeds | Cargill's specialty cultivation control anchors plant-based sterol cost positioning. |
| Encapsulation Technology Acquisition | Kerry's delivery systems protect oxidative stability for beverage fortification entry. |
| Long-term Supply Agreement | BASF sustains infant nutrition contracts through integrated marine-algal networks. |
| Regulatory Dossier Investment | Simultaneous GRAS, Novel Food, and NMPA submissions accelerate market access timelines. |
Methodological Framework
Document review covered EFSA Novel Food submissions, NMPA registration filings, and EU Green Deal supply chain disclosures, complemented by interviews with fermentation facility operators, infant formula procurement directors, and lipid oxidation chemists. Secondary validation drew from customs trade data, SEC 10-K filings of listed ingredient suppliers, and industry association technical standards. Bottom-up volume modeling triangulated against top-down market sizing across product type, source, application, and end user dimensions.
Cross-referencing historical capacity expansion patterns with expert panel input on regulatory timeline probabilities shaped the analytical framework across the projection horizon. Segmentation modeling captured fatty acid, phospholipid, triglyceride, and sterol categories by microbial, plant, animal, and synthetic sources. CAGR derivation incorporated infant formula manufacturer qualification pace, algal DHA adoption curves, and encapsulation technology penetration rates.
Peruvian anchovy quota volatility, EFSA purity threshold revisions, and Chinese domestic formulation capability buildout are the dominant revision risks. Deviation in NMPA registration processing speed would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
South America Nutraceuticals Market
Nutritional Supplements
Medicinal Mushroom Supplement Market
Nutritional Supplements
Low-Carb Fat Loss Market
Nutritional Supplements
North America Immune Health Supplements Market
Nutritional Supplements
Mineral Supplements Market
Nutritional Supplements
Asia-Pacific Nutraceutical Excipients Market
Nutritional Supplements
Vegan Protein Supplements Market
Nutritional Supplements
Garlic Extract Supplement Market
Nutritional Supplements
Europe Nutritional Beverages Market
Nutritional Supplements
Vitamin B12 Market
Nutritional Supplements
Global Oncology Nutrition Market
Nutritional Supplements
Effervescent Product Market
Nutritional Supplements
Vegan Supplements Market
Nutritional Supplements
Algae Omega 3 Market
Nutritional Supplements
Lithium Orotate Supplement Market
Nutritional Supplements
North America Digestive Health Supplements Market