
 Global Proanthocyanidins Market | 2026-2036
Global Proanthocyanidins Market Size, Share, and Industry Trends Forecast 2026-2036
Global Proanthocyanidins Market Foresight
EU REACH compliance is hardening purity thresholds for botanical extracts entering European nutraceutical channels. Indena S.p.A. leverages its Milan-based extraction infrastructure to sustain pharmaceutical-grade supply chains across EU member states. Nexira anchors its competitive position through specialized grape seed and pine bark sourcing networks in France. Naturex competes on certified organic extraction credentials that navigate tightening EFSA novel food evaluations.
Proanthocyanidins constitute a class of oligomeric and polymeric flavan-3-ols, typically comprising two to twelve catechin or epicatechin subunits linked through C4-C8 and C4-C6 bonds, with molecular weights ranging from approximately 580 to over 3000 Daltons; these polyphenolic compounds function primarily as radical scavengers in industrial formulations targeting oxidative stress modulation. Purified extracts command premium positioning in pharmaceutical applications where standardization to specified oligomeric ratios determines contract eligibility. Functional beverages represent the fastest-growing application dimension as beverage brands reformulate with plant-derived antioxidants to replace synthetic preservatives.
FDA GRAS self-affirmation pathways and EFSA novel food authorization frameworks create divergent market access conditions for proanthocyanidin suppliers targeting transatlantic distribution. USDA organic certification and EU organic regulation 2018/848 further segment pricing structures across premium and conventional extraction tiers. Stakeholders must monitor evolving pharmacopeial monograph standards that will determine which extraction technologies achieve regulatory recognition for therapeutic-grade supply.
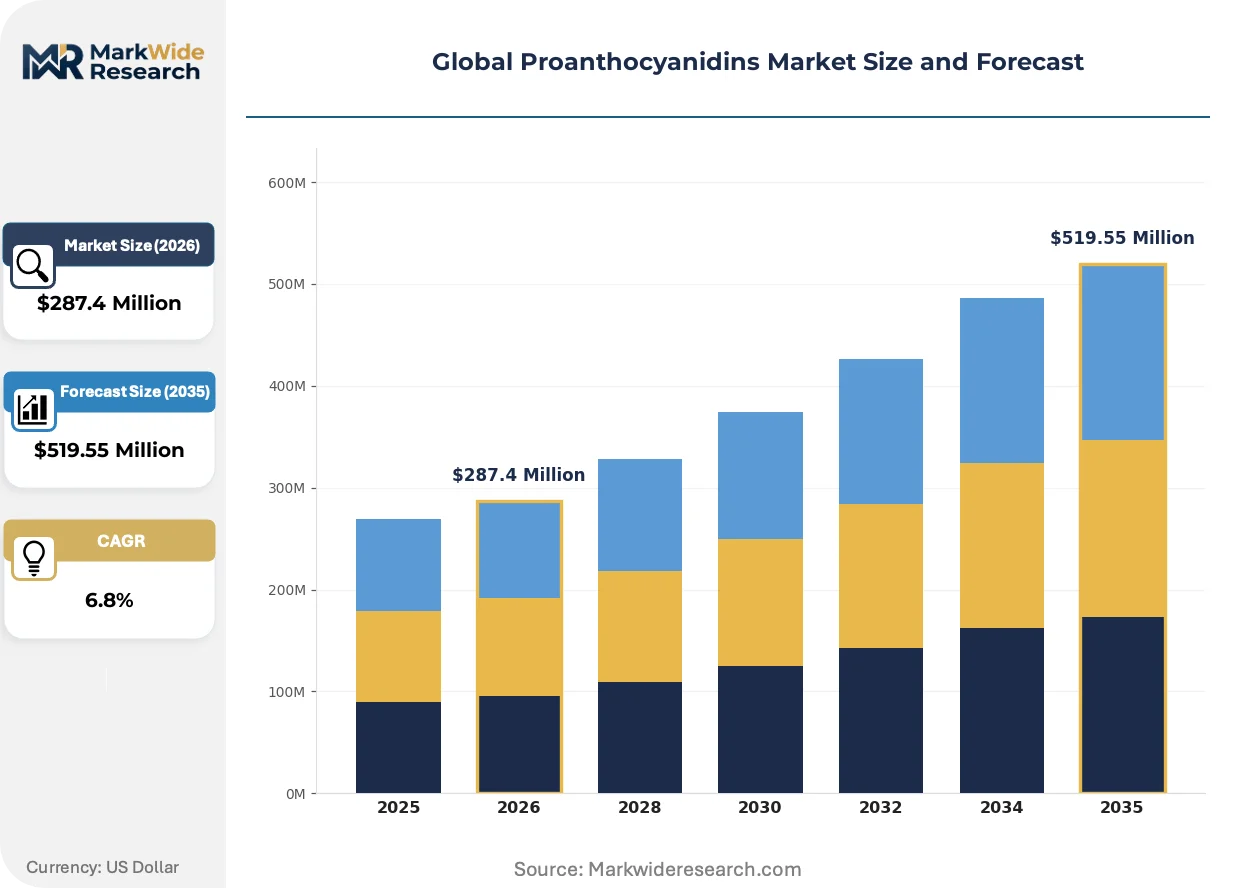
Market Dynamics
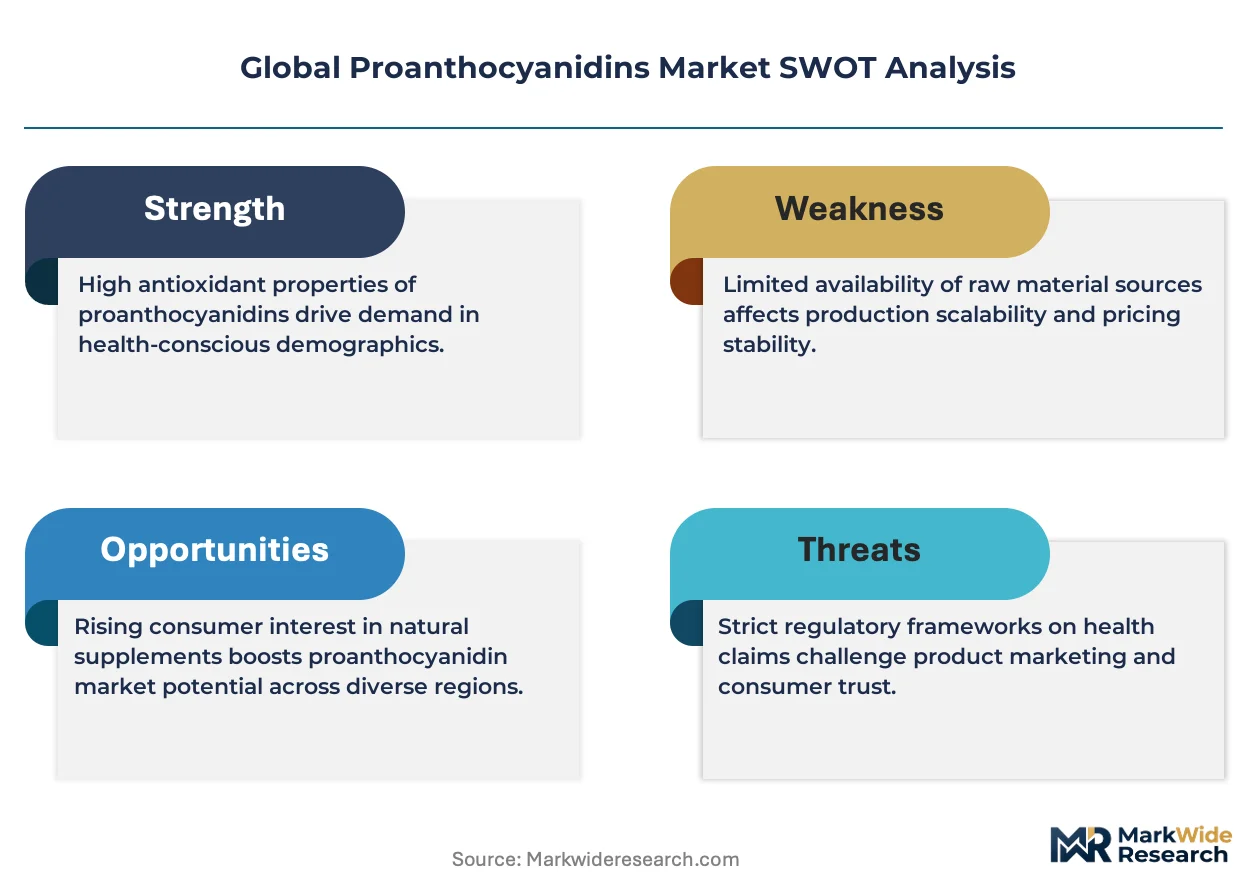
REACH compliance in Europe is hardening extraction purity thresholds and forcing proanthocyanidin suppliers to requalify their entire supplier base, while functional beverage brands in the United States are accelerating procurement of grape seed and cranberry extracts to replace synthetic preservatives.
Growth Catalysts
- Clean-label reformulation mandates:Functional beverage brands in the United States are integrating grape seed and cranberry extracts into mainstream product lines to displace synthetic antioxidants.
- EU REACH compliance hardening:Extraction purity standards are reshaping supplier qualification protocols and creating competitive moats for pharmaceutical-grade producers.
- Pharmaceutical standardization requirements:Oligomeric ratio specifications in therapeutic-grade applications are locking in long-term procurement contracts with certified extractors.
Market Restraints
- Raw material supply concentration:Premium grape seed and pine bark sourcing networks concentrate in southwestern France and northern Italy, exposing buyers to regional climate volatility.
- Regulatory friction from divergent frameworks:FDA GRAS self-affirmation pathways and EFSA novel food authorization create incompatible market access conditions for transatlantic distribution.
- Substitution threat from synthetic antioxidants:Butylated hydroxytoluene and tertiary butylhydroquinone retain cost advantages in mass-market food preservation despite clean-label pressures.
Strategic Opportunities
- Underpenetrated nutricosmetic channels in South Korea:MFDS regulatory pathways for functional beauty ingredients are opening procurement contracts for oral antioxidant formulations.
- Organic certification premium tier:USDA organic and EU regulation 2018/848 compliance is creating pricing stratification that rewards certified extraction investments.
- Emerging pet nutrition applications:Veterinary antioxidant supplementation is generating new demand for standardized proanthocyanidin extracts in companion animal formulations.
Industry Challenges
- Analytical chemistry skill scarcity:Oligomeric proanthocyanidin quantification requires specialized HPLC-MS expertise that extraction facilities struggle to recruit.
- Pharmacopeial monograph alignment timelines:USP and EP standard updates are delaying regulatory recognition for novel extraction technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Proanthocyanidins Market |
| Market Size in 2026 | $287.4 Million |
| Market Size in 2035 | $519.55 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Purified Extracts, Concentrated Powders, Liquid Concentrates, Granules, Capsules Application: Dietary Supplements, Functional Beverages, Cosmetics Formulations, Pharmaceuticals, Animal Nutrition Extraction Technology: Solvent Extraction, Enzymatic Extraction, Ultrasonic Assisted, Microwave Assisted, Supercritical Fluid End User: Contract Manufacturers, Nutraceutical Companies, Personal Care Brands, Pharmaceutical Firms |
| Companies Covered | Indena S.p.A., Nexira, Naturex, Artemis International, Xian Yuensun Biological Technology, Polyphenolics, Eevia Health, Fruit d'Or, Natac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Proanthocyanidins Market Shifts & Advancements
Supercritical CO2 extraction technology is converging with subcritical water processing to reshape how proanthocyanidin suppliers achieve pharmaceutical-grade purity without residual solvent contamination.
Subcritical water extraction technology is converging with in-line spectroscopic monitoring to enable real-time oligomeric profile adjustment during grape seed processing. Pharmaceutical formulators in Germany and Switzerland are adopting these integrated systems to secure USP-grade supply contracts. The structural consequence is compressing batch-to-batch variability from historical ranges toward pharmacopeial monograph tolerances.
EU REACH authorization requirements for solvent residues in botanical extracts are forcing extraction facilities to document supply chain chemistry back to raw material orchards. The industrial consequence is disqualifying traditional ethanol-based processors from pharmaceutical channel eligibility. Nutraceutical contract manufacturers in France and Italy are responding by consolidating procurement around supercritical CO2-certified suppliers.
Direct sourcing relationships between functional beverage brands and extraction facilities are displacing traditional ingredient distributor intermediaries. Procurement teams at North American beverage companies are negotiating multi-year offtake agreements with French and Italian extractors. This channel compression is most visible in the United States, where clean-label positioning requires documented provenance that distributors cannot provide.
Global Proanthocyanidins Market Segmentation
Proanthocyanidin procurement patterns diverge sharply across product formats and end-use channels. Extraction technology choices now determine regulatory eligibility as REACH and FDA standards harden. Understanding these segment boundaries clarifies where margin compression and premium capture concentrate.
Product Type:
Purified extracts command the steepest price premiums where pharmaceutical-grade oligomeric ratios are specified.
- Purified Extracts:Standardized to defined procyanidin B1-B4 profiles with molecular weight distributions between 580-3000 Daltons. German and Swiss pharmaceutical formulators lock in multi-year procurement contracts for USP-grade material.
- Concentrated Powders:Spray-dried matrices carrying 50-95% polyphenolic content. Functional beverage brands in the United States source these for clean-label antioxidant claims that displace synthetic preservatives.
- Liquid Concentrates:Aqueous or glycerin-based solutions targeting beverage fortification with simplified dissolution.
- Granules:Free-flowing agglomerates designed for tableting operations in dietary supplement manufacturing.
- Capsules:Pre-formulated unit doses reducing downstream processing steps for nutraceutical contract manufacturers.
Volume sits with concentrated powders; growth tilts toward purified extracts.
Application:
Channel requirements split between cosmetic tolerance thresholds and pharmaceutical monograph rigor.
- Dietary Supplements:Capsule and tablet formats dominate procurement from nutraceutical contract manufacturers. EFSA novel food evaluations and FDA GRAS self-affirmation pathways create divergent compliance costs across Atlantic distribution.
- Functional Beverages:Grape seed and cranberry extracts integrate into mainstream product lines as beverage brands reformulate with plant-derived antioxidants. North American procurement teams negotiate direct offtake agreements with French and Italian extractors.
- Cosmetics Formulations:Topical antioxidant claims drive demand for low-molecular-weight oligomers with enhanced dermal penetration.
- Pharmaceuticals:Therapeutic-grade applications require pharmacopeial alignment to USP and EP monographs.
- Animal Nutrition:Veterinary antioxidant supplementation generates new demand for standardized extracts in companion animal formulations.
Dietary supplements anchor current volume; functional beverages are climbing the fastest.
Extraction Technology:
Regulatory recognition now favors solvent-free methods that document supply chain chemistry to raw material orchards.
- Supercritical Fluid:CO2-based systems achieve pharmaceutical-grade purity without residual solvent contamination. EU REACH authorization requirements for solvent residues disqualify traditional ethanol processors from pharmaceutical channel eligibility.
- Subcritical Water:In-line spectroscopic monitoring enables real-time oligomeric profile adjustment during grape seed processing. French and Italian nutraceutical contract manufacturers consolidate procurement around these certified suppliers.
- Solvent Extraction:Ethanol and methanol-based methods face tightening residue thresholds in European markets.
- Enzymatic Extraction:Cell-wall degrading enzymes improve yield from grape seed and pine bark matrices.
- Ultrasonic Assisted:Cavitation-enhanced mass transfer reduces processing time for industrial-scale operations.
- Microwave Assisted:Rapid heating protocols accelerate polyphenolic release from botanical matrices.
Supercritical fluid systems dominate premium tier positioning; subcritical water methods gain share fastest.
End User:
Procurement sophistication separates pharmaceutical-grade buyers from mass-market formulators.
- Pharmaceutical Firms:Therapeutic-grade specifications demand certified extraction with documented oligomeric ratios. USP and EP standard updates determine which technologies achieve regulatory recognition.
- Nutraceutical Companies:Direct sourcing relationships with extraction facilities displace traditional ingredient distributor intermediaries.
- Contract Manufacturers:Toll processing operations serve brands lacking in-house extraction capabilities.
- Personal Care Brands:Cosmetic tolerance testing requirements drive demand for low-irritant extract grades.
Contract manufacturers handle the largest throughput volumes; pharmaceutical firms represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of proanthocyanidin concentrates clusters in Mediterranean extraction facilities, while formulation demand concentrates in North American beverage laboratories and German pharmaceutical campuses. This geographic split creates regulatory arbitrage opportunities for suppliers navigating divergent purity standards.
United States
Functional beverage brands in the United States are accelerating procurement of grape seed and cranberry extracts to displace synthetic preservatives in clean-label reformulations. FDA GRAS self-affirmation pathways enable faster market entry compared to European authorization frameworks. Procurement teams in Chicago and Los Angeles negotiate direct offtake agreements with French and Italian extractors, bypassing traditional distributor intermediaries.
Germany
German pharmaceutical formulators lock in multi-year procurement contracts for USP-grade proanthocyanidin material with specified oligomeric ratios. EMA pharmacopeial alignment requirements determine which extraction technologies achieve regulatory recognition for therapeutic-grade supply. Heidelberg and Frankfurt host the primary analytical chemistry clusters where HPLC-MS expertise supports oligomeric quantification for contract eligibility.
France
French nutraceutical contract manufacturers consolidate procurement around supercritical CO2-certified suppliers to meet REACH authorization requirements for solvent residues. ECHA thresholds disqualify traditional ethanol-based processors from pharmaceutical channel eligibility. The Bordeaux and Provence regions anchor specialized grape seed and pine bark sourcing networks that supply premium extraction feedstock.
Italy
Italian extraction facilities leverage Milan-based infrastructure to sustain pharmaceutical-grade supply chains across EU member states. EFSA novel food evaluations reshape competitive positioning for suppliers targeting nutraceutical channels. Northern Italian processors specialize in certified organic extraction credentials that navigate tightening regulatory frameworks.
China
Chinese suppliers face divergent market access conditions when targeting transatlantic distribution due to incompatible FDA and EFSA frameworks. NMPA domestic regulations and GB standards govern local production quality tiers. Xian and Zhengzhou host concentration zones for biological technology firms serving both domestic and export markets.
Global Proanthocyanidins Market Competitive Landscape
The competitive structure tilts toward extraction technology specialists with documented supply chain chemistry back to raw material orchards. Three archetypes dominate: pharmaceutical-grade standardizers with USP-certified facilities, organic-certified processors capturing premium tier pricing, and scale-driven commodity suppliers serving mass-market beverage formulators. M&A activity concentrates on backward integration into captive vineyard and forest bark supply, while technology licensing partnerships proliferate around supercritical CO2 and subcritical water extraction systems.
Within the European pharmaceutical-grade tier, Indena S.p.A. and Nexira occupy positions anchored by Milan and French extraction infrastructure respectively. Among North American specialists, Artemis International exemplifies the clean-label procurement archetype serving functional beverage brands. Xian Yuensun Biological Technology represents the Chinese biological technology cluster targeting export qualification. These three entities illustrate how geographic regulatory specialization creates competitive segmentation.
| Leading Market Players |
|---|
| Indena S.p.A. |
| Nexira |
| Naturex |
| Artemis International |
| Xian Yuensun Biological Technology |
| Polyphenolics |
| Eevia Health |
| Fruit d'Or |
| Natac |
| Others |
Supply & Pricing Matrix
Pharmaceutical formulators in Germany and Switzerland anchor premium tier demand through multi-year procurement contracts, locking in contract-based long-term offtake pricing that rewards documented oligomeric standardization. This buyer concentration creates asymmetric power dynamics where certified extractors capture margin while uncertified competitors face disqualification from therapeutic-grade channels.
Pricing Analysis
Cost compression in mass-market beverage grades accelerates as functional brands negotiate direct offtake agreements with French and Italian extractors, bypassing distributor markups. Three-tier pricing structure across pharmaceutical-grade, certified organic, and conventional extraction levels reflects REACH compliance costs and USP certification investments. Price differentiation rests on pharmacopeial alignment and organic credentialing under EU regulation 2018/848. Beverage formulators exhibit highest price sensitivity; pharmaceutical buyers prioritize standardization over unit cost.
Supply Chain Analysis
REACH authorization requirements for solvent residues are gating supplier eligibility, forcing consolidation around supercritical CO2-certified facilities in France, Italy, and Germany. Raw material networks draw from specialized grape seed orchards in Bordeaux and Provence plus pine bark sources in northern Italy. Single-source vulnerability concentrates in southwestern French feedstock regions exposed to climate volatility. Distribution runs through direct procurement relationships between North American beverage brands and Mediterranean extraction facilities, displacing traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EU REACH authorization creates barrier-to-entry moats for pharmaceutical-grade extractors while disqualifying traditional ethanol processors from premium channels.
For Market Incumbents: Lock in backward integration into captive vineyard and forest bark supply to defend against raw material concentration risk in southwestern France. Secure pharmacopeial alignment ahead of USP and EP monograph updates to preempt regulatory disqualification of competitors. Prioritize analytical chemistry capability investments to address HPLC-MS expertise scarcity constraining batch certification throughput. For New Entrants and Emerging Players: Launch via subcritical water extraction technology targeting South Korean nutricosmetic channels where MFDS regulatory pathways for oral antioxidant formulations remain underpenetrated. Enter through certified organic tier positioning to capture pricing premiums under EU regulation 2018/848. Emphasize real-time oligomeric profiling capabilities to differentiate from incumbent batch-processing limitations. For Investors and Strategic Acquirers: Distressed-cycle entries favor analytical chemistry-specialist mid-caps in Germany and Switzerland facing temporary pharmacopeial alignment delays but possessing core HPLC-MS infrastructure. Long-term viability hinges on regulatory certification durability across REACH and FDA frameworks. Watch EFSA novel food evaluation timelines as inflection indicator for nutraceutical channel expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Feedstock | Secures Bordeaux and Provence grape seed supply against climate volatility disrupting competitor procurement. |
| Pharmacopeial Monograph Alignment Investment | Positions extractors for USP and EP therapeutic-grade contracts as standards harden across EU and Swiss markets. |
| Supercritical CO2 Certification Program | Enables REACH-compliant pharmaceutical channel eligibility disqualifying traditional ethanol-based processors. |
| Direct Sourcing Relationship Development | Bypasses distributor intermediaries to capture margin compression from North American beverage brand procurement teams. |
| Analytical Chemistry Capability Buildout | Addresses HPLC-MS expertise scarcity constraining oligomeric quantification throughput for batch certification. |
Research Methodology
Document review covered EFSA novel food authorization databases, REACH registration dossiers, and USP pharmacopeial monograph updates, complemented by interviews with extraction facility technical directors, pharmaceutical formulator procurement leads, nutraceutical contract manufacturing executives, and dietary supplement brand managers. Secondary validation drew from ECHA regulatory filings, customs trade data for botanical extract flows, and SEC disclosures from publicly traded ingredient suppliers. Bottom-up segment sizing triangulated against top-down market reconstruction from production capacity estimates.
Output modeling generated volume and value trajectories across the projection horizon through multi-dimensional segmentation by extraction technology tier, application channel, and end-user sophistication level. CAGRs derived from regression analysis against historical procurement patterns and regulatory event impacts. Forecast inputs incorporated REACH authorization timeline assumptions, EFSA evaluation queue velocities, and functional beverage reformulation commitment announcements from North American brand portfolios.
Regulatory authorization delays, raw material harvest volatility, and synthetic antioxidant substitution cost advantages are the dominant revision risks to modeled trajectories. Forecasts embed assumptions regarding pharmacopeial standard adoption schedules and clean-label procurement acceleration rates. A model refresh is warranted upon material change in EFSA novel food evaluation throughput or REACH solvent residue threshold amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
South America Dietary Supplement Market
Nutritional Supplements
Lactates Market
Nutritional Supplements
Bone Meal Supplement Market
Nutritional Supplements
Global Liver Health Supplements Market
Nutritional Supplements
Testosterone Booster Supplements Market
Nutritional Supplements
Liquid Dietary Supplements Market
Nutritional Supplements
Tea Tree Oil Market
Nutritional Supplements
Latin America Herbal Supplements Market
Nutritional Supplements
Natural Immune Booster Market
Nutritional Supplements
Vegan Vitamins and Supplements Market
Nutritional Supplements
Calcium Market
Nutritional Supplements
Canada Protein Market
Nutritional Supplements
Weight Loss Supplements Market
Nutritional Supplements
Pet Dietary Supplements Market
Nutritional Supplements
Europe Beta-Glucan Market
Nutritional Supplements
Longevity and Anti-Aging Brain Health Supplements Market