
 Smart Nutrition Scale Market | 2026-2036
Smart Nutrition Scale Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Nutrition Scale Market Insights
Bluetooth-enabled precision tiering is redrawing competitive boundaries in the smart nutrition scale landscape. Withings leverages its connected health ecosystem to sustain premium positioning across European and North American channels. Tanita Corporation anchors its reputation on bioelectrical impedance analysis integration, competing on clinical-grade accuracy rather than consumer price points. Etekcity dominates mass-market distribution through Amazon-centric channel control, while iHealth positions around HIPAA-aligned data architecture for healthcare-adjacent buyers.
A smart nutrition scale is an electronic weighing device equipped with load-cell sensors, microcontrollers, and wireless transceivers that measures food mass and queries nutritional databases to calculate macronutrient composition. These devices typically achieve precision of one gram or finer, operating through smartphone applications that synchronize intake data with fitness platforms. Smart scales and connected devices command the dominant revenue share, with Bluetooth-enabled units leading volume due to lower power draw and universal smartphone compatibility. Meal planning applications represent the fastest-expanding use case as consumers shift from passive weight tracking to proactive dietary intervention. Kitchen aids remain a niche margin pool, serving institutional foodservice rather than household penetration.
FDA digital health guidance and FCC Part 15 rules for unintentional radiators shape hardware certification timelines and data handling protocols in the United States. The EU Green Deal and REACH substance restrictions influence material selection for load-cell housings and circuit board substrates across European supply chains. Stakeholders must monitor whether emerging cybersecurity labeling requirements for connected kitchen appliances fragment certification paths or consolidate compliance around existing ISO 27001 frameworks.
Market Dynamics
Bluetooth Low Energy is compressing power requirements and certification costs, enabling mass-market OEMs to field connected scales at sub-premium price points while maintaining smartphone ecosystem compatibility.
Growth Catalysts
- FDA Digital Health Guidance:Streamlined 510(k) pathways for software-as-medical-device classifications accelerate time-to-market for nutrition-tracking hardware paired with diagnostic applications.
- Meal Planning Applications:Proactive dietary intervention platforms are pulling hardware sales as consumers seek integrated intake-to-action workflows rather than passive measurement.
- Germany:REACH-compliant material sourcing and EU Green Deal alignment position domestic manufacturers for preferential procurement by institutional foodservice buyers.
Market Restraints
- Load-Cell Sensor Concentration:Precision strain-gauge manufacturing clusters in East Asian foundries expose OEMs to single-source vulnerability and tariff exposure.
- FCC Part 15 Certification:Unintentional radiator testing for 2.4 GHz transceivers adds 8-14 week hardware validation timelines before US commercialization.
- Smartphone App Dependency:Nutrition scale functionality collapses without companion software, creating substitution risk from native phone camera-based food logging.
Strategic Opportunities
- HIPAA-Aligned Healthcare Channels:Clinical reimbursement pathways for remote patient monitoring create white space for scales with encrypted data architecture.
- China:Dual carbon goals and domestic MIIT standards for low-power IoT devices incentivize local production of BLE-enabled kitchen peripherals.
- Bioelectrical Impedance Convergence:Integration of body-composition sensing into nutrition scales opens wellness-club and corporate wellness procurement channels.
Industry Challenges
- Cybersecurity Labeling Fragmentation:Emerging connected-appliance security standards in multiple jurisdictions threaten to multiply certification burdens beyond existing ISO 27001 baselines.
- Legacy Platform Integration:Enterprise foodservice buyers demand API compatibility with decades-old inventory management systems, extending sales cycles and customization costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Nutrition Scale Market |
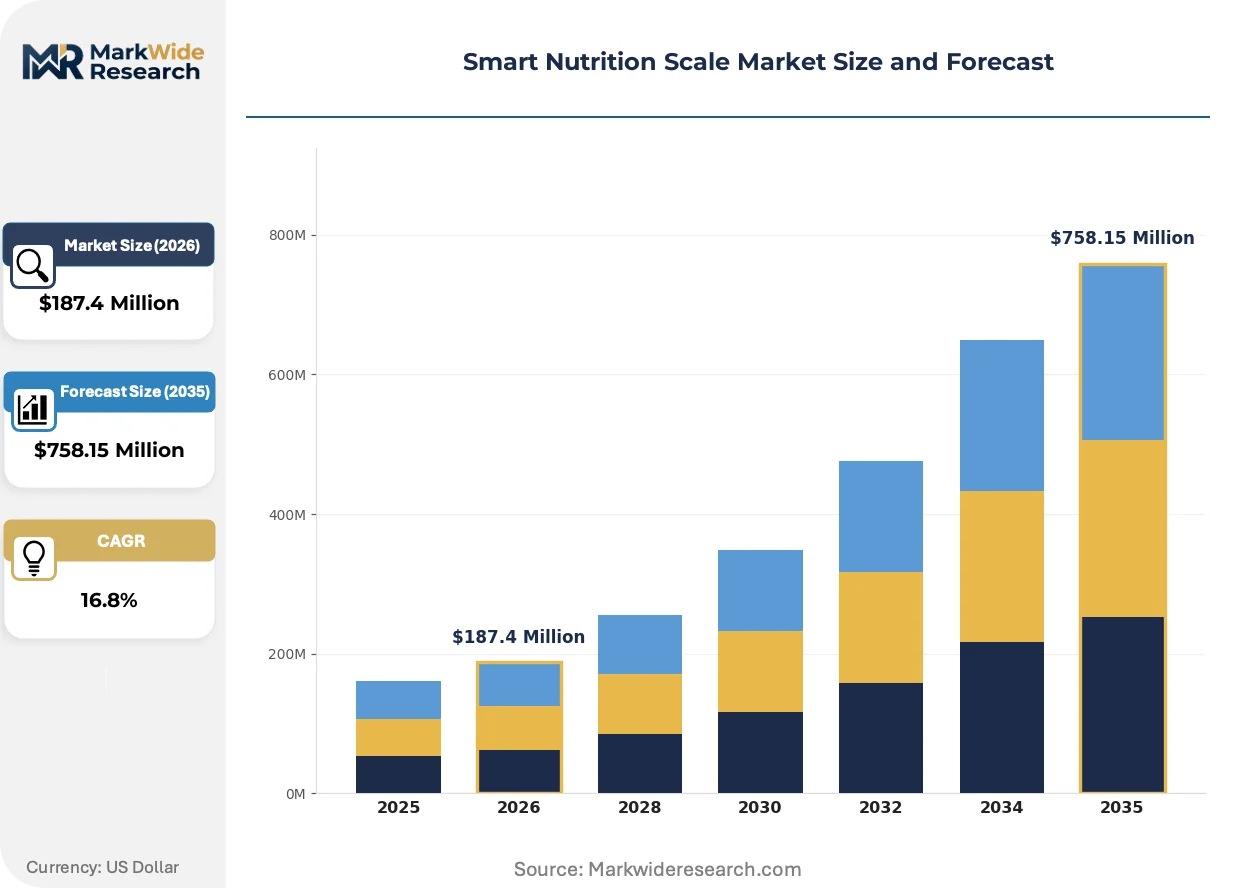
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $758.15 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Scales, Connected Devices, Manual Scales, Kitchen Aids End User: Home Users, Fitness Enthusiasts, Dietitians, Restaurants Technology: Bluetooth, Wi-Fi, NFC, USB Application: Weight Tracking, Meal Planning, Caloric Intake, Food Logging |
| Companies Covered | Fitbit, Withings, Tanita Corporation, Etekcity, Ozeri, Greater Goods, Escali, iHealth, Smart Diet Scale, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Nutrition Scale Market Trends and Innovations
Precision measurement hardware is converging with predictive software, shifting value capture from standalone devices toward recurring data-service relationships and platform-locked ecosystems.
Load-cell miniaturization combined with AI-driven food recognition is supplanting manual barcode scanning as the dominant intake-logging method. Fitness enthusiasts and weight-management clinics are adopting camera-assisted scales at accelerating rates. This compression of user friction is eroding subscription revenue for standalone nutrition databases while concentrating value in integrated hardware-software bundles.
EU Green Deal material restrictions and REACH substance limitations are forcing redesigns of circuit board substrates and load-cell housings across European supply chains. Manufacturers must validate alternative alloys and bio-based plastics without compromising gram-level precision. German and French OEMs are responding by vertically integrating materials testing to accelerate compliance timelines.
Corporate wellness procurement is consolidating vendor relationships around single-platform contracts that bundle scales with wearables and telehealth access. Traditional retail channel volumes are compressing as employers and insurers negotiate direct OEM relationships. This concentration is most visible in United States enterprise accounts, where HIPAA-aligned data architecture has become a table-stakes requirement rather than a premium feature.
Smart Nutrition Scale Market Segmentation
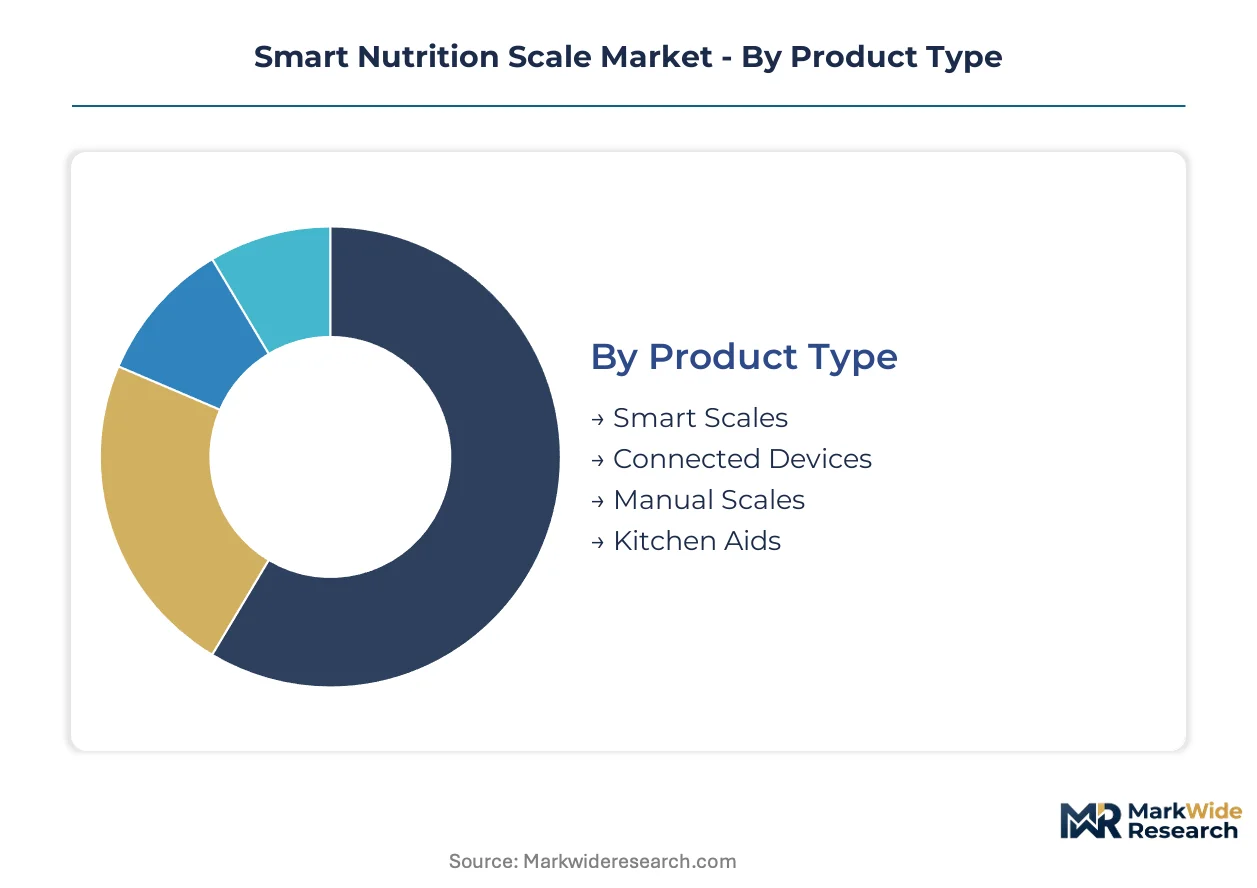
Smart nutrition scale segmentation reveals divergent margin architectures across hardware tiers and connectivity protocols. Product type and technology choices determine whether vendors capture value through premium ecosystem lock-in or mass-market volume turnover.
Product Type:
Margin pools concentrate in connected hardware that sustains recurring data-service relationships rather than one-time device sales.
- Smart Scales:Load-cell sensors paired with microcontrollers and BLE transceivers deliver gram-level precision while synchronizing intake data to fitness platforms. Fitness enthusiasts and weight-management clinics in the United States and Germany drive replacement cycles as software ecosystems deepen integration.
- Connected Devices:Multi-sensor platforms incorporating bioelectrical impedance analysis command wellness-club and corporate procurement premiums. HIPAA-aligned data architecture has become a mandatory specification for United States enterprise accounts bundling hardware with telehealth access.
- Manual Scales:Strain-gauge hardware without wireless connectivity serves price-sensitive household segments through retail channels. Etekcity dominates this tier through Amazon-centric distribution control.
- Kitchen Aids:Institutional foodservice peripherals with API compatibility demands extend sales cycles for legacy inventory system integration. German manufacturers leverage REACH-compliant material sourcing for preferential procurement by European institutional buyers.
Smart Scales holds installed capacity. Connected Devices is rotating up the share rankings.
End User:
Volume concentrates in consumer segments while clinical and enterprise channels extract premium pricing through compliance requirements.
- Home Users:Mass-market households purchasing through e-commerce platforms prioritize smartphone ecosystem compatibility over clinical-grade accuracy. Bluetooth Low Energy enables sub-premium price points while maintaining universal device pairing.
- Fitness Enthusiasts:Proactive dietary intervention demands pull hardware sales toward integrated intake-to-action workflows. Camera-assisted food recognition is supplanting manual barcode scanning as the dominant logging method for this segment.
- Dietitians:Clinical practitioners require encrypted data architecture and diagnostic-application pairing under FDA software-as-medical-device pathways. Reimbursement eligibility for remote patient monitoring creates procurement pull.
- Restaurants:Enterprise foodservice buyers demand API compatibility with decades-old inventory management systems, compressing vendor margins through customization requirements.
Home Users commands current volume leadership. Fitness Enthusiasts is climbing the fastest as proactive health management displaces passive tracking.
Technology:
Certification cost structures and power requirements stratify competitive positioning across connectivity protocols.
- Bluetooth:BLE transceivers operating at 2.4 GHz achieve FCC Part 15 compliance with 8-14 week validation timelines, enabling rapid United States commercialization. Universal smartphone compatibility sustains mass-market volume leadership.
- Wi-Fi:Higher bandwidth enables cloud-native nutritional database queries without smartphone tethering. Kitchen aids and institutional deployments in China leverage domestic MIIT standards for low-power IoT device certification.
- NFC:Near-field pairing eliminates app-discovery friction for first-time users. European OEMs integrate NFC for tap-to-connect workflows that bypass Bluetooth pairing complexity.
- USB:Wired connectivity persists in clinical settings where electromagnetic interference concerns override convenience priorities. Dietitian office deployments specify USB for guaranteed data transmission integrity.
Bluetooth holds installed capacity. Wi-Fi is rotating up the share rankings as cloud-native architectures displace smartphone-dependent workflows.
Application:
Use case evolution is shifting value capture from measurement hardware toward predictive software and platform-locked ecosystems.
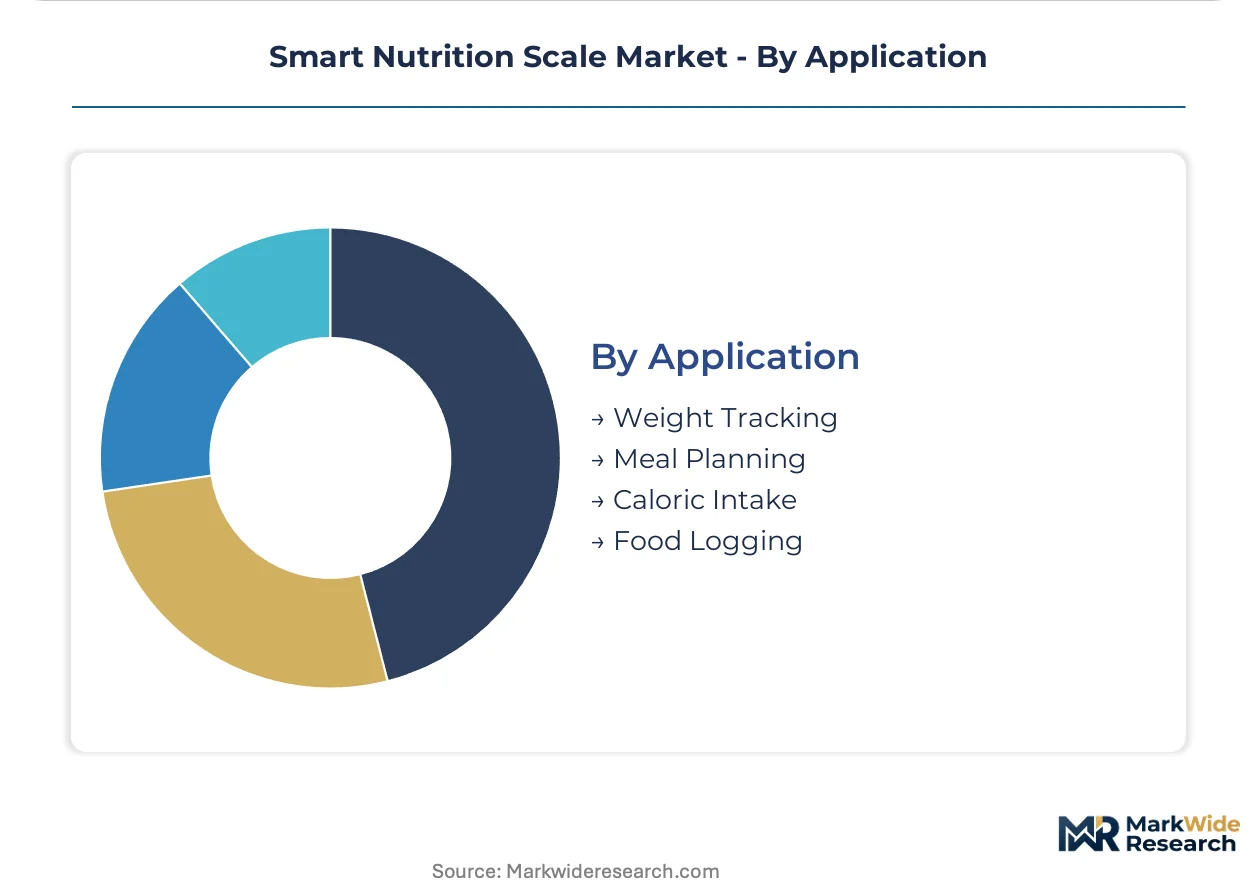
- Meal Planning:Proactive dietary intervention platforms pull hardware sales as consumers seek integrated intake-to-action workflows. This application is expanding most quickly as passive weight tracking loses relevance.
- Weight Tracking:Legacy mass-measurement functionality now serves as a commodity entry point rather than value driver. Smartphone camera-based food logging creates substitution risk for single-purpose hardware.
- Caloric Intake:Macronutrient calculation precision determines premium positioning for connected health ecosystem vendors. Withings leverages this application to sustain European and North American channel premiums.
- Food Logging:AI-driven food recognition compression of user friction is eroding subscription revenue for standalone nutrition databases. Value concentrates in integrated hardware-software bundles rather than point solutions.
Weight Tracking holds installed capacity. Meal Planning is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of precision load-cell sensors concentrate in East Asian foundries while import demand clusters in high-income markets with connected-health infrastructure. The United States, Germany, and China anchor volume absorption through divergent regulatory and procurement pathways.
United States
Fitness enthusiasts and corporate wellness programs drive hardware procurement through HIPAA-aligned data architecture requirements. FDA digital health guidance streamlines 510(k) pathways for software-as-medical-device classifications paired with nutrition-tracking hardware. Greater Boston and the Pacific Northwest host telehealth-integrated scale deployments for remote patient monitoring reimbursement pathways.
Germany
Institutional foodservice buyers in Bavaria and North Rhine-Westphalia prioritize REACH-compliant material sourcing for load-cell housings. EU Green Deal alignment positions domestic manufacturers for preferential procurement by European institutional buyers. Baden-Württemberg OEMs vertically integrate materials testing to accelerate compliance timelines for circuit board substrate redesigns.
China
Domestic MIIT standards for low-power IoT devices incentivize local production of BLE-enabled kitchen peripherals under dual carbon goals. Yangtze River Delta foundries supply precision strain-gauge components to global OEMs while facing tariff exposure. Pearl River Delta assembly clusters scale mass-market units for Amazon-centric distribution channels.
Japan
METI standards for connected appliance cybersecurity shape certification timelines for kitchen peripherals entering commercial channels. Kansai region wellness clubs adopt bioelectrical impedance-integrated scales for member retention programs. Tokyo-based insurers bundle nutrition hardware with wearable contracts under corporate wellness procurement consolidation.
United Kingdom
London and Southeast England concentrate demand from private dietitian practices requiring encrypted data architecture. GDPR compliance costs filter mass-market entrants while favoring vendors with established ISO 27001 frameworks. Midlands distribution hubs handle EU-UK transit of REACH-certified components post-Brexit customs realignment.
Smart Nutrition Scale Market Competitive Landscape
Concentration sits with ecosystem-locked premium vendors and mass-market Amazon-centric distributors rather than mid-tier generalists. Bluetooth-enabled precision tiering compresses power requirements and certification costs, enabling sub-premium price points while maintaining smartphone compatibility. Three archetypes dominate: connected-health ecosystem integrators, clinical-grade accuracy specialists, and mass-market channel controllers. Competitive moves center on backward integration into load-cell sensor sourcing and strategic partnerships with meal-planning application platforms.
Within the ecosystem-locked tier, Withings exemplifies premium positioning across European and North American channels through connected health infrastructure. Tanita Corporation anchors clinical-grade accuracy specialization with bioelectrical impedance analysis integration. Etekcity occupies the mass-market vector through Amazon-centric distribution control. These three represent divergent margin-capture strategies rather than direct price competition.
| Leading Market Players |
|---|
| Fitbit |
| Withings |
| Tanita Corporation |
| Etekcity |
| Ozeri |
| Greater Goods |
| Escali |
| iHealth |
| Smart Diet Scale |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with Yangtze River Delta foundries lock in strain-gauge sensor access and stabilize unit economics for OEMs navigating tariff volatility. These arrangements tether pricing visibility to load-cell manufacturing concentration while forcing trade-offs between inventory carrying costs and supply security.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on FDA 510(k) certification tier and Bluetooth Low Energy integration depth. Pricing pressure stems from Amazon-centric mass-market entrants compressing margins at the economy tier. Home users exhibit highest price sensitivity while corporate wellness procurement demonstrates lowest elasticity due to HIPAA compliance mandates.
Supply Chain Analysis
Strait of Malacca transit underwrites critical semiconductor and sensor flows from East Asian foundries to global assembly points. Manufacturing concentrates in China, Vietnam, and Malaysia for circuit board substrates and load-cell housings. Raw material dependencies span aluminum alloys for strain gauges, lithium for BLE power cells, and epoxy resins for housing compounds. Single-source vulnerability in precision sensor fabrication exposes OEMs to disruption. Distribution runs through Amazon FBA networks and direct enterprise procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA digital health guidance streamlining software-as-medical-device pathways is accelerating hardware-software convergence, creating a high-growth disruption window for stakeholders who align with clinical reimbursement infrastructure.
For Market Incumbents: Compound ecosystem lock-in by deepening meal-planning application integrations and securing backward integration into load-cell sensor sourcing. Camera-assisted food recognition from smartphone native apps threatens hardware relevance; counter by embedding AI recognition directly into scale firmware. Prioritize REACH-compliant material certification to defend European institutional procurement share. For New Entrants and Emerging Players: Lead with HIPAA-aligned data architecture to penetrate United States remote patient monitoring reimbursement channels. The clinical dietitian segment remains underpenetrated relative to fitness enthusiasts. Deploy direct-to-clinic sales models bypassing Amazon margin compression. For Investors and Strategic Acquirers: BLE-enabled kitchen peripheral specialists with captive sensor relationships offer superior acquisition profiles against pure software plays. Long-term viability hinges on platform-locked recurring revenue rather than transactional hardware margins. Watch for MIIT standard alignment in Chinese domestic production as inflection signal for cost-competitive supply base expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Meal Planning Platform Integration | Deepens intake-to-action workflows for Fitness Enthusiasts and Dietitians segments. |
| Backward Integration into Load-Cell Sourcing | Mitigates single-source vulnerability from Yangtze River Delta concentration. |
| HIPAA-Aligned Data Architecture Certification | Unlocks United States corporate wellness and remote patient monitoring procurement. |
| REACH-Compliant Material Redesign | Secures preferential positioning with German institutional foodservice buyers. |
| AI-Driven Food Recognition Embedding | Defends against smartphone camera-based substitution for passive weight tracking. |
Research Methodology
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings. The research team conducted discussions with connected health product managers, FDA regulatory consultants, hospital biomedical engineers, and Amazon third-party seller operations leads. Secondary sources encompassed FDA 510(k) device listings, FCC Part 15 certification databases, EU REACH substance restriction updates, and MIIT IoT standard publications. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Sensitivity analysis around BLE adoption curves and clinical reimbursement pathway expansion shapes the analytical framework. Segmentation modeling spans product type, connectivity protocol, end-user archetype, and application use case across the projection horizon. CAGR derivation incorporated hardware replacement cycle analysis, smartphone ecosystem penetration rates, and enterprise wellness contract renewal patterns. Forecast inputs included load-cell sensor cost trajectories and cybersecurity labeling requirement evolution.
Forecasts assume regulatory continuity in FDA digital health guidance and EU Green Deal material restrictions; material policy shifts would require re-modeling. Specific risks encompass FCC Part 15 timeline extensions, REACH substance ban accelerations, and smartphone native app feature expansion. Practitioners should keep alternative scenarios live as cybersecurity certification fragmentation and tariff regime adjustments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Feed Prebiotics Market
Nutritional Supplements
Global Reishi Mushroom Extracts Market
Nutritional Supplements
Europe Amino Acid in Dietary Supplements Market
Nutritional Supplements
Middle East and Africa Nutraceutical Excipients Market
Nutritional Supplements
Marine Supplements Market
Nutritional Supplements
Omega-3 Concentrates Market
Nutritional Supplements
Medium Chain Triglyceride (MCT) Food Market
Nutritional Supplements
Nutritional Yeast Market
Nutritional Supplements
Vegan Collagen Powder Market
Nutritional Supplements
Argentina Nutraceuticals Market
Nutritional Supplements
Liuweidihuang Market
Nutritional Supplements
Organic Whey Protein Market
Nutritional Supplements
Fiber Supplements Market
Nutritional Supplements
Global Hangover Rehydration Supplements Market
Nutritional Supplements
Vitamin D Supplements Market
Nutritional Supplements
Medicinal Mushroom Supplement Market