
 EPA and DHA Market | 2026-2036
EPA and DHA Market Size, Share, and Industry Trends Forecast 2026-2036
EPA and DHA Market Intelligence
Subscription-based replenishment programs for omega-3 supplements is shifting how EPA and DHA reach end consumers, converting one-time purchases into recurring revenue streams. Croda International Plc. leverages its pharmaceutical-grade lipid expertise to serve prescription omega-3 drugmakers. Aker BioMarine ASA anchors Antarctic krill oil supply through its vertically controlled harvesting fleet. KD Pharma Group specializes in ultra-concentrated EPA formulations for medical nutrition applications.
Eicosapentaenoic acid (EPA) and docosahexaenoic acid (DHA) are long-chain omega-3 polyunsaturated fatty acids with 20 and 22 carbon atoms respectively, typically extracted via molecular distillation or supercritical CO2 processing from marine biomass, then concentrated to 60-90% purity for therapeutic use. Marine oil dominates commercial supply chains due to established fisheries infrastructure, though algal oil attracts investment as a vegetarian alternative with controlled contaminant profiles. Softgel formulations occupy the largest share of consumer-facing product forms, while liquid formats gain traction in pediatric and geriatric applications where swallowing difficulties limit capsule use.
FDA qualified health claims for omega-3 cardiovascular benefits create a dual-track market structure separating regulated pharmaceutical pathways from dietary supplement channels. EFSA novel food approvals and EU Green Deal sustainable fishing mandates shape European sourcing requirements and traceability obligations. Stakeholders must monitor evolving pharmaceutical-grade certification standards and algae fermentation yield improvements as these factors determine which production platforms capture margin expansion in prescription and clinical nutrition segments.
Market Dynamics
Pharmaceutical-grade certification requirements are bifurcating the EPA and DHA supply base, separating API-capable producers from commodity-grade refiners and redistributing margin capture toward prescription drug pipelines.
Growth Catalysts
- FDA Qualified Health Claims Framework:The cardiovascular benefit pathway accelerates prescription omega-3 drug development in the United States, pulling API demand through regulated channels.
- Algal Oil Fermentation Yields:Controlled-environment production platforms in China eliminate marine contaminant concerns and secure vegetarian supply chains for domestic supplement brands.
- Pediatric and Geriatric Liquid Formats:Swallowing-difficulty populations drive formulation diversification beyond softgel dominance, expanding addressable patient bases.
Market Restraints
- Antarctic Krill Harvest Concentration:Single-fleet vertical control over raw biomass creates supply vulnerability and price inelasticity for krill-derived omega-3.
- Marine Oil Input Volatility:Wild catch fluctuations and fishery quota restrictions transmit directly to refined EPA and DHA feedstock costs.
- EFSA Novel Food Approval Timelines:Extended safety dossier reviews delay algal strain commercialization and freeze European market entry for new suppliers.
Strategic Opportunities
- Medical Nutrition Infusion:Ultra-concentrated EPA formulations for clinical enteral and parenteral applications command pricing premiums unavailable in consumer supplements.
- Subscription Replenishment Platforms:Direct-to-consumer recurring revenue models convert episodic supplement purchases into predictable demand streams with lower customer acquisition costs.
- EU Green Deal Traceability Mandates:Sustainable fishing certification requirements favor integrated harvesters with documented chain-of-custody systems over commodity traders.
Industry Challenges
- Pharmaceutical-Grade cGMP Compliance:API manufacturing facility qualification demands capital intensity and technical workforce scarcity that commodity refiners cannot bridge.
- Algae Strain IP Licensing Complexity:Proprietary fermentation organisms require negotiated royalty structures that fragment technology access and slow capacity scaling.
- Multi-Regulatory Label Architecture:Divergent FDA, EFSA, and NMPA health claim frameworks force parallel product positioning and packaging configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EPA and DHA Market |
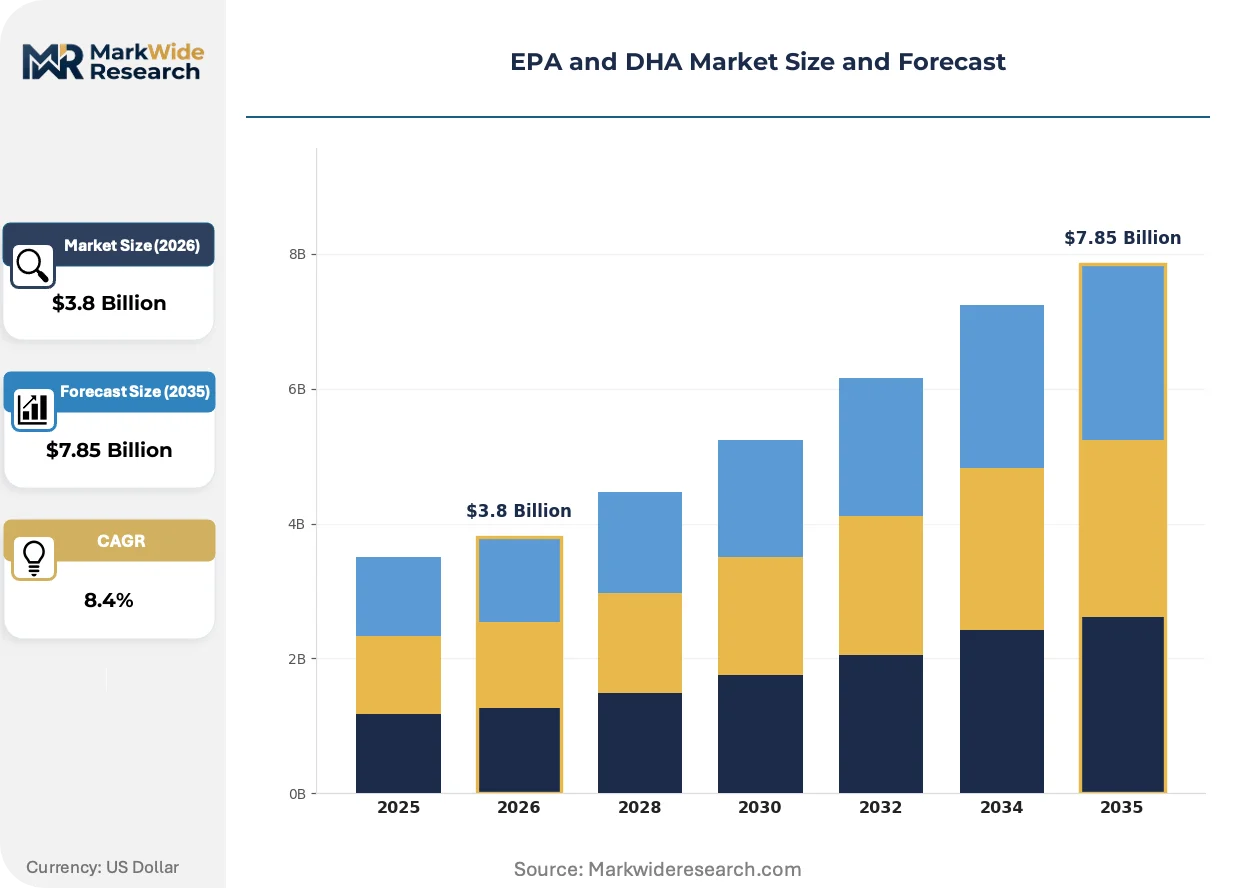
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Source Type: Marine Oil, Algal Oil, Krill Oil, Synthetic Oil Product Form: Capsules, Softgels, Liquid, Powder, Emulsions Application Area: Cardiovascular Health, Cognitive Function, Prenatal Nutrition, Joint Support, Skin Care End User: Dietary Supplements Manufacturers, Functional Food Producers, Pharmaceuticals, Personal Care Brands, Veterinary Products |
| Companies Covered | Croda International Plc., Corbion N.V., BASF SE, Aker BioMarine ASA, Golden Omega S.A., Koninklijke DSM N.V., KD Pharma Group, Organic Technologies, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EPA and DHA Market Strategic Shifts & Innovations
Production platforms and distribution architectures are simultaneously reconfiguring, with fermentation-based alternatives challenging marine extraction dominance while digital channels displace traditional retail replenishment patterns.
Supercritical CO2 processing technology is modularizing EPA and DHA concentration workflows, enabling mid-scale refiners to deploy pharmaceutical-grade purification without continuous distillation infrastructure. Regional API manufacturers in India and China are adopting these skid-mounted systems to bypass capital-intensive molecular distillation investments. The technology is modularizing competitive entry barriers that previously protected large-volume marine oil processors.
EFSA novel food approvals and EU Green Deal sustainable fishing mandates are tightening European sourcing documentation requirements and traceability obligations. Integrated harvesters with vessel-level monitoring systems capture preferential supply contracts from brands targeting ESG-conscious consumers. Pharmaceutical and clinical nutrition segments face the steepest compliance cost escalations as batch-level sustainability certification becomes mandatory.
Subscription-based replenishment programs are displacing pharmacy and mass-market retail as the primary omega-3 acquisition channel for chronic-condition consumers. Direct-to-consumer platforms capture purchase data that enables personalized dosing recommendations and cross-selling into adjacent supplement categories. The United States exhibits the deepest channel transformation, though Chinese domestic brands are rapidly deploying comparable captive digital ecosystems.
EPA and DHA Market Segmentation
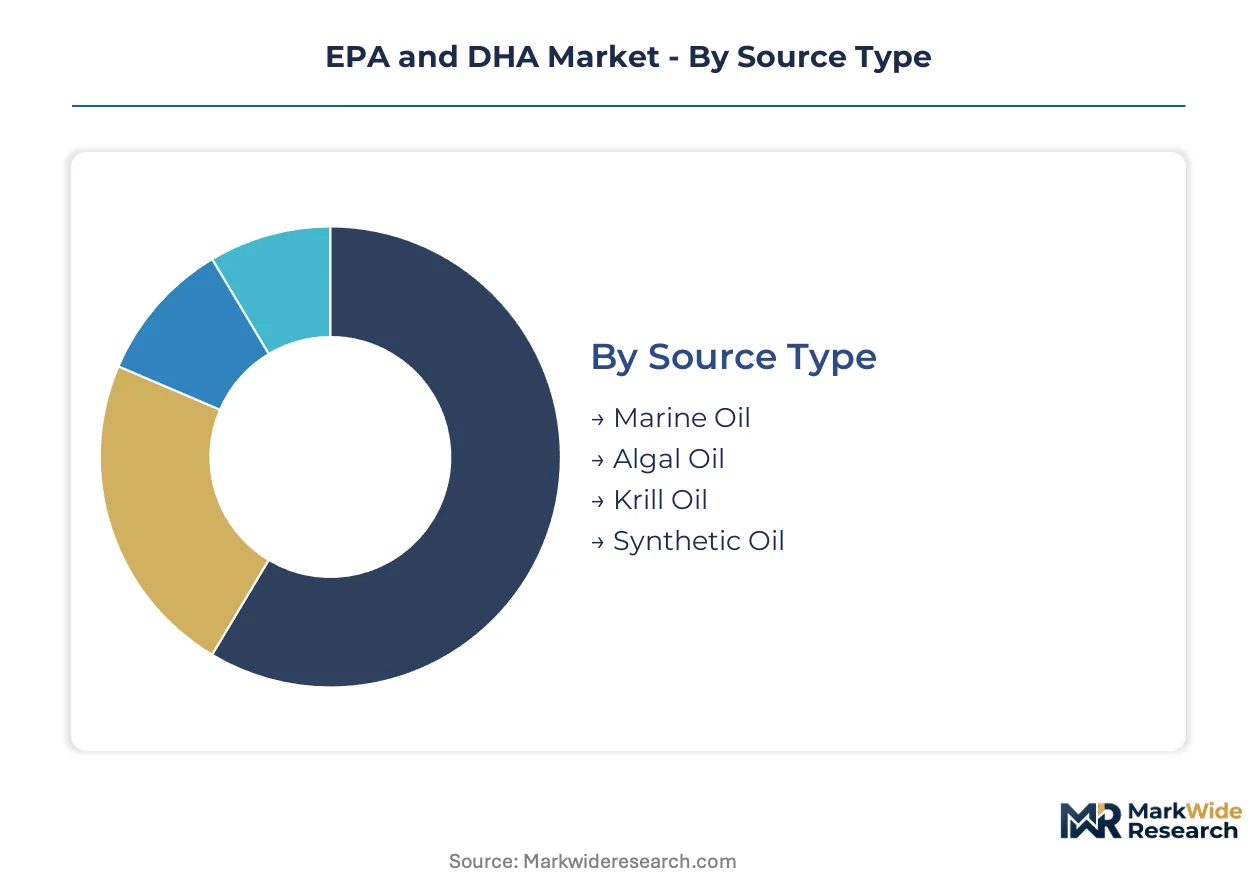
EPA and DHA segmentation reveals divergent margin structures across extraction platforms and formulation technologies. Source type determines regulatory pathway eligibility, while product form dictates addressable patient populations and channel economics.
Source Type:
Marine oil dominates standalone therapeutic applications, whereas algal and krill oils embed into premium positioning strategies.
- Marine Oil:Extracted via molecular distillation from anchovy, sardine, and mackerel fisheries, marine oil supplies 60-90% concentrated EPA/DHA fractions for pharmaceutical APIs. Demand concentrates in prescription cardiovascular drug pipelines where FDA qualified health claims validate clinical positioning.
- Algal Oil:Fermentation-derived from Schizochytrium and Crypthecodinium strains, algal oil eliminates marine contaminant concerns and secures vegetarian supply chains. Chinese domestic brands source captive algal capacity to bypass import dependency.
- Krill Oil:Antarctic biomass delivers phospholipid-bound omega-3 with superior bioavailability claims for premium supplement positioning.
- Synthetic Oil:Laboratory-synthesized EPA/DHA from petrochemical precursors serves research applications and specialized medical nutrition where marine sourcing faces religious or allergen restrictions.
Volume placements concentrate in Marine Oil; the faster expansion belongs to Algal Oil.
Product Form:
Softgel encapsulation captures mainstream supplement economics, while liquid and emulsion formats unlock pediatric and geriatric access barriers.
- Softgels:Gelatin or plant-based shells containing 500-1000mg EPA/DHA doses dominate retail shelf presence and subscription replenishment programs. US direct-to-consumer platforms favor softgels for shipping stability and dosing standardization.
- Liquid:Flavored oil suspensions enable precise pediatric dosing and geriatric administration where dysphagia limits capsule use. Clinical nutrition services in Germany and France specify liquid formats for enteral feeding protocols.
- Capsules:Two-piece hard shells accommodate powder-filled EPA/DHA for combination products with vitamins or minerals.
- Powder:Microencapsulated and free-flowing grades integrate into functional food matrices including infant formula and sports nutrition bars.
- Emulsions:Water-dispersible omega-3 concentrates enhance bioavailability marketing claims and beverage fortification applications.
Softgels anchor current volume; liquid formats are climbing the fastest as swallowing-difficulty populations expand.
Application Area:
Cardiovascular endpoints drive prescription drug development, while cognitive and prenatal applications anchor consumer supplement loyalty.
- Cardiovascular Health:EPA-specific formulations target triglyceride reduction with FDA-approved drug pathways distinguishing pharmaceutical from supplement positioning. US prescribing patterns favor high-dose EPA therapies for statin-intolerant patients.
- Cognitive Function:DHA concentrates support neurodevelopment and aging brain health claims, with EFSA novel food approvals shaping European product architecture.
- Prenatal Nutrition:DHA supplementation during pregnancy and lactation commands premium pricing through obstetrician recommendation channels.
- Joint Support:Anti-inflammatory positioning competes with glucosamine and collagen in osteoarthritis management segments.
- Skin Care:Topical and ingestible beauty applications leverage omega-3 barrier function claims in Korean and Japanese cosmetic markets.
Cardiovascular Health holds the largest revenue footprint; Cognitive Function is gaining share fastest through aging-population targeting.
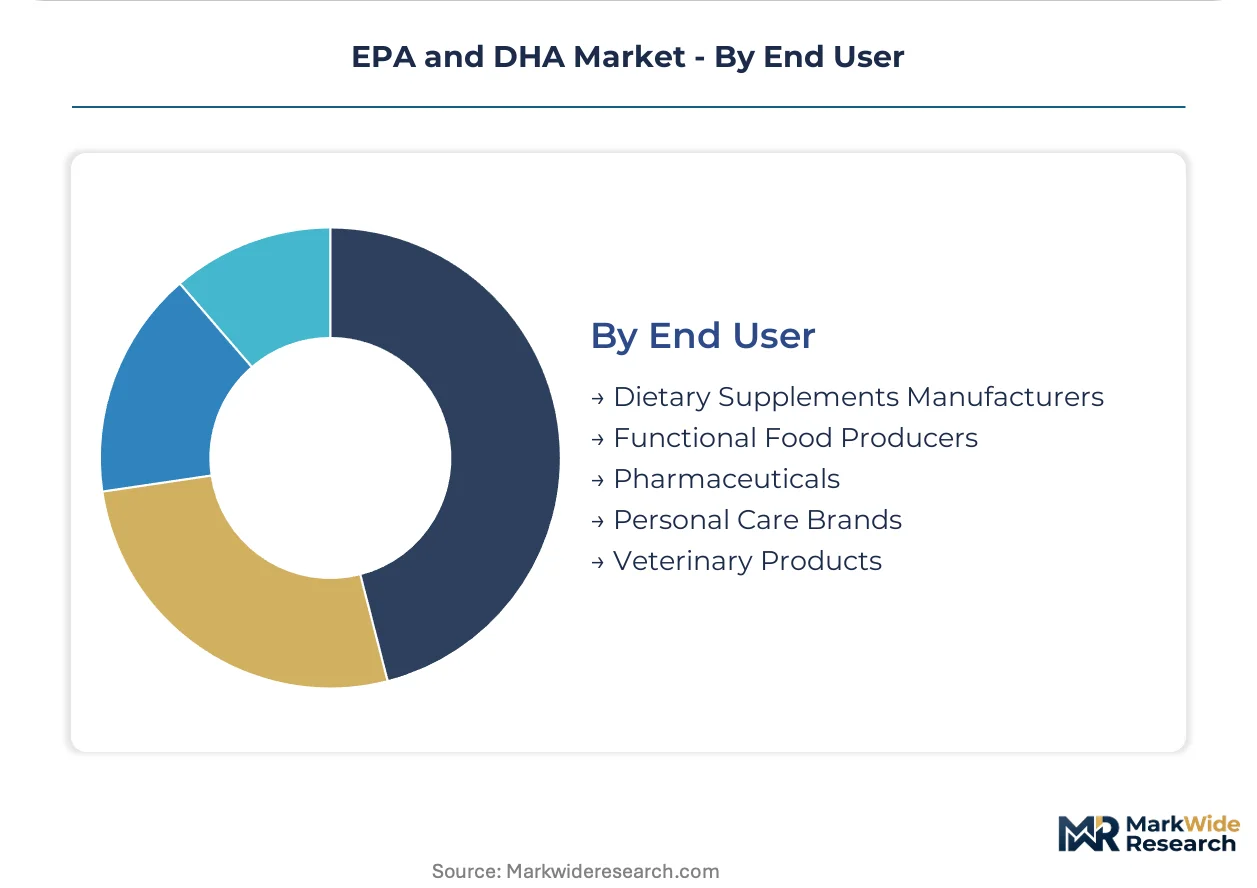
End User:
Pharmaceutical manufacturers extract maximum margin through API supply agreements, while supplement and food producers compete on brand differentiation.
- Pharmaceuticals:cGMP-certified EPA/DHA APIs enter prescription drug pipelines requiring batch-level documentation and stability testing that commodity refiners cannot supply.
- Dietary Supplements Manufacturers:Brand marketers source concentrated omega-3 for private-label and branded capsule, softgel, and gummy formulations.
- Functional Food Producers:Bakery, dairy, and beverage fortification demands odor-masked and oxidation-stable omega-3 grades with extended shelf-life performance.
- Personal Care Brands:Cosmetic formulators specify ultra-pure DHA for topical anti-aging and barrier repair product lines.
- Veterinary Products:Pet supplement and aquaculture feed applications utilize lower-grade marine oils with reduced concentration requirements.
Pharmaceuticals command the steepest pricing tier; Functional Food Producers show the steepest expansion trajectory as fortification regulations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors the world's fastest-expanding algal oil fermentation corridor, with Chinese domestic brands sourcing captive omega-3 supplies from Yangtze River Delta bioreactor clusters.
United States
Prescription omega-3 drug development concentrates API demand in New Jersey and Massachusetts pharmaceutical corridors. The FDA's qualified health claims framework shapes cardiovascular product positioning and label architecture. Boston-area clinical nutrition services specify liquid EPA/DHA formats for enteral feeding protocols.
China
Domestic supplement brands source captive algal oil from Schizochytrium fermentation facilities in Jiangsu and Zhejiang provinces. NMPA novel food approvals accelerate strain commercialization timelines for local producers. Qingdao marine oil refiners supply concentrated fractions to Asia-Pacific pharmaceutical formulators.
Germany
EFSA novel food dossier reviews and EU Green Deal traceability mandates tighten sourcing documentation for Hamburg and Bremen-based refiners. Bavarian medical nutrition specialists command premium pricing for ultra-concentrated EPA formulations. Frankfurt pharmaceutical distributors batch-test omega-3 APIs for cGMP compliance.
India
Regional API manufacturers in Hyderabad and Mumbai adopt skid-mounted supercritical CO2 systems to bypass capital-intensive molecular distillation. CDSCO pharmaceutical-grade certification requirements separate API-capable producers from commodity refiners. Gujarat marine oil processors supply concentrated fractions to European supplement brands.
EPA and DHA Market Key Industry Players
Capital-heavy producers compete with asset-light designers across extraction platform choices, with fermentation-based algal specialists facing off against vertically integrated marine harvesters. The vendor base stratifies across three tiers: pharmaceutical-grade API suppliers, premium-positioned krill oil harvesters, and commodity marine oil refiners. Dominant competitive moves include backward integration into biomass supply and technology licensing for modular purification systems.
Among European-headquartered chemical conglomerates, BASF SE and Koninklijke DSM N.V. exemplify diversified nutrition ingredient platforms that span omega-3 alongside adjacent lipid categories. Aker BioMarine ASA represents the vertically controlled harvesting archetype, with Antarctic fleet operations anchoring krill-derived supply chains. These three entities occupy positions across distinct competitive vectors—synthetic chemistry, nutritional ingredients, and marine biomass control—illustrating how source-type specialization fragments market structure.
| Leading Market Players |
|---|
| Croda International Plc. |
| Corbion N.V. |
| BASF SE |
| Aker BioMarine ASA |
| Golden Omega S.A. |
| Koninklijke DSM N.V. |
| KD Pharma Group |
| Organic Technologies |
| Archer Daniels Midland Company |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap marine oil refiners in Peru and Morocco anchor feedstock procurement through long-standing fishery relationships, converting quota stability into pricing discipline that resists spot-market volatility. Their ownership structure insulates inventory decisions from quarterly earnings pressure, allowing contracted offtake pricing that undercuts private-equity-rolled competitors during harvest fluctuations.
Pricing Analysis
Value-based pricing anchored to cardiovascular outcome claims separates pharmaceutical-grade EPA APIs from commodity supplement grades. Three-tier pricing structure across premium, standard, and economy levels tracks certification intensity: cGMP-batched APIs command maximum premiums, algal-derived vegetarian grades occupy mid-tier positioning, and unrefined marine oils compete on volume scale. Cost compression in standard-tier softgels is intensifying because Chinese fermentation capacity expansion floods mid-market supply. Functional food producers exhibit highest price sensitivity due to thin fortification margins, while prescription drug developers accept premium pricing for batch-documentation security.
Supply Chain Analysis
Wild catch biomass rests on Peruvian anchovy, Moroccan sardine, and Norwegian mackerel fisheries for marine oil fractionation. Algal fermentation draws from Schizochytrium and Crypthecodinium strain banks, phospholipid inputs, and bioreactor-grade glucose feedstocks. Single-fleet vertical control over Antarctic krill harvest creates irreplaceable-source vulnerability for phospholipid-bound omega-3 supply. Distribution runs through pharmaceutical distributors for API grades, direct-to-consumer platforms for subscription replenishment, and mass-market retail for commodity softgels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EPA and DHA market operates as a cost-of-compliance story where FDA pharmaceutical-grade cGMP certification creates a barrier-to-entry moat that protects incumbent API suppliers from commodity refiners. EFSA novel food approval timelines and EU Green Deal traceability mandates compound European compliance burdens, favoring producers with pre-invested documentation infrastructure.
For Market Incumbents: Deepen backward integration into vessel-level harvest monitoring to satisfy EU Green Deal chain-of-custody requirements and preempt traceability-driven supply disqualification. Expand cGMP-certified fermentation capacity in Jiangsu province to capture NMPA-fast-tracked algal strain approvals before domestic Chinese competitors scale. Threat of modular supercritical CO2 adoption by Indian mid-caps demands defensive patent positioning around purification process IP.
For New Entrants and Emerging Players: Subscription-based direct-to-consumer platforms offer the lowest customer-acquisition-cost entry path for chronic-condition consumers seeking personalized dosing regimens. Target liquid format white space in German and French clinical nutrition services where dysphagia-addressing enteral protocols specify EPA/DHA emulsions. Pediatric precision-dosing applications remain underpenetrated by incumbent softgel-centric portfolios. Go-to-market leverage: partner with hospital discharge planners for post-cardiac-event prescription-to-supplement transition programs.
For Investors and Strategic Acquirers: Distressed-cycle entries favor fermentation-technology specialists with stranded algal strain IP in China facing NMPA approval delays but possessing scalable bioreactor infrastructure. Long-term viability centers on dual-use platforms serving both pharmaceutical API and premium vegetarian supplement channels. Signal to watch: EFSA novel food approval acceleration for Schizochytrium strains would unlock European market entry and re-rate algal-derived asset valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade cGMP Certification | FDA batch-documentation requirements separate API-capable producers from commodity refiners in prescription drug pipelines. |
| Algal Fermentation Scale-Up | Schizochytrium strain commercialization in Yangtze River Delta bioreactor clusters secures vegetarian supply chains for Chinese domestic brands. |
| Subscription Platform Deployment | Direct-to-consumer recurring revenue models convert episodic supplement purchases into predictable demand with lower acquisition costs. |
| EU Green Deal Traceability Compliance | Vessel-level monitoring systems capture preferential supply contracts from ESG-conscious European supplement brands. |
| Modular Supercritical CO2 Adoption | Skid-mounted purification systems enable mid-scale Indian refiners to bypass capital-intensive molecular distillation infrastructure. |
Research Approach
Multi-period observation of fishery quota allocations, fermentation capacity buildouts, and prescription omega-3 drug pipeline progressions anchored the trend analysis, supplemented by interviews with pharmaceutical procurement directors, algal fermentation plant managers, supplement brand marketers, and regulatory affairs specialists at FDA and EFSA. Secondary validation drew from FDA Orange Book filings, EFSA novel food approval registers, NMPA strain commercialization databases, and EU fishing quota documentation. Bottom-up triangulation across extraction platform economics and top-down demand modeling across application segments ensured cross-verified volume and value estimates.
Input-output matrix framing connected raw biomass availability through concentration technology yields to end-use pricing tiers across the projection horizon. Segmentation dimensions modeled encompassed source type, product form, application area, and end-user industry, with regional regulatory cluster effects layered across geographies. CAGRs derived from fitted growth curves applied to disclosed capacity expansions and prescription drug approval timelines. Industry-specific forecast inputs incorporated algal fermentation yield improvement trajectories and marine oil input cost volatility indices.
Inputs from fishery management organizations and pharmaceutical API contract manufacturers were available through the study window; gaps in proprietary strain-level fermentation economics introduce uncertainty bands around algal oil cost curve projections. Forecasts reflect documented assumptions regarding NMPA approval velocity and EFSA novel food dossier processing rates. Regulatory timeline delays, krill harvest quota reductions, or breakthrough synthetic biology pathways for EPA/DHA production warrant ongoing watch as forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Bee Pollen Supplements Market
Nutritional Supplements
Algae Supplements Market
Nutritional Supplements
Europe Botanical Supplements Market
Nutritional Supplements
Postbiotic Supplements Market
Nutritional Supplements
Lactoferrin Supplements Market
Nutritional Supplements
Global Oncology Nutrition Market
Nutritional Supplements
Health Supplements Market
Nutritional Supplements
Hair Growth Supplements Market
Nutritional Supplements
Middle-East and Africa Dietary Supplement Market
Nutritional Supplements
Grass-Fed Collagen Market
Nutritional Supplements
Europe Collagen Supplements Market
Nutritional Supplements
Middle East and Africa Nutricosmetics Market
Nutritional Supplements
Smart Nutrition Scale Market
Nutritional Supplements
Prenatal Supplements Market
Nutritional Supplements
Middle East and Africa Nutraceutical Excipients Market
Nutritional Supplements
Oyster Shell Calcium Market