
 Lactoferrin Products Market | 2026-2036
Lactoferrin Products Market Size, Share, and Industry Trends Forecast 2026-2036
Lactoferrin Products Market Insights
Infant formula manufacturers are unwinding long-standing reliance on commodity whey processors as healthcare providers and nutritionists demand higher-purity lactoferrin for immune-support applications. Royal FrieslandCampina leverages its Dutch dairy cooperative structure to sustain vertical integration from raw milk to fractionated protein. Synlait Milk Ltd anchors its position through pharmaceutical-grade extraction capacity in New Zealand, while Fonterra Co-operative Group competes on manufacturing scale across Australasian spray-drying facilities.
Lactoferrin is an iron-binding glycoprotein comprising approximately 690 amino acid residues, typically extracted from bovine whey via cation exchange chromatography and applied for its antimicrobial, anti-inflammatory, and iron-regulation properties in human and animal nutrition. Powder form dominates current output due to superior stability in infant formula and dietary supplement matrices, while capsules represent the fastest-growing delivery format among individual consumers seeking targeted immune support. Functional foods command the deepest margin pools as manufacturers embed lactoferrin into positioned premium dairy beverages with validated health claims.
The EU Novel Food Regulation and EFSA health claim frameworks shape product standardization across European markets, while China's NMPA and national food safety standards govern import access and clinical-grade specifications for pharmaceutical applications. The US FDA GRAS notification pathway and FSMA preventive controls further segment market entry requirements by intended use category. Stakeholders must monitor evolving purity thresholds and regional claim substantiation rules to align capacity investments with addressable demand pools.
Market Dynamics
The EU Novel Food Regulation is compressing legacy supply chains as German infant formula manufacturers abandon commodity whey processors in favor of vertically integrated dairy cooperatives with captive fractionation capacity.
Growth Catalysts
- Immune-positioned infant nutrition:Pediatricians in China are prescribing lactoferrin-fortified formulas for at-risk neonates, creating clinical-grade demand that outstrips domestic whey processing capacity.
- EFSA health claim substantiation:Validated antimicrobial and iron-regulation claims enable premium positioning in European functional dairy beverages, expanding addressable margin pools beyond commodity protein markets.
- Cation exchange chromatography advances:Continuous processing systems are reducing extraction losses from bovine whey, improving yield economics for mid-scale dairy processors entering the fractionation segment.
Market Restraints
- Bovine whey supply concentration:New Zealand and Netherlands dairy cooperatives control approximately three-quarters of globally traded high-purity lactoferrin feedstock, creating procurement vulnerability for Asian formulators.
- Input cost volatility:Whey protein concentrate prices fluctuate with global milk powder auctions, compressing margins for non-integrated extractors without backward integration into raw milk supply.
- Regulatory friction:China's NMPA novel food registration timeline extends eighteen to twenty-four months for imported lactoferrin, delaying market entry for European and Oceanian suppliers.
Strategic Opportunities
- Pharmaceutical-grade specifications:Injectable and clinical nutrition applications in Japanese hospitals command purity premiums five to eight times above food-grade benchmarks.
- Capsule format penetration:Direct-to-consumer immune support supplements in North American e-commerce channels represent the fastest-growing delivery vector outside infant formula.
- PLI scheme alignment:India's production-linked incentive framework for nutritional ingredients offers tariff and capital subsidies for domestic lactoferrin manufacturing investments.
Industry Challenges
- Chromatography engineering talent scarcity:Protein fractionation specialists with cation exchange optimization experience command premium compensation, constraining capacity expansion timelines for new entrants.
- Multi-jurisdictional certification complexity:Simultaneous FDA GRAS notification, EU Novel Food approval, and NMPA registration require dedicated regulatory affairs infrastructure that smaller processors struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lactoferrin Products Market |
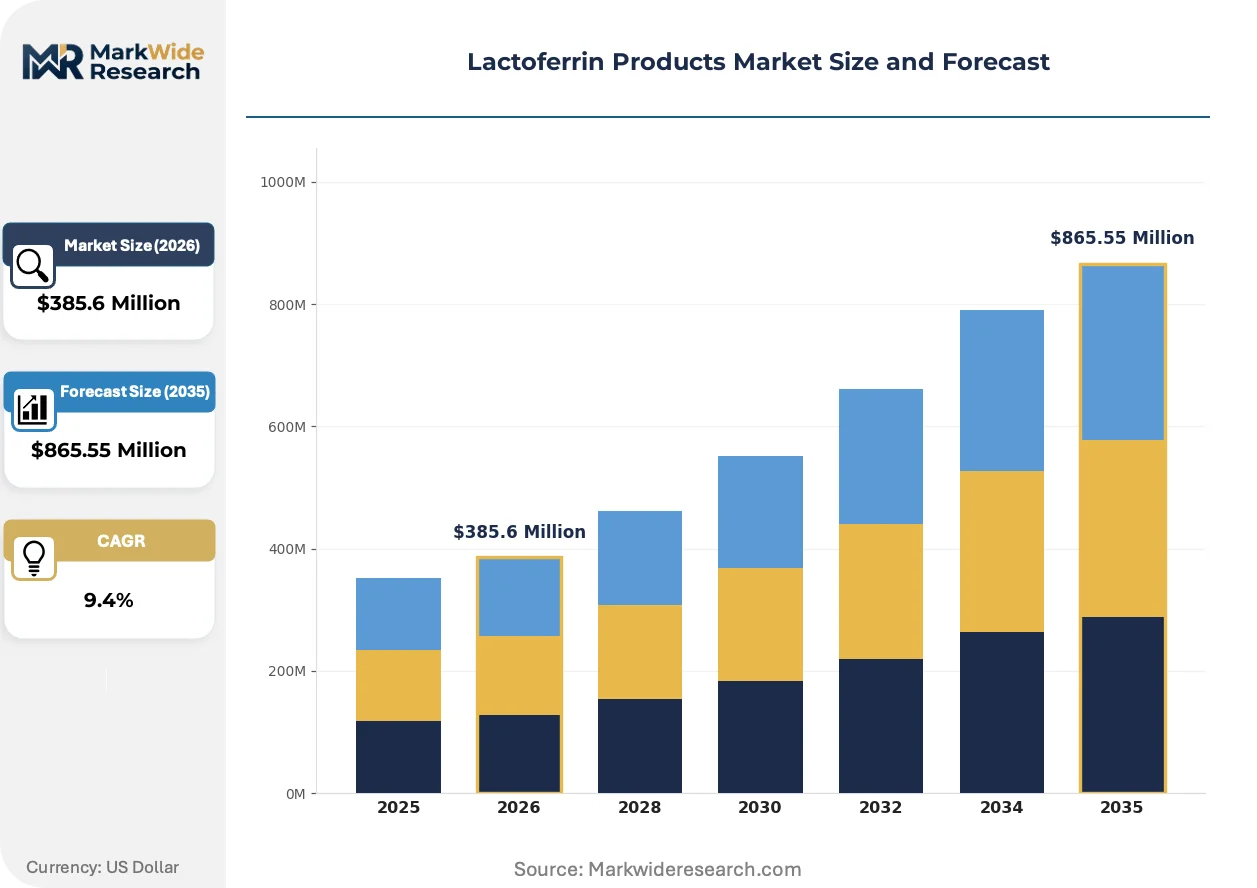
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $865.55 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Form, Powder Form, Capsules, Tablets Application: Functional Foods, Dietary Supplements, Pharmaceutical Products, Infant Formula End User: Healthcare Providers, Nutritionists, Manufacturers, Individual Consumers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | Hilmar Cheese Company, Royal FrieslandCampina, Synlait Milk Ltd, Fonterra Co-operative Group, Glanbia plc, Bega Cheese Limited, Morinaga Co., Ltd, Ingredia SA, MILEI GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lactoferrin Products Market Trends and Innovations
Continuous processing technologies and precision fermentation alternatives are compressing traditional extraction economics while regulatory convergence around purity benchmarks reshapes competitive qualification requirements.
Membrane filtration cascades paired with simulated moving bed chromatography are miniaturizing plant footprints for pharmaceutical-grade lactoferrin production. New Zealand dairy processors are retrofitting existing whey facilities with skid-mounted continuous systems that reduce solvent consumption by half. This compression enables distributed production closer to Asian demand centers without greenfield capital intensity.
REACH-compliant solvent recovery mandates are forcing European extractors to adopt closed-loop processing architectures that eliminate methanol and acetonitrile discharge. The regulation accelerates capital replacement cycles for aging batch facilities in France and Germany. Pharmaceutical-grade suppliers are responding by certifying zero-discharge operations to preempt ECHA substance restriction proposals.
Chinese infant formula brands are consolidating supplier relationships around vertically integrated dairy cooperatives with demonstrated NMPA registration success. Long-term offtake agreements now span five to seven years, displacing spot-market whey protein purchases. This concentration is most visible in Shanghai and Beijing, where domestic dairy processors are acquiring minority stakes in New Zealand fractionation assets to secure captive supply.
Lactoferrin Products Market Segmentation
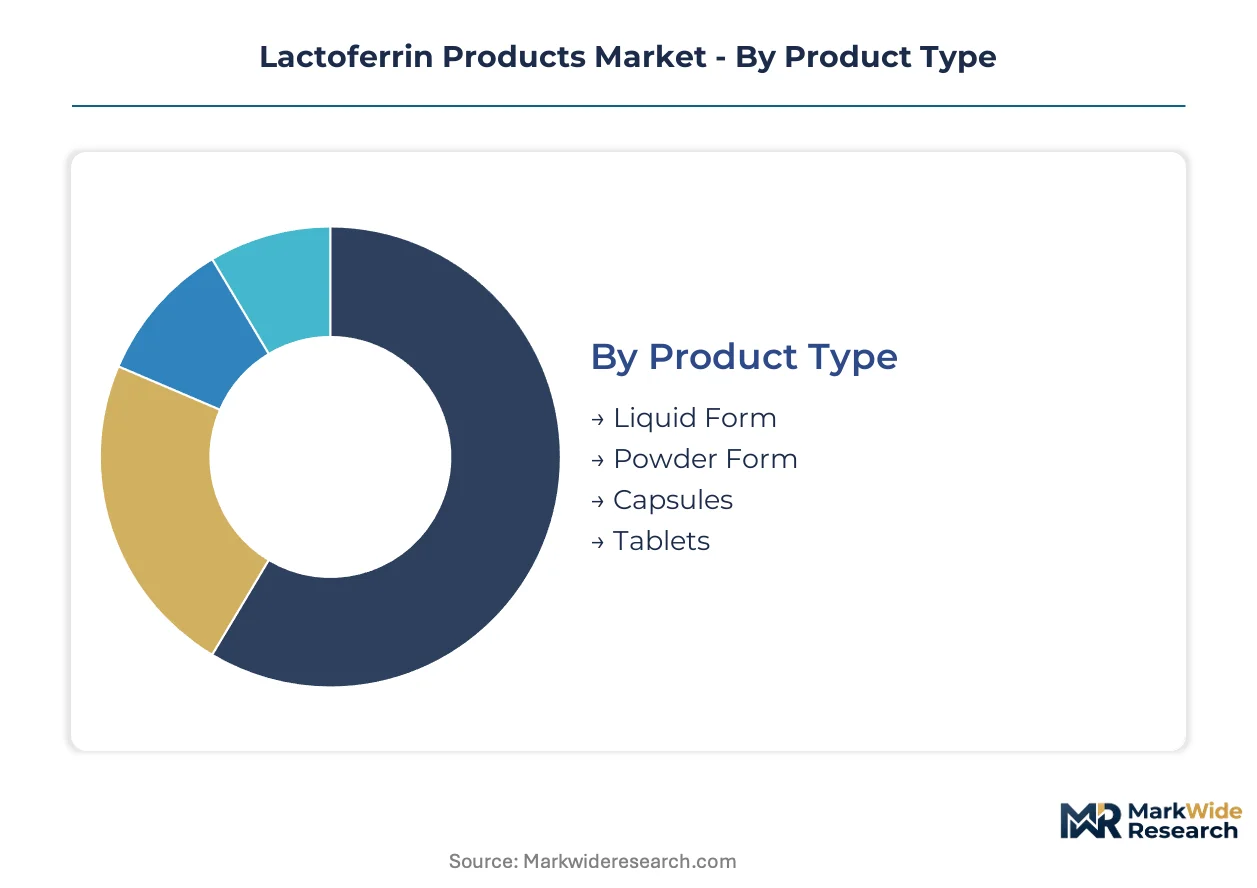
Lactoferrin product segmentation reflects divergent purity requirements across infant nutrition, pharmaceutical, and consumer wellness channels. Regulatory frameworks in China, the EU, and the US create distinct specification tiers that reshape manufacturing investments and distribution economics for each product category.
Product Type:
EFSA Novel Food approvals and FDA GRAS notifications impose divergent stability testing protocols that separate pharmaceutical-grade powder from commodity liquid concentrates.
- Powder Form:Spray-dried lactoferrin maintains bioactivity across 24-month shelf life in infant formula matrices, commanding specification premiums from Chinese dairy processors seeking NMPA registration. German manufacturers prioritize this format for immune-positioned functional foods under EU health claim frameworks.
- Capsules:Hard-shell gelatin and vegetable-derived encapsulation enables precise 100-250mg dosing for direct-to-consumer immune support, with North American e-commerce channels driving format innovation. Purity thresholds match pharmaceutical specifications as consumers self-direct toward clinical-grade supplementation.
- Liquid Form:Aqueous suspensions require cold-chain logistics and shorter shelf life, limiting deployment to clinical nutrition settings in Japanese hospitals.
- Tablets:Compressed formats face compression-force limitations that reduce bioavailability, constraining adoption to mass-market dietary supplement lines with lower purity positioning.
Established volume favors Powder Form; emerging adoption favors Capsules.
Application:
Margin structures concentrate in segments where health claim substantiation creates pricing power distinct from commodity protein benchmarks.
- Infant Formula:Neonatal immune support applications in Chinese maternity hospitals drive clinical-grade demand exceeding domestic whey fractionation capacity. Pediatric prescription patterns favor lactoferrin-fortified formulas for premature and low-birth-weight infants, with purity specifications exceeding 95% protein content.
- Functional Foods:Premium dairy beverages in the Netherlands and New Zealand embed validated antimicrobial claims into positioned consumer products, capturing margin pools unavailable to unbranded ingredient suppliers. EFSA-approved iron-regulation claims enable shelf-price premiums of 40-60% above standard probiotic yogurts.
- Dietary Supplements:Direct-to-consumer immune positioning in US and Canadian markets emphasizes convenience formats over clinical validation, with Amazon and specialized wellness platforms dominating channel economics.
- Pharmaceutical Products:Injectable and enteral nutrition applications in Japanese and South Korean hospital systems command purity premiums requiring dedicated cGMP manufacturing suites and batch-level endotoxin testing.
Functional Foods generate the deepest margin capture; Infant Formula delivers the steepest volume expansion trajectory.
End User:
Procurement authority separates institutional specification-setters from price-sensitive consumer-directed purchases.
- Healthcare Providers:Hospital pharmacy committees in Shanghai and Beijing mandate third-party purity certification for neonatal nutrition protocols, creating non-negotiable entry barriers for non-registered suppliers.
- Manufacturers:Infant formula and functional food producers in Germany and the Netherlands consolidate supplier relationships around vertically integrated cooperatives with demonstrated regulatory track records.
- Nutritionists:Registered dietitian recommendations in North American clinical practice drive consumer trial of capsule formats, though reimbursement limitations constrain sustained prescription volume.
- Individual Consumers:Self-directed immune supplementation via Amazon and iHerb prioritizes unit economics and review velocity over clinical validation, with subscription models capturing recurring revenue.
Healthcare Providers enforce the tightest specification discipline; Individual Consumers expand addressable volume most rapidly.
Distribution Channel:
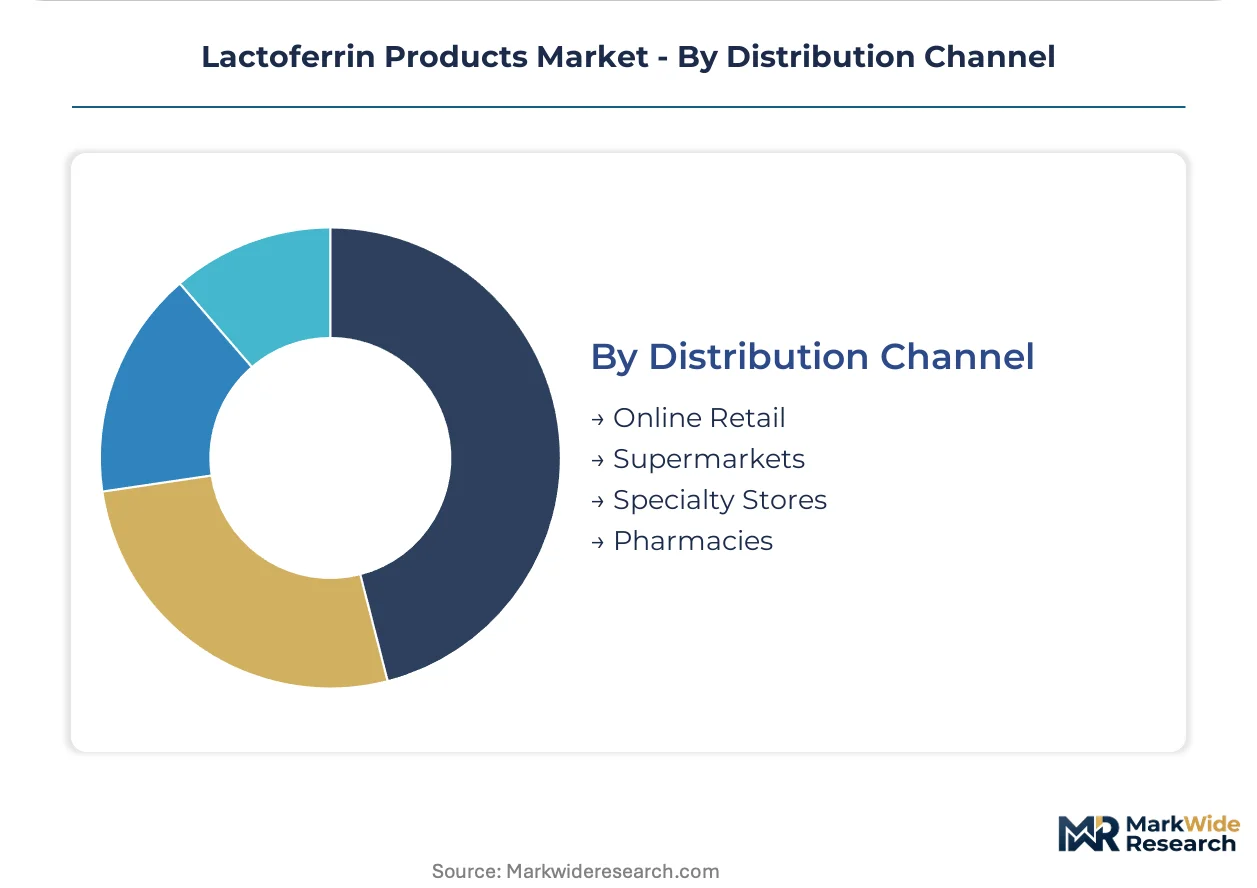
Channel selection determines regulatory exposure and margin retention for finished product suppliers.
- Pharmacies:Hospital and retail pharmacy networks in China and Japan require NMPA or PMDA registration for lactoferrin-containing products, filtering out unbranded commodity suppliers.
- Online Retail:Amazon, Tmall, and specialized supplement platforms enable direct-to-consumer immune positioning with minimal regulatory friction for food-grade formulations.
- Specialty Stores:Natural products retailers in the US and Canada emphasize non-GMO and grass-fed sourcing claims, with staff training programs driving conversion of premium-priced capsules.
- Supermarkets:Mass-market grocery distribution in Europe and Australasia concentrates lactoferrin-fortified products in premium dairy aisles, with slotting fees favoring established cooperative brands.
Pharmacies maintain the highest barrier to entry; Online Retail offers the most scalable customer acquisition economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Zealand dairy cooperatives export pharmaceutical-grade lactoferrin to Chinese infant formula manufacturers under long-term offtake agreements. German processors source from Dutch vertically integrated suppliers as the EU Novel Food Regulation tightens purity benchmarks.
China
Domestic dairy processors in Shanghai and Beijing seek captive lactoferrin supply as pediatricians prescribe immune-fortified formulas for at-risk neonates. NMPA novel food registration timelines extend eighteen to twenty-four months for imported material. Yangtze River Delta infant formula clusters are acquiring minority stakes in New Zealand fractionation assets to bypass procurement bottlenecks.
Germany
Infant formula manufacturers in Bavaria and North Rhine-Westphalia unwind legacy commodity whey procurement patterns. EFSA health claim substantiation requirements favor suppliers with validated antimicrobial and iron-regulation documentation. Frankfurt-area functional food developers embed lactoferrin into premium dairy beverages with shelf-price premiums exceeding standard probiotic lines.
New Zealand
Dairy cooperatives control approximately three-quarters of globally traded high-purity lactoferrin feedstock. Canterbury region processors retrofit existing whey facilities with continuous cation exchange systems that halve solvent consumption. Synlait Milk anchors pharmaceutical-grade extraction capacity while Fonterra leverages Australasian spray-drying scale.
United States
Direct-to-consumer capsule demand concentrates in California and New York Metro e-commerce corridors. FDA GRAS notification pathways segment market entry by intended use category. Amazon and specialized wellness platforms drive format innovation for immune support supplements outside infant formula channels.
Japan
Hospital pharmacy committees in Tokyo and Osaka mandate third-party purity certification for neonatal nutrition protocols. PMDA registration requirements filter out unbranded commodity suppliers for injectable and enteral nutrition applications. Kanto region clinical nutrition commands purity premiums five to eight times above food-grade benchmarks.
Lactoferrin Products Market Competitive Landscape
Listed leaders compete with private specialists across regulatory certification capacity and backward integration depth. The vendor base concentrates around dairy cooperatives with captive fractionation infrastructure and mid-scale extractors with pharmaceutical-grade chromatography suites. Three archetypes dominate: vertically integrated cooperatives controlling raw milk-to-protein pipelines, specialist fractionators with cGMP-certified facilities, and commodity whey processors upgrading purity capabilities. Competitive moves center on long-term offtake agreements with Asian infant formula manufacturers and retrofit investments in continuous processing systems.
Within the cooperative archetype, Fonterra Co-operative Group and Royal FrieslandCampina exemplify upstream control over raw milk supply combined with multi-jurisdictional regulatory track records. Synlait Milk Ltd occupies a position among pharmaceutical-grade specialists, while Hilmar Cheese Company and Glanbia plc represent listed entities with scale-driven manufacturing footprints across multiple protein fractionation lines.
| Leading Market Players |
|---|
| Hilmar Cheese Company |
| Royal FrieslandCampina |
| Synlait Milk Ltd |
| Fonterra Co-operative Group |
| Glanbia plc |
| Bega Cheese Limited |
| Morinaga Co., Ltd |
| Ingredia SA |
| MILEI GmbH |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four-month NMPA registration timelines for imported lactoferrin concentrate procurement leverage among Chinese infant formula manufacturers, compressing spot-market liquidity and amplifying contract-price premiums for pre-qualified suppliers with demonstrated regulatory track records.
Pricing Analysis
Batch-processing versus continuous-extraction technology-generation pricing gaps separate pharmaceutical-grade premiums from commodity whey-protein benchmarks. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certification levels anchors contract negotiations, with purity thresholds and endotoxin-testing protocols as primary price differentiation drivers. Pricing pressure stems from whey protein concentrate auction volatility, eroding extractor margins lacking backward integration into raw milk supply. Asian infant formula manufacturers exhibit highest price sensitivity due to NMPA registration sunk costs, while Japanese hospital pharmacy committees demonstrate lowest sensitivity given clinical-nutrition protocol mandates.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes from Auckland and Rotterdam ports inflate inbound logistics costs for spot purchasers lacking long-term offtake agreements. Supply concentrates in New Zealand, the Netherlands, and Australia, with Canterbury and Friesland dairy cooperatives controlling fractionation capacity. Raw material dependencies center on bovine whey feedstock, cation-exchange resins, and pharmaceutical-grade solvents. Single-source vulnerability pervades the New Zealand-Australia corridor, where Fonterra and Synlait anchor export volume. Distribution runs through vertically integrated cooperative networks and specialized pharmaceutical ingredient distributors serving Asian infant formula clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation-derived lactoferrin alternatives threaten incumbent bovine-extraction economics as biotechnology startups achieve gram-scale production, forcing traditional processors to defend specification-grade positioning against novel manufacturing routes.
For Market Incumbents: Fortify NMPA registration portfolios through dedicated regulatory affairs infrastructure in Shanghai and Beijing, preempting eighteen-to-twenty-four-month approval bottlenecks that strand competitor inventory. Deepen captive fractionation capacity via continuous cation-exchange retrofit investments, insulating margin structures from whey protein concentrate spot-price volatility. Lock five-to-seven-year offtake agreements with Yangtze River Delta infant formula clusters before precision fermentation alternatives achieve cost parity. For New Entrants and Emerging Players: Differentiate on pharmaceutical-grade cGMP certification for Japanese and South Korean hospital pharmacy committees, where purity premiums exceed food-grade benchmarks by five-to-eight multiples. Target India's production-linked incentive scheme for nutritional ingredients, leveraging tariff and capital subsidies unavailable to established Oceanian suppliers. Pursue direct-to-consumer capsule formats through North American e-commerce channels, bypassing NMPA registration barriers that constrain import-dependent competitors. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because NMPA, FDA GRAS, and EU Novel Food approval timelines create durable barriers against commodity whey processors lacking certification infrastructure. Acquisition targets should concentrate on mid-scale fractionators with demonstrated multi-jurisdictional track records and continuous processing technology already deployed. Monitor precision fermentation scale-up announcements as the critical inflection signal for bovine-extraction valuation compression.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Processing Retrofit | Halves solvent consumption while enabling pharmaceutical-grade output from existing whey facilities. |
| NMPA Registration Acceleration | Eighteen-to-twenty-four-month timelines filter out undercapitalized competitors seeking Chinese infant formula access. |
| Long-term Offtake Agreements | Five-to-seven-year contracts displace spot-market vulnerability for Asian dairy processors. |
| Pharmaceutical-grade cGMP Certification | Unlocks Japanese hospital pharmacy committees commanding purity premiums above food-grade benchmarks. |
| Precision Fermentation R&D Partnership | Defensive positioning against biotechnology alternatives threatening bovine-extraction economics. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with dairy cooperative procurement directors, infant formula regulatory affairs managers, cation-exchange chromatography engineers, and hospital pharmacy committee members; alongside secondary validation through NMPA registration databases, FDA GRAS notification filings, EFSA Novel Food approval records, and Fonterra-Synlait-Glanbia SEC disclosures. Bottom-up volume triangulation across whey fractionation capacity and top-down value estimation via infant formula ingredient pricing reconciled within five-percent variance thresholds.
Across the analysis window, the forecasting framework modeled lactoferrin demand through product type segmentation (powder, capsule, liquid, tablet), application tier (infant formula, functional foods, dietary supplements, pharmaceutical products), and end-user procurement authority (healthcare providers, manufacturers, nutritionists, individual consumers). CAGRs derived from infant formula birth-rate projections, immune-positioning adoption curves, and pharmaceutical-grade specification penetration. Industry-specific inputs incorporated pediatric prescription patterns in Chinese maternity hospitals and EFSA health claim substantiation timelines.
Forecasts assume regulatory continuity in NMPA novel food registration, FDA GRAS notification, and EU Novel Food approval regimes; material policy shifts compressing approval timelines or elevating purity thresholds would require re-modeling. Recalibration cycles align with material shifts in precision fermentation scale-up milestones, whey protein concentrate auction volatility, and NMPA registration backlog clearance rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Omega-3 Fatty Acids Market
Nutritional Supplements
Microalgae DHA Market
Nutritional Supplements
Milk Powder for Pregnant Women Market
Nutritional Supplements
Asia-Pacific Nutraceutical Excipients Market
Nutritional Supplements
Cognition Supplements Market
Nutritional Supplements
North America Spirulina Extract Market
Nutritional Supplements
Feed Prebiotics Market
Nutritional Supplements
Global Adaptogens Market
Nutritional Supplements
Global Nutraceuticals Product Market
Nutritional Supplements
Global Corn Germs Supplements Market
Nutritional Supplements
Lactoferrin Market
Nutritional Supplements
Canada Protein Market
Nutritional Supplements
Micronutrient Powders (Mnps) Market
Nutritional Supplements
Smart Nutrition Scale Market
Nutritional Supplements
Algae Omega Market
Nutritional Supplements
Japan Dietary Supplements Market