
 Liquid Dietary Supplements Market | 2026-2036
Liquid Dietary Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Dietary Supplements Market Intelligence
The EU Green Deal is shifting liquid supplement procurement toward sustainably sourced botanical inputs. Abbott Laboratories leverages its clinical nutrition heritage to anchor hospital and home-care channels. Nestlé Health Science competes through science-backed functional positioning in metabolic health. Glanbia plc dominates sports nutrition liquids with deep dairy protein expertise and athlete-focused branding.
Liquid dietary supplements encompass concentrated nutrient formulations delivered in fluid or semi-fluid states, typically containing bioactive compounds suspended in aqueous, oil-based, or emulsion carriers with particle sizes below 500 nanometers for optimal absorption. These products serve industrial-scale wellness programs, clinical nutrition protocols, and direct-to-consumer preventive health regimens. Vitamins and minerals occupy mature, high-volume positions with thin margins, while herbal extracts command premium pricing due to traceability requirements and organic certification complexity. Protein shakes represent the fastest-expanding product type, driven by gym culture proliferation and meal-replacement convenience trends among time-constrained professionals.
The FDA enforces Current Good Manufacturing Practice regulations that mandate identity testing for every raw material lot, elevating compliance costs but filtering out informal competitors. EFSA novel food assessments and EMA borderline product rulings create divergent pathway costs between European member states, complicating pan-EU launch strategies. China's NMPA health food blue-hat registration system imposes multi-year clinical substantiation requirements that only well-capitalized multinationals can navigate. Stakeholders must monitor evolving probiotic and postbiotic classification debates across jurisdictions, as reclassification would force reformulation investments or channel restrictions.
Market Dynamics
The FDA's updated dietary supplement labeling requirements are compressing informal competitors while concentrating procurement among certified manufacturers capable of absorbing multi-million-dollar compliance investments.
Growth Catalysts
- CGMP identity testing mandates:The FDA's lot-level raw material verification protocols elevate barrier-to-entry costs, filtering out uncertified suppliers and consolidating volume with established pharmaceutical-grade manufacturers.
- Geriatric care infrastructure:Japan's super-aged demographic and Germany's expanding home-care nursing protocols are institutionalizing liquid supplement protocols within hospital discharge and long-term care reimbursement frameworks.
- Ready-to-drink protein convenience:Time-compressed professionals in the United States are substituting traditional meals with shelf-stable liquid nutrition, expanding addressable occasions beyond fitness into workplace consumption.
Market Restraints
- Organic botanical traceability costs:EU Green Deal sustainable sourcing requirements impose farm-to-bottle documentation burdens that inflate herbal extract input costs by 15-40% versus conventional supply chains.
- Cross-border regulatory fragmentation:EFSA novel food assessments and EMA borderline product rulings create divergent compliance costs between European member states, complicating unified launch strategies.
- Emulsion stability technical ceiling:Particle size distribution below 500 nanometers requires specialized high-pressure homogenization equipment that limits contract manufacturing options for mid-scale entrants.
Strategic Opportunities
- Postbiotic reclassification white space:Evolving probiotic and postbiotic classification debates across jurisdictions will force reformulation investments, creating first-mover advantage for substantiated live culture claims.
- China's blue-hat registration pathway:NMPA health food clinical substantiation requirements favor well-capitalized multinationals capable of multi-year registration timelines, locking out smaller competitors.
- Metabolic health functional positioning:Science-backed glycemic control and weight management claims represent underexploited positioning territory beyond saturated sports nutrition and basic vitamin categories.
Industry Challenges
- Pharmaceutical-grade emulsion formulation expertise:The talent pool for lipid-based delivery system design remains concentrated among former infant nutrition and parenteral specialists, creating recruitment bottlenecks for scaling brands.
- Dual validation for clinical and consumer channels:Manufacturers seeking hospital formulary placement alongside retail distribution must maintain parallel quality systems, doubling documentation overhead without guaranteed institutional volume.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Dietary Supplements Market |
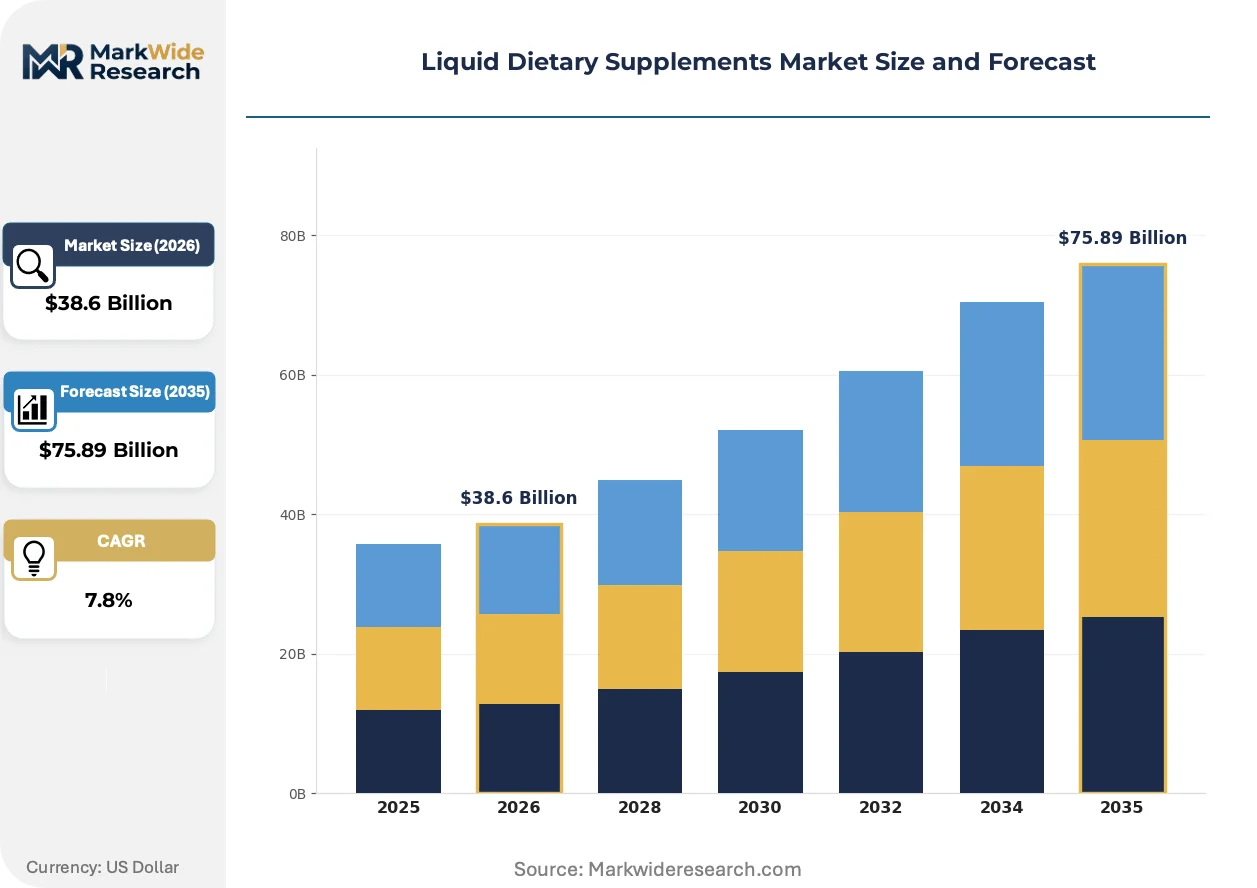
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $75.89 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Herbal Extracts, Protein Shakes Delivery Mode: Syrups, Liquid Capsules, Gummies, Shots End User: Healthcare Providers, Fitness Enthusiasts, General Consumers, Athletes Distribution Channel: Pharmacies, Supermarkets, Online Retail, Health Stores |
| Companies Covered | Abbott Laboratories, Nestlé Health Science, Herbalife Nutrition, Amway, Bayer AG, Unilever, DSM, Glanbia plc, Liquid Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Dietary Supplements Market Strategic Shifts & Innovations
Formulation science and regulatory science are converging to reshape competitive advantage, with absorption optimization and jurisdictional compliance emerging as distinct capability axes separating premium from commodity positioning.
Nano-emulsion delivery systems are decentralizing manufacturing advantage away from centralized pharmaceutical facilities toward specialized regional processors capable of toll-manufacturing liposomal and micellar formulations. Mid-scale wellness brands are adopting these technologies through contract partnerships rather than captive investment, compressing the traditional scale economies that protected large incumbents. The technology is decentralizing quality differentiation across the supplier base, enabling smaller entrants to match absorption claims previously reserved for clinical nutrition heritage brands.
EU Green Deal sustainable sourcing mandates are redirecting botanical procurement toward certified organic supply chains with full farm-to-bottle traceability. The regulation is forcing reformulation investments as conventional extract suppliers lose approved supplier status, particularly affecting herbal liquid supplement categories. German and French manufacturers are responding fastest, leveraging proximity to established organic agriculture cooperatives in Eastern Europe and Mediterranean growing regions.
Fitness enthusiasts are consolidating purchase decisions around subscription-based direct-to-consumer models that bypass traditional retail markup structures. Brick-and-mortar sports nutrition specialty stores are losing traffic to algorithm-curated replenishment programs with personalized flavor and macronutrient rotation. This channel migration is most pronounced in the United States, where gym culture penetration and digital payment infrastructure enable seamless auto-replenishment adoption.
Liquid Dietary Supplements Market Segmentation
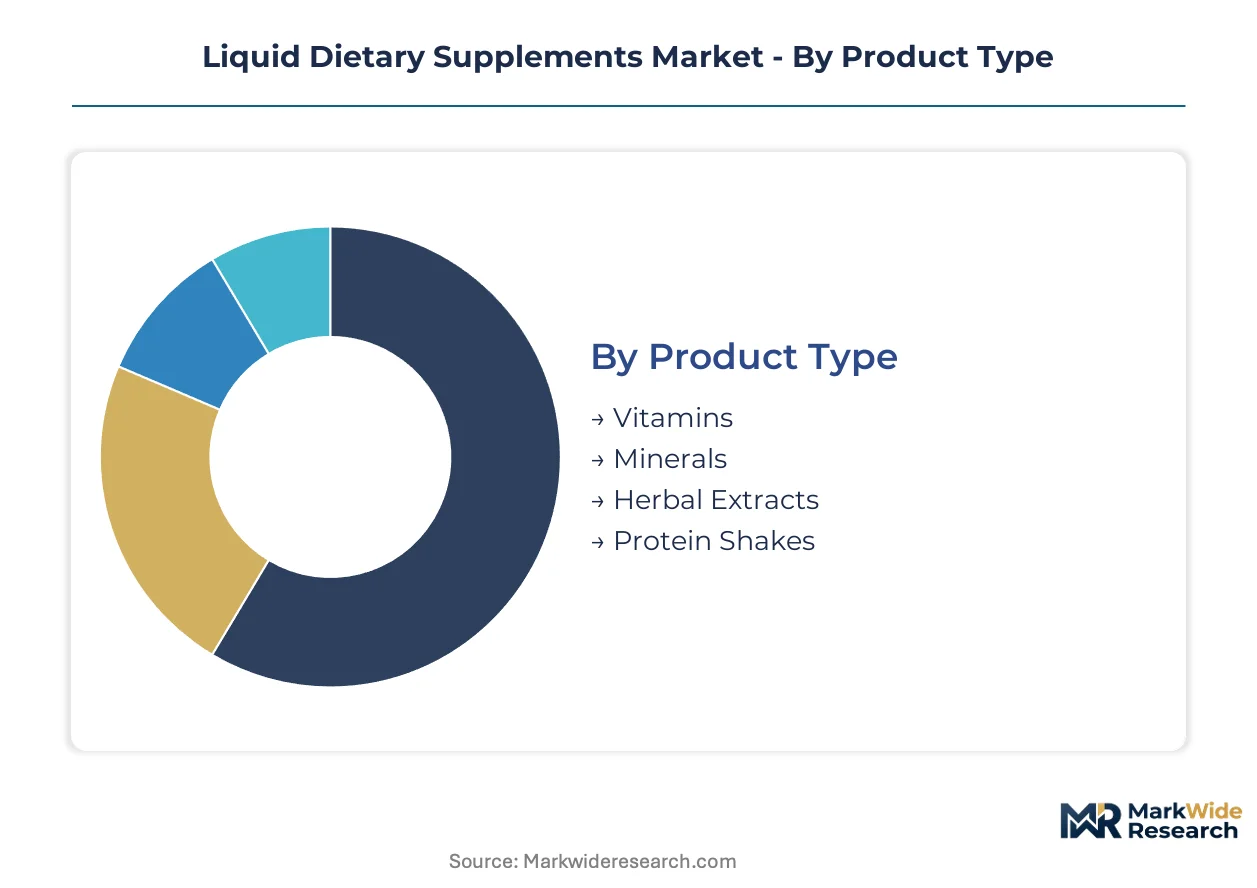
Liquid supplement manufacturers calibrate formulation architecture and channel strategy against distinct consumption occasions. Each segment boundary reflects divergent absorption requirements, purchasing triggers, and regulatory exposure that reshape margin profiles across the value chain.
Product Type:
Upgrade cycles accelerate where clinical substantiation unlocks reimbursement or premium positioning, compressing replacement timelines for basic commodity formulations.
- Vitamins:Aqueous suspensions of fat-soluble and water-soluble micronutrients in stabilized emulsion matrices. Volume concentrates in United States retail pharmacy chains serving preventive health regimens; thin margins force manufacturers toward multi-vitamin complexes with mineral co-formulation to defend shelf price points.
- Protein Shakes:Dairy and plant-derived protein isolates delivered in ready-to-drink formats with extended ambient stability. Demand clusters among United States fitness enthusiasts seeking post-workout recovery convenience; meal-replacement positioning among time-compressed professionals extends consumption occasions beyond gym environments.
- Minerals:Ionic or chelated mineral solutions targeting specific deficiency protocols. Hospital discharge and home-care channels in Japan absorb specialized formulations for geriatric populations.
- Herbal Extracts:Botanical bioactives suspended in ethanol or glycerin carriers with certified organic provenance. EU Green Deal traceability mandates inflate input costs and restrict supplier pools to certified organic cooperatives.
Volume placements concentrate in Vitamins; the faster expansion belongs to Protein Shakes.
Delivery Mode:
Cost tiers stratify sharply between commodity liquid formats and precision-delivery systems requiring specialized equipment investment.
- Syrups:Viscous aqueous solutions with high solids content and extended shelf stability through pH modulation and preservative systems. Pediatric and geriatric applications in Germany favor palatability-engineered formulations with masking agents for bitter botanical extracts.
- Shots:Concentrated single-serve formats delivering functional doses in minimal volume. United States convenience retail and gym channels absorb high-frequency impulse purchases; compact logistics reduce distribution cost per dose versus bulk liquid alternatives.
- Liquid Capsules:Soft-gel encapsulation of oil-based nutrients with tamper-evident sealing. Pharmaceutical-grade manufacturing requirements limit contract manufacturer availability.
- Gummies:Gelatin or pectin-based matrices with liquid nutrient infusion. Adult compliance positioning expands beyond traditional pediatric applications.
Manufacturing scale clusters around Syrups; steepest expansion trajectory characterizes Shots.
End User:
Application context dictates formulation specification, with clinical protocols demanding pharmaceutical-grade documentation absent from consumer wellness positioning.
- Healthcare Providers:Hospital, long-term care, and home-care institutions administering liquid supplements under clinical supervision. Japan's super-aged demographic and Germany's expanding nursing infrastructure institutionalize reimbursement-eligible protocols.
- Fitness Enthusiasts:Recreational exercisers seeking performance and recovery optimization through protein and amino acid supplementation. United States gym culture penetration drives subscription-based direct-to-consumer migration away from brick-and-mortar specialty retail.
- Athletes:Competitive and professional sports participants requiring batch-tested formulations with banned substance certification. Anti-doping compliance documentation elevates supplier qualification thresholds.
- General Consumers:Preventive health seekers purchasing without clinical indication or fitness-specific motivation. Mass retail and online channels absorb price-sensitive volume with basic vitamin and mineral formulations.
Procurement volume aggregates with Healthcare Providers; Fitness Enthusiasts are gaining share fastest.
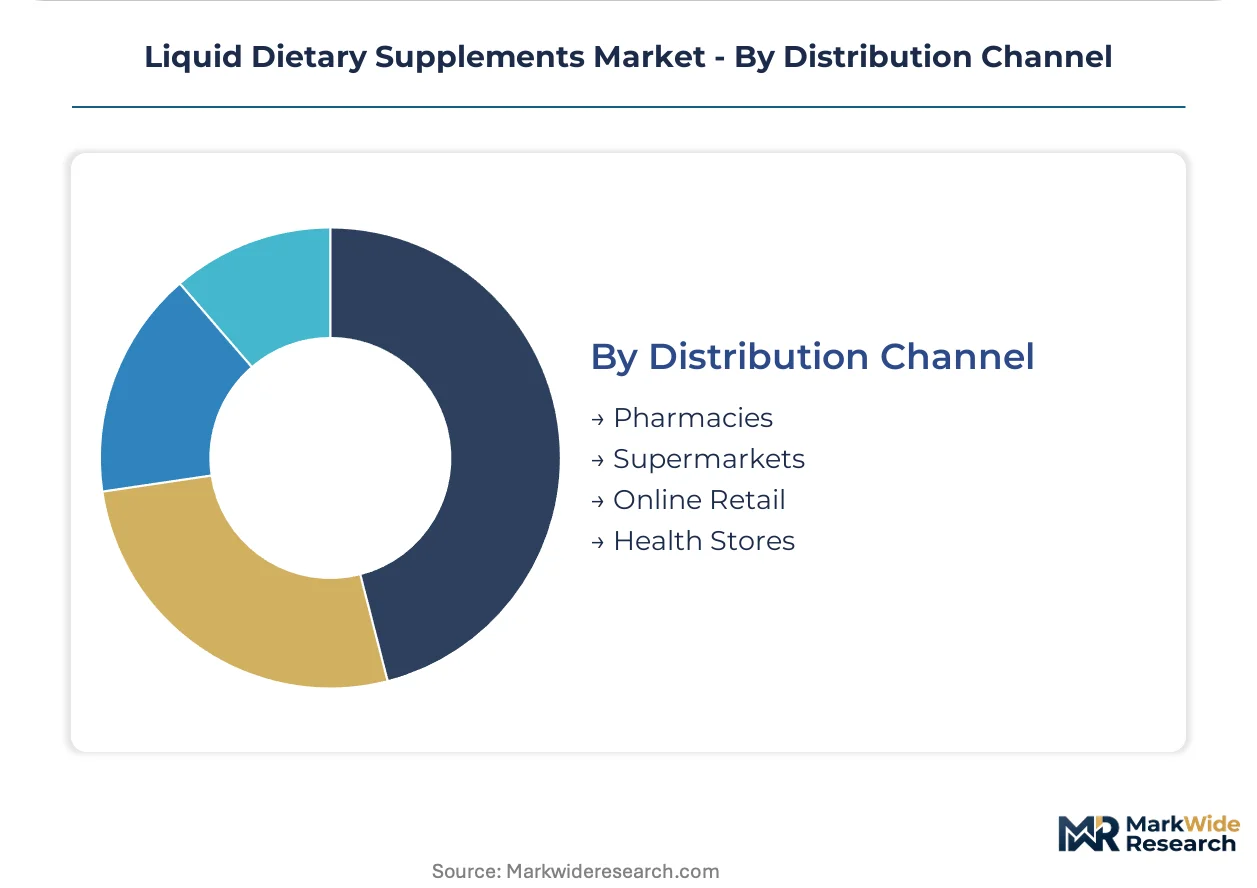
Distribution Channel:
Customer type fragmentation across clinical, fitness, and wellness occasions fragments channel strategy, with digital infrastructure enabling disintermediation where subscription economics prove superior.
- Online Retail:Direct-to-consumer platforms with algorithm-curated replenishment and personalized macronutrient rotation. United States digital payment infrastructure and gym culture penetration enable seamless auto-replenishment adoption.
- Pharmacies:Licensed dispensaries with pharmacist consultation and insurance reimbursement integration. Clinical nutrition formulations with hospital formulary heritage anchor shelf positioning.
- Health Stores:Specialty retailers with trained staff and premium private-label portfolios. Organic certification and sustainable sourcing credentials drive assortment decisions.
- Supermarkets:Mass-market retail with high-velocity basic vitamin and protein shake placement. Price competition compresses margins and favors multi-national scale manufacturers.
Transaction volume flows through Supermarkets; Online Retail climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's biotech corridor anchors North American liquid supplement innovation, hosting formulation labs that serve hospital discharge protocols and direct-to-consumer subscription channels.
United States
Fitness enthusiasts in California and Texas drive ready-to-drink protein demand through gym-based subscription models. FDA CGMP identity testing mandates filter out uncertified suppliers, concentrating volume with pharmaceutical-grade manufacturers. Chicago's contract manufacturing cluster specializes in high-pressure homogenization equipment for nano-emulsion stability.
Germany
Super-aged demographics and expanding home-care nursing protocols institutionalize liquid supplement reimbursement frameworks. EU Green Deal traceability requirements redirect botanical procurement toward certified organic cooperatives in Eastern Europe. Bavaria's food technology institutes pioneer palatability-engineered formulations for geriatric compliance.
Japan
Hospital discharge and long-term care reimbursement frameworks absorb specialized mineral formulations for aging populations. METI standards harmonize with international pharmaceutical-grade documentation requirements. Osaka-Kobe manufacturing corridor concentrates emulsion stability expertise derived from infant nutrition heritage.
China
NMPA health food blue-hat registration imposes multi-year clinical substantiation timelines that favor well-capitalized multinationals. Shanghai's free-trade zones host toll-manufacturing partnerships for liposomal delivery systems. Yangtze River Delta logistics hubs enable cold-chain distribution for live culture postbiotic formulations.
Brazil
ANVISA's evolving borderline product classifications create compliance uncertainty for herbal extract positioning. São Paulo's pharmaceutical manufacturing base adapts European formulation standards for Latin American taste preferences. Southeast industrial corridors develop local organic botanical supply chains to reduce import dependency.
Liquid Dietary Supplements Market Key Industry Players
The competitive structure tilts toward heritage pharmaceutical and nutrition conglomerates with clinical channel access. Established players leverage hospital formulary relationships and multi-million-dollar compliance infrastructure to filter out mid-scale entrants. Three archetypes dominate: clinical nutrition heritage brands, sports nutrition specialists with dairy protein expertise, and direct-to-consumer wellness platforms with algorithmic personalization. Consolidation pressure intensifies through M&A targeting contract manufacturing capacity and strategic partnerships for nano-emulsion technology licensing.
Within the clinical nutrition tier, Abbott Laboratories and Nestlé Health Science exemplify hospital and home-care channel anchoring through reimbursement-eligible protocols. Glanbia plc occupies a position among sports nutrition specialists, leveraging dairy protein heritage for athlete-focused branding and anti-doping certification infrastructure. These three entities represent distinct capability axes—clinical heritage, sports specialization, and metabolic health science—that separate premium positioning from commodity liquid supplement manufacturing.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Nestlé Health Science |
| Herbalife Nutrition |
| Amway |
| Bayer AG |
| Unilever |
| DSM |
| Glanbia plc |
| Liquid Health |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between pharmaceutical-grade manufacturers and commodity liquid supplement producers manifests in both pricing power and supply chain configurations. FDA CGMP compliance costs filter procurement toward certified suppliers capable of absorbing multi-million-dollar identity testing infrastructure, while uncertified competitors face margin compression from exclusion.
Pricing Analysis
Value-based pricing anchored to clinical substantiation and reimbursement eligibility separates premium positioning from commodity tiers. Pharmaceutical-grade emulsion formulations command substantial premiums over basic aqueous suspensions due to hospital formulary access and home-care reimbursement frameworks. Price differentiation stems from certification grade and volume scale, with institutional buyers negotiating contract-based long-term offtake while direct-to-consumer channels absorb subscription-tiered premiums. Pricing pressure intensifies in mass-market protein shakes as fitness enthusiasts migrate toward algorithm-curated replenishment models that compress traditional retail markups. General consumers through supermarket channels exhibit highest price sensitivity, whereas healthcare providers demonstrate lowest sensitivity due to reimbursement insulation.
Supply Chain Analysis
EU Green Deal domestic-content mandates for organic botanical traceability are redirecting procurement toward certified cooperatives in Germany, France, and Eastern European growing regions. Raw material dependencies center on dairy protein isolates from Ireland and New Zealand, high-pressure homogenization equipment from Germany and Japan, and certified organic herbal extracts from Mediterranean and Eastern European suppliers. Supply chain risk concentrates in single-source vulnerability for nano-emulsion manufacturing equipment capable of achieving sub-500 nanometer particle stability. Distribution runs through hospital procurement systems and direct-to-consumer subscription platforms, with traditional retail pharmacy and health store channels losing share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race as players pursue backward control over organic botanical supply chains to defend margin positions against EU Green Deal traceability mandates.
For Market Incumbents: Cement hospital formulary relationships through reimbursement-eligible clinical nutrition protocols before mid-scale entrants achieve pharmaceutical-grade emulsion expertise. Expand captive manufacturing capacity in Germany and Japan to exploit proximity to super-aged care infrastructure. Counter the threat from algorithm-curated direct-to-consumer subscription models by acquiring specialized contract manufacturers with nano-emulsion toll capabilities. For New Entrants and Emerging Players: Begin with metabolic health functional positioning in glycemic control and weight management, the most penetrable white space beyond saturated sports nutrition categories. Target United States fitness enthusiasts through direct-to-consumer subscription channels where digital payment infrastructure enables seamless auto-replenishment adoption. Pursue science-backed claims substantiation as the primary go-to-market angle to differentiate from commodity vitamin and mineral formulations. For Investors and Strategic Acquirers: Re-rating potential sits with specialized contract manufacturers possessing high-pressure homogenization equipment and pharmaceutical-grade documentation capabilities given the talent scarcity for lipid-based delivery system design. Long-term viability across the analysis window favors entities with dual validation for clinical and consumer channels. Watch NMPA health food blue-hat registration timelines in China as the inflection indicator for multinational market access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Botanical Supply | EU Green Deal traceability mandates force farm-to-bottle documentation investments that lock out informal competitors. |
| Nano-Emulsion Technology Licensing | Specialized high-pressure homogenization partnerships enable mid-scale brands to match absorption claims of clinical heritage players. |
| Direct-to-Consumer Subscription Launch | Algorithm-curated replenishment models bypass retail markup compression and capture United States gym culture penetration. |
| Hospital Formulary Partnership | Reimbursement-eligible protocols in Japan and Germany institutionalize volume through discharge and long-term care frameworks. |
| Postbiotic Classification Compliance Investment | First-mover substantiation of live culture claims creates advantage as probiotic reclassification debates resolve across jurisdictions. |
Research Approach
Multi-period observation of FDA enforcement actions, NMPA registration timelines, and EU Green Deal implementation progress anchored the trend analysis, supplemented by interviews with formulation scientists at contract manufacturing organizations, procurement managers at hospital systems, regulatory affairs leads at multinational nutrition conglomerates, and category buyers at United States pharmacy chains. Secondary validation drew from FDA warning letter databases, EFSA novel food assessment registers, NMPA health food approval disclosures, and customs trade data for organic botanical inputs. Bottom-up demand modeling across end-user segments triangulated against top-down market sizing from pharmaceutical-grade manufacturing capacity assessments.
Input-output matrices structured the analytical framework, linking raw material cost trajectories for dairy proteins and organic extracts to finished product pricing across the projection horizon. Segmentation dimensions modeled included product type, delivery mode, end-user application context, and distribution channel format, with regional regulatory cluster as the industry-specific overlay. CAGRs were derived from trend extrapolation of historical volume flows adjusted for compliance cost absorption rates and channel migration patterns. Forecast inputs incorporated hospital discharge protocol adoption curves and fitness subscription penetration rates.
Underlying measurement precision varies by segment; pharmaceutical-grade clinical nutrition formulations carry tighter precision than commodity protein shakes due to reimbursement documentation requirements. Forecasts reflect assumptions regarding regulatory timeline stability and organic certification supply expansion that could revise materially if NMPA accelerates blue-hat review processes or EU Green Deal traceability mandates tighten unexpectedly. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Nutraceutical Oral Thin Films Market
Nutritional Supplements
Sea Moss Supplements Market
Nutritional Supplements
Medium Chain Triglyceride (MCT) Food Market
Nutritional Supplements
Tea Tree Oil Market
Nutritional Supplements
Cod Liver Oil Market
Nutritional Supplements
Collagen Supplements Market
Nutritional Supplements
Europe Botanical Supplements Market
Nutritional Supplements
Nutritional Supplements Market
Nutritional Supplements
Heart Health Supplement Market
Nutritional Supplements
Functional Carbohydrates Market
Nutritional Supplements
Australia Collagen Peptides Market
Nutritional Supplements
Global Proanthocyanidins Market
Nutritional Supplements
Middle East Protein Market
Nutritional Supplements
Asia Pacific Nutritional Supplements Market
Nutritional Supplements
Microencapsulated Fish Oil Market
Nutritional Supplements
South Africa Collagen Peptides Market